
 Copper Wire Market | 2026-2036
Copper Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Wire Market Analysis
Multi-source procurement among tier-one cable assemblers is consolidating around fewer qualified copper wire suppliers with integrated smelting-to-drawing capabilities. Prysmian Group leverages backward integration into copper rod production to secure feedstock consistency across European and Latin American plants. Nexans anchors its competitiveness through deep specialization in fire-resistant and low-smoke halogen-free compounds for building infrastructure. Southwire Company sustains manufacturing scale advantages across its southeastern US wire-drawing complexes, competing on delivery velocity to electrical utility contractors.
Copper wire consists of a single or grouped metallic conductor, typically exceeding 99.9% pure copper, formed through continuous casting and sequential wire drawing with intermediate annealing to achieve target conductivity and ductility specifications; its primary purpose is efficient transmission of electrical current across power, signal, and electromagnetic applications. Enamelled wire commands premium positioning in motor and transformer windings where insulation thermal class determines equipment lifespan and energy efficiency ratings. Stranded wire dominates overhead and underground power distribution due to mechanical flexibility requirements, while bare wire maintains cost leadership in grounding and busbar applications where environmental protection is handled externally.
The US EPA regulates copper smelter emissions under National Ambient Air Quality Standards, while the EU REACH framework restricts hazardous substance content in wire insulation and coating chemistries. China's GB standards and MEE enforcement protocols shape export eligibility for copper wire products entering Asian supply chains. Stakeholders must monitor evolving conductor efficiency mandates and traceability requirements as regulators link material sourcing disclosure to public procurement access.
Market Dynamics
Integrated smelting-to-drawing operations are consolidating procurement power among tier-one cable assemblers, squeezing mid-scale wire producers dependent on external copper rod supply. This structural concentration is accelerating qualification barriers and reshaping competitive access to automotive and utility contracts.
Growth Catalysts
- Ecodesign for Sustainable Products Regulation:The EU framework tightens material efficiency mandates for electrical components, compelling OEMs to source higher-grade conductor materials with verified lifecycle data.
- Traction motor winding demand:Electric vehicle manufacturers are expanding procurement of high-conductivity copper winding wire as motor power density requirements intensify.
- Eastern China manufacturing corridor:Cable and magnet wire production clusters near downstream appliance and automotive plants concentrate demand visibility and shorten logistics loops for just-in-time delivery.
Market Restraints
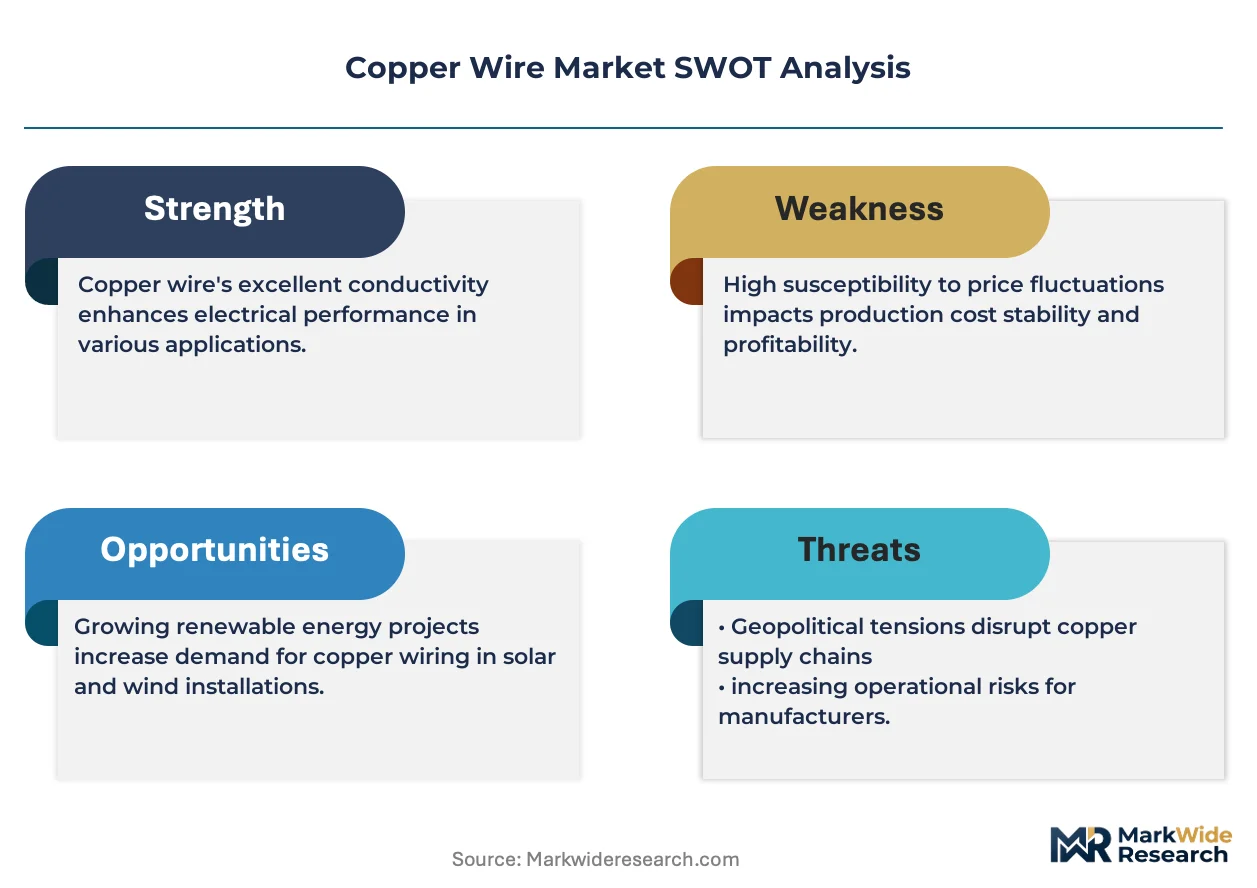
- Copper concentrate supply volatility:Smelter feedstock costs fluctuate with Chilean and Peruvian mine output disruptions, compressing rod-to-wire margin stability for non-integrated producers.
- REACH compliance friction:The EU framework restricts hazardous substance content in wire insulation chemistries, forcing reformulation investments that disadvantage smaller coating compound suppliers.
- Aluminum substitution in overhead lines:Utility distributors in cost-sensitive markets are specifying aluminum conductor steel-reinforced cable for new transmission builds where conductivity-to-weight ratios permit.
Strategic Opportunities
- Fire-resistant compound specialization:Building infrastructure codes across Germany, France, and Italy are mandating low-smoke halogen-free cable specifications, opening premium positioning for compound-integrated wire producers.
- Direct e-commerce channels:Electrical contractors and maintenance shops are migrating procurement to specialized industrial platforms, disintermediating traditional distributor markups for standard wire gauges.
- Dual carbon alignment:China's MEE enforcement protocols and carbon intensity disclosure requirements are creating first-mover advantage for smelters with verified renewable energy inputs.
Industry Challenges
- Conductor drawing technician shortage:Precision wire-drawing operations require skilled operators capable of calibrating multi-die sequences for enamelled wire gauge consistency, yet vocational pipeline output lags replacement demand.
- Traceability system integration:EU and North American procurement mandates for conflict mineral and carbon footprint disclosure are forcing legacy ERP upgrades that strain mid-tier producer IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Wire Market |
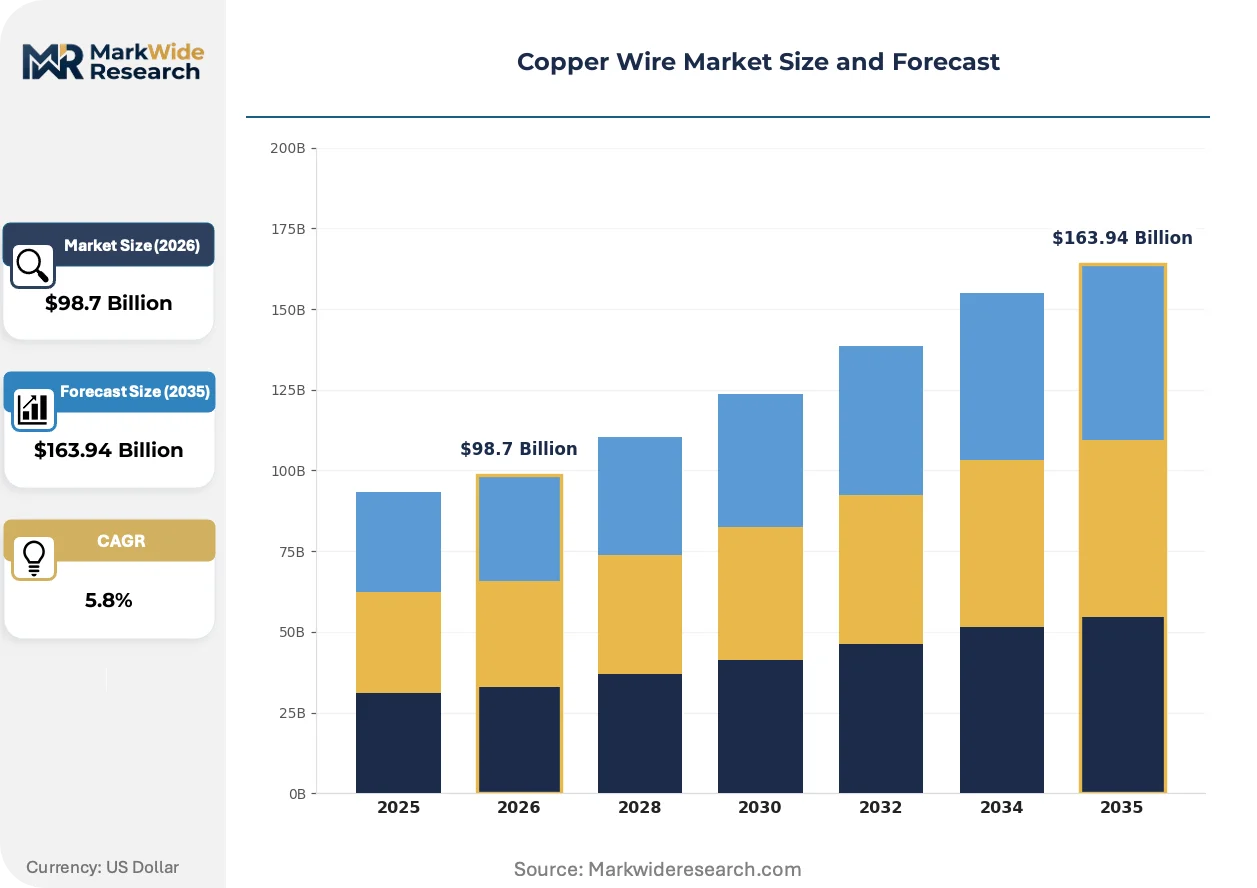
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enamelled Wire, Bare Wire, Stranded Wire, Composite Wire Application: Electrical Wiring, Electronics, Power Distribution, Communication Systems End User: Electrical Utilities, Automotive, Aerospace, Construction Manufacturing Stage: Raw Material Processing, Wire Drawing, Annealing, Coating |
| Companies Covered | Prysmian Group, Nexans, Southwire Company, Sumitomo Electric Industries Ltd, KEI Industries, Furukawa Electric Co., Ltd., Belden Inc, LS Cable & System, Alan Wire Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Wire Market Emerging Trajectories
Active material science advances and procurement digitization are compressing product development cycles while fragmenting traditional supply relationships. Wire producers must now coordinate compound innovation with real-time demand signaling.
Continuous annealing inline with wire drawing is decentralizing thermal processing from centralized batch furnaces to production-line integration. Motor and transformer manufacturers in Japan and South Korea are specifying enamelled wire with in-process annealed grain structures for improved fatigue resistance. This distributed thermal control is compressing capital requirements for new market entrants while raising quality consistency thresholds.
REACH Annex XVII restrictions on persistent organic pollutants in insulation coatings are compelling reformulation toward bio-based polyesterimide chemistries. Wire producers serving European appliance OEMs must now validate thermal class ratings through accelerated aging protocols that add six to nine months to qualification timelines. Building cable assemblers are responding by consolidating supplier panels to those with in-house compound development capabilities.
Electrical utility contractors are unbundling after-sales technical support from wire procurement, purchasing commodity conductors through digital marketplaces while sourcing engineering consultation separately. This service decoupling is most visible across southeastern US infrastructure projects, where project managers prioritize delivery velocity over bundled distributor relationships. Traditional full-service wire distributors are responding with tiered pricing that separates logistics from specification consulting.
Copper Wire Market Segmentation
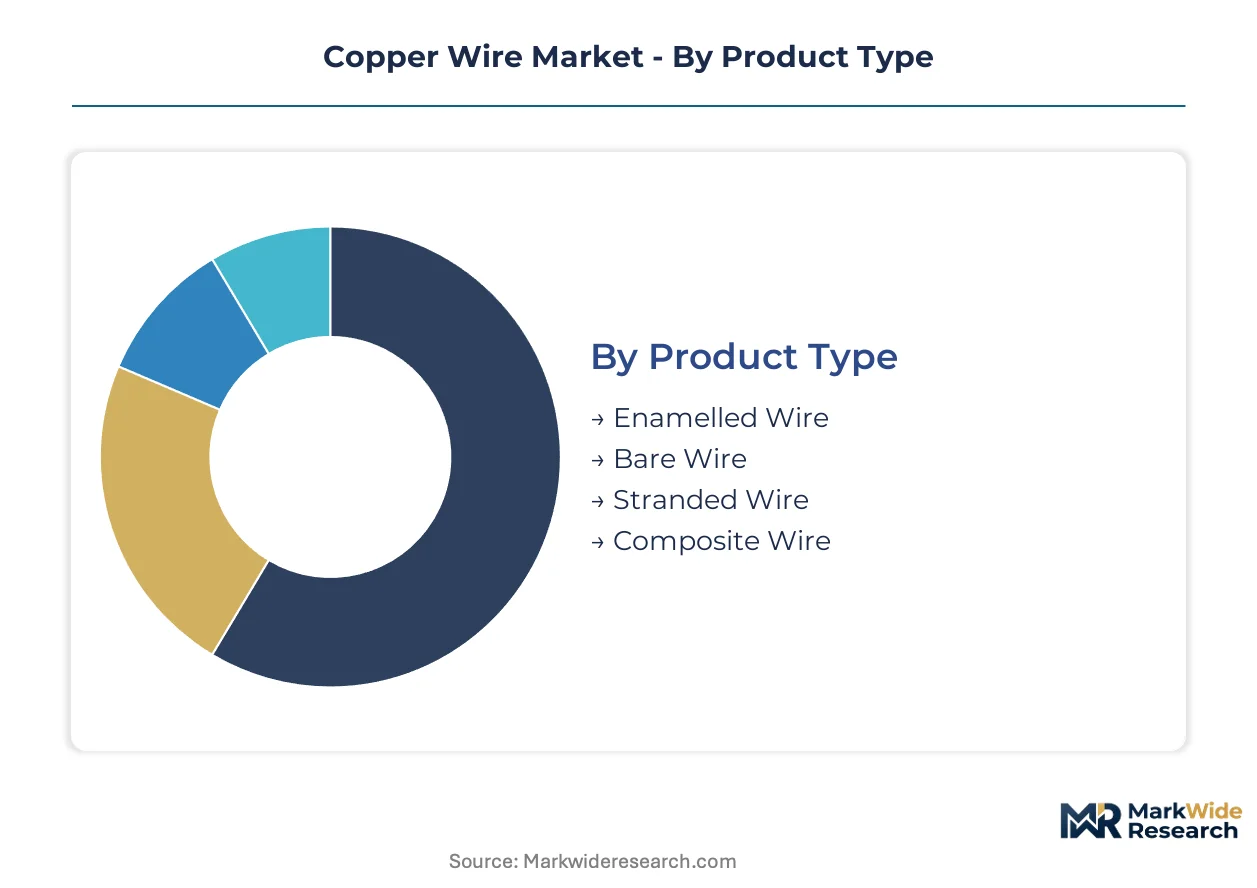
Copper wire segmentation reflects divergent technical requirements across electrical transmission, electromagnetic conversion, and structural applications. Each category maps distinct value chain positions from smelter feedstock through precision coating operations.
Product Type:
Customization intensity varies from specification-critical enamel formulations to commodity bare conductors, creating tiered margin structures across the fabrication spectrum.
- Enamelled Wire:Thin copper conductors coated with synthetic resin insulation, typically polyesterimide or polyamide-imide, achieving thermal classes from 155°C to 220°C. Demand concentrates in Japanese and South Korean motor manufacturing clusters where traction motor power density requirements are tightening insulation performance specifications.
- Stranded Wire:Multiple copper strands twisted into flexible conductors, balancing conductivity with mechanical fatigue resistance for dynamic installations. European building infrastructure codes in Germany, France, and Italy are mandating low-smoke halogen-free specifications for fire-resistant stranded constructions in commercial developments.
- Bare Wire:Uninsulated solid or stranded conductors used where external environmental protection is provided by installation method. Grounding grids and electrical busbars in Chinese eastern manufacturing corridor facilities absorb volume shipments for appliance and automotive plant infrastructure.
- Composite Wire:Hybrid constructions combining copper with aluminum or specialized alloys for weight-optimized applications. Aerospace wiring harnesses specify composite configurations where conductivity-to-mass ratios determine fuel efficiency calculations.
Most installed capacity flows through Stranded Wire. Expansion is steepest in Enamelled Wire.
Application:
End-use concentration shapes procurement scale, with utility-scale transmission demanding kilometer-length consistency while electronics tolerates batch flexibility.
- Electrical Wiring:Building and equipment internal conductors for power and lighting circuits, spanning residential through industrial installations. Chinese construction activity in eastern coastal provinces drives bulk procurement for mixed-use developments and manufacturing facilities.
- Power Distribution:High-voltage transmission and distribution conductors for grid infrastructure, including overhead lines and underground cable systems. US southeastern utility contractors prioritize delivery velocity for grid modernization projects, consolidating procurement around regional wire-drawing complexes.
- Electronics:Miniature conductors for printed circuit boards, connectors, and consumer device internal wiring. REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation investments among European appliance OEM supply chains.
- Communication Systems:Signal transmission conductors for telecommunications and data infrastructure, including twisted pair and coaxial constructions. Data center construction in Singapore and Frankfurt is pulling specialized high-frequency copper cabling.
Power Distribution commands the largest installed base. Electronics demonstrates the steepest expansion trajectory.
End User:
Customer scale determines contract structure, with utilities negotiating multi-year framework agreements while aerospace procurement emphasizes qualification longevity.
- Electrical Utilities:Grid operators and distribution companies procuring conductors for transmission, substation, and last-mile infrastructure. Aluminum conductor steel-reinforced cable substitution is pressuring copper share in cost-sensitive emerging market transmission builds.
- Automotive:OEMs and tier suppliers sourcing winding wire for traction motors, alternators, and onboard electrical systems. Electric vehicle manufacturers are expanding high-conductivity copper winding wire procurement as motor power density requirements intensify.
- Construction:Building contractors and electrical installers purchasing wire for commercial, residential, and industrial developments. German, French, and Italian building codes mandating low-smoke halogen-free specifications are opening premium positioning for compound-integrated producers.
- Aerospace:Aircraft manufacturers and maintenance providers specifying lightweight, fire-resistant conductors for airframe and avionics systems. Composite wire configurations dominate where mass reduction translates directly to fuel efficiency.
Electrical Utilities anchor installed consumption. Automotive is climbing the fastest.
Manufacturing Stage:
Process depth determines capital intensity and margin capture, with integrated operations controlling feedstock cost volatility.
- Raw Material Processing:Copper concentrate smelting and fire refining to produce cathode and rod feedstock. Chilean and Peruvian mine output disruptions are compressing rod-to-wire margin stability for non-integrated producers dependent on external supply.
- Wire Drawing:Sequential mechanical reduction of rod diameter through multi-die systems to achieve target gauge. Precision wire-drawing operations require skilled technicians capable of calibrating multi-die sequences for enamelled wire consistency, yet vocational pipeline output lags replacement demand.
- Annealing:Thermal treatment to restore ductility and conductivity after work-hardening from drawing. Continuous annealing inline with drawing is decentralizing thermal processing from centralized batch furnaces to production-line integration in Japanese and South Korean motor supply chains.
- Coating:Application of insulation, shielding, or protective layers through extrusion, enameling, or taping. REACH compliance friction is forcing reformulation investments that disadvantage smaller coating compound suppliers serving European markets.
Wire Drawing represents the largest processing capacity base. Coating is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor concentrates the densest clustering of cable and magnet wire production capacity, with downstream appliance and automotive plants driving procurement visibility across Asia-Pacific supply chains.
China
Electric vehicle traction motor manufacturers in Jiangsu and Zhejiang provinces are expanding high-conductivity winding wire procurement as domestic OEMs scale production targets. The Ministry of Ecology and Environment enforces dual carbon alignment protocols that favor smelters with verified renewable energy inputs. Shanghai and Suzhou host integrated drawing-coating complexes serving just-in-time delivery requirements for appliance exporters.
United States
Southeastern utility contractors prioritize delivery velocity for grid modernization projects, consolidating procurement around regional wire-drawing complexes in Georgia and the Carolinas. The EPA regulates copper smelter emissions under National Ambient Air Quality Standards, shaping feedstock sourcing decisions. Electrical contractors across Texas and Florida are migrating procurement to specialized industrial platforms, disintermediating traditional distributor markups for standard wire gauges.
Germany
Building infrastructure codes mandate low-smoke halogen-free cable specifications for commercial developments, opening premium positioning for compound-integrated wire producers serving construction markets. ECHA administers REACH Annex XVII restrictions on persistent organic pollutants in insulation coatings, forcing reformulation investments among coating compound suppliers. The Ruhr industrial region maintains specialized enamel wire production for European motor and transformer manufacturers.
Japan
Motor and transformer manufacturers specify enamelled wire with in-process annealed grain structures for improved fatigue resistance in high-performance applications. METI coordinates industrial standards that influence thermal class rating protocols across Asian supply chains. Nagoya and Osaka manufacturing clusters concentrate precision wire-drawing operations requiring skilled technicians capable of calibrating multi-die sequences.
Italy
Fire-resistant compound specialization creates differentiation opportunities as German, French, and Italian building codes tighten safety specifications for commercial cable installations. CE marking requirements enforce conductor efficiency mandates that link material sourcing disclosure to public procurement access. Northern industrial zones around Milan maintain legacy enamel wire production serving European appliance OEM supply chains.
Copper Wire Market Vendor Landscape
Global majors compete with regional champions across integrated smelting-to-drawing capabilities, with tier-one cable assemblers consolidating procurement around fewer qualified suppliers. The vendor base stratifies into three archetypes: integrated conglomerates controlling captive copper rod supply, specialized compound developers with in-house coating expertise, and scale-driven regional fabricators competing on logistics velocity. Dominant competitive moves include backward integration into copper rod production and qualification-driven supplier panel consolidation for automotive and utility contracts.
Among European-integrated conglomerates, Prysmian Group and Nexans exemplify divergent strategic positioning—Prysmian anchors competitiveness through upstream control over feedstock consistency across European and Latin American plants, while Nexans occupies a position within the specialized compound tier through fire-resistant and low-smoke halogen-free expertise for building infrastructure. Southwire Company represents the scale-driven regional archetype, sustaining manufacturing advantages across southeastern US wire-drawing complexes.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Southwire Company |
| Sumitomo Electric Industries Ltd |
| KEI Industries |
| Furukawa Electric Co., Ltd. |
| Belden Inc |
| LS Cable & System |
| Alan Wire Company |
| Others |
Supply Flow & Price Mechanics
Precision wire-drawing technicians in Japan's Nagoya-Osaka corridor command wage premiums that widen spreads between thermal-class-rated enamelled wire and commodity bare conductors. Labor-cost differentials between these skilled-operator-dependent tiers and automated stranded-wire production in China's eastern corridor stratify pricing across certification grades.
Pricing Analysis
Input-cost pass-through from Chilean and Peruvian copper concentrate volatility anchors spot pricing for non-integrated rod buyers, while backward-integrated producers buffer through captive smelter supply. Three-tier pricing structure across premium, standard, and economy levels separates IEC 60317-thermal-class-certified enamelled wire from building-code-compliant stranded constructions and uninsulated bare grounding conductors. Cost compression in standard-grade stranded wire intensifies because aluminum conductor steel-reinforced substitution in utility tenders squeezes copper share. Electrical utilities exhibit highest price sensitivity through competitive bidding frameworks, while aerospace harness specifications tolerate premium positioning for mass-optimized composite configurations.
Supply Chain Analysis
Certification gating through REACH Annex XVII compliance and GB standards enforcement restricts qualified supplier pools for European and Chinese appliance OEMs. Geographic supply concentration centers on China for cathode and rod feedstock, Japan and South Korea for precision enamelled wire, and Germany and Italy for fire-resistant compound-integrated cable. Raw material dependencies draw from Chilean mine concentrate, Chinese smelter output, and specialized polyesterimide resin chemistries. Single-source vulnerability in high-purity copper cathode supply amplifies disruption risk from Andean labor actions or export licensing shifts. Distribution runs through tier-one cable assemblers consolidating procurement panels, with direct e-commerce channels fragmenting standard-gauge flows to electrical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: electric vehicle traction motor specifications are tightening insulation thermal-class requirements, displacing commodity-grade suppliers unable to validate accelerated aging protocols.
For Market Incumbents: Deepen backward integration into copper rod production to secure feedstock consistency against Chilean concentrate volatility, and consolidate fire-resistant compound development capabilities ahead of German, French, and Italian building-code mandates. Aluminum substitution in utility transmission tenders threatens volume-based producers lacking premium-mix diversification. For New Entrants and Emerging Players: Specialized industrial maintenance shops migrating procurement to digital marketplaces represent an underserved buyer archetype disintermediating traditional distributor markups. White-space targets include direct e-commerce channels for standard-gauge inventory and continuous annealing inline technology licensing to Japanese motor manufacturers seeking fatigue-resistant grain structures. A technical-service-unbundled go-to-market angle separates logistics velocity from specification consulting. For Investors and Strategic Acquirers: Tier-one automotive cable assemblers are the most active acquirer in this space, pursuing qualified winding-wire suppliers with validated thermal-class ratings and traceability systems. Long-term viability hinges on compound-integrated positioning within EU Ecodesign compliance frameworks. Watch for MEE enforcement protocol tightening on carbon intensity disclosure as the inflection indicator for smelter asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Production | Prysmian Group secures feedstock consistency across European and Latin American plants against concentrate volatility. |
| Fire-Resistant Compound Specialization | Nexans captures premium positioning in German, French, and Italian commercial building infrastructure codes. |
| Continuous Annealing Inline Deployment | Japanese motor manufacturers specify in-process annealed grain structures for improved fatigue resistance. |
| Direct E-Commerce Channel Development | Electrical contractors in Texas and Florida disintermediate distributor markups through specialized industrial platforms. |
| Dual Carbon Alignment Certification | China's MEE enforcement protocols favor smelters with verified renewable energy inputs for export eligibility. |
Methodological Framework
Multiple input streams — primary interviews with wire-drawing plant managers, cable assembler procurement leads, and appliance OEM technical directors; secondary validation through customs trade data, SEC 10-K filings, and ECHA REACH registration databases; and technical literature from IEC and JIS standards committees — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across supply-side capacity assessments and demand-side procurement pattern analysis shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application, end user, and manufacturing stage depth. CAGRs were derived from reconciling historical shipment volumes with forward-looking OEM capacity announcements and regulatory compliance timelines. Forecast inputs incorporated electric vehicle production targets and building-code amendment schedules.
Underlying measurement precision varies by segment; enamelled wire with thermal-class certification carries tighter precision than commodity bare conductor estimates. Forecasts reflect assumptions around Chilean mine output stability and REACH reformulation adoption curves. A model refresh is warranted upon material change in EU Ecodesign material efficiency mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Rubidium Market
Metals
Clutch Spring Wires Market
Metals
Metal Finishing Market
Metals
Aluminum Flat Products Market
Metals
High Carbon Bearing Steel Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Bismuth Oxide Market
Metals
316 Stainless Steel Container Market
Metals
Europe Aluminium Cans Market
Metals
Zinc Plating Market
Metals
Carbotanium Market
Metals
US and Mexico Stainless Steel Market
Metals
Copper Clad Aluminum Wire Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Japan Aluminium Powder Market
Metals
Copper and Copper Alloy Foil Market