
 Part Feeder Market | 2026-2036
Part Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Part Feeder Market Analytics
Polymer composite housings is hardening as the preferred material over cast aluminum in bowl feeder fabrication, cutting unit weight and damping acoustic resonance during high-frequency operation. Rhein-Nadel Automation leverages captive tooling capabilities to control bowl surface finishing tolerances within 0.05 mm. Afag Automation sustains a Swiss-German manufacturing footprint that anchors premium positioning in medical and watchmaking feeder segments. Weber Schraubautomaten GmbH dominates screwdriving-integrated feeder systems through backward integration into drive technology.
A part feeder is an automated material-handling device that orients and delivers discrete components to downstream assembly, inspection, or packaging stations using controlled vibration, belt conveyance, or robotic pick interfaces; operating frequencies typically range from 15 Hz to 120 Hz with feed rates adjustable between 10 and 1,000 parts per minute depending on component geometry and surface finish requirements. Vibratory technology occupies the largest installed base due to proven reliability in high-volume automotive fastener delivery, though linear feeder configurations are gaining specification share in electronics cleanroom environments where particle generation must stay below ISO Class 7 thresholds. Belt technology leads margin pools in food and pharmaceutical packaging lines where stainless steel construction and quick-changeover tooling command price premiums over standard industrial grades.
The EU Machinery Directive and ISO 10218 collaborative robot safety standards shape feeder design by mandating force-limiting interfaces and emergency-stop integration for human-robot workcell configurations. OSHA lockout-tagout regulations in the United States and Japan's METI industrial robot certification framework further fragment compliance requirements across export markets. Stakeholders must monitor how IEC 62061 functional safety ratings become a de facto gate for automotive OEM feeder procurement specifications before committing capital to platform redesigns.
Market Dynamics
Automotive assembly plants are expanding their use of automated feeding systems to handle lightweight composite components, tightening integration requirements across feeder OEM supply chains.
Growth Catalysts
- EU Machinery Directive compliance mandates:Force-limiting interfaces and emergency-stop integration requirements are pulling investment into human-robot workcell configurations across German precision engineering clusters.
- Electronics cleanroom expansion:Linear feeder configurations are gaining specification share where particle generation must stay below ISO Class 7 thresholds in semiconductor packaging facilities.
- Stuttgart-Munich engineering corridor:Specification intensity for high-speed linear and bowl feeder configurations is concentrating demand among automotive tier-one suppliers.
Market Restraints
- Polymer composite tooling costs:Captive tooling capabilities required to control bowl surface finishing tolerances within 0.05 mm are raising capital barriers for mid-tier fabricators.
- Regulatory fragmentation:OSHA lockout-tagout regulations in the United States and Japan's METI industrial robot certification framework create divergent compliance costs for export-oriented suppliers.
- ISO 10218 safety standard complexity:Collaborative robot integration timelines are extending by six to twelve months as OEMs validate force-limiting feeder interfaces.
Strategic Opportunities
- Medical device feeder segments:Swiss-German manufacturing footprints are anchoring premium positioning in cleanroom-validated bowl feeder systems for pharmaceutical packaging lines.
- Watchmaking precision applications:Micro-component orientation below one millimeter is opening specification windows for linear drive technology with closed-loop positioning feedback.
- Food-grade stainless steel construction:Quick-changeover tooling requirements in dairy and beverage packaging are commanding price premiums over standard industrial grades.
Industry Challenges
- IEC 62061 functional safety certification:Automotive OEM procurement specifications are gating feeder platform redesigns before capital commitment, compressing vendor R&D cycles.
- Legacy pneumatic system integration:Retrofitting vibratory feeders with electric drive technology requires redesign of mounting interfaces and control architectures.
- Acoustic damping engineering talent:Finite element modeling expertise for polymer composite bowl resonance suppression is concentrated among a narrow supplier base in southern Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Part Feeder Market |
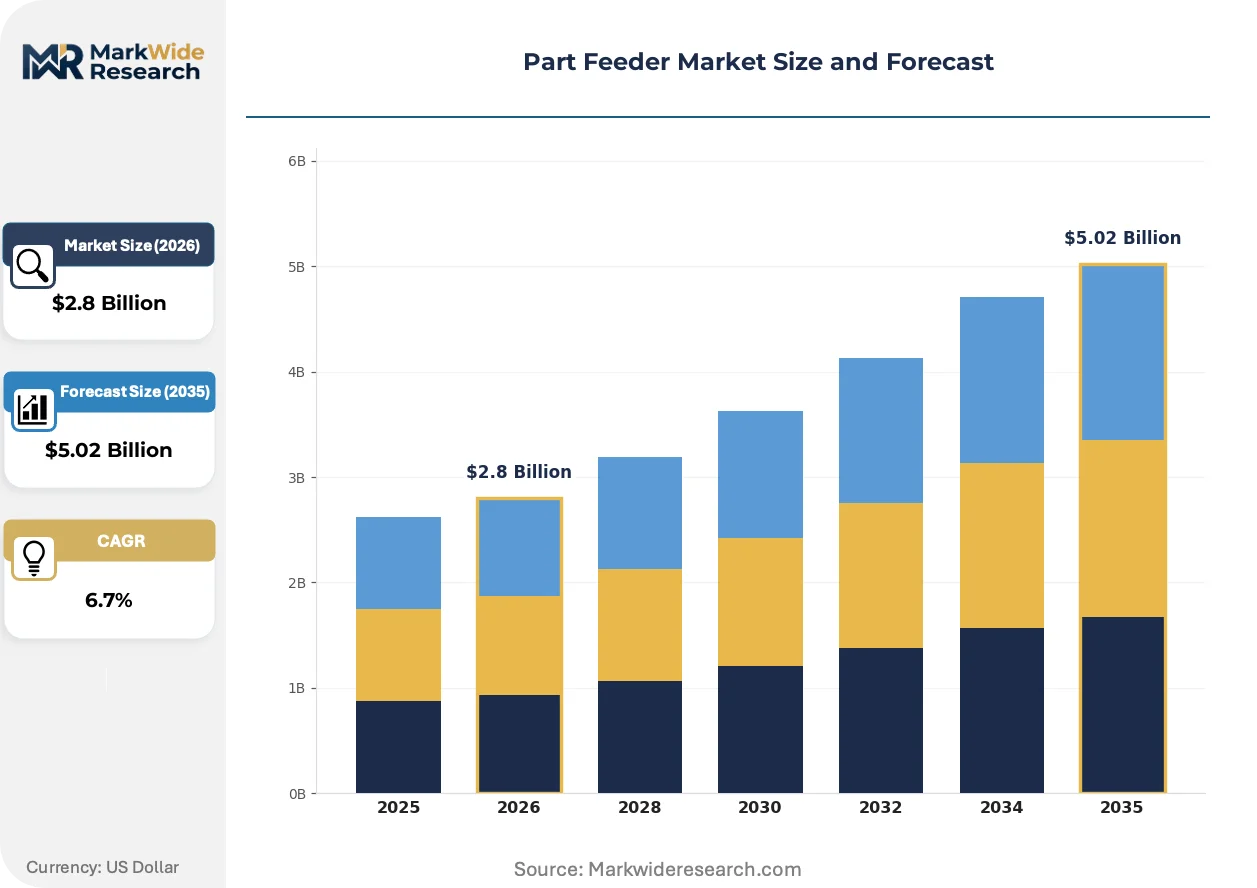
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vibratory, Belt, Bowl, Linear End User: Automotive, Electronics, Healthcare, Packaging Installation: Automated, Manual, Mobile, Fixed Capacity: Low, Medium, High, Customized |
| Companies Covered | Rhein-Nadel Automation (RNA), Afag Automation, Weber Schraubautomaten GmbH, SANKI, Performance Feeders, Asyril, Graco, NTN, DEPRAG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Part Feeder Market Evolving Landscape
Feeder technology is pivoting toward electric actuation and intelligent control architectures that compress energy consumption while expanding programmable motion profiles for complex component geometries.
Electromagnetic linear drive technology is electrifying traditional vibratory bowl configurations by replacing pneumatic actuators with direct-drive voice coil motors. Medical device manufacturers in Switzerland are specifying these systems for micro-implant handling where stroke precision below ten micrometers is mandatory. The shift is compressing maintenance intervals from quarterly to annual cycles while eliminating compressed air infrastructure from cleanroom environments.
REACH substance restrictions on nickel-bearing alloys are forcing migration toward austenitic stainless steel grades in bowl feeder fabrication for European pharmaceutical applications. Surface passivation requirements under the EU Medical Device Regulation are extending qualification timelines for new material formulations. German feeder OEMs are responding by consolidating supply relationships with certified steel mills in the Ruhr region to secure batch traceability documentation.
Buyer concentration among automotive tier-one suppliers is compressing procurement cycles from twelve-month frameworks to quarterly volume commitments with price renegotiation clauses. Direct sourcing teams at Stuttgart-based assembly plants are disintermediating traditional distribution channels for spare parts and consumable tooling. The shift is most visible in screwdriving-integrated feeder systems where backward integration into drive technology is becoming a vendor selection criterion.
Part Feeder Market Segmentation
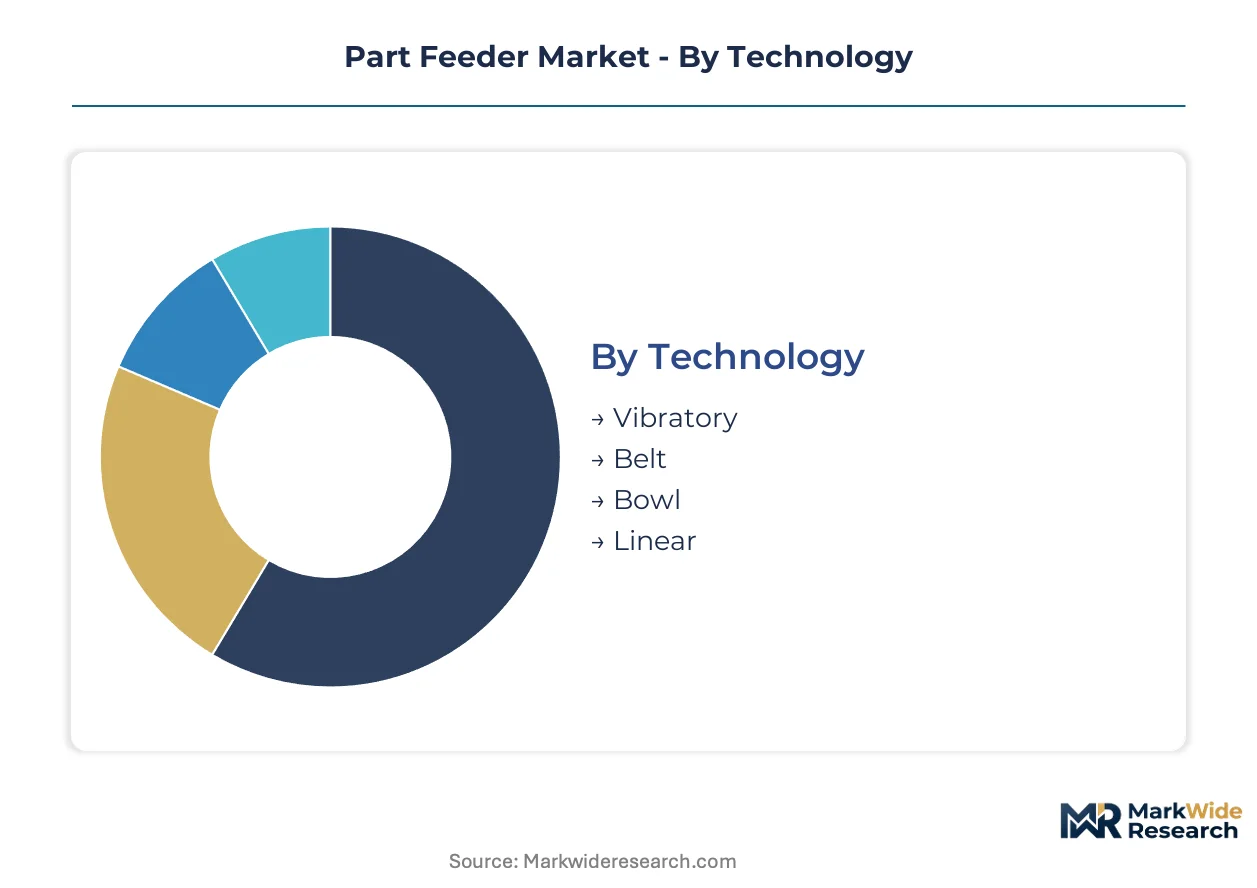
Part feeder configurations diverge sharply across vibration frequency, drive architecture, and mounting topology. Specification intensity concentrates where automotive fastener throughput, electronics particle control, and pharmaceutical validation requirements create incompatible performance envelopes.
Technology:
Drive architecture and motion control philosophy separate configurations along frequency range, precision tolerance, and cleanroom compatibility.
- Vibratory:Electromagnetic coil actuation generates elliptical motion patterns through tuned spring-mass systems. Automotive fastener delivery in Stuttgart assembly plants sustains the largest installed base, though pneumatic-to-electric retrofits are compressing maintenance intervals.
- Linear:Direct-drive voice coil motors deliver stroke precision below ten micrometers with programmable acceleration profiles. Electronics cleanrooms in Dresden and semiconductor packaging facilities across South Korea specify these systems where ISO Class 7 particle thresholds are mandatory.
- Bowl:Polymer composite or stainless steel spiral tracks orient components through controlled vibration. Surface finishing tolerances within 0.05 mm anchor premium positioning in medical device and watchmaking segments.
- Belt:Continuous conveyor surfaces handle irregular geometries and soft components unsuited to vibration. Food-grade stainless steel construction commands price premiums in dairy packaging lines.
Vibratory technology leads on scale; linear drive configurations lead on momentum.
End User:
Downstream process requirements dictate force-limiting interfaces, material validation, and changeover tooling specifications.
- Automotive:Tier-one suppliers around Munich specify high-speed bowl and linear configurations for lightweight composite component handling. EU Machinery Directive compliance mandates are pulling investment into human-robot workcell integration.
- Electronics:Semiconductor packaging facilities prioritize particle suppression and programmable motion profiles. Linear feeder adoption is climbing fastest where micro-implant handling demands stroke precision below ten micrometers.
- Healthcare:Pharmaceutical packaging lines require austenitic stainless steel construction under REACH substance restrictions. Surface passivation documentation extends qualification timelines for new material formulations.
- Packaging:Quick-changeover tooling and stainless steel hygiene ratings dominate dairy and beverage applications. Belt technology occupies the dominant share in this segment.
Automotive anchors volume concentration; healthcare is expanding most quickly on regulatory tailwinds.
Installation:
Mounting flexibility and human-robot collaboration depth shape capital deployment and safety certification pathways.
- Automated:Fixed-position robotic workcells with force-limiting interfaces and emergency-stop integration. ISO 10218 validation timelines extend six to twelve months for collaborative configurations.
- Manual:Operator-tended stations with lockout-tagout compliance under OSHA frameworks. Lower capital barriers sustain presence in mid-tier fabrication environments.
- Mobile:Castor-mounted units with quick-disconnect utilities for flexible production layouts. Demand is climbing in contract manufacturing where product mix volatility requires frequent line reconfiguration.
- Fixed:Permanent foundation mounting for high-throughput continuous operation. Stuttgart automotive assembly plants favor these configurations for screwdriving-integrated feeder systems.
Fixed installation dominates throughput-intensive environments; mobile configurations are gaining share fastest on flexibility premiums.
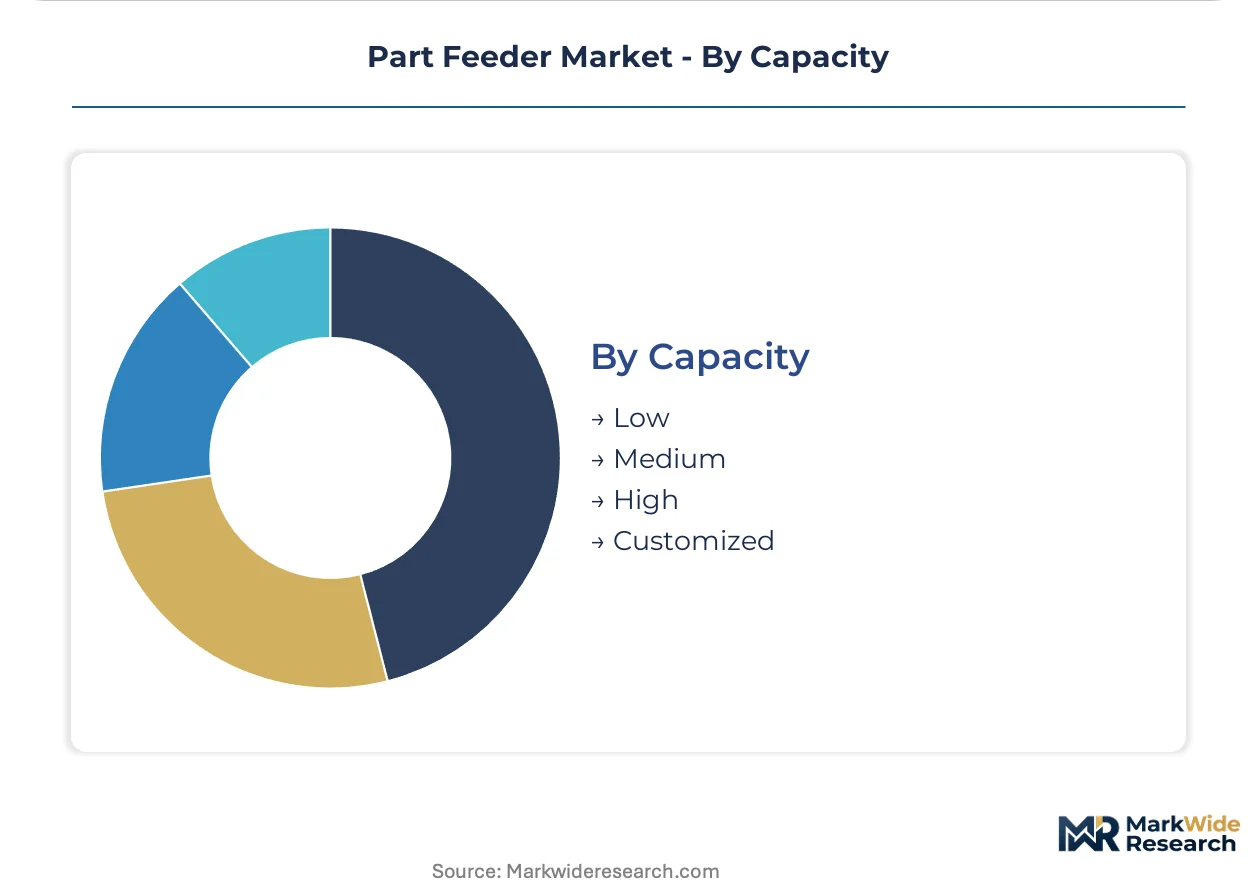
Capacity:
Throughput specification and component geometry complexity determine drive sizing, bowl diameter, and control architecture investment.
- Low:Feed rates below 100 parts per minute for large or fragile components. Watchmaking micro-component orientation below one millimeter concentrates specification in Swiss precision engineering clusters.
- Medium:100-500 parts per minute range serving general industrial automation. This tier captures the broadest cross-section of packaging and electronics applications.
- High:500-1,000+ parts per minute with closed-loop feedback and thermal management. Automotive fastener delivery systems in Munich anchor demand for sustained high-frequency operation.
- Customized:Application-specific designs with non-standard bowl geometries or multi-track configurations. Medical device manufacturers in Switzerland specify these for micro-implant handling validation.
High-capacity systems lead on revenue per unit; customized configurations are climbing fastest on specification intensity in medical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stuttgart-Munich engineering corridor concentrates specification intensity for high-speed linear and bowl feeder configurations, with German precision engineering clusters driving demand for force-limiting interfaces compliant with EU Machinery Directive mandates.
Germany
Automotive tier-one suppliers around Stuttgart specify bowl and linear feeders for lightweight composite component handling. The EU Machinery Directive mandates emergency-stop integration and force-limiting interfaces for human-robot workcells. Munich-based assembly plants anchor demand for screwdriving-integrated systems with backward integration into drive technology.
United States
Electronics cleanrooms in Austin and semiconductor packaging facilities across Arizona prioritize linear feeders with particle suppression below ISO Class 7 thresholds. OSHA lockout-tagout regulations govern manual feeder station compliance in mid-tier fabrication environments. The Pacific Northwest hosts medical device manufacturers specifying micro-implant handling systems with stroke precision below ten micrometers.
Japan
Watchmaking precision applications in Nagoya and micro-component orientation below one millimeter drive specification for linear drive technology with closed-loop positioning feedback. METI industrial robot certification frameworks create divergent compliance costs for export-oriented suppliers. The Kansai region concentrates demand for cleanroom-validated bowl feeder systems in pharmaceutical packaging lines.
Switzerland
Medical device manufacturers in Geneva and Basel specify electric linear drive systems for micro-implant handling where stroke precision below ten micrometers is mandatory. Swissmedic regulations extend qualification timelines for surface passivation documentation under EU Medical Device Regulation alignment. The Swiss-German manufacturing footprint anchors premium positioning in pharmaceutical and watchmaking feeder segments.
South Korea
Semiconductor packaging facilities in Suwon and Pyeongtaek specify linear feeder configurations where ISO Class 7 particle thresholds are mandatory for cleanroom operation. MFDS pharmaceutical regulations drive stainless steel construction requirements in medical device feeder applications. The Seoul Capital Area concentrates electronics cleanroom expansion for programmable motion profile adoption.
Part Feeder Market Competitive Landscape
Backward integration into drive technology dominates the current landscape as vendors consolidate control over critical subsystems. The vendor base clusters around three strategic archetypes: captive tooling specialists controlling bowl surface finishing tolerances, Swiss-German precision engineering houses serving medical and watchmaking segments, and screwdriving-integrated system providers with in-house drive technology. M&A activity and capacity expansion in polymer composite fabrication represent the two dominant competitive moves reshaping supply-side positioning.
Among German-based fabricators, Rhein-Nadel Automation GmbH exemplifies the captive tooling specialist archetype, while Weber Schraubautomaten GmbH occupies a position representing screwdriving-integrated system providers with upstream control over drive technology. Afag Automation sits within the Swiss-German precision engineering tier, anchoring premium positioning in cleanroom-validated applications.
| Leading Market Players |
|---|
| Rhein-Nadel Automation (RNA) |
| Afag Automation |
| Weber Schraubautomaten GmbH |
| SANKI |
| Performance Feeders |
| Asyril |
| Graco |
| NTN |
| DEPRAG |
| Others |
Value Network & Pricing Analysis
Polymer composite raw material costs flow through captive tooling investments to stratify pricing across three tiers: premium bowl systems with 0.05 mm surface tolerances, standard electromagnetic configurations, and economy-grade pneumatic alternatives. Stuttgart automotive tier-one suppliers absorb premium pricing for screwdriving-integrated systems, while mid-tier fabricators face capital barriers that compress margins in the standard tier.
Pricing Analysis
Input-cost pass-through from nickel-bearing alloy restrictions under REACH regulations is intensifying price divergence between austenitic stainless steel grades and polymer composite alternatives. Three-tier pricing structure across premium, standard, and economy levels separates medical device validation tiers from automotive volume procurement and manual-station economy configurations. Pricing pressure stems from buyer concentration among automotive tier-one suppliers demanding quarterly renegotiation clauses. Electronics cleanroom operators show least price sensitivity due to ISO Class 7 compliance mandates, while packaging segment buyers prioritize quick-changeover tooling economics.
Supply Chain Analysis
CE marking and ISO 10218 functional safety certifications gate supplier access to EU automotive procurement channels, compressing vendor qualification timelines. Manufacturing concentrates in Germany, Switzerland, and South Korea, with Ruhr-region steel mills supplying traceable austenitic grades for pharmaceutical applications. Raw material dependencies span polymer composites, electromagnetic voice coil assemblies, and precision-machined aluminum castings. Single-source vulnerability concentrates in southern Germany for finite element modeling expertise on acoustic damping. Distribution runs through direct sourcing teams at Stuttgart-based assembly plants disintermediating traditional spare parts channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification intensity for micro-implant handling below ten micrometers is displacing commodity pneumatic configurations across medical and watchmaking segments.
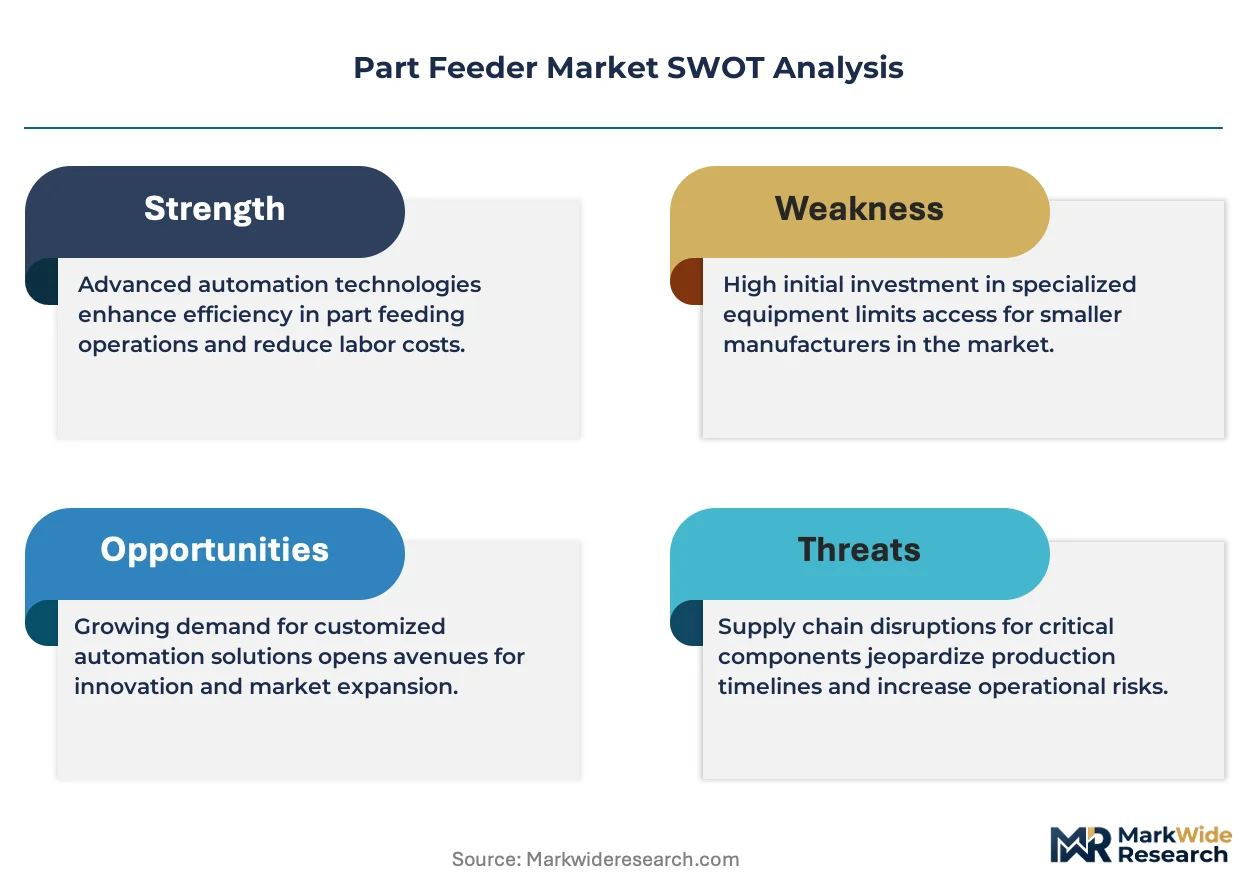
For Market Incumbents: Anchor premium positioning by deepening backward integration into drive technology and consolidating captive tooling capabilities for bowl surface finishing. Defend against electric linear drive substitution by accelerating IEC 62061 functional safety certification timelines that gate automotive OEM procurement. Prioritize capacity addition in the Swiss-German corridor to capture medical device validation workflows. For New Entrants and Emerging Players: EU Machinery Directive compliance mandates in Germany open a window for force-limiting interface specialists targeting human-robot workcell retrofits. Penetrate the mobile installation segment where contract manufacturing demand for flexible line reconfiguration outpaces incumbent response capacity. Pursue partnership routes with automotive tier-one direct sourcing teams rather than legacy distribution channels. For Investors and Strategic Acquirers: Consolidation pressure builds where captive polymer composite fabrication capabilities concentrate among narrow supplier bases in southern Germany. Five-to-ten-year viability favors targets with certified steel mill relationships and cleanroom validation documentation rather than undifferentiated pneumatic system portfolios. Watch for inflection when automotive OEMs mandate closed-loop positioning feedback as standard procurement specification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drive Technology | Weber Schraubautomaten GmbH exemplifies upstream control over voice coil motor sourcing that compresses maintenance intervals. |
| Captive Polymer Composite Tooling Investment | Rhein-Nadel Automation's 0.05 mm surface tolerance capability anchors premium medical segment positioning. |
| ISO 10218 Safety Certification Acceleration | Force-limiting interface validation timelines determine competitive access to collaborative robot workcell specifications. |
| Swiss-German Manufacturing Footprint Expansion | Afag Automation's regional concentration captures pharmaceutical packaging line demand under Swissmedic regulations. |
| Direct Sourcing Channel Development | Stuttgart automotive assembly plants are disintermediating spare parts distributors for screwdriving-integrated system procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and automation integration specialists against secondary validation through SEC filings, customs trade records, VDMA automation sector reports, and EU Machinery Directive implementation documentation. Bottom-up capacity modeling across polymer composite fabricators and top-down demand estimation from automotive production databases were reconciled through iterative triangulation.
Comparable historical periods anchored the projection horizon across technology, end-user, installation, and capacity segmentation dimensions, with CAGRs derived from regression analysis of adoption curves for electric linear drive substitution. Feed rate specifications, ISO cleanliness class thresholds, and regional regulatory cluster compliance costs served as industry-specific forecast inputs.
Revisions become necessary when EU Machinery Directive enforcement intensity shifts, REACH substance restrictions expand, or automotive lightweight composite adoption accelerates beyond current Stuttgart-Munich corridor expansion rates. A model refresh is warranted upon material change in IEC 62061 functional safety rating adoption as de facto automotive OEM procurement gate.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Walform Machines Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Stamping Machines Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Deep Hole Drilling Machines Market