
 United Kingdom AI in Fintech Market | 2026-2036
United Kingdom AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom AI in Fintech Market Insights
Subscription-based AI fraud detection is consolidating as the dominant revenue model for fintech infrastructure vendors. Revolut leverages machine learning pipelines across its multi-currency platform to sustain transaction monitoring scale. Monzo anchors its competitive stance through real-time spending analytics that differentiate its retail banking interface. Adyen competes in merchant acquiring by extending AI-powered risk scoring across cross-border payment corridors.
United Kingdom AI in Fintech encompasses algorithmic systems that process financial data through neural networks, natural language models, and robotic automation to execute decisions previously requiring human judgment; these systems operate with latency thresholds below fifty milliseconds for high-frequency trading applications while maintaining audit trails mandated by prudential supervisors. Fraud detection solutions occupy the largest deployment share as legacy banks replace rules-based engines with adaptive models that reduce false-positive rates. Natural language processing applications in customer service automation represent the fastest-expanding solution category as voice-enabled assistants handle compliance-sensitive queries without human escalation. Cloud-based deployment dominates infrastructure choices though hybrid architectures gain traction among investment firms managing classified client portfolios.
The Financial Conduct Authority and the Prudential Regulation Authority jointly govern AI deployment through the consumer duty and operational resilience frameworks that mandate explainability standards for automated lending decisions. The Bank of England's AI Public-Private Forum shapes supervisory expectations for model risk management across systemically important payment systems. Stakeholders must monitor how the Digital Regulation Cooperation Forum harmonizes enforcement approaches across competition, data protection, and financial conduct mandates as algorithmic products blur traditional regulatory boundaries.
Market Dynamics
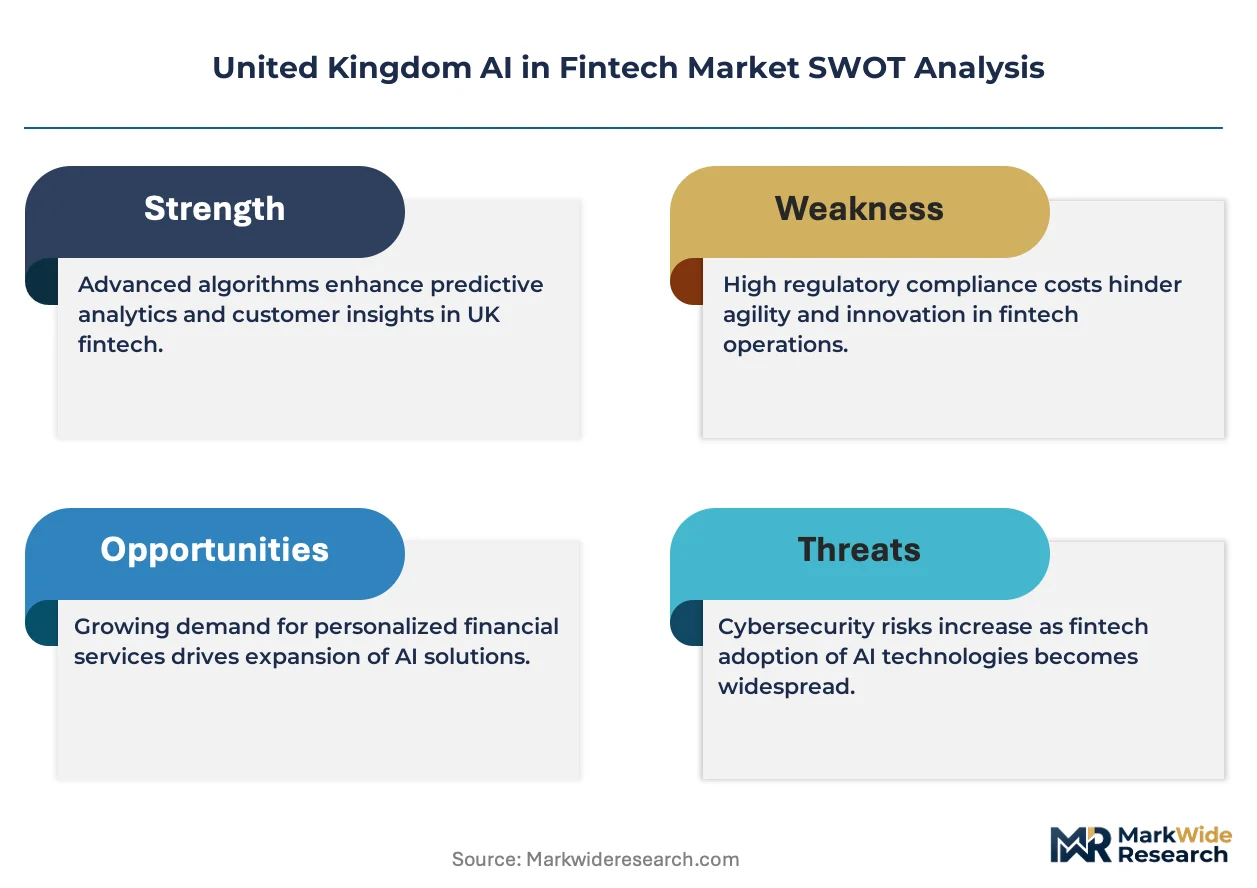
The Financial Conduct Authority's consumer duty framework is compressing product development cycles as challenger banks race to embed explainable AI into lending pipelines before compliance deadlines crystallize.
Growth Catalysts
- Regulatory Sandboxing:The FCA's sandbox program accelerates deployment timelines for AI-native payment infrastructure by permitting live testing under modified authorization conditions.
- Neural Network Automation:Transformer architectures slash false-positive rates in transaction monitoring, pulling demand from legacy rules-based fraud engines across retail banking.
- London Talent Density:The Square Mile's concentration of quantitative researchers and venture capital creates self-reinforcing innovation clusters for algorithmic trading applications.
Market Restraints
- Compute Cost Volatility:GPU scarcity inflates training costs for large language models, squeezing margin structures at mid-tier infrastructure vendors.
- Data Localization Mandates:Prudential Regulation Authority guidance on operational resilience fragments cloud architectures, forcing hybrid deployments that degrade latency performance.
- Rules-Based Engine Inertia:Tier-one clearing banks face technical debt burdens from decades-old COBOL cores that resist API-layer abstraction.
Strategic Opportunities
- Open Finance APIs:The UK's implementation of PSD3 standards creates white space for consent-driven wealth management algorithms that aggregate fragmented account data.
- Voice-Enabled Compliance:Natural language processing converges with biometric authentication to automate Know Your Customer verification without human escalation pathways.
- Scotland's Fintech Corridor:Edinburgh's lower operating costs and university research partnerships offer expansion terrain for AI model development outside London's rent pressure.
Industry Challenges
- Explainability Engineering:The shortage of machine learning operations specialists capable of documenting algorithmic decision trails stalls automated underwriting rollouts.
- Model Risk Governance:The Bank of England's evolving expectations for AI validation frameworks force repeated architecture redesigns during deployment phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom AI in Fintech Market |
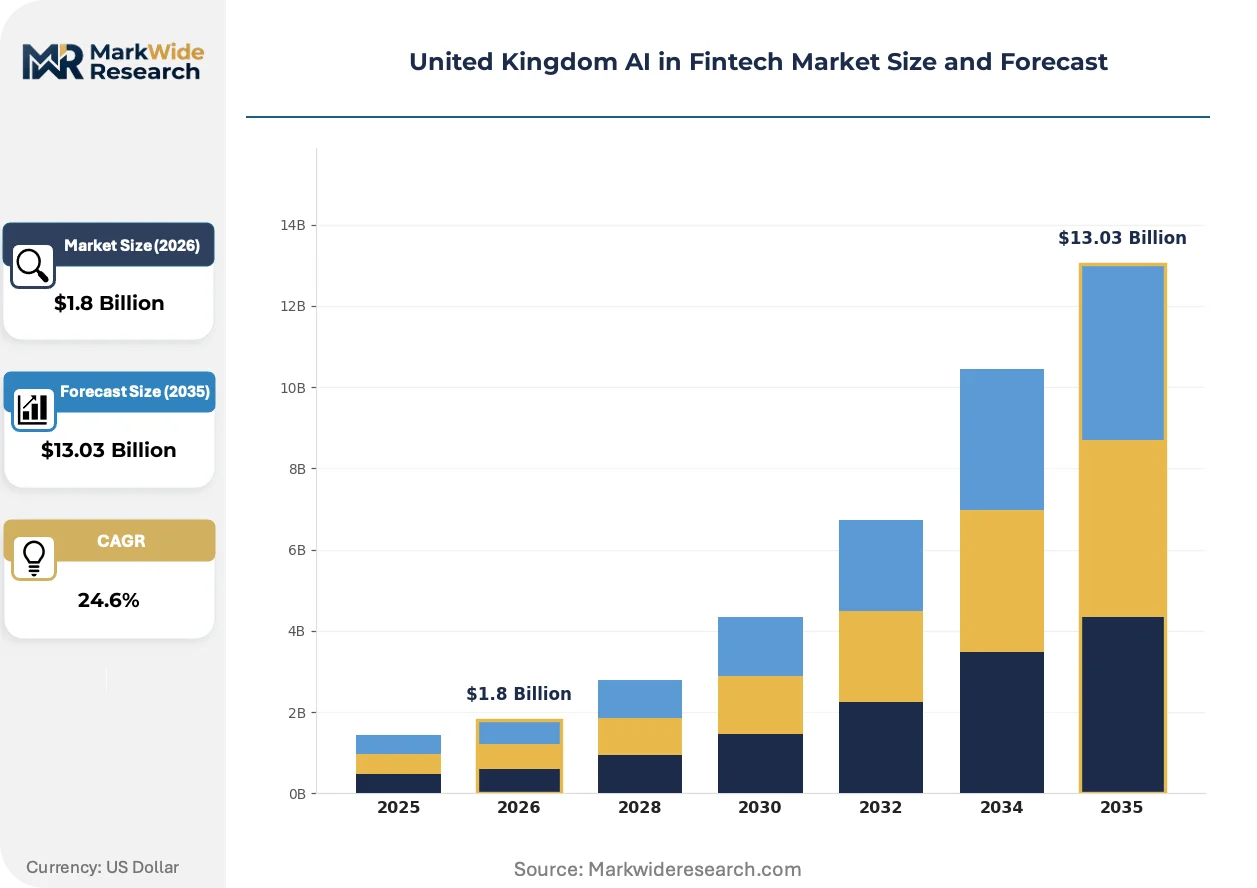
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Assessment, Customer Service Automation, Credit Scoring, Algorithmic Trading, Compliance Monitoring Solution: Machine Learning Platforms, Natural Language Processing, Robotic Process Automation, Predictive Analytics, Computer Vision, Chatbots End User: Banks, Fintech Startups, Insurance Companies, Investment Firms, Payment Providers, Wealth Management Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Revolut, Monzo, Abound, QuantoPay, Adyen, JPMorgan Chase, Affirm, Fetch.ai, PolyAI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom AI in Fintech Market Trends and Innovations
Generative architectures are penetrating financial workflows previously guarded by deterministic systems, compressing the boundary between experimental research and production-grade infrastructure.
Federated learning architectures are converging with differential privacy techniques to enable cross-institutional model training without raw data sharing. Consortiums of regional building societies adopt these methods to pool fraud pattern recognition while preserving customer confidentiality. The structural consequence is a shift from centralized data lakes toward distributed intelligence networks that reduce single-point breach exposure.
The FCA's consumer duty rules mandate that automated lending decisions carry human-interpretable rationale documentation. Product teams redesign neural network outputs to generate natural language explanations alongside credit determinations. Retail banking interfaces now embed transparency layers that satisfy supervisory audit requirements while maintaining sub-second response times.
Corporate treasury functions increasingly source AI fraud detection through subscription APIs rather than perpetual license deployments. Mid-market merchants in Manchester and Birmingham adopt modular, pay-per-transaction risk scoring that scales with seasonal volume fluctuations. This procurement pattern displaces capital-intensive on-premise installations and concentrates vendor relationships around platform ecosystems with native integration depth.
United Kingdom AI in Fintech Market Segmentation
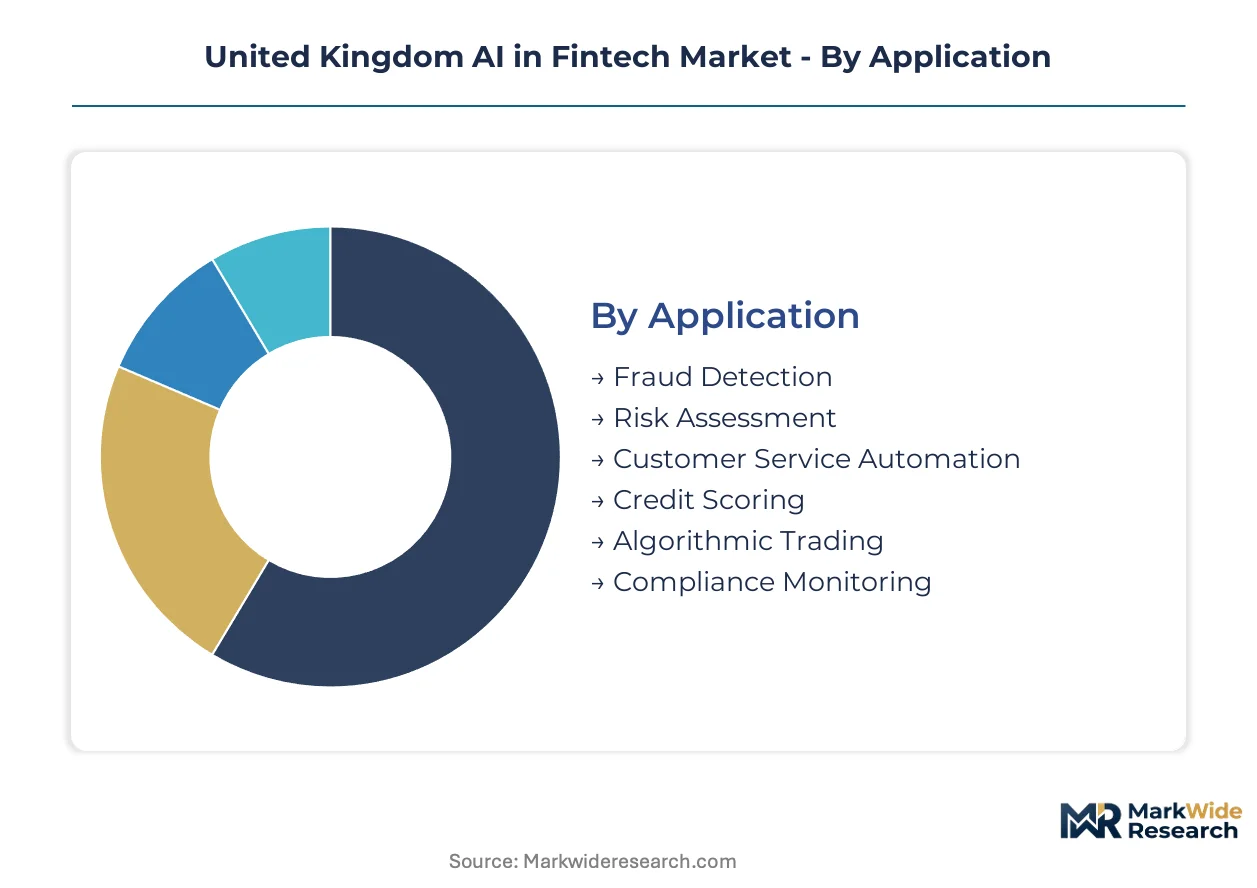
Segmentation of United Kingdom AI in Fintech reveals how deployment choices and solution architectures map to distinct regulatory pressures and latency requirements across London's financial corridor. Buyers select categories based on explainability mandates from the Financial Conduct Authority and operational resilience thresholds set by the Prudential Regulation Authority.
Application:
Application selection hinges on the tension between automation depth and audit trail completeness demanded by UK prudential supervisors.
- Fraud Detection:Adaptive neural networks replace rules-based transaction monitoring engines, cutting false-positive rates while maintaining sub-fifty-millisecond response times for high-frequency payment rails. Demand concentrates at challenger banks and payment providers facing FCA consumer duty deadlines for explainable automated decisions.
- Risk Assessment:Transformer architectures process multi-source credit data through natural language models that generate human-interpretable rationale documentation alongside scoring outputs. Investment firms and wealth managers deploy these systems to satisfy model risk governance expectations from the Bank of England's AI Public-Private Forum.
- Customer Service Automation:Voice-enabled assistants handle compliance-sensitive queries without human escalation, expanding fastest among retail banks seeking operational cost reduction.
- Credit Scoring:Alternative data pipelines ingest open banking feeds to expand lending access while embedding transparency layers for supervisory audit.
- Algorithmic Trading:Low-latency execution systems cluster in London's quantitative trading desks where talent density and co-location infrastructure converge.
- Compliance Monitoring:Real-time surveillance of communications and transactions automates regulatory reporting for tier-one clearing banks burdened by legacy COBOL technical debt.
Fraud Detection leads on scale; Customer Service Automation leads on momentum.
Solution:
Solution procurement patterns reflect the shift from perpetual licenses toward subscription APIs that scale with transaction volume.
- Machine Learning Platforms:End-to-end model development environments with native MLOps capabilities support automated underwriting pipelines at fintech startups and challenger banks. Cloud-native deployments dominate though hybrid architectures gain traction among investment firms managing classified client portfolios under Prudential Regulation Authority data localization guidance.
- Natural Language Processing:Large language models fine-tuned on financial domain corpora power document extraction and sentiment analysis for compliance and research functions. Scottish university partnerships in Edinburgh drive R&D cost advantages outside London's rent pressure.
- Robotic Process Automation:Rules-based bots handle repetitive back-office workflows at legacy banks modernizing core systems incrementally.
- Predictive Analytics:Forecasting models optimize treasury operations and liquidity management across corporate banking divisions.
- Computer Vision:Document verification and biometric authentication automate Know Your Customer checks at onboarding.
- Chatbots:Conversational interfaces deflect routine service inquiries while escalating complex cases to human agents.
Machine Learning Platforms anchor vendor revenue; Natural Language Processing is climbing the fastest.
End User:
End user category penetration varies with regulatory sandbox access and venture capital depth across the UK financial technology corridor.
- Banks:Tier-one clearing institutions and challenger banks deploy divergent AI strategies—legacy players retrofit API layers atop decades-old cores while digital natives build AI-native infrastructure from inception. The FCA's sandbox program accelerates deployment timelines for challenger banks testing novel payment infrastructure under modified authorization conditions.
- Fintech Startups:Venture-backed firms concentrate in London's financial technology corridor where regulatory sandbox access and quantitative researcher talent create self-reinforcing innovation clusters. GPU scarcity inflates training costs, squeezing margin structures at mid-tier infrastructure vendors serving this segment.
- Insurance Companies:Claims automation and pricing optimization drive adoption among general insurers and life offices.
- Investment Firms:Asset managers deploy alternative data ingestion and algorithmic execution to differentiate alpha generation.
- Payment Providers:Cross-border risk scoring and real-time fraud detection sustain competitive positioning in merchant acquiring.
- Wealth Management:PSD3 implementation creates white space for consent-driven algorithms aggregating fragmented account data across providers.
Banks command the largest deployment budgets; Fintech Startups show the steepest expansion trajectory.
Deployment:
Deployment architecture decisions trade latency performance against data sovereignty requirements under operational resilience frameworks.
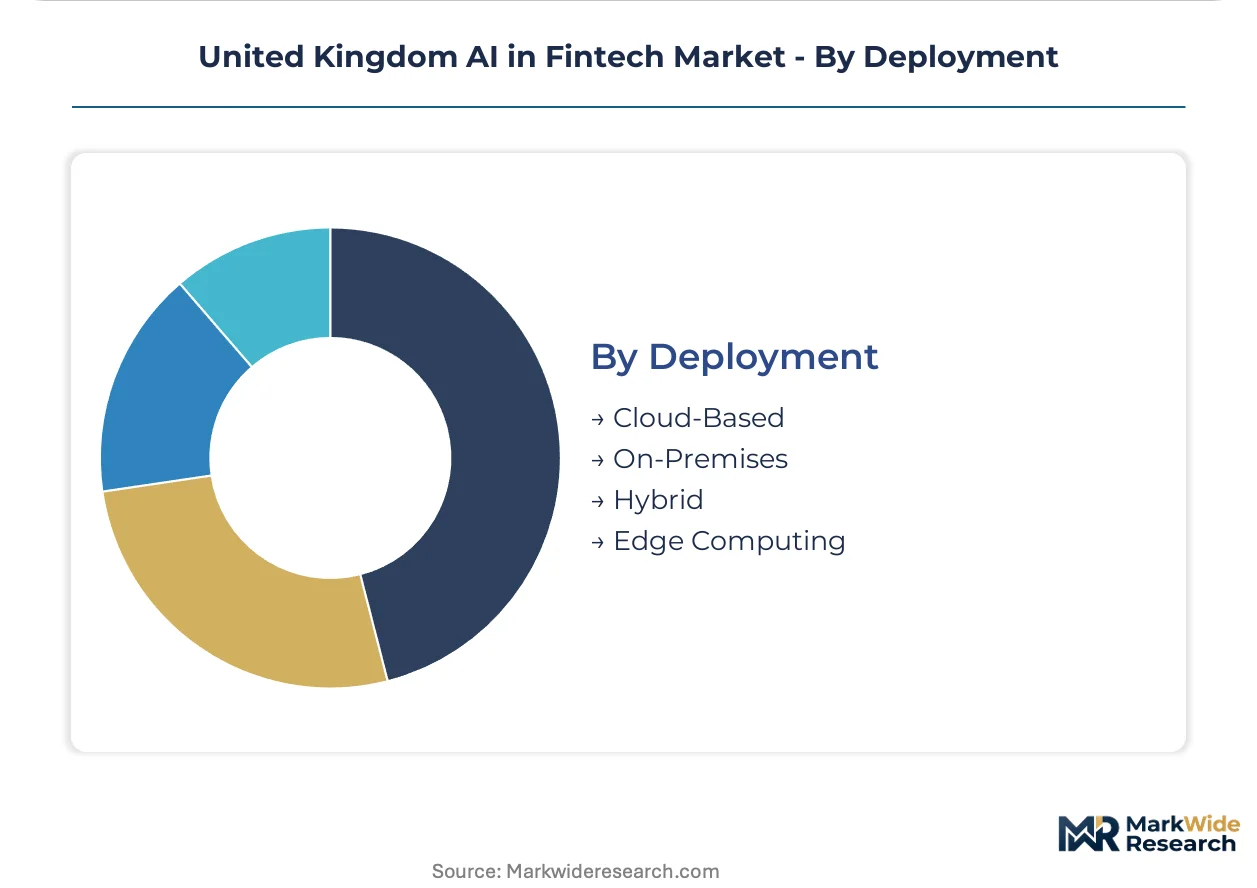
- Cloud-Based:Hyperscaler infrastructure dominates model training and inference workloads for fintech startups and mid-tier banks lacking capital-intensive data center investments. The Prudential Regulation Authority's guidance on operational resilience fragments pure cloud architectures for systemically important payment systems.
- Hybrid:Split workloads between cloud training and on-premises inference satisfy classified data handling requirements at investment firms and wealth managers. These deployments degrade latency performance relative to pure cloud but preserve regulatory compliance for sensitive client portfolios.
- On-Premises:Captive infrastructure persists at tier-one clearing banks with decades-old technical debt resisting cloud migration.
- Edge Computing:Distributed inference nodes process transactions at merchant locations and branch networks for ultra-low-latency applications.
Cloud-Based holds the dominant share; Hybrid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are fragmenting AI fintech development across the United Kingdom as compliance cost differentials between England and devolved administrations reshape talent migration patterns. Scotland's lower operating costs attract model development labs fleeing London's rent pressure, while Welsh data center incentives pull cloud training workloads westward.
London and the Southeast
The Square Mile's venture capital depth and FCA sandbox access concentrate AI-native challenger banks and quantitative trading desks. The Financial Conduct Authority's consumer duty framework compresses product development cycles for firms testing automated lending infrastructure. Canary Wharf and Shoreditch form self-reinforcing innovation clusters where payment providers and wealth managers cluster for regulatory proximity.
Scotland
Edinburgh's university research partnerships and lower cost base attract federated learning consortia and natural language processing R&D. The Scottish government's fintech strategy funds AI ethics centers that align with Bank of England model risk expectations. Glasgow's emerging tech corridor hosts voice-enabled compliance startups serving UK-wide Know Your Customer automation demand.
North England
Manchester and Leeds merchant acquiring markets drive subscription-based fraud detection adoption among mid-market retailers. The Northern Powerhouse investment program supports cloud infrastructure expansion for hybrid deployment architectures. Regional building societies pool alternative data pipelines to expand credit access under prudential supervision.
Midlands
Birmingham's corporate banking presence sustains demand for robotic process automation retrofitting legacy COBOL cores. The West Midlands fintech cluster leverages proximity to manufacturing supply chains for trade finance algorithm development. Operational resilience guidance from the Prudential Regulation Authority fragments pure cloud architectures toward hybrid setups.
Wales
South Wales data center incentives pull GPU training workloads from London as compute cost volatility squeezes mid-tier vendors. Cardiff's regulatory technology sector specializes in explainability engineering for automated underwriting audit trails. Welsh Development Bank funding targets AI model development outside England's regulatory intensity.
United Kingdom AI in Fintech Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with AI-native challengers capturing growth while legacy institutions retrofit technical debt. The vendor base stratifies into three tiers: hyperscaler-backed platforms, venture-scaled fintechs, and incumbent banks rebuilding core infrastructure. Dominant competitive moves center on M&A for talent acquisition and strategic partnerships for regulatory sandbox access, while geographic expansion into lower-cost UK regions accelerates.
Within the challenger bank archetype, Revolut and Monzo exemplify AI-native infrastructure built from inception rather than retrofitted atop legacy cores. Adyen anchors the payment infrastructure tier with cross-border risk scoring capabilities. These three occupy positions defined by regulatory sandbox maturity and venture capital backing depth rather than incumbent scale advantages.
| Leading Market Players |
|---|
| Revolut |
| Monzo |
| Abound |
| QuantoPay |
| Adyen |
| JPMorgan Chase |
| Affirm |
| Fetch.ai |
| PolyAI |
| Others |
Pricing and Supply Chain Analysis
Challenger banks' procurement preference for subscription-based fraud detection APIs is forcing infrastructure vendors to abandon perpetual license models and absorb GPU scarcity costs into recurring pricing structures. This demand-side shift compresses margin structures at mid-tier vendors while concentrating pricing power among hyperscaler-backed platforms with captive compute access.
Pricing Analysis
Direct-to-fintech discounts dominate the channel structure, bypassing traditional distributor markups for API-first procurement relationships. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade explainability engineering from mid-market transaction monitoring and basic rules-based bot deployments. Cost compression in the standard tier is intensifying because GPU training costs inflate while venture capital tightens for Series B infrastructure plays. Mid-market merchants in Manchester and Birmingham exhibit highest price sensitivity, while tier-one clearing banks prioritize audit trail completeness over unit economics.
Supply Chain Analysis
Machine learning operations specialist shortages in London, Edinburgh, and Cambridge constrain model deployment velocity for automated underwriting pipelines. Compute infrastructure draws from Taiwan, South Korea, and USA for GPU fabrication, while cloud hyperscalers anchor training workloads in Dublin, Frankfurt, and Amsterdam data centers. Single-source vulnerability concentrates in NVIDIA's datacenter GPU supply chain, exposing UK vendors to allocation rationing during demand spikes. Distribution runs through direct API marketplaces and strategic partnership channels with regulatory sandbox participants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom AI in Fintech market compounds steadily as regulatory mandates for explainable AI create durable demand for compliance-embedded infrastructure. The Financial Conduct Authority's consumer duty framework ensures replacement cycles for legacy rules-based engines extend through the analysis window.
For Market Incumbents: Anchor defensive positioning through backward integration into MLOps talent pipelines and captive GPU allocation agreements with hyperscalers. Tier-one clearing banks face substitution threat from AI-native challengers; retrofit API abstraction layers atop COBOL cores to compress deployment timelines for automated lending decisions. For New Entrants and Emerging Players: Begin with voice-enabled compliance automation for regional building societies in Scotland and North England, where federated learning consortia seek white-label Know Your Customer solutions. The most penetrable segment sits in mid-market merchant acquiring, where subscription-based fraud detection displaces legacy on-premise installations. Pursue regulatory sandbox partnerships as primary go-to-market credential. For Investors and Strategic Acquirers: Asymmetric upside sits with venture-scaled fintechs holding FCA sandbox maturity and Edinburgh-based NLP R&D partnerships. Five-to-ten year viability hinges on model risk governance capabilities aligned with Bank of England validation expectations. Monitor Prudential Regulation Authority operational resilience guidance revisions as inflection signal for hybrid deployment architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Partnership | FCA-modified authorization accelerates live testing timelines for AI-native payment infrastructure. |
| MLOps Talent Acquisition | Explainability engineering specialists document algorithmic decision trails for automated underwriting audit compliance. |
| Hybrid Cloud Deployment | Split cloud-on-premises architectures satisfy Prudential Regulation Authority data localization guidance for classified portfolios. |
| Federated Learning Consortium | Cross-institutional model training pools fraud pattern recognition without raw customer data sharing. |
| Voice-Enabled Compliance Platform | Natural language processing converges with biometric authentication to automate Know Your Customer verification pathways. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs at challenger banks, machine learning operations leads at infrastructure vendors, regulatory affairs directors at tier-one clearing institutions, and procurement officers at payment providers with secondary validation. Sources included FCA authorization filings, Bank of England AI Public-Private Forum publications, Prudential Regulation Authority operational resilience guidance, venture capital transaction databases, and hyperscaler capex disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation cross-validated volume estimates.
Segment-weighting approaches applied differential growth assumptions across fraud detection, risk assessment, customer service automation, credit scoring, algorithmic trading, and compliance monitoring applications. Deployment models, solution architectures, end-user categories, and regional adoption patterns structured the analytical framework across the projection horizon. CAGRs derived from historical trajectory analysis and regulatory deadline impact modeling, with inputs from GPU supply constraints and open banking API penetration rates.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor supply chains, abrupt FCA consumer duty deadline extensions, and wholesale migration of tier-one banks to fully cloud-native cores. Forecasts reflect assumptions about regulatory enforcement consistency and venture capital availability for Series B infrastructure plays. Material deviation in GPU allocation rationing or Prudential Regulation Authority data localization guidance warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Singapore AI in Fintech Market
FinTech
Blockchain in Fintech Market
FinTech
France BNPL Market
FinTech
Financial Management Software Market
FinTech
Supply Chain Finance Market
FinTech
Autonomous Finance Market
FinTech
Smart Finance Connectivity Market
FinTech
Europe Fintech Market
FinTech
China Fintech Market
FinTech
Asia-Pacific Fintech Market
FinTech
Asia-Pacific Neo Banking Market
FinTech
US AI in Fintech Market
FinTech
Finance Cloud Market
FinTech
Africa AI in Fintech Market
FinTech
Japan AI in Fintech Market
FinTech
Smart Finance Technologies Market