
 Malaysia Fintech Market | 2026-2036
Malaysia Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Fintech Market Foresight
Bank Negara Malaysia's Financial Sector Blueprint is consolidating the cost-of-entry calculus for fintech operators by mandating capital adequacy and consumer protection standards that favor scaled platforms. Touch 'n Go Digital leverages its transport-linked ecosystem to sustain transaction density across retail and transit corridors. GrabPay Malaysia anchors its position through super-app integration with food delivery and mobility services. MoneyMatch specializes in cross-border remittance corridors, competing on forex transparency against incumbent banking channels.
Malaysia fintech encompasses technology-enabled financial services delivered through software platforms, mobile applications, and cloud infrastructure, typically processing transactions via APIs integrated with licensed banking rails and adhering to real-time gross settlement protocols. Its primary commercial purpose is to disintermediate traditional financial intermediation, reduce transaction friction, and extend credit or payment access to digitally native users. Digital Payments leads transaction volume as the most mature segment, while Insurtech Solutions records the fastest expansion driven by embedded distribution models in e-commerce checkout flows. Lending Platforms occupies concentrated margin pools where AI-driven credit scoring enables risk-adjusted pricing for thin-file borrowers across consumer and small business categories.
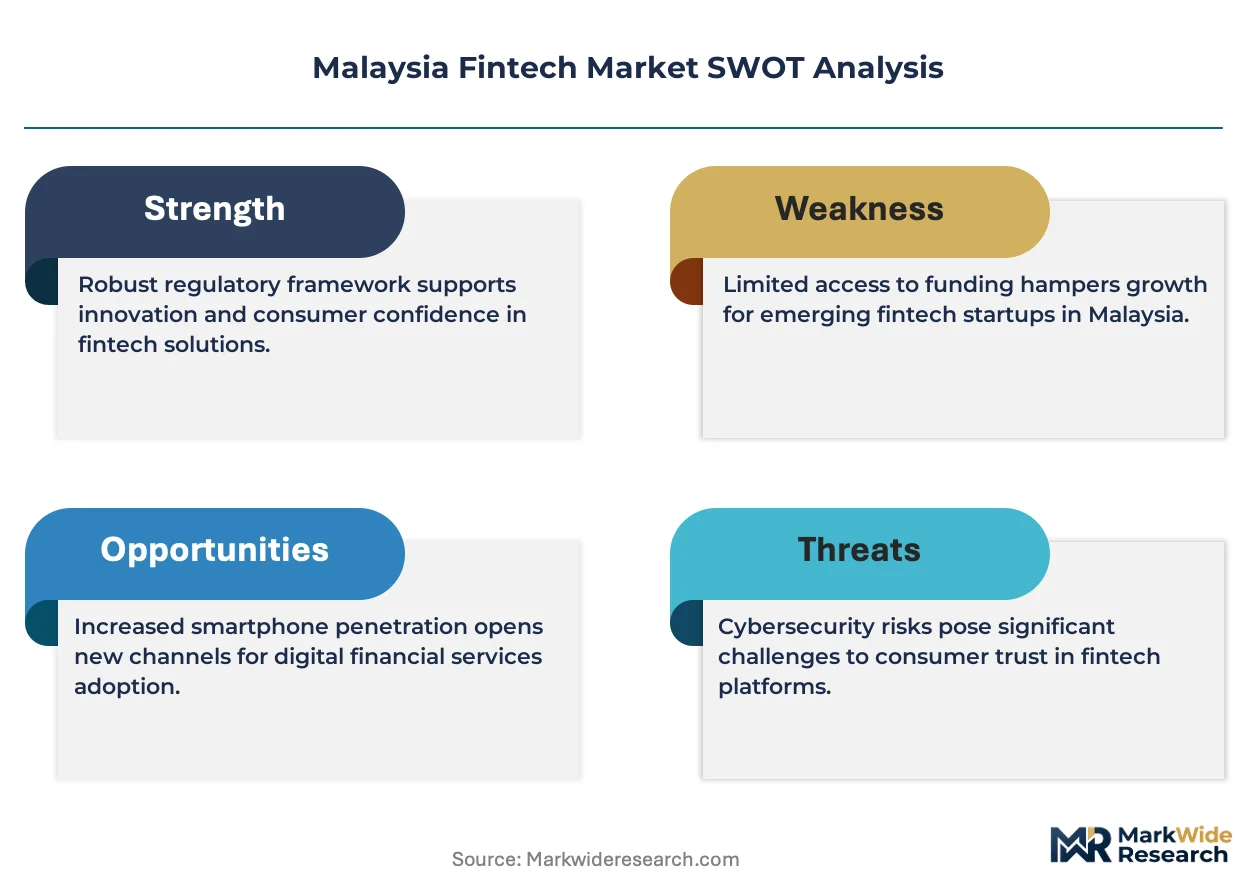
Bank Negara Malaysia enforces licensing frameworks under the Financial Services Act and Payment Services Act, while the Securities Commission Malaysia regulates equity crowdfunding and peer-to-peer lending platforms under its Guidelines on Recognized Markets. These dual regulatory layers shape product design by segregating deposit-taking from payment facilitation and mandating operational resilience standards for cloud-hosted infrastructure. Stakeholders must monitor impending digital banking license renewals and open finance API standards that will determine which technology layers become regulated utilities versus competitive differentiators.
Market Dynamics
Bank Negara Malaysia's e-KYC framework and Payment Services Act licensing regime are compressing time-to-market for digital payment providers while elevating compliance thresholds that favor capitalized platforms over bootstrapped entrants.
Growth Catalysts
- Financial Sector Blueprint:Bank Negara Malaysia's strategic roadmap mandates digital infrastructure investment across banking rails, creating standardized API protocols that reduce integration friction for new payment platforms.
- Underbanked demand concentration:Rural consumer segments in Sabah and Sarawak lack traditional branch access, generating pull for mobile wallet solutions that operate on basic smartphone connectivity.
- Cloud infrastructure maturation:Distributed ledger technology deployments for cross-border remittance settlement are reducing correspondent banking delays and forex opacity in ASEAN corridors.
Market Restraints
- Capital adequacy thresholds:Payment Services Act licensing requires minimum paid-up capital that restricts bootstrapped fintech operators from achieving regulatory authorization.
- Legacy core banking concentration:Incumbent financial institutions maintain proprietary transaction processing infrastructure, creating interoperability friction with API-native platforms.
- Talent scarcity in Shariah-compliant fintech:Shortage of professionals combining Islamic finance certification with software engineering expertise constrains Islamic fintech product development velocity.
Strategic Opportunities
- SME credit gap:Small businesses in Johor and Selangor face documented unmet demand for working capital facilities, creating white space for AI-driven alternative lending platforms.
- Embedded insurance distribution:E-commerce checkout flows enable parametric micro-insurance products that reach previously uninsured consumer segments without standalone policy administration.
- Open finance API standards:Anticipated regulatory mandates for account aggregation will determine which technology layers become regulated utilities versus competitive differentiators for data analytics providers.
Industry Challenges
- Cybersecurity certification timelines:Bank Negara Malaysia's operational resilience standards require penetration testing and disaster recovery validation that extend product launch schedules.
- Interoperability with legacy switch networks:Real-time gross settlement integration demands specialized expertise in mainframe protocols that API-native engineering teams rarely possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Fintech Market |
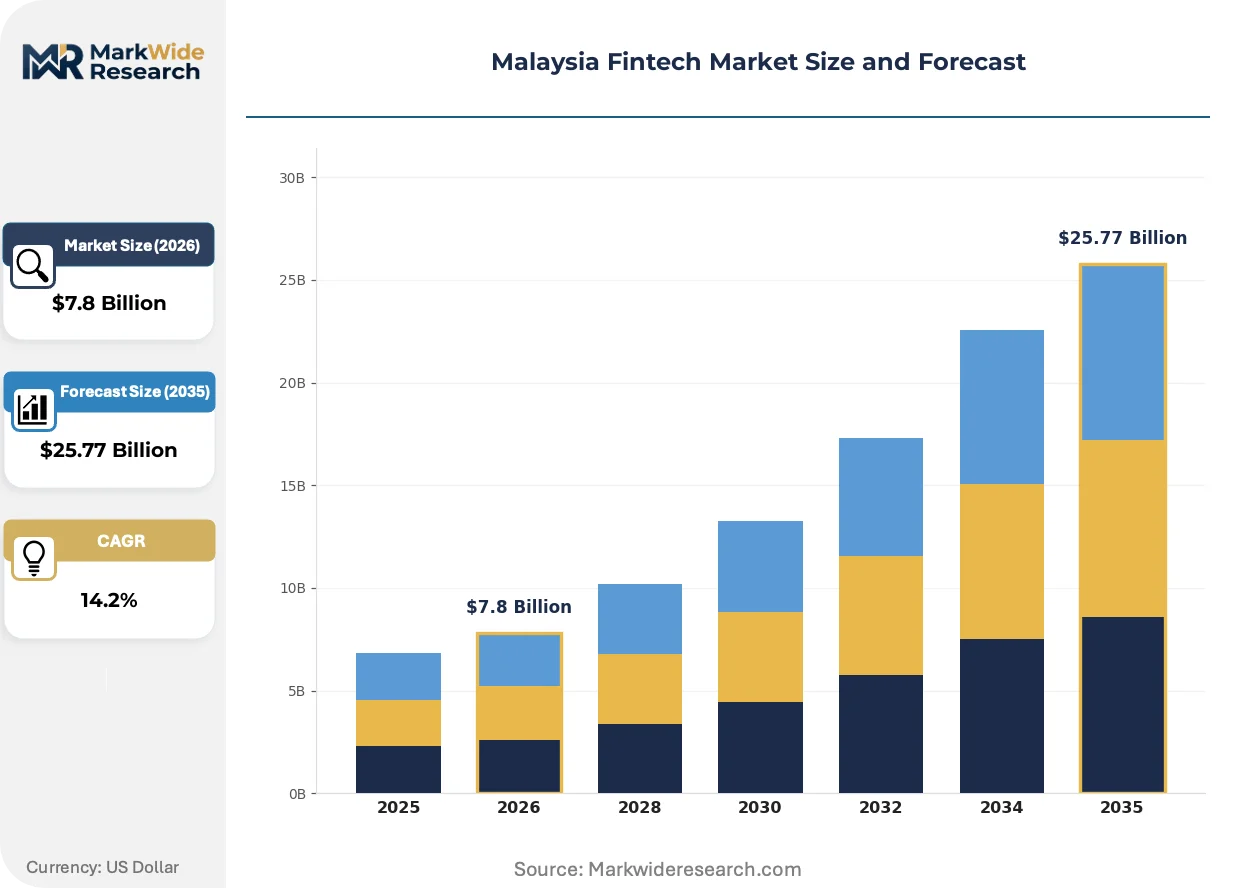
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $25.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Payments, Lending Platforms, Insurtech Solutions, Investment Management Customer Type: Consumers, Small Businesses, Enterprises, Financial Institutions Technology: Blockchain, AI, Mobile Apps, Cloud Computing End User: Retail, E-commerce, Travel, Telecom |
| Companies Covered | CIMB OCTO & Boost, MoneyMatch, Touch 'n Go Digital, Razer Merchant Services, iMoney, Maybank MAE, BigPay, Bjak, GrabPay Malaysia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Fintech Market Shifts & Advancements
Malaysian fintech infrastructure is fragmenting into composable service layers as regulatory clarity enables specialization, while demand-side behavior shifts from product ownership toward embedded financial utility.
API-first core banking platforms are modularizing the technology stack for digital lenders, enabling neobanks to license ledger, compliance, and card-issuing functions as discrete services rather than building captive infrastructure. Regional banks in Penang and Johor Bahru are adopting these modular cores to compress digital product launch cycles from years to quarters. This architectural shift is modularizing competitive moats away from balance sheet scale toward data network effects and user experience differentiation.
Bank Negara Malaysia's Payment Services Act amendments are tightening operational resilience requirements for cloud-hosted payment infrastructure, mandating localized data residency and failover capabilities. Licensed e-money issuers must now demonstrate geographic redundancy and penetration testing protocols that mirror banking sector standards. Digital wallet operators serving transit and retail corridors are responding by diversifying cloud provider relationships and investing in captive data center capacity.
Merchant acquisition is fragmenting across vertical-specific software platforms rather than concentrating through traditional ISO networks. Food delivery aggregators and logistics marketplaces in Kuala Lumpur are embedding payment acceptance as a native feature, displacing standalone point-of-sale terminal relationships. This channel disintermediation is most visible in food and beverage verticals where transaction data enables working capital advances that traditional acquirers cannot underwrite.
Malaysia Fintech Market Segmentation
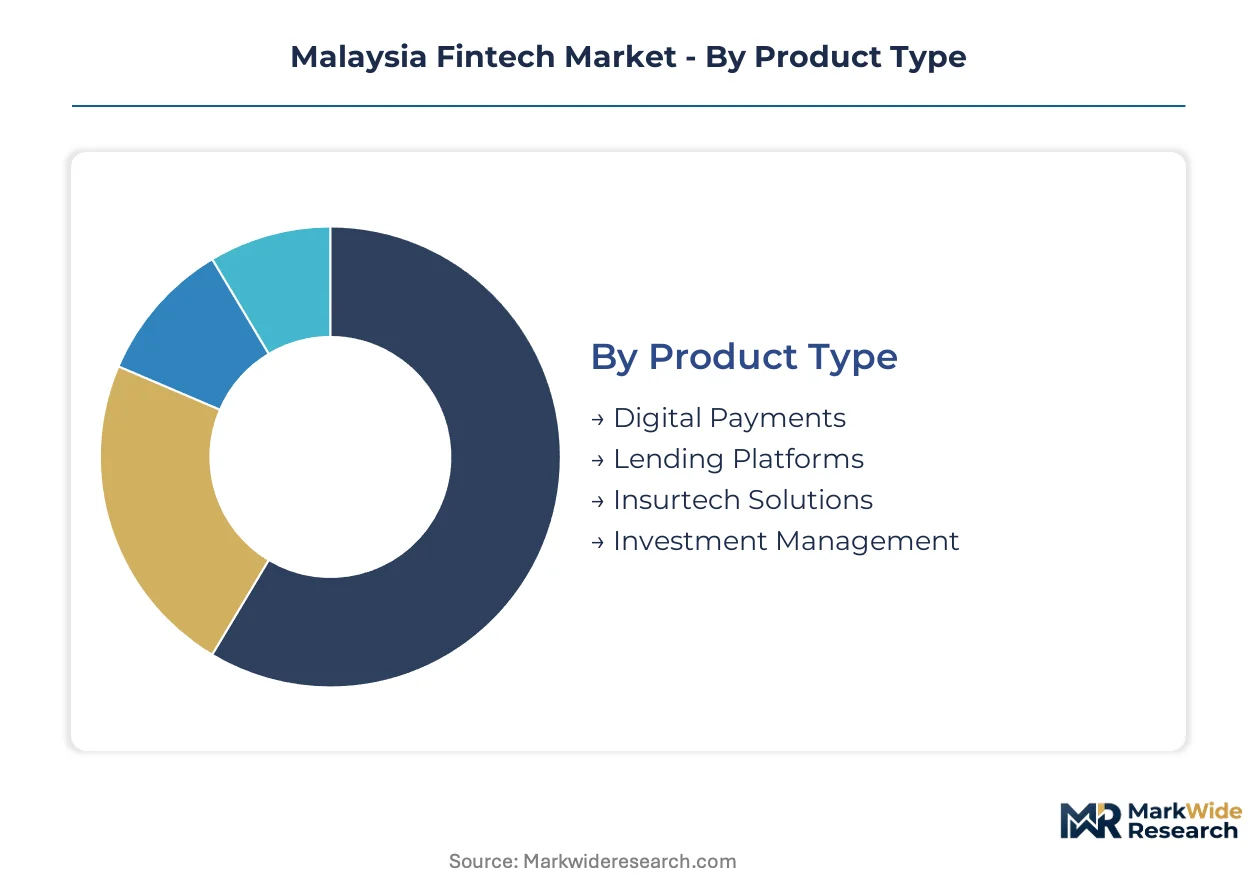
Malaysia's fintech ecosystem fragments along four intersecting dimensions that determine go-to-market economics and regulatory exposure. Product type dictates capital requirements under Bank Negara Malaysia's licensing tiers, while customer type shapes unit economics from high-frequency consumer transactions to enterprise software contracts. Technology selection drives infrastructure cost curves, and end-user verticals concentrate demand in corridors with distinct compliance obligations.
Product Type:
Digital Payments commands transaction volume through embedded utility, while Insurtech Solutions captures premium pricing through distribution innovation.
- Digital Payments:Mobile wallet infrastructure processing real-time transactions via API-integrated banking rails. Demand clusters in Kuala Lumpur transit corridors and Penang retail zones where transport-linked ecosystems sustain transaction density.
- Insurtech Solutions:Embedded distribution models deploying parametric micro-insurance at e-commerce checkout flows. Sabah and Sarawak rural segments generate pull for products bypassing traditional agent networks.
- Lending Platforms:AI-driven credit scoring for thin-file borrowers across consumer and SME categories, competing on risk-adjusted pricing where alternative data sources enable margin expansion.
- Investment Management:Robo-advisory and fractional securities access for digitally native retail investors, constrained by Securities Commission Malaysia licensing thresholds for discretionary portfolio management.
Today's leader: Digital Payments. Tomorrow's challenger: Insurtech Solutions.
Customer Type:
Consumer segments drive transaction velocity, while financial institutions anchor enterprise contract value through infrastructure procurement.
- Consumers:Individual users accessing payment, credit, and wealth services through mobile-first interfaces. Johor and Selangor urban corridors exhibit highest wallet penetration alongside underbanked demand in East Malaysia.
- Small Businesses:Merchants and sole proprietors requiring working capital facilities and payment acceptance. Documented credit gaps in manufacturing and logistics verticals create white space for alternative lenders.
- Enterprises:Corporate treasury departments procuring cross-border payment infrastructure and supply chain finance solutions. Procurement concentrates in multinational manufacturing operations with ASEAN currency exposure.
- Financial Institutions:Banks and insurers licensing technology layers for digital transformation. Regional banks in Penang and Johor Bahru adopt modular core systems to compress product launch cycles.
Consumer transaction density funds platform economics. Enterprise contracts deliver margin stability.
Technology:
Cloud Computing underpins cost-efficient scaling, while AI enables differentiation in credit and fraud decisions.
- Blockchain:Distributed ledger deployments for cross-border remittance settlement reducing correspondent banking delays in ASEAN corridors. Regulatory clarity on digital asset custody remains pending.
- AI:Machine learning models for credit scoring, fraud detection, and customer service automation. Talent scarcity constrains deployment velocity for Shariah-compliant product development.
- Mobile Apps:Native iOS and Android interfaces constituting primary customer touchpoints for wallet and lending services. Super-app integration patterns concentrate user engagement in food delivery and mobility verticals.
- Cloud Computing:Distributed infrastructure enabling geographic redundancy and elastic capacity for payment processing. Bank Negara Malaysia's operational resilience mandates now require localized data residency and failover capabilities.
Cloud infrastructure is the regulated utility layer. AI represents the competitive moat under construction.
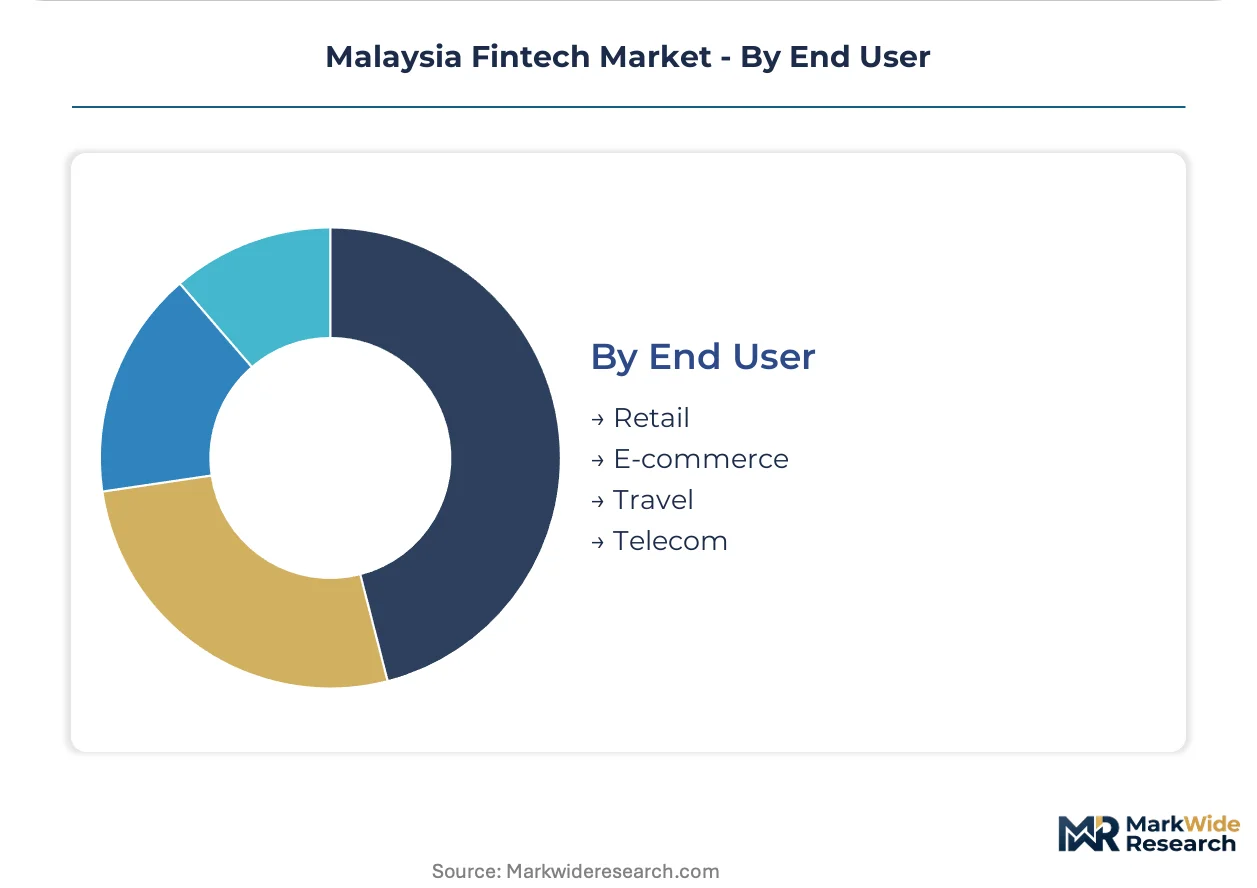
End User:
E-commerce channels drive embedded finance adoption, while retail physical networks sustain payment terminal density.
- Retail:Brick-and-mortar merchants adopting QR-code acceptance and inventory-linked working capital advances. Food and beverage verticals exhibit highest platform penetration through delivery aggregator integration.
- E-commerce:Online marketplaces embedding payment, credit, and insurance at checkout flows. Merchant acquisition fragments away from standalone ISO networks toward vertical-specific software platforms.
- Travel:Airlines and hospitality operators deploying multi-currency wallets and installment payment options. Cross-border transaction volumes correlate with ASEAN tourism corridor recovery.
- Telecom:Mobile network operators leveraging subscriber data for credit underwriting and digital wallet distribution. Prepaid customer bases in rural segments provide alternative data advantages over traditional credit bureaus.
E-commerce platforms are consolidating financial service distribution. Telecom operators retain latent data network effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's fintech ecosystem emerged from Kuala Lumpur's financial district consolidation in the 2010s, when Bank Negara Malaysia began licensing non-bank payment providers under nascent e-money frameworks. This regulatory foundation enabled the digital wallet proliferation now visible across Peninsular Malaysia and East Malaysian states.
Selangor
Petaling Jaya and Cyberjaya host the densest concentration of fintech engineering talent, with AI-driven credit scoring startups clustering near Monash University Malaysia. Bank Negara Malaysia's Payment Services Act enforcement creates compliance infrastructure that smaller operators license from specialized service providers. Shah Alam manufacturing corridors generate SME working capital demand that alternative lenders target with supply chain finance products.
Kuala Lumpur
The capital's transit-linked retail corridors sustain Touch 'n Go Digital's transaction density across LRT and MRT stations. Securities Commission Malaysia's regulatory sandbox permits equity crowdfunding platforms to test retail investor onboarding workflows. Bukit Bintang commercial zones exhibit highest QR-code merchant penetration, with food delivery aggregators embedding payment acceptance into vendor management systems.
Penang
George Town's semiconductor manufacturing ecosystem creates corporate treasury demand for cross-border payment infrastructure serving ASEAN currency exposure. Regional banks adopt modular core banking platforms to compress digital product launch cycles from years to quarters. Bayan Lepas industrial zones generate documented credit gaps among precision engineering subcontractors that AI-driven lenders target.
Johor
Iskandar Malaysia's logistics corridors concentrate e-commerce fulfillment demand that drives embedded insurance distribution at checkout flows. Small businesses in manufacturing verticals face unmet working capital facility demand, creating white space for alternative lending platforms. Singapore cross-border commuter flows sustain multi-currency wallet usage across the causeway economic zone.
Sabah and Sarawak
Rural consumer segments in East Malaysia lack traditional branch access, generating pull for mobile wallet solutions operating on basic smartphone connectivity. Telecom operators leverage prepaid subscriber data for credit underwriting advantages over traditional credit bureaus. Kuching and Kota Kinabalu urban centers exhibit accelerating merchant QR adoption through agent banking networks.
Malaysia Fintech Market Competitive Landscape
The competitive structure tilts toward platform-scale incumbents with transport-linked or super-app ecosystems. Three archetypes dominate: bank-backed digital wallets with captive deposit bases, independent fintechs specializing in cross-border corridors, and technology giants embedding financial services into non-financial marketplaces. M&A activity concentrates on acquiring e-money licenses and cloud infrastructure capabilities. Strategic partnerships between legacy banks and API-native technology providers reshape product distribution economics.
Among bank-affiliated operators, CIMB OCTO & Boost and Maybank MAE represent the institutional digitization archetype, leveraging existing customer relationships and balance sheet capacity to compress customer acquisition costs. Touch 'n Go Digital and GrabPay Malaysia occupy the ecosystem-integrated tier, anchoring transaction density through transit and mobility verticals respectively. MoneyMatch exemplifies the specialized corridor player, competing on forex transparency against incumbent banking channels in cross-border remittance. Razer Merchant Services sits within the gaming-adjacent payment acceptance segment, targeting youth demographic transaction flows.
| Leading Market Players |
|---|
| CIMB OCTO & Boost |
| MoneyMatch |
| Touch 'n Go Digital |
| Razer Merchant Services |
| iMoney |
| Maybank MAE |
| BigPay |
| Bjak |
| GrabPay Malaysia |
| Others |
Supply & Pricing Matrix
SME banking customers in Johor and Selangor manufacturing corridors concentrate procurement of payment infrastructure, anchoring a transaction-fee pricing model where per-unit charges scale with settlement volume and API integration complexity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with premium tiers commanding higher fees for real-time settlement and dedicated API support while economy tiers serve basic QR-code acceptance. Price differentiation rests on transaction volume commitments and cloud infrastructure redundancy certifications. Cost compression in standard tiers is intensifying because modular core banking platforms reduce captive infrastructure requirements. Micro-merchants in Sabah and Sarawak exhibit highest price sensitivity, while corporate treasury departments in Penang semiconductor clusters prioritize reliability over unit cost.
Supply Chain Analysis
Direct-to-bank channels handle hyperscale payment processor demand, while API-native platforms distribute through cloud service marketplaces and specialized fintech infrastructure vendors. Geographic supply concentration centers on Singapore for regional banking rails, Malaysia for cloud data residency compliance, and India for back-office engineering talent. Raw material dependencies include proprietary fraud detection algorithms, licensed e-money issuance frameworks, and Shariah-compliant product certification workflows. Single-source vulnerability in cloud provider relationships poses structural risk as Bank Negara Malaysia mandates geographic failover capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bank Negara Malaysia's Payment Services Act amendments function as a regulatory compounder, with operational resilience mandates driving demand for compliant infrastructure that smaller operators cannot self-provision.
For Market Incumbents: Anchor transaction density through super-app integration with food delivery and mobility verticals to defend against modular core banking platforms that compress product launch cycles. Invest in captive data center capacity across Kuala Lumpur and Penang to satisfy localized data residency requirements before license renewal deadlines.
For New Entrants and Emerging Players: Rural manufacturing subcontractors in Bayan Lepas and Shah Alam represent an underserved buyer archetype with documented credit gaps and limited traditional banking relationships. Target AI-driven supply chain finance products with alternative data underwriting that bypasses legacy credit bureau dependencies.
For Investors and Strategic Acquirers: Regional banks seeking digital transformation acceleration are the most active acquirer in this space, hunting for e-money licenses and cloud-native engineering teams. Long-term viability favors platforms with data network effects in underbanked East Malaysia corridors. Monitor open finance API standard announcements as the inflection indicator for which technology layers become regulated utilities versus competitive differentiators.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Core Banking Adoption | Regional banks in Penang compress digital product launch cycles from years to quarters. |
| E-Money License Acquisition | Strategic buyers secure regulatory authorization without multi-year application timelines. |
| Cloud Infrastructure Diversification | Licensed operators satisfy Bank Negara Malaysia failover mandates across multiple providers. |
| Embedded Insurance Distribution | E-commerce checkout flows reach uninsured rural segments without standalone policy administration. |
| Shariah-Compliant Product Development | Islamic fintech certification unlocks underserved Muslim consumer and SME banking demand. |
Research Methodology
Direct dialogue with digital payment executives, alternative lending platform founders, regulatory compliance officers at Bank Negara Malaysia, and cloud infrastructure procurement leads grounded the qualitative foundation. Secondary validation drew from Securities Commission Malaysia regulatory filings, Payment Services Act licensing records, Bursa Malaysia fintech sector disclosures, and ASEAN cross-border remittance flow data. Bottom-up transaction volume modeling and top-down GDP-correlation approaches were triangulated to ensure consistency.
Bottom-up segment modeling tracked digital payments, insurtech solutions, lending platforms, and investment management across consumer, SME, enterprise, and financial institution customer types. Deployment architecture, AI integration intensity, and end-user vertical adoption patterns were modeled as cross-cutting dimensions. CAGRs were derived from regression analysis against macroeconomic indicators and regulatory milestone timing. Forecast inputs included e-KYC adoption velocity, open finance API standard progression, and cloud infrastructure cost curves.
Inputs from regulatory filing databases and cloud provider capacity disclosures were available through the study window; gaps in private company transaction volume data introduce uncertainty bands around alternative lending segment estimates. Forecasts reflect assumptions regarding Bank Negara Malaysia licensing timeline adherence and cross-border remittance corridor stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Smart Finance Technologies Market
FinTech
Fintech-As-A-Service Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
UAE Fintech Market
FinTech
Africa AI in Fintech Market
FinTech
Micro-Investing Platform Market
FinTech
United Kingdom Fintech Market
FinTech
Financial Analytics Market
FinTech
Indonesia Financial Technology Services Market
FinTech
China Fintech Market
FinTech
Multichannel Digital Banking Integration Software Market
FinTech
Spain AI in Fintech Market
FinTech
Advanced Authentication in Financial Services Market
FinTech
Financial Management Software Market
FinTech
Europe Fintech Market
FinTech
Netherlands AI in Fintech Market