
 Generative AI in Fintech Market | 2026-2036
Generative AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Generative AI in Fintech Market Analytics
The fintech AI stack is restructuring around a sharp split between premium orchestration layers and commodity inference services. OpenAI leverages its foundation model leadership to anchor enterprise partnerships with major financial institutions. Microsoft Corporation sustains cloud-native integration advantages through Azure's vertical tooling for regulated workloads.
Generative AI in fintech denotes transformer-based and large language model systems trained on financial datasets to synthesize predictive outputs for credit scoring, fraud pattern generation, and conversational customer interfaces, typically operating with sub-100-millisecond latency requirements for real-time transaction decisions. Automated lending platforms dominate current revenue pools as banks deploy synthetic borrower profiles for stress testing, while natural language processing applications in customer support represent the fastest-expanding segment as institutions reduce call center dependency. Cloud-based deployment leads among payment processors seeking elastic compute for seasonal transaction spikes, whereas on-premises configurations persist at investment firms managing proprietary trading algorithms.
The SEC enforces disclosure standards for AI-driven investment advice, while the EU AI Act classifies credit scoring systems as high-risk applications requiring conformity assessments and human oversight protocols. The CFPB monitors fair lending outcomes when generative models substitute traditional underwriting, creating compliance cost differentials between regulated banks and unlicensed fintech entrants. Stakeholders must weigh model explainability investments against speed-to-market advantages as supervisory frameworks harden across jurisdictions.
Market Dynamics
The fintech AI stack is restructuring around a sharp split between premium orchestration layers and commodity inference services, with regulatory pressure from the EU AI Act forcing algorithmic accountability investments that reshape competitive economics.
Growth Catalysts
- EU AI Act compliance mandates:Credit scoring systems face high-risk classification requiring conformity assessments, driving demand for explainable model architectures and human-in-the-loop validation frameworks.
- Cloud-native deployment elasticity:Payment processors adopt generative AI for seasonal transaction spikes, leveraging distributed compute to maintain sub-100-millisecond latency during peak load periods.
- Synthetic borrower profiling:Retail banks deploy generative models for stress testing automated lending platforms, accelerating validation cycles for credit risk scenarios.
Market Restraints
- Foundation model supply concentration:Inference capabilities consolidate among a narrow set of cloud providers, creating dependency risks for financial institutions seeking model diversity.
- GPU compute cost volatility:Training and fine-tuning expenses for transformer architectures fluctuate with semiconductor supply constraints, compressing margins for mid-tier fintech entrants.
- Cross-border data localization:Divergent national requirements for financial data residency fragment model training pipelines and inflate compliance overhead.
Strategic Opportunities
- Conversational customer interface expansion:Natural language processing applications in support functions remain underpenetrated relative to lending automation, offering white space for call center displacement.
- On-premises edge deployment:Investment firms managing proprietary trading algorithms seek localized inference to protect alpha-generating model weights from cloud exposure.
- Regulatory arbitrage through explainability:Early investments in interpretable AI architectures create competitive moats as supervisory frameworks harden across jurisdictions.
Industry Challenges
- Model risk management talent scarcity:Financial institutions compete for quantitative researchers capable of validating generative outputs against fair lending standards enforced by the CFPB.
- Legacy core system integration friction:Mainframe banking infrastructure requires costly middleware development to interface with transformer-based decision engines.
- Algorithmic audit trail standardization:Absence of unified protocols for documenting generative model lineage complicates regulatory examination preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generative AI in Fintech Market |
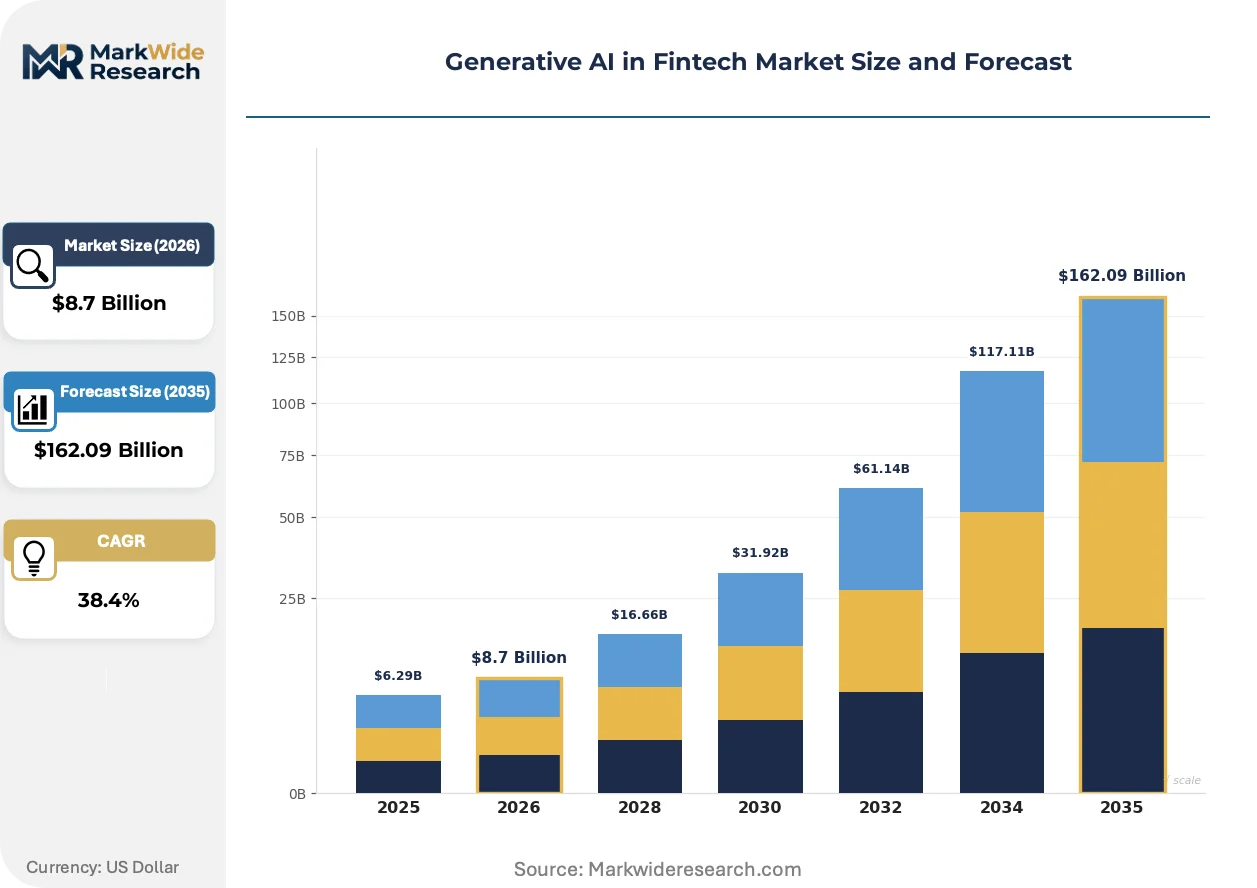
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $162.09 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Automated Lending, Fraud Detection, Risk Management, Customer Support Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Retail Banks, Investment Firms, Insurance Companies, Payment Processors Technology: Machine Learning, Natural Language Processing, Computer Vision, Blockchain |
| Companies Covered | OpenAI, Microsoft Corporation, Google LLC, IBM Corporation, Salesforce, MOSTLY AI, Genie AI Ltd., Upstart, Zest AI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generative AI in Fintech Market Evolving Landscape
Transformer architectures are electrifying real-time transaction decisions while regulatory frameworks harden algorithmic accountability requirements and procurement patterns shift toward outcome-based service contracts.
Retrieval-augmented generation is electrifying credit decision workflows by grounding large language model outputs in verified borrower documentation. Regional banks and credit unions adopt these architectures faster than money-center institutions due to lower legacy system entanglement. The structural consequence is compressing the competitive gap between tier-one and tier-two lenders in automated underwriting speed.
The EU AI Act's high-risk classification for credit scoring systems mandates conformity assessments and human oversight protocols before deployment. This industrial consequence forces model developers to invest in explainability layers that trace generative outputs to training data provenance. Investment firms operating cross-border face the steepest compliance cost differentials as they reconcile EU requirements with SEC disclosure standards for AI-driven advice.
Financial institutions are unbundling after-sales model maintenance from initial deployment contracts, shifting toward continuous validation subscriptions that align vendor compensation with sustained regulatory compliance. This procurement evolution displaces traditional perpetual licensing in favor of performance-guaranteed service agreements. The pattern is most visible among United States-based payment processors seeking elastic governance for seasonal transaction volumes.
Generative AI in Fintech Market Segmentation
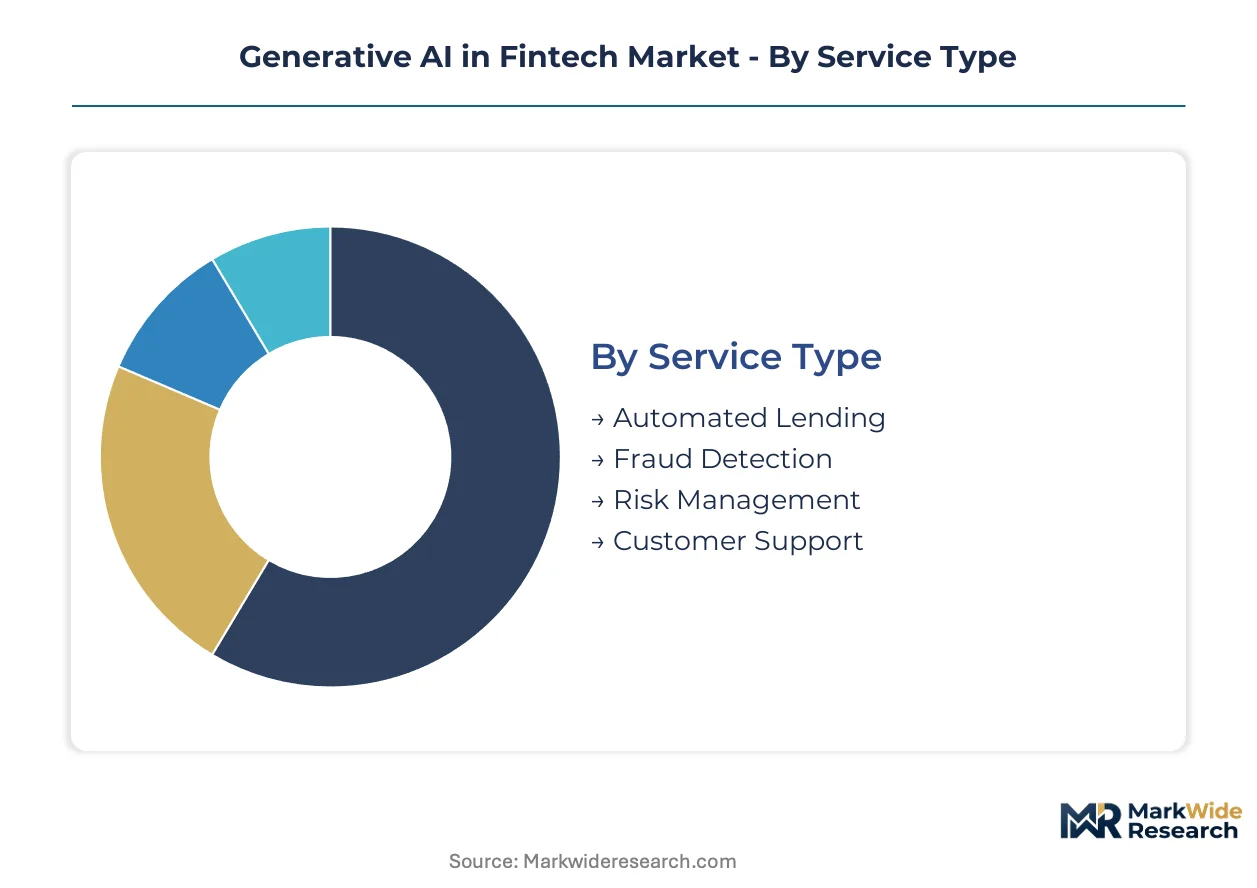
Generative AI deployment patterns in fintech diverge sharply by institutional risk tolerance and legacy infrastructure burden. Segmentation reveals how regulatory pressure and compute economics reshape procurement across service layers.
Service Type:
Buyer differentiation hinges on regulatory exposure depth and customer touchpoint volume.
- Automated Lending:Transformer models generate synthetic borrower profiles for stress testing and real-time credit decisions. Retail banks dominate procurement as they seek to compress underwriting cycles while satisfying CFPB fair lending scrutiny.
- Fraud Detection:Generative architectures synthesize adversarial transaction patterns to train detection systems against emerging attack vectors. Payment processors concentrate demand here, driven by seasonal transaction spikes requiring elastic inference capacity.
- Risk Management:Portfolio-level scenario modeling using large language models for regulatory reporting automation.
- Customer Support:Conversational interfaces displace call center operations through retrieval-augmented response generation.
Volume sits with Automated Lending; growth tilts toward Customer Support.
Deployment:
Cost tier stratification separates institutions with captive infrastructure from those prioritizing capital efficiency.
- Cloud-Based:Distributed compute architectures enable elastic scaling for transaction processing peaks. Investment firms in the United States accelerate adoption here, leveraging Azure's vertical tooling for SEC-regulated workloads.
- On-Premises:Localized inference protects proprietary model weights and satisfies data residency mandates. Tier-one banks maintain these configurations for core lending algorithms despite higher TCO.
- Hybrid:Split architectures route sensitive operations on-premises while offloading batch inference to cloud.
- SaaS:Outcome-based service contracts align vendor compensation with sustained compliance performance.
Cloud-Based captures current procurement volume; Hybrid deployments are climbing the fastest as institutions seek regulatory arbitrage.
End User:
Application maturity varies by sector-specific regulatory density and legacy system entanglement.
- Retail Banks:Automated lending platforms dominate internal investment, with synthetic profiling accelerating validation cycles for credit risk scenarios.
- Investment Firms:Proprietary trading algorithms demand sub-100-millisecond latency, driving edge deployment for alpha protection.
- Insurance Companies:Claims processing automation and actuarial model enhancement represent emerging use cases.
- Payment Processors:Seasonal transaction spikes create concentrated demand for elastic generative fraud detection.
Retail Banks anchor current spending; Payment Processors show the steepest expansion trajectory.
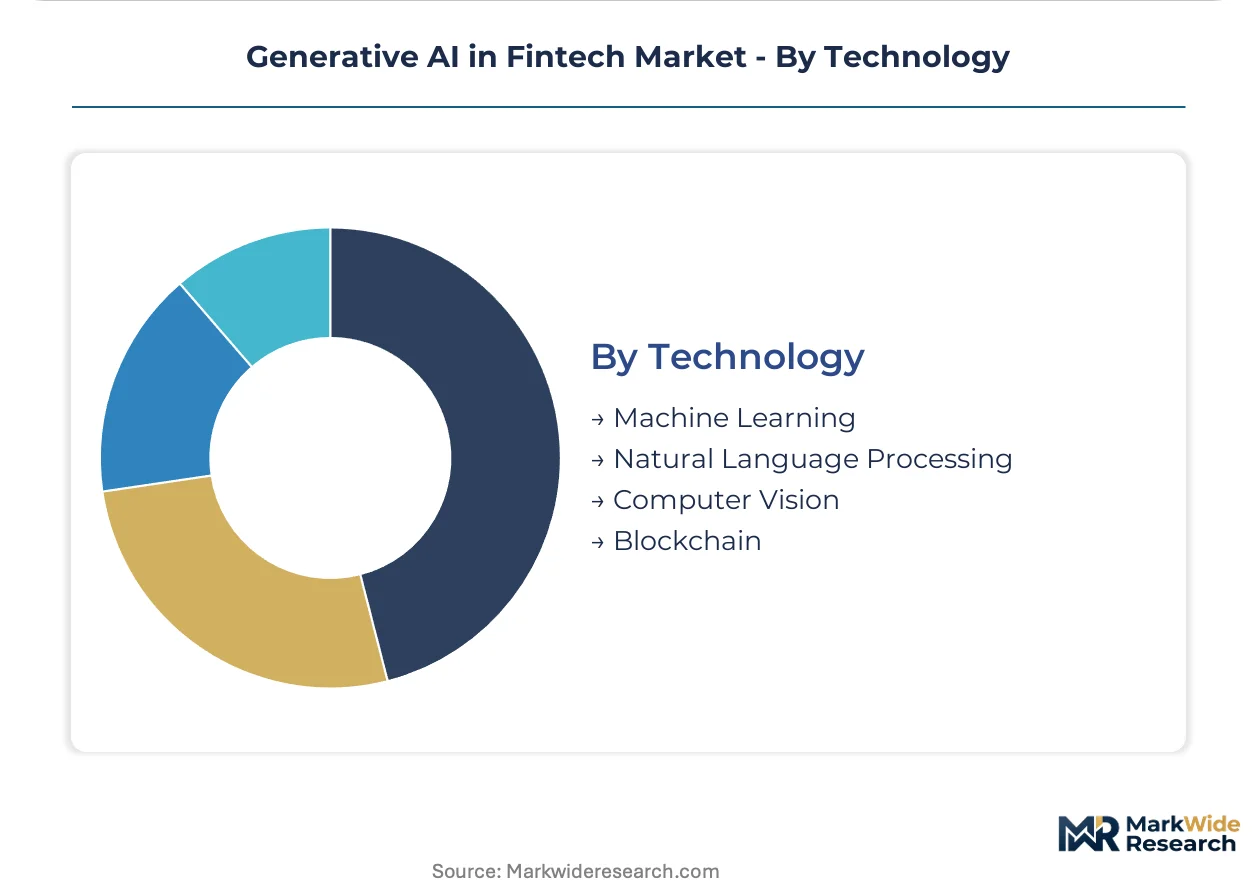
Technology:
Supply concentration in foundation model layers forces architecture decisions around explainability versus performance tradeoffs.
- Natural Language Processing:Retrieval-augmented generation grounds LLM outputs in verified documentation for credit decisions. Regional banks adopt faster than money-center institutions due to lower legacy entanglement.
- Machine Learning:Traditional predictive models persist in risk scoring where regulatory interpretability requirements dominate.
- Computer Vision:Document extraction and KYC automation drive niche adoption in onboarding workflows.
- Blockchain:Decentralized model validation and audit trail immutability attract consortium experiments.
Machine Learning maintains installed base dominance; Natural Language Processing gains share fastest as conversational interfaces mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City's financial district concentrates generative AI deployment for real-time trading decisions, while London's fintech corridor drives regulatory technology innovation. Cloud infrastructure investments in Singapore and Frankfurt anchor distributed compute architectures for cross-border transaction processing.
United States
Investment firms in Manhattan and Chicago accelerate cloud-native adoption for sub-100-millisecond latency requirements. The SEC enforces disclosure standards for AI-driven investment advice, creating compliance cost premiums for registered advisors. Silicon Valley clusters dominate foundation model development partnerships with retail banks.
United Kingdom
The City of London's institutional investors deploy generative architectures for portfolio scenario modeling and regulatory reporting automation. The Financial Conduct Authority monitors algorithmic trading systems under MiFID II alignment protocols. Edinburgh's banking sector leads synthetic borrower profiling for stress testing automation.
Germany
Frankfurt's commercial banks invest heavily in explainable model architectures to satisfy EU AI Act conformity assessments. BaFin mandates human oversight protocols for credit scoring systems classified as high-risk applications. Munich's insurance clusters pioneer claims processing automation using retrieval-augmented generation.
Singapore
Payment processors headquartered in the city-state leverage elastic cloud compute for seasonal transaction spikes across Southeast Asian markets. The Monetary Authority of Singapore publishes AI governance frameworks for financial services. The Marina Bay financial district anchors regional fraud detection model training pipelines.
Japan
Tokyo's megabanks deploy on-premises inference for proprietary trading algorithms requiring alpha protection from cloud exposure. METI promotes trustworthy AI guidelines for financial sector adoption. Osaka's regional banks adopt conversational interfaces faster than money-center institutions due to lower legacy system entanglement.
Generative AI in Fintech Market Competitive Landscape
Capital-heavy cloud infrastructure providers compete with asset-light model orchestration specialists for fintech enterprise partnerships. The market structure concentrates around three strategic tiers: hyperscale platform operators, vertical fintech AI specialists, and open-source foundation model distributors. Dominant competitive moves include strategic cloud partnerships with regulated financial institutions and targeted acquisitions of explainability technology layers.
Within the hyperscale platform tier, Microsoft Corporation and Google LLC anchor enterprise cloud-native integration advantages for SEC-regulated workloads. OpenAI exemplifies foundation model leadership through enterprise partnership structures with major financial institutions. IBM Corporation occupies a position bridging legacy system integration with transformer-based decision engines for mainframe banking infrastructure.
| Leading Market Players |
|---|
| OpenAI |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Salesforce |
| MOSTLY AI |
| Genie AI Ltd. |
| Upstart |
| Zest AI |
| Others |
Value Network & Pricing Analysis
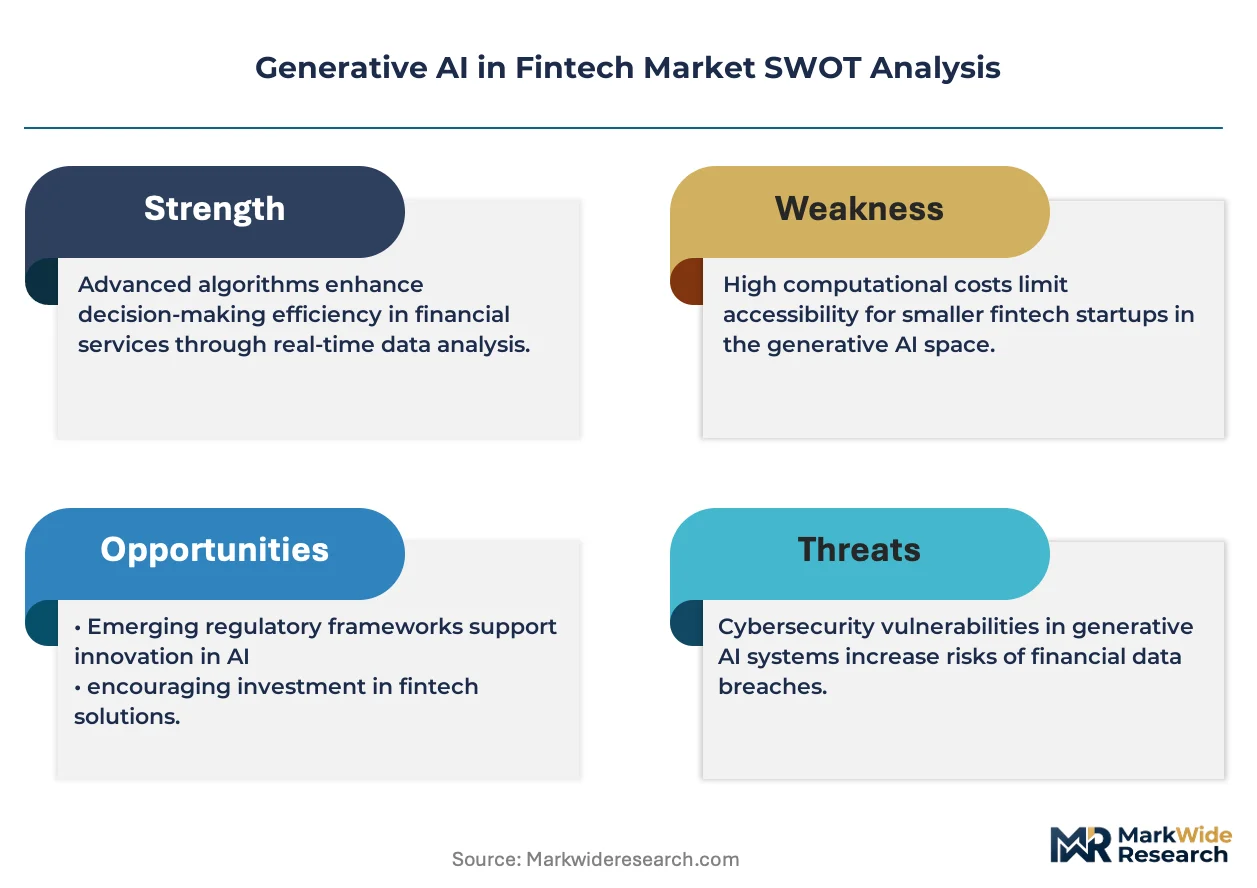
EU AI Act conformity assessment mandates for high-risk credit scoring systems are compressing procurement timelines for explainable model architectures, forcing cloud providers to pre-certify inference stacks and tier-one banks to absorb premium pricing for compliant orchestration layers.
Pricing Analysis
Outcome-guaranteed service contracts now anchor enterprise procurement, with vendor compensation tied to sustained regulatory compliance performance rather than perpetual licensing. Pricing stratifies across premium explainability tiers, standard cloud-native configurations, and economy SaaS offerings differentiated by human-in-the-loop validation depth. Cost compression in mid-tier inference services is intensifying because GPU compute volatility and foundation model supply concentration squeeze margins for non-hyperscale entrants. Payment processors show highest price sensitivity due to seasonal volume unpredictability, while investment firms accept premium tiers for sub-100-millisecond latency guarantees.
Supply Chain Analysis
EU AI Act certification requirements and SEC disclosure standards are gating vendor participation, filtering cloud providers to those with documented conformity assessment capabilities and vertical tooling for regulated workloads. Compute infrastructure concentrates in the United States, Taiwan, and Ireland, with NVIDIA GPU supply and custom ASIC development anchoring capacity expansion. The stack draws from specialized semiconductor fabrication, high-bandwidth memory modules, and low-latency networking hardware. Single-source vulnerability in foundation model training clusters poses structural risk as financial institutions seek model diversity. Distribution runs through direct enterprise sales teams and strategic cloud partnership channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU compute scarcity and foundation model supply concentration are propping pricing power for hyperscale cloud operators, creating a supply-constrained market structure that favors incumbents with captive infrastructure.
For Market Incumbents: Deepen vertical integration into custom silicon and edge deployment hardware to defend margins against commodity inference erosion. Secure long-term GPU supply agreements with NVIDIA and TSMC to lock in capacity before mid-tier entrants scale. Threat of regulatory arbitrage from explainability specialists demands pre-emptive investment in interpretable AI architectures. For New Entrants and Emerging Players: Begin with regional bank and credit union segments where legacy system entanglement is lowest and procurement cycles are shortest. Conversational customer support interfaces remain underpenetrated relative to automated lending, offering white space for call center displacement. Go-to-market angle should emphasize rapid deployment timelines and outcome-based pricing without heavy upfront integration costs. For Investors and Strategic Acquirers: The window for entry favors model orchestration specialists with explainability technology layers and established regulatory compliance track records. Long-term viability hinges on differentiation from hyperscale commodity inference services. Signal to watch is CFPB enforcement intensity against fair lending outcomes in generative underwriting systems.| Strategic Initiative | Industry Significance |
|---|---|
| Explainability Technology Acquisition | Builds defensible moats as EU AI Act and SEC disclosure standards harden across jurisdictions. |
| Custom Silicon Development | Reduces dependency on NVIDIA GPU supply volatility and compresses inference latency for trading applications. |
| Regulatory Technology Partnership | Accelerates conformity assessment completion for high-risk credit scoring deployments under EU AI Act timelines. |
| Edge Deployment Infrastructure | Captures investment firm demand for alpha-protecting on-premises inference away from cloud exposure. |
| Synthetic Data Platform Launch | Enables retail bank stress testing automation while reducing reliance on sensitive borrower record access. |
Research Methodology
Multi-period observation of foundation model deployment timelines, regulatory enforcement patterns, and cloud infrastructure capex anchored the trend analysis, supplemented by interviews with chief technology officers at retail banks, AI procurement leads at investment firms, compliance officers navigating EU AI Act implementation, and cloud platform engineering directors. Secondary validation drew from SEC disclosure filings for AI-driven advisory services, EU AI Act conformity assessment documentation, hyperscaler earnings call transcripts, and CFPB fair lending examination reports. Bottom-up segmentation modeling triangulated against top-down market sizing from cloud infrastructure spend allocation.
Input-output matrices mapped deployment model adoption curves against regulatory compliance cost trajectories across the projection horizon, with segmentation dimensions covering service type, deployment architecture, end-user sector, and technology layer. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity constraints. Industry-specific forecast inputs included GPU supply pipeline visibility and foundation model release cadence from major providers.
Underlying measurement precision varies by segment; cloud-based deployment volumes carry tighter precision than on-premises configurations where vendor reporting is fragmented. Forecasts reflect assumptions around regulatory enforcement intensity and semiconductor supply normalization. A model refresh is warranted upon material change in EU AI Act implementation timelines or CFPB fair lending scrutiny escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Latin America Fintech Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
Saudi Arabia Fintech Market
FinTech
Financial Forecasting Software Market
FinTech
Australia Fintech Market
FinTech
Fintech Credit Management Blockchain Market
FinTech
Financial Analytics Market
FinTech
France BNPL Market
FinTech
Financial Technology Fintech Market
FinTech
Fintech Cloud Market
FinTech
Netherlands AI in Fintech Market
FinTech
Global Saas Spend Management Software Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Global Fintech Market
FinTech
Advanced Authentication in Financial Services Market
FinTech
Fintech Lending Market