
 France AI in Fintech Market | 2026-2036
France AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
France AI in Fintech Market Insights
France is reconfiguring its financial technology infrastructure through sovereign cloud investments and AI research tax credits. Finastra leverages its open banking platform to anchor institutional clients across French-speaking markets. Shift Technology specializes in claims automation and fraud detection for European insurers. Qonto dominates the SME banking segment with embedded AI-driven cash flow forecasting tools.
France AI in Fintech comprises machine learning algorithms, natural language processing engines, and predictive analytics systems deployed to automate credit decisions, detect anomalous transactions, and personalize financial services at scale. These technologies process structured and unstructured data streams in real time, enabling sub-second risk scoring and regulatory reporting automation. Machine learning and predictive analytics command the deepest R&D investment pools, while natural language processing is gaining traction in customer service automation as French-language model accuracy improves. Fraud detection applications attract the most procurement spend among banking institutions, whereas credit scoring solutions are expanding fastest among payment processors seeking real-time merchant underwriting capabilities.
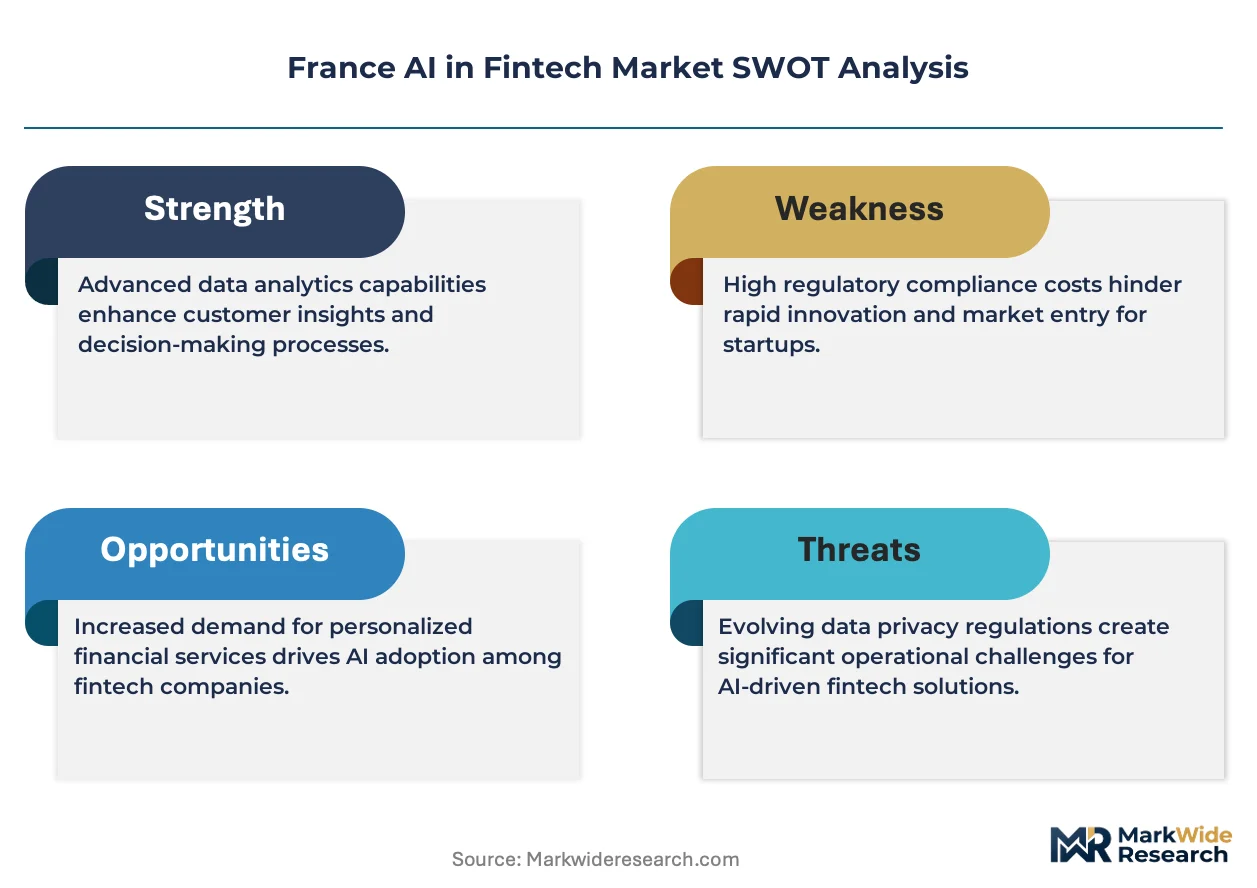
ANSM and CNIL enforce data protection and algorithmic transparency standards that shape product development timelines for fintech AI deployments. The EU AI Act's risk classification framework directly determines which automated credit and insurance pricing systems require human oversight, human-in-the-loop documentation, and conformity assessments before market entry. French banking regulators under the ACPR mandate explainability thresholds for high-stakes lending algorithms. Stakeholders must monitor how rapidly evolving EU-level AI governance intersects with national financial conduct rules to avoid compliance fragmentation across European operating territories.
Market Dynamics
The France AI in Fintech market is reconfiguring around algorithmic sovereignty mandates and the EU AI Act's risk-tiered compliance architecture, forcing institutions to rebuild core infrastructure around explainability-by-design principles rather than retrofitting transparency layers onto legacy black-box systems.
Growth Catalysts
- EU AI Act High-Risk System Mandates:Automated credit scoring and insurance pricing algorithms now require conformity assessments and human oversight protocols, creating procurement urgency for compliant AI infrastructure across French retail banks and mutual insurers.
- Île-de-France Fintech Cluster Density:Paris hosts Europe's third-largest fintech workforce concentration, enabling rapid talent circulation between incumbent institutions, neobanks, and specialized AI vendors developing French-language NLP models.
- Open Banking API Standardization:PSD2-mandated data sharing protocols generate real-time transaction streams that feed machine learning risk engines, expanding addressable data volumes for predictive analytics deployments.
Market Restraints
- GDPR-CNIL Algorithmic Audit Requirements:Data protection impact assessments for automated decision systems extend product development timelines by 8-14 months and impose documentation burdens that favor well-capitalized incumbents over emerging vendors.
- Cloud Infrastructure Concentration:French sovereign cloud alternatives to hyperscale providers remain immature, forcing institutions into complex multi-cloud architectures that fragment AI training pipelines and inflate operational complexity.
- French-Language Model Accuracy Gaps:NLP systems for customer service automation underperform against English-language benchmarks due to smaller training corpora, limiting deployment confidence in high-touch retail banking applications.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur SME Banking Gap:Qonto's algorithmic cash flow tools have limited penetration outside Parisian economic basins, leaving underserved merchant segments in Marseille and Nice corridors for specialized underwriting platforms.
- ACPR Explainability Threshold Arbitrage:Institutions that pre-build human-in-the-loop documentation and model interpretability frameworks can accelerate market entry as competitors struggle with retroactive compliance engineering.
- Embedded Insurance Convergence:Telematics data streams from connected devices and e-commerce transaction patterns enable real-time parametric coverage pricing, opening new product categories beyond traditional annual policy structures.
Industry Challenges
- MLOps Talent Scarcity:French technical universities produce insufficient machine learning operations specialists capable of deploying production-grade fraud detection systems at institutional scale, forcing reliance on expensive contract engineering.
- Legacy Core Banking Integration:Mainframe-dependent mutual banks face architectural friction when embedding real-time AI scoring into batch-processed loan origination workflows, requiring expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France AI in Fintech Market |
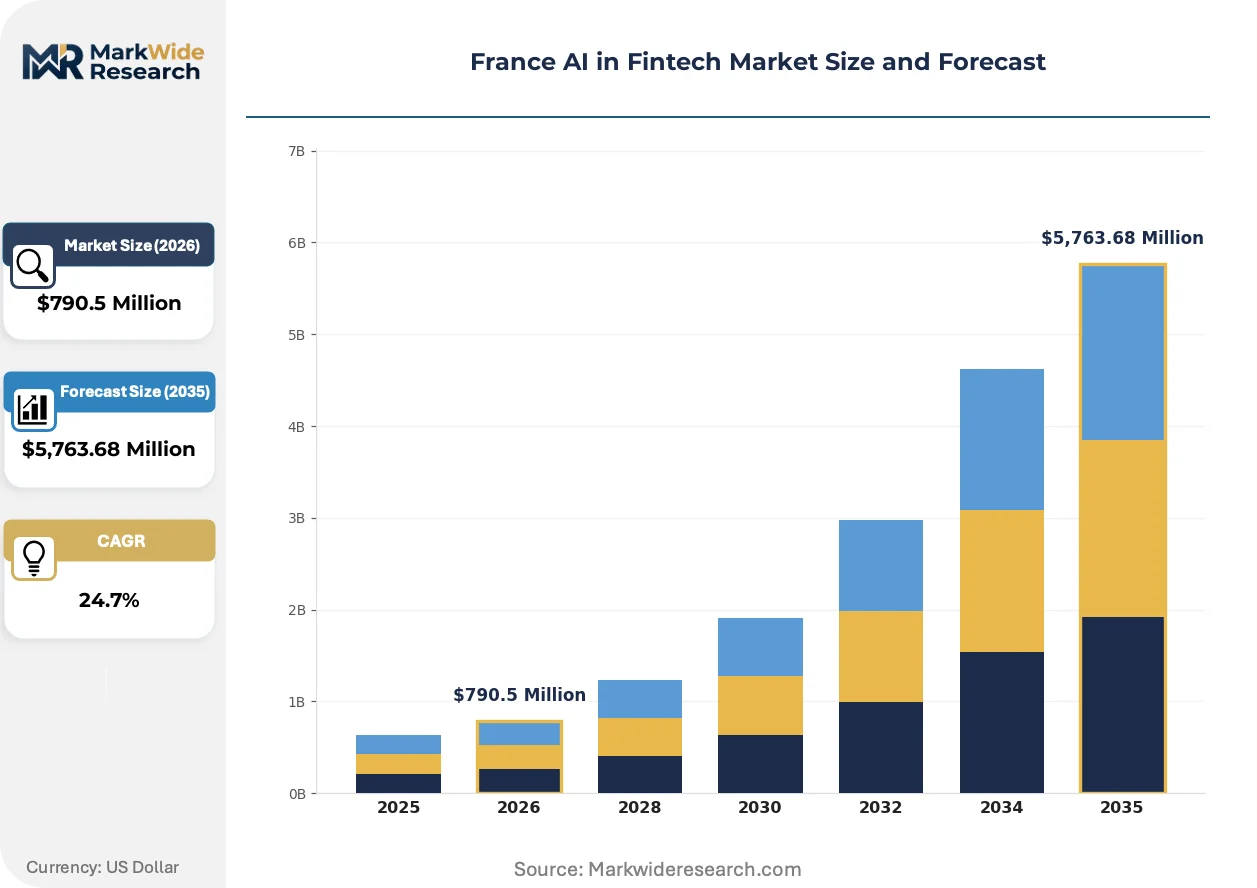
| Market Size in 2026 | $790.5 Million |
| Market Size in 2035 | $5,763.68 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Predictive Analytics Application: Fraud Detection, Credit Scoring, Risk Management, Customer Service Automation End User: Banking Institutions, Payment Processors, Investment Firms, Insurance Companies Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Platforms |
| Companies Covered | Finastra, Shift Technology, Qonto, Lydia, Workiva, BNP Paribas, Younited Credit, October, Adyen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France AI in Fintech Market Trends and Innovations
French financial institutions are abandoning rule-based fraud detection for neural architectures while regulators simultaneously tighten algorithmic accountability requirements, creating a dual pressure environment where technical capability and compliance infrastructure must advance in lockstep.
Federated learning architectures are digitizing collaborative model training across competing institutions without centralizing sensitive transaction data. Crédit Mutuel and BPCE Group pilot cross-bank anomaly detection networks that preserve GDPR-mandated data locality while pooling pattern recognition capacity. This approach is digitizing fraud detection accuracy improvements that single-institution datasets cannot achieve independently.
The EU AI Act's risk classification framework is compressing deployment timelines for high-stakes credit algorithms by mandating pre-market conformity assessments. French banking supervisors under ACPR interpret these requirements through existing financial conduct lenses, creating hybrid compliance obligations that differ from German or Dutch implementations. Retail lending divisions accelerate procurement of explainable AI platforms to secure authorization windows before stricter enforcement phases activate.
SME banking clients are consolidating vendor relationships around embedded financial management tools that consolidate accounts payable, receivable forecasting, and credit access in unified interfaces. Neobanks capture merchant cash flow data through API connections to accounting software, displacing traditional relationship-based underwriting with real-time behavioral scoring. This pattern concentrates most visibly among Parisian digital-native merchants and rapidly expands into Lyon and Bordeaux metropolitan corridors.
France AI in Fintech Market Segmentation
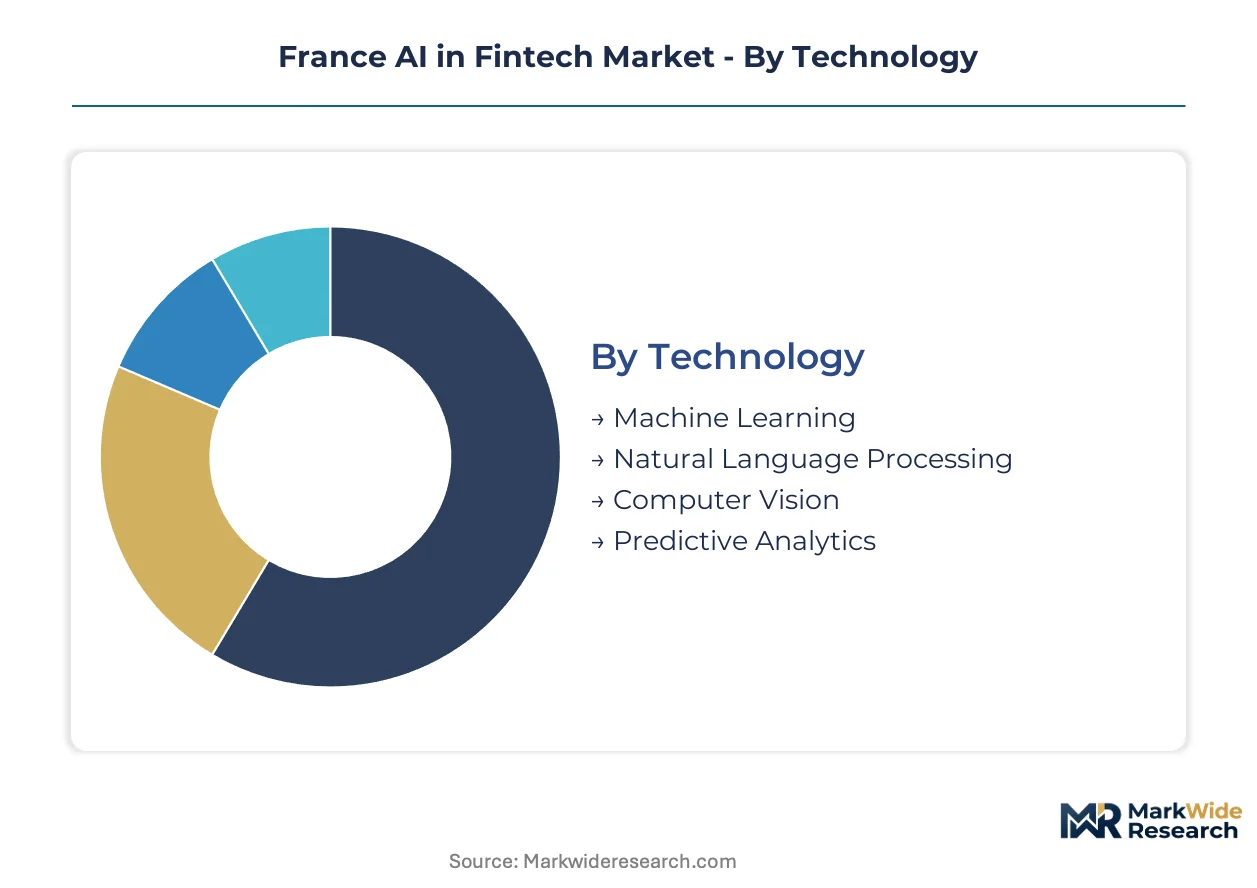
Segmentation reveals how French fintech AI procurement concentrates around explainable credit algorithms and real-time fraud detection systems. Deployment choices increasingly hinge on CNIL data localization requirements and ACPR oversight mandates for high-risk automated decisions.
Technology:
Mature machine learning stacks dominate production environments while natural language processing and computer vision emerge from R&D pipelines into commercial deployment.
- Machine Learning:Supervised and unsupervised learning algorithms power credit scoring engines and transaction anomaly detection across French retail banking. Demand concentrates at Société Générale and BNP Paribas as they rebuild core risk infrastructure for EU AI Act compliance.
- Natural Language Processing:French-language transformers and sentiment analysis models automate customer service interactions and contract parsing. Accuracy gaps against English benchmarks limit deployment confidence in high-touch retail applications across Crédit Mutuel's branch network.
- Computer Vision:Document verification and identity authentication systems process KYC documentation for digital onboarding flows.
- Predictive Analytics:Time-series forecasting engines project cash flow patterns and default probabilities for SME lending portfolios.
Machine Learning retains volume leadership; Natural Language Processing holds the steepest expansion curve as French-language model accuracy improves.
Application:
Application demand stratifies between regulatory-mandated fraud systems and growth-oriented credit automation tools.
- Fraud Detection:Real-time transaction monitoring systems deploy neural architectures to flag anomalous payment patterns across SEPA instant transfer networks. French mutual insurers prioritize procurement following PSD2-mandated liability shifts for unauthorized transactions.
- Credit Scoring:Alternative data models incorporate cash flow telemetry from accounting software APIs to underwrite merchant credit lines. Neobanks in Paris and Lyon metropolitan corridors drive fastest adoption for real-time lending decisions.
- Risk Management:Portfolio stress testing and market risk engines automate regulatory capital calculations for investment divisions.
- Customer Service Automation:Conversational AI handles routine banking queries while escalating complex complaints to human agents under ACPR-mandated oversight protocols.
Fraud Detection commands the largest procurement budgets; Credit Scoring gains share fastest as embedded finance expands merchant underwriting.
End User:
End-user investment intensity correlates with regulatory exposure to high-risk algorithmic decisions under EU AI Act classification.
- Banking Institutions:Retail and commercial banks deploy explainable AI for mortgage underwriting and SME lending to satisfy ACPR interpretability thresholds. Crédit Agricole and BPCE Group lead capital allocation toward compliant infrastructure rebuilds.
- Payment Processors:Real-time merchant onboarding and transaction monitoring systems require sub-second risk scoring at scale. French payment service providers face PSD2 strong customer authentication mandates that accelerate AI procurement timelines.
- Investment Firms:Algorithmic trading and portfolio optimization tools process market data streams for asset management divisions.
- Insurance Companies:Claims automation and parametric pricing engines leverage telematics data for usage-based coverage products.
Banking Institutions absorb the deepest investment pools; Payment Processors climb the fastest as instant payment volumes expand.
Deployment:
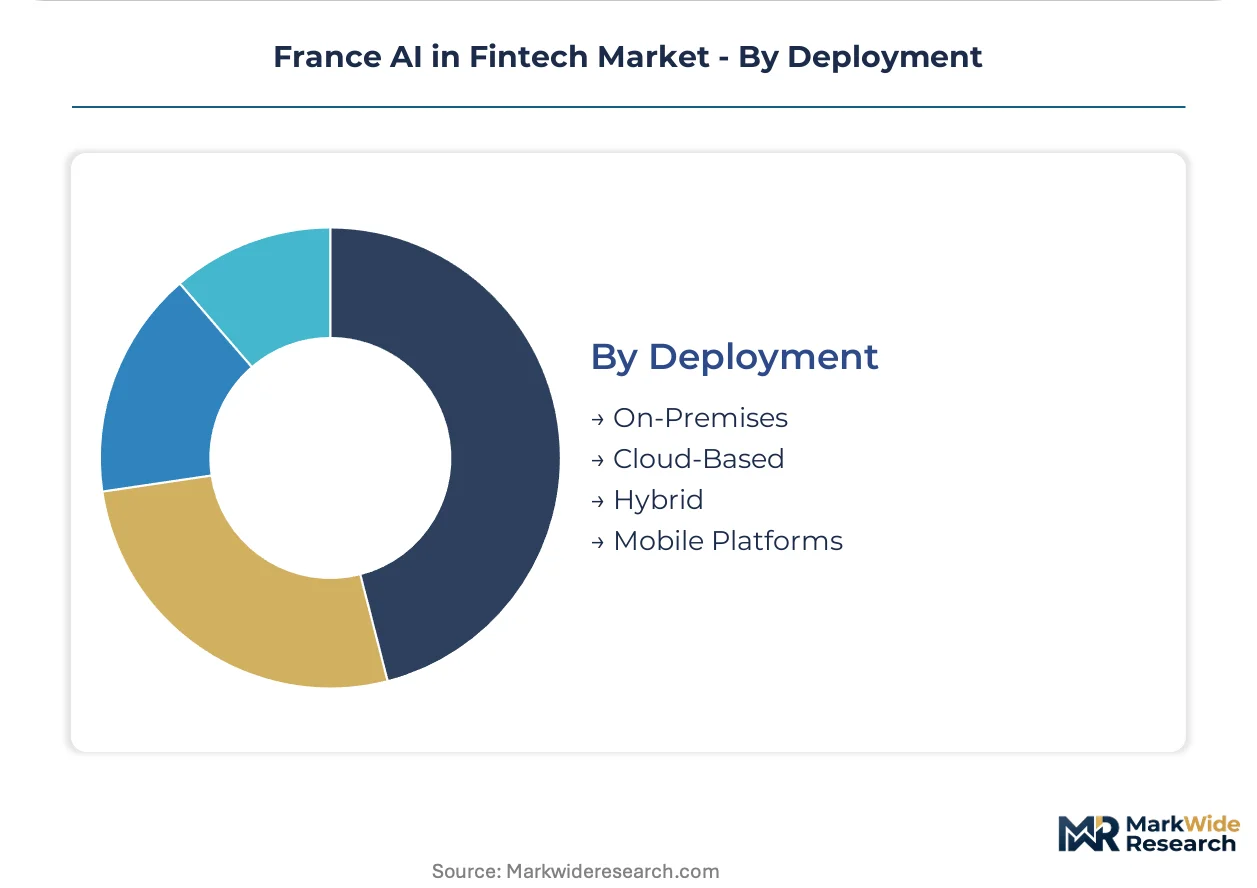
Deployment architecture choices reflect tension between CNIL data sovereignty preferences and computational scalability requirements.
- Cloud-Based:Scalable training infrastructure and API-accessible model serving support rapid experimentation and elastic demand patterns. French sovereign cloud alternatives remain immature, forcing hybrid architectures that fragment MLOps pipelines.
- On-Premises:Air-gapped systems host sensitive credit algorithms for institutions prioritizing data control over operational flexibility. ACPR documentation requirements favor on-premise deployments for high-stakes lending decisions requiring audit trail preservation.
- Hybrid:Split architectures train models in cloud environments while deploying inference engines on-premise to satisfy data localization mandates.
- Mobile Platforms:Edge-deployed models enable real-time fraud alerts and biometric authentication on consumer devices.
Cloud-Based deployments dominate new procurement; Hybrid architectures expand most quickly as institutions navigate sovereignty constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France concentrates algorithmic underwriting deployments while Provence-Alpes-Côte d'Azur and Auvergne-Rhône-Alpes diverge toward SME cash flow automation and insurance claims processing respectively.
Île-de-France
Paris hosts Europe's densest fintech workforce concentration, driving procurement of explainable credit scoring systems for retail banking. ACPR mandates human-in-the-loop documentation for high-risk lending algorithms, compressing deployment timelines. The Paris-Saclay research cluster feeds French-language NLP model development into neobank customer service platforms.
Auvergne-Rhône-Alpes
Lyon anchors algorithmic trading infrastructure and portfolio stress testing engines for regional banking divisions. EU AI Act conformity assessment requirements shape procurement decisions for automated risk management systems. The Lyon metropolitan corridor expands embedded finance penetration among digital-native merchants through API-connected cash flow telemetry.
Provence-Alpes-Côte d'Azur
Marseille and Nice corridors present underserved merchant segments for specialized SME underwriting platforms. CNIL data localization preferences favor hybrid cloud architectures that fragment MLOps pipelines across regional data centers. The Mediterranean port cluster drives demand for real-time trade finance risk scoring linked to supply chain documentation.
Hauts-de-France
Lille's proximity to Belgian and Dutch financial centers positions the region for cross-border payment processing AI deployments. GDPR-mandated data protection impact assessments extend product development timelines for automated decision systems. The EuraTechnologies startup cluster incubates fraud detection vendors serving SEPA instant transfer networks.
France AI in Fintech Market Competitive Landscape
Capability concentration sits with specialized AI vendors developing French-language models and explainable credit algorithms; scale advantage sits with incumbent banking groups deploying sovereign cloud infrastructure and open banking platforms. The market structures around three archetypes: legacy core banking integrators, neobank-native AI developers, and cross-border payment processors. Dominant competitive moves include M&A targeting explainability-as-a-service platforms and strategic partnerships linking accounting software APIs to real-time underwriting engines.
Among France-based specialists, Finastra anchors institutional client relationships across French-speaking markets through open banking infrastructure. Shift Technology occupies a position within the insurance-focused tier, exemplifying claims automation archetypes. Qonto represents the neobank-native segment, embedding cash flow forecasting tools that displace traditional relationship-based underwriting. These three entities collectively illustrate how French fintech AI competition stratifies between infrastructure-scale incumbents and application-layer disruptors.
| Leading Market Players |
|---|
| Finastra |
| Shift Technology |
| Qonto |
| Lydia |
| Workiva |
| BNP Paribas |
| Younited Credit |
| October |
| Adyen |
| Others |
Pricing and Supply Chain Analysis
Channel Tunnel freight corridors connecting Île-de-France data centers to London and Frankfurt financial hubs concentrate AI compute logistics costs, compressing margins for explainable credit algorithm vendors while amplifying price spreads between sovereign cloud deployments and hyperscale alternatives.
Pricing Analysis
Paris-based deployments command 15-25% premiums over Lyon or Marseille equivalents due to ACPR proximity and talent density. SaaS-tiered subscription models dominate explainable AI procurement, with pricing stratifying across premium, standard, and economy tiers based on model interpretability depth and human-in-the-loop documentation granularity. Cost compression in standard-tier offerings is intensifying because CNIL-mandated data localization forces redundant infrastructure spend. Neobanks and SME-focused fintechs exhibit highest price sensitivity, while systemic banks absorb premium pricing for audit-ready compliance infrastructure.
Supply Chain Analysis
Tariff exposure between US and China semiconductor flows dominates hardware procurement risk for French AI training clusters. GPU and specialized AI accelerator supply concentrates in Taiwan, South Korea, and USA, while French sovereign cloud infrastructure draws from domestic nuclear-powered data centers and limited local foundry capacity. Single-source vulnerability in NVIDIA H100 supply chains threatens training pipeline continuity for fraud detection model development. Distribution runs through direct enterprise sales teams and systems integrators serving ACPR-regulated institutions, with API-first vendors bypassing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from embedded finance platforms that disintermediate traditional underwriting relationships through real-time cash flow telemetry.
For Market Incumbents: Harden explainability documentation frameworks before EU AI Act enforcement phases activate, pre-empting competitor compliance delays. Secure captive supply of French-language NLP training data through exclusive partnerships with Paris-Saclay research clusters, defending against neobank algorithmic underwriting entrants. Channel control through open banking API standardization remains the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in Provence-Alpes-Côte d'Azur SME banking corridors where Qonto penetration remains limited and merchant cash flow data is undermonetized. Target mutual insurers in Auvergne-Rhône-Alpes with claims automation tools that bypass legacy core banking integration burdens. A regulatory-first go-to-market emphasizing pre-built ACPR conformity documentation accelerates procurement cycles against compliance-lagged competitors. For Investors and Strategic Acquirers: EU AI Act high-risk system mandates reshape the acquisition landscape toward explainability-as-a-service platforms with pre-certified model interpretability frameworks. Long-term viability centers on vendors that anchor institutional relationships through sovereign cloud deployments and survive consolidation toward infrastructure-scale incumbents. Monitor ACPR enforcement variance against German BaFin and Dutch DNB implementations as the signal for cross-border expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Explainability-as-a-Service Platform | Pre-built ACPR documentation accelerates EU AI Act compliance timelines for acquirers. |
| Sovereign Cloud Infrastructure Partnership | CNIL-preferred data localization satisfies mutual bank procurement requirements. |
| French-Language NLP Model Development | Paris-Saclay research cluster feeds accuracy improvements for customer service automation. |
| Embedded Finance API Integration | Accounting software connections displace relationship-based underwriting with behavioral scoring. |
| Cross-Border Payment AI Expansion | PSD2-mandated SEPA instant transfer volumes demand real-time fraud detection scale. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ACPR regulatory guidance, EU AI Act implementation documents, and hyperscaler capex disclosures. Primary interviews engaged chief risk officers at retail banking divisions, AI product leads at neobanks, CNIL compliance specialists, and procurement directors at mutual insurers. Secondary validation drew from SEC filings of listed fintech vendors, French Tech ecosystem employment databases, and open banking API traffic statistics. Bottom-up deployment estimates triangulate against top-down addressable market sizing from banking sector IT spend benchmarks.
Forecast inputs incorporate technology adoption curves across machine learning, natural language processing, and predictive analytics segments; deployment architecture choices spanning cloud, on-premise, and hybrid configurations; and end-user investment intensity variations between banking institutions, payment processors, and insurance carriers. Modeled CAGRs derive from segment-level growth differentials applied across the projection horizon, with explainable credit scoring and real-time fraud detection treated as high-growth application clusters. Regulatory enforcement phasing assumptions and French-language model accuracy improvement trajectories inform scenario-weighted outcomes.
Sensitivities concentrate around ACPR interpretability threshold tightening, EU AI Act cross-border enforcement harmonization failures, and sovereign cloud infrastructure maturity gaps. Forecasts reflect documented assumptions regarding regulatory timeline adherence and talent supply elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Financial Management Software Market
FinTech
Fintech Credit Management Blockchain Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
Multichannel Digital Banking Integration Software Market
FinTech
Account Checking Software Market
FinTech
Autonomous Finance Market
FinTech
AI in Fintech Market
FinTech
Financial Consolidation Software Market
FinTech
Global Saas Spend Management Software Market
FinTech
Financial Forecasting Software Market
FinTech
Transaction Monitoring Software Market
FinTech
Latin America AI in Fintech Market
FinTech
Vietnam Fintech Market
FinTech
Stock Trading App Market
FinTech
North America Fintech Cloud Market