
 Germany Fintech Market | 2026-2036
Germany Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Fintech Market Foresight
The EU Green Deal's sustainable finance taxonomy is consolidating compliance requirements across German fintech operations. N26 GmbH leverages its banking license to anchor pan-European digital wallet services from its Berlin headquarters. Trade Republic Bank GmbH competes aggressively on commission-free securities trading, while Solaris SE specializes in white-label banking infrastructure that powers third-party neobank launches.
Germany fintech encompasses technology-driven financial services delivered through software platforms, API architectures, and mobile interfaces that automate payments, lending, wealth management, and insurance distribution. These systems typically integrate real-time data pipelines, machine learning risk models, and regulatory reporting modules to serve retail consumers and institutional clients. Payment Processing dominates transaction volume across the sector, while Insurtech Solutions captures expanding margin pools as legacy insurers digitize distribution. Blockchain Services represents the fastest-growing application segment, driven by enterprise demand for tokenized assets and smart-contract settlement.
BaFin enforces strict anti-money laundering protocols and payment services licensing under the German Banking Act, shaping product design and customer onboarding workflows. The EU AI Act and GDPR impose additional algorithmic transparency and data governance obligations on automated credit scoring and fraud detection systems. Stakeholders must monitor how upcoming digital euro specifications from the European Central Bank will reshape wallet infrastructure and interchange economics.
Market Dynamics
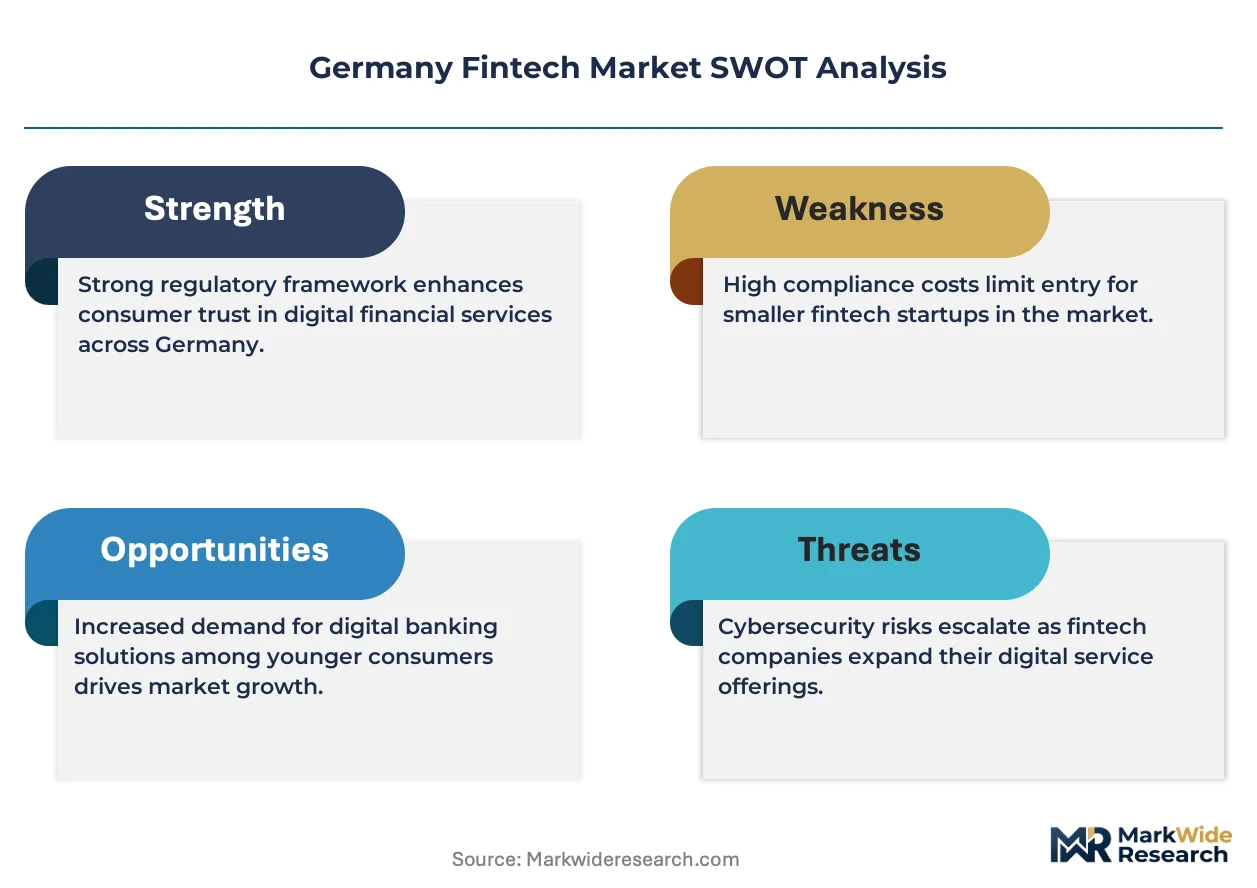
BaFin's regulatory sandbox framework is compressing licensing timelines for neobanks and blockchain providers, while Berlin and Munich venture clusters concentrate capital deployment around payment processing and insurtech infrastructure. This dual regulatory-capital dynamic is restructuring competitive entry barriers across German fintech.
Growth Catalysts
- EU Green Deal taxonomy:Sustainable finance disclosure requirements are forcing legacy insurers to digitize distribution platforms, creating procurement demand for insurtech middleware.
- Real-time payment infrastructure:The European Payments Initiative is accelerating merchant adoption of instant settlement rails across German retail and hospitality sectors.
- Berlin-Munich venture concentration:Seed-stage capital clustering in these cities is compressing startup runway timelines and forcing faster product-market iteration cycles.
Market Restraints
- BaFin AML protocol stringency:Enhanced customer due diligence requirements under the German Banking Act are extending onboarding timelines and increasing compliance headcount ratios.
- Core banking system vendor concentration:Dependency on a limited pool of licensed core system providers creates single-point-of-failure risk for scaling neobanks.
- GDPR algorithmic transparency mandates:Automated credit scoring models face explainability requirements that increase model development costs and constrain feature engineering flexibility.
Strategic Opportunities
- Eastern Germany SME banking:Corporate banking penetration gaps in Saxony and Thuringia create white-space for specialized B2B payment and lending platforms.
- Digital euro wallet infrastructure:Upcoming ECB specifications will require new custody and interchange architectures, creating first-mover advantage for compliant infrastructure builders.
- Embedded finance convergence:API-native banking-as-a-service layers are enabling non-financial platforms in automotive and healthcare to integrate native payment and lending workflows.
Industry Challenges
- Regulatory technologist scarcity:The intersection of financial engineering and EU AI Act compliance expertise commands premium compensation, constraining hiring velocity.
- Legacy core integration friction:Neobanks dependent on white-label banking infrastructure face API versioning conflicts and data schema misalignment during scaling phases.
- CSRD reporting timeline compression:Sustainability disclosure mandates are forcing fintechs to build ESG data pipelines alongside core product development, diverting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Fintech Market |
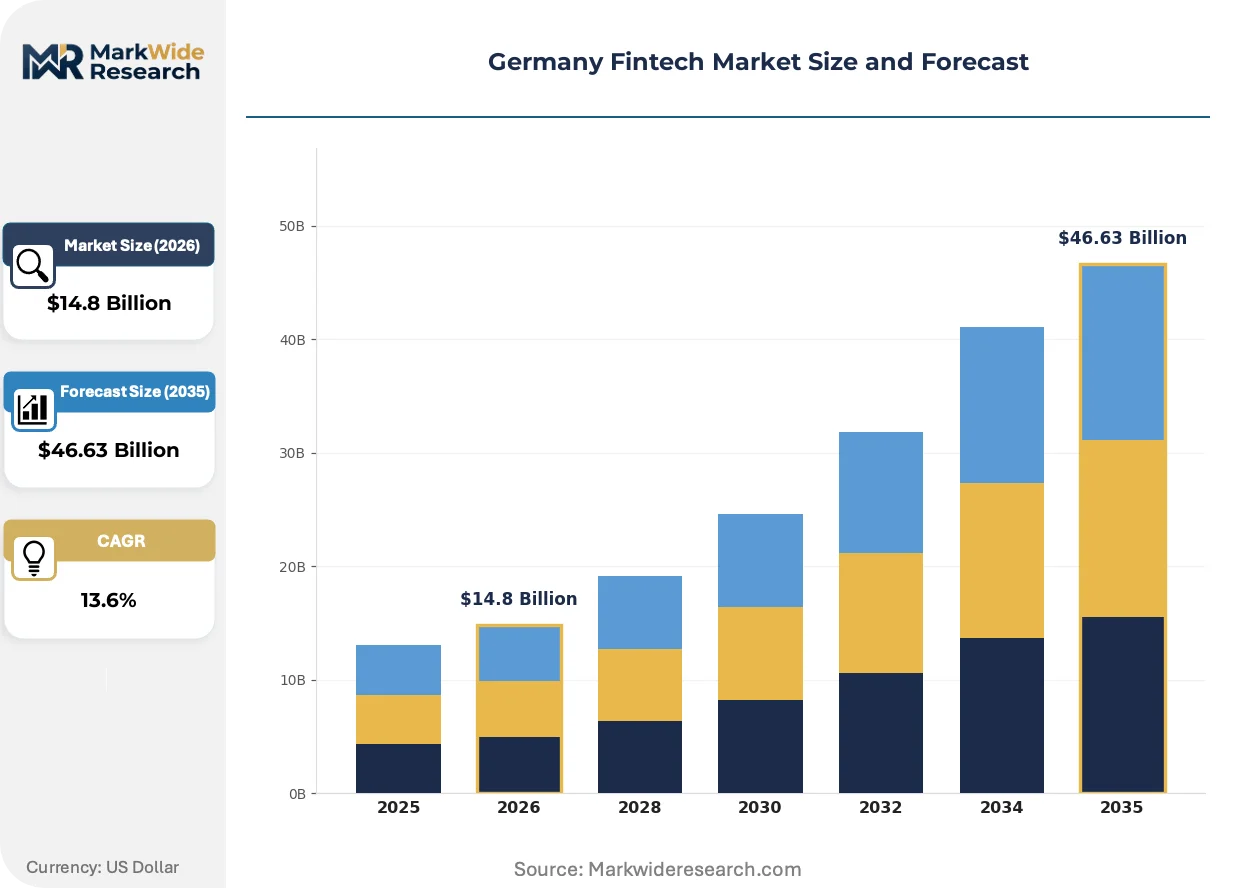
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Payment Processing, Crowdfunding Platforms, Digital Wallets, Blockchain Services, Insurtech Solutions Application: Peer-to-Peer Lending, Wealth Management, Fraud Detection, Regulatory Compliance, Credit Scoring Client Type: Startups, Small and Medium Enterprises, Corporate Firms, Financial Institutions, Venture Capitalists Deployment Model: Cloud-Based, On-Premises, Hybrid Cloud, API Integration, Mobile Platforms |
| Companies Covered | Raisin DS GmbH, Penta Bank GmbH, N26 GmbH, Clark Germany GmbH, Vivid Money GmbH, Trade Republic Bank GmbH, Scalable Capital GmbH, Auxmoney, Solaris SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Fintech Market Shifts & Advancements
Machine learning risk engines and open finance APIs are compressing the traditional banking value chain, while regulatory technology investments reshape cost structures across compliance functions.
Embedded machine learning credit decisioning is rewriting underwriting economics for German SME lenders. Mid-market corporate banks are deploying these models to compress loan approval cycles from weeks to hours. The technology is enabling real-time cash-flow-based lending that bypasses traditional collateral requirements.
The EU AI Act's risk-classification framework is imposing documentation and audit obligations on automated fraud detection systems. German fintechs must now maintain model cards and human-in-the-loop protocols for high-risk AI applications. Payment processors with cross-border operations face the steepest compliance cost escalations as they harmonize German BaFin guidance with Brussels-level enforcement.
SME treasury management is migrating from relationship-bank portals to multi-bank API aggregators. Finance teams in manufacturing and logistics verticals are consolidating cash visibility across fragmented banking relationships. This behavioral shift is most pronounced in Baden-Württemberg's automotive supplier ecosystem, where just-in-time working capital requirements demand real-time liquidity monitoring.
Germany Fintech Market Segmentation
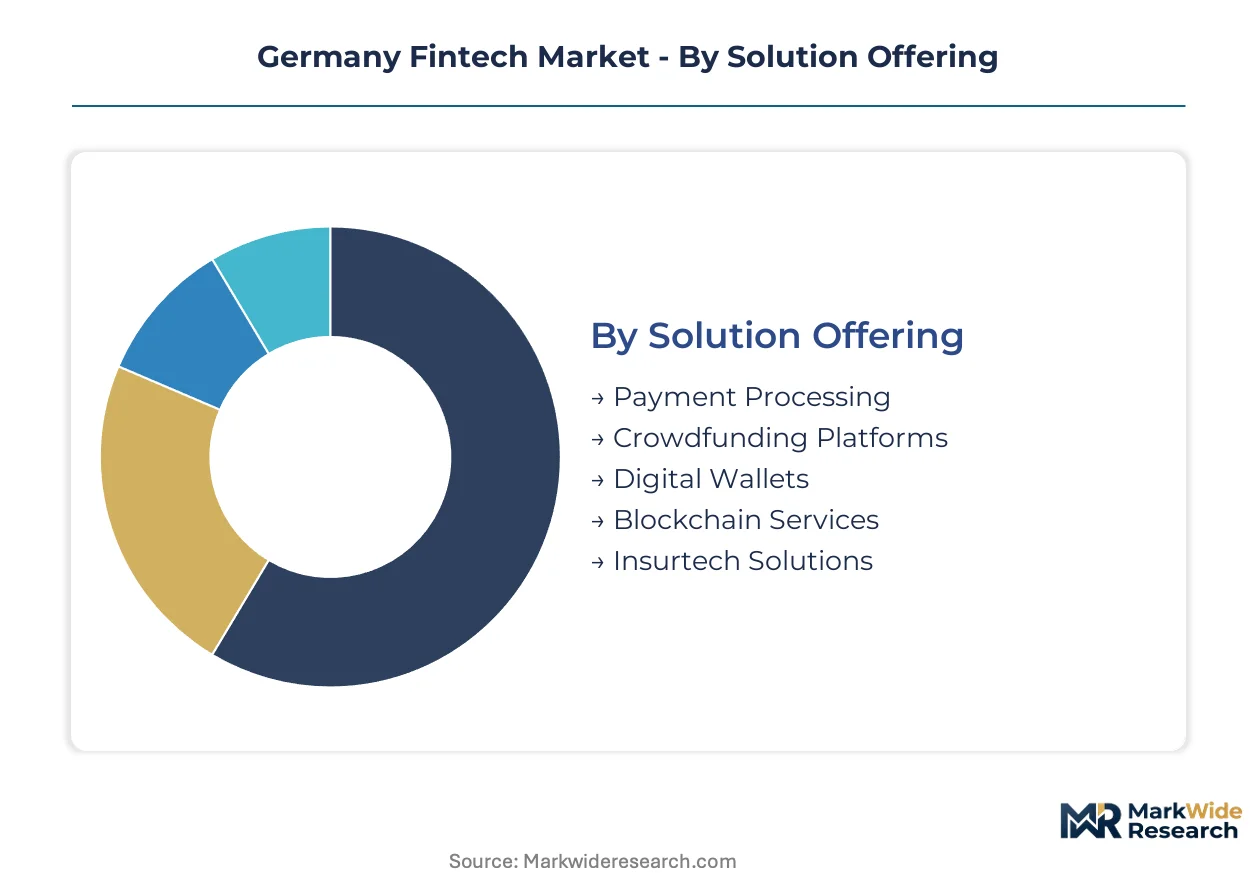
Segmentation reveals how German fintech vendors architect product portfolios around regulatory pressure points and client digital maturity. Understanding these divisions exposes where infrastructure investments concentrate and which deployment models BaFin's compliance frameworks favor.
Solution Offering:
Replacement cycles in German financial infrastructure are accelerating as legacy core systems reach end-of-life and real-time payment mandates take effect.
- Payment Processing:Real-time settlement rails and SEPA Instant integration dominate merchant acquisition strategies across German retail and hospitality. Berlin-based processors are capturing volume from traditional acquiring banks by embedding instant confirmation APIs into POS terminals.
- Blockchain Services:Enterprise tokenization platforms and smart-contract settlement engines are displacing manual reconciliation workflows in trade finance. BaFin's crypto custody licensing regime is filtering out unregulated operators while concentrating institutional demand among licensed infrastructure providers.
- Insurtech Solutions:Middleware platforms digitizing legacy insurer distribution networks.
- Digital Wallets:Pan-European wallet infrastructure anchored by German banking licenses.
- Crowdfunding Platforms:SME debt and equity platforms serving BaFin-regulated alternative investment markets.
Payment Processing sits at the top of the volume ranking, with Blockchain Services climbing the fastest.
Application:
Cost tier differentiation separates commodity fraud detection from high-margin wealth management platforms requiring MiFID II compliance architecture.
- Fraud Detection:Machine learning transaction monitoring systems with EU AI Act documentation requirements. German payment processors face steepest compliance cost escalations as they harmonize BaFin guidance with Brussels-level enforcement.
- Regulatory Compliance:Automated AML screening and CSRD reporting pipelines with explainable audit trails. Engineering teams in Munich are diverting resources from core product development to build ESG data infrastructure alongside compliance modules.
- Credit Scoring:Cash-flow-based underwriting models for SME lending.
- Wealth Management:Robo-advisory platforms with MiFID II suitability protocols.
- Peer-to-Peer Lending:Marketplace platforms connecting retail investors to SME borrowers.
Fraud Detection commands the largest addressable spend, while Regulatory Compliance is expanding most quickly.
Client Type:
Customer type segmentation maps directly to sales cycle length and implementation complexity across German fintech vendor pipelines.
- Financial Institutions:Incumbent banks procuring white-label infrastructure and API layers for digital transformation. These clients demand ISO 20022 messaging compatibility and multi-year service level agreements.
- Small and Medium Enterprises:Mid-market corporates in Baden-Württemberg's automotive supplier ecosystem adopting multi-bank treasury aggregators. Real-time liquidity monitoring requirements are displacing relationship-bank portal dependency.
- Corporate Firms:Large enterprises with captive finance units.
- Startups:Venture-backed neobanks and embedded finance platforms.
- Venture Capitalists:Investors funding Series A and B rounds in Berlin-Munich clusters.
Financial Institutions anchor current revenue concentration, with Small and Medium Enterprises gaining share fastest.
Deployment Model:
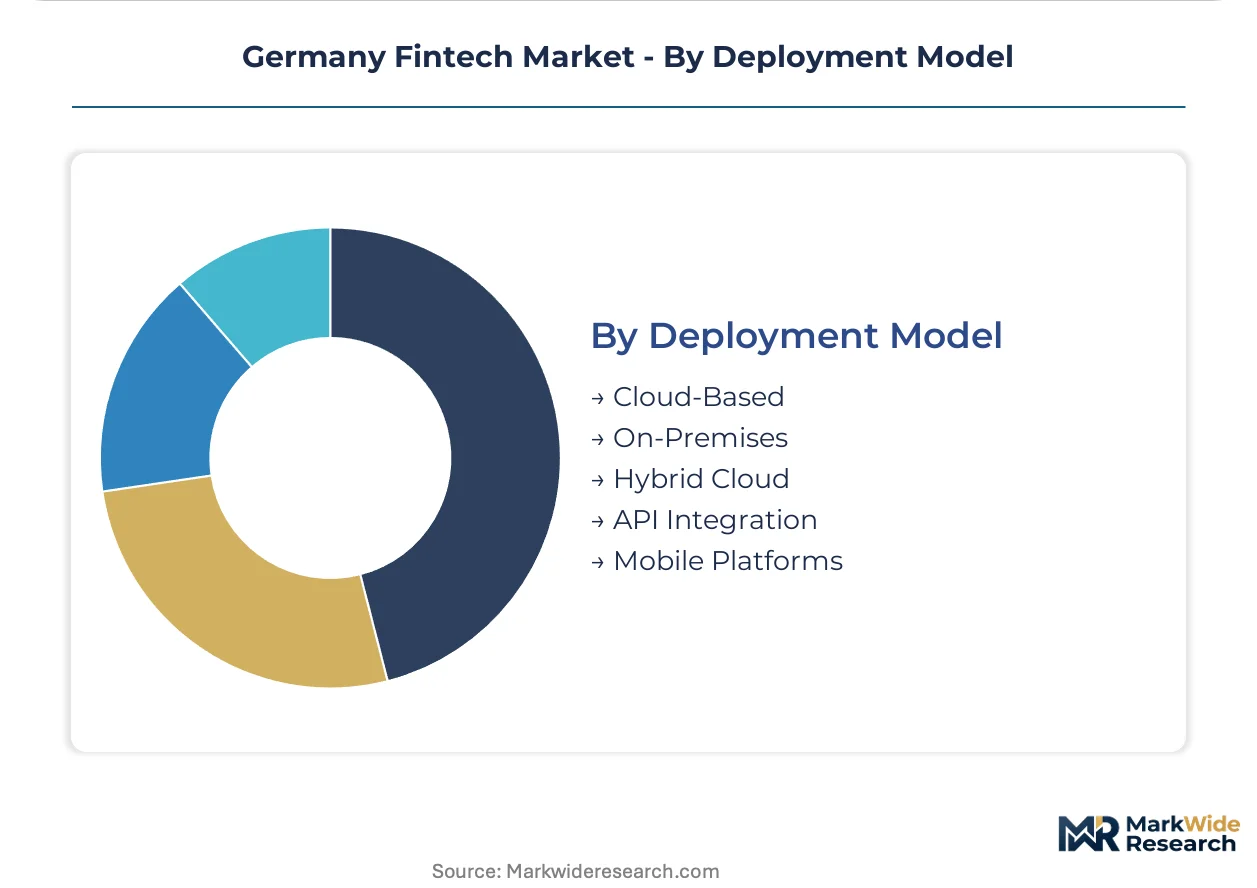
Volume distribution favors cloud-native architectures, though BaFin's data localization requirements preserve hybrid demand for sensitive core banking functions.
- Cloud-Based:Fully managed SaaS infrastructure with EU sovereign cloud certifications. German fintechs are migrating fraud detection and customer onboarding workloads to Frankfurt-region data centers.
- API Integration:Banking-as-a-service layers enabling non-financial platforms to embed payment and lending workflows. Automotive and healthcare verticals in Bavaria are integrating native financial services through these interfaces.
- Hybrid Cloud:Split architectures keeping core ledger data on-premises while front-end services scale elastically.
- On-Premises:Legacy core systems in regulated custody and securities processing.
- Mobile Platforms:Native iOS and Android applications with biometric authentication.
Cloud-Based deployment dominates transaction volume, with API Integration showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical talent pools in Berlin and Munich anchor Germany's fintech infrastructure, drawing engineering graduates from TU Berlin, LMU Munich, and international recruitment pipelines. This workforce concentration shapes where venture capital deploys and which regulatory interpretations gain traction.
Bavaria
Automotive finance units and industrial SME banking drive platform procurement in Munich and Ingolstadt. BaFin's regional office interprets AML protocols strictly for payment processors serving Bavaria's manufacturing exporters. The Munich venture cluster concentrates insurtech infrastructure investments alongside corporate venture arms of Allianz and Munich Re.
North Rhine-Westphalia
Ruhr Valley industrial restructuring creates demand for B2B lending platforms serving mid-market metalworking and logistics firms. The state's economic development agency channels public co-investment into fintechs addressing SME credit gaps. Cologne anchors payment processing scale-ups targeting retail and hospitality verticals across the Rhine-Ruhr metropolitan region.
Baden-Württemberg
Automotive supplier ecosystems in Stuttgart and Mannheim require real-time treasury management and working capital optimization tools. The regional government's Mittelstand 4.0 initiative subsidizes digital banking adoption among family-owned manufacturers. Heidelberg and Karlsruhe host blockchain infrastructure labs spun out from university research partnerships.
Berlin-Brandenburg
Neobank headquarters density and crypto custody licensing activity concentrate in Berlin's Kreuzberg and Mitte districts. BaFin's primary supervision office processes the majority of German fintech license applications from this location. The Brandenburg hinterland provides lower-cost engineering offices while maintaining regulatory proximity to the federal capital.
Hesse
Frankfurt's incumbent banking infrastructure creates procurement demand for regulatory technology and core system modernization. The European Central Bank's presence shapes compliance product development timelines for vendors serving eurozone-facing clients. Darmstadt's technical university feeds risk modeling talent into Frankfurt's quantitative finance sector.
Germany Fintech Market Competitive Landscape
Capital-heavy licensed banks compete with asset-light banking-as-a-service orchestrators across German fintech infrastructure. The market structure fragments across three tiers: full-stack neobanks holding BaFin licenses, white-label infrastructure providers licensing core systems, and vertical SaaS platforms embedding financial workflows. Strategic moves concentrate on API partnership networks and geographic expansion into adjacent EU markets under passporting rights.
Among Berlin-based full-stack operators, N26 GmbH and Trade Republic Bank GmbH exemplify the licensed-neobank archetype, while Solaris SE occupies the infrastructure-provider tier enabling third-party launches. These entities represent contrasting capital intensity models within the same regulatory jurisdiction.
| Leading Market Players |
|---|
| Raisin DS GmbH |
| Penta Bank GmbH |
| N26 GmbH |
| Clark Germany GmbH |
| Vivid Money GmbH |
| Trade Republic Bank GmbH |
| Scalable Capital GmbH |
| Auxmoney |
| Solaris SE |
| Others |
Supply & Pricing Matrix
Regulatory technologist scarcity in Berlin and Munich widens pricing-tier spreads between premium compliance-integrated platforms and commodity middleware providers, compressing margins for vendors lacking BaFin licensing expertise.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates full-stack neobanks with BaFin licenses from white-label infrastructure renters and API-only middleware vendors. Price differentiation hinges on certification depth—EU AI Act documentation and GDPR audit trails command substantial premiums—while cost compression in the economy tier intensifies because unlicensed blockchain providers undercut on customer onboarding fees. Financial institutions exhibit lowest price sensitivity due to regulatory liability exposure, whereas SME fintech adopters in Eastern Germany drive hardest bargain negotiations.
Supply Chain Analysis
BaFin's crypto custody licensing regime gates supply participation, filtering vendor pools to qualified infrastructure builders. Engineering talent draws from TU Berlin, LMU Munich, and Frankfurt-region technical universities, while core banking system components source from established German and Dutch software houses. Single-source vulnerability concentrates in licensed core ledger providers, creating scaling bottlenecks for neobanks. Distribution runs through direct enterprise sales teams for institutional clients and API marketplaces for embedded finance integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Fintech Market reads as a late-cycle quality story, with procurement shifting toward premium-specification platforms bearing full BaFin compliance architecture and explainable AI documentation.
For Market Incumbents: Deploy regulatory technology talent acquisition as the primary defensive lever. Consolidate around captive compliance engineering teams to offset BaFin AML protocol stringency, while extending API versioning stability guarantees to white-label banking clients facing core system integration friction. N26 GmbH and Solaris SE anchor competitive positioning through licensing moats that unlicensed entrants cannot replicate without 18-24 month regulatory timelines. For New Entrants and Emerging Players: Automotive OEM treasury departments in Baden-Württemberg represent the most penetrable white-space target, given real-time liquidity monitoring requirements displacing relationship-bank portal dependency. Eastern Germany SME banking gaps in Saxony and Thuringia offer secondary entry vectors with lower competitive density. Pursue banking-as-a-service partnerships with healthcare and logistics verticals seeking embedded finance integration rather than direct-to-consumer neobank launches. For Investors and Strategic Acquirers: Corporate venture arms of incumbent insurers and automotive finance units are the most active acquirers in this space, prioritizing digital distribution infrastructure and treasury management APIs. Long-term viability favors platforms with dual competency in financial engineering and EU AI Act compliance documentation. Monitor ECB digital euro specification releases as the critical inflection signal for wallet infrastructure valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Entry | BaFin's compressed licensing timelines accelerate neobank market entry versus traditional banking charters. |
| Core System Modernization | ISO 20022 messaging compatibility investments unlock incumbent bank procurement pipelines for infrastructure vendors. |
| AI Compliance Documentation | Model cards and human-in-the-loop protocols satisfy EU AI Act risk-classification mandates for automated underwriting. |
| API Partnership Expansion | Banking-as-a-service layers enable automotive and healthcare verticals to embed native payment workflows. |
| Regional Venture Clustering | Berlin-Munich capital concentration compresses startup runway timelines and forces faster product-market iteration. |
Research Methodology
Direct dialogue with BaFin licensing officers, neobank CTOs, insurtech product leads, and SME treasury managers in Baden-Württemberg grounded the qualitative foundation. Secondary validation drew from ECB payment infrastructure disclosures, BaFin sandbox approval registers, German Banking Act amendments, and venture capital deployment databases tracked by regional economic development agencies. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-level projections incorporated solution offering splits by payment processing, blockchain services, and insurtech middleware alongside deployment model differentiation between cloud-native and hybrid architectures. CAGRs derived from regression analysis against real-time payment adoption curves and regulatory technology investment cycles. Model inputs included BaFin licensing velocity trends and ECB digital euro development milestones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement calibration and digital euro specification finalization. A model refresh is warranted upon material change in BaFin sandbox throughput rates or ECB central bank digital currency timeline announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
US AI in Fintech Market
FinTech
United States Fintech Market
FinTech
Germany AI in Fintech Market
FinTech
Africa AI in Fintech Market
FinTech
Netherlands AI in Fintech Market
FinTech
North America Fintech Cloud Market
FinTech
AI Finance Market
FinTech
Fintech Lending Market
FinTech
Cyber Security in Fintech Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
Latin America Fintech Market
FinTech
UAE Fintech Market
FinTech
Account Checking Software Market
FinTech
Cloud AI in Fintech Market
FinTech
Lendtech Market