
 API Banking Market | 2026-2036
API Banking Market Size, Share, and Industry Trends Forecast 2026-2036
API Banking Market Analysis
Enterprise buyer concentration is shifting as mid-market fintech aggregators consolidate their vendor relationships around fewer API infrastructure partners. Plaid leverages its North American bank coverage to sustain connectivity density across thousands of institutions. TrueLayer anchors European open-banking payment initiation, competing on raw API latency against regional specialists. Salt Edge differentiates through multi-jurisdiction compliance tooling that spans emerging and developed markets simultaneously.
API banking denotes programmable interfaces that expose core banking functions—account data retrieval, payment initiation, and fund verification—to authorized third parties via standardized REST or SOAP protocols with OAuth authentication layers. These interfaces eliminate screen-scraping fragility and enable real-time financial data exchange between institutions and licensed fintech operators. Payment Services currently dominates transaction volume across the Service Type dimension, while Account Information Services occupies the margin-rich analytics layer where subscription pricing models proliferate. Full Stack Integration leads among Integration Level categories as neobanks seek end-to-end control, though Middleware Solutions is growing fastest among legacy institutions attempting phased modernization without core replacement.
PSD2 and the forthcoming PSD3 framework in Europe, alongside the Consumer Financial Protection Bureau's Section 1033 rulemaking in the United States, are reshaping liability allocation and data portability requirements for API providers. The Financial Conduct Authority in the United Kingdom enforces operational resilience standards that mandate 99.99% uptime commitments for critical payment APIs, directly inflating infrastructure cost structures. Stakeholders must monitor which jurisdictions move from permissive open-banking regimes toward mandatory open-finance expansion into lending and insurance data, as this regulatory boundary will determine the next wave of addressable API endpoints.
Market Dynamics
Embedded finance adoption is compressing intermediary layers as e-commerce merchants demand direct payment orchestration capabilities, forcing API infrastructure providers to reconfigure their connectivity architectures around real-time data exchange rather than batch-processed aggregation.
Growth Catalysts
- PSD2 and PSD3 Frameworks:European mandates for open banking are compelling legacy institutions to expose core functions through standardized interfaces, creating mandatory demand for API infrastructure upgrades.
- Real-Time Payment Rails:Instant settlement networks in the United Kingdom and Brazil are eliminating float-based revenue models and requiring API providers to engineer sub-second latency into payment initiation flows.
- Merchant Payment Orchestration:E-commerce platforms are building in-house checkout stacks that bypass traditional payment aggregators, pulling raw banking connectivity directly from API specialists.
Market Restraints
- Core System Replacement Costs:Legacy mainframe architectures at tier-one banks require capital-intensive middleware layers to achieve API compatibility, constraining vendor selection to well-capitalized infrastructure providers.
- Operational Resilience Mandates:The Financial Conduct Authority's 99.99% uptime requirements for critical payment APIs are inflating infrastructure cost structures and compressing margins for connectivity providers.
- Screen-Scraping Persistence:Unregulated data aggregation methods continue to undercut compliant API pricing in jurisdictions without active enforcement, delaying full market transition to authorized access models.
Strategic Opportunities
- Open Finance Expansion:Regulatory boundary extensions into lending and insurance data in Australia and Brazil will multiply addressable API endpoints beyond current payment and account information scopes.
- Middleware Solutions Growth:Phased modernization demand from regional banks seeking core replacement avoidance is accelerating adoption of API abstraction layers that bridge legacy and modern infrastructure.
- Cross-Border Payment APIs:Correspondent banking compression is creating white space for API providers to engineer direct currency exchange and settlement corridors between non-traditional banking partners.
Industry Challenges
- OAuth Implementation Complexity:Multi-factor authentication engineering across heterogeneous bank security architectures is consuming disproportionate development resources and extending integration timelines.
- Standardization Fragmentation:Competing API specifications across national open-banking regimes are forcing providers to maintain parallel codebases, diluting engineering focus and inflating maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | API Banking Market |
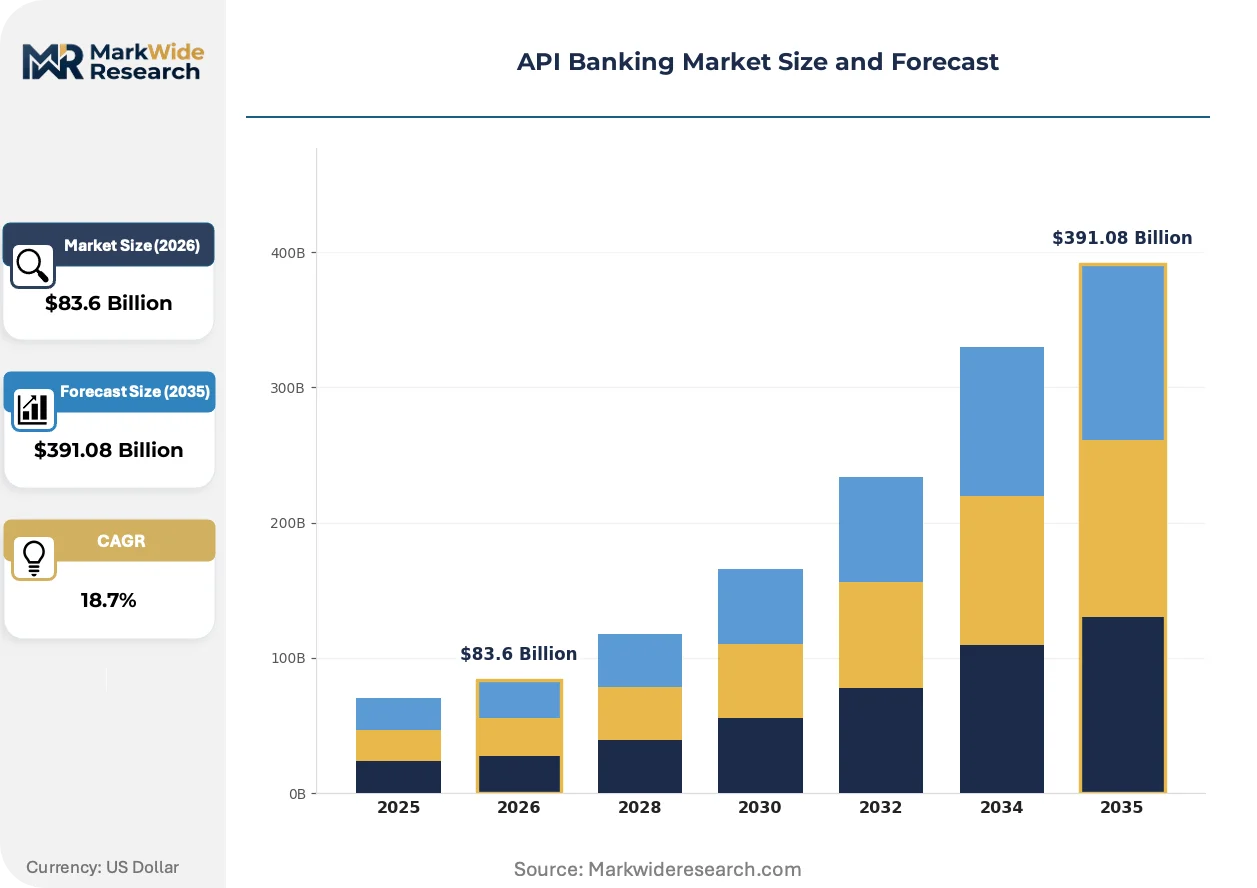
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $391.08 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Services, Account Information Services, Fund Confirmation Services, Credit Scoring Services End User: Financial Institutions, Fintech Companies, E-commerce Platforms, Retail Banks Integration Level: Full Stack Integration, Partial Integration, Middleware Solutions, Sandbox APIs Deployment: Public Cloud, Private Cloud, On-Premises, Hybrid Cloud |
| Companies Covered | Yapily, Salt Edge, Plaid, Finicity, Bud Financial, Tink, Token, MX Technologies, TrueLayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
API Banking Market Emerging Trajectories
API banking infrastructure is absorbing generative capabilities as providers embed conversational interfaces and automated code generation into developer portals, compressing integration timelines and reducing technical barriers for non-specialist engineering teams.
Event-driven architecture is absorbing real-time webhooks as the dominant notification pattern for account data changes, displacing polling-based retrieval methods that consumed unnecessary compute resources. Neobanks and fintech aggregators are adopting these streaming interfaces at scale, enabling instant balance updates and transaction alerts without repeated API calls. This shift is absorbing latency out of customer-facing applications and compressing the competitive differentiation window for providers still reliant on request-response models.
REACH chemical safety frameworks and parallel consumer data protection mandates in Europe are tightening liability allocation for API providers handling sensitive financial information, forcing explicit data residency commitments and encryption standard upgrades. The industrial consequence is geographic fragmentation of infrastructure deployment as providers establish region-specific processing nodes to satisfy sovereignty requirements. Payment initiation services in Germany and France are responding by engineering multi-region failover architectures that maintain compliance without sacrificing cross-border functionality.
Developer experience has become the primary procurement differentiator as mid-market fintech aggregators consolidate vendor relationships around unified API documentation, sandbox environments, and SDK availability rather than raw connectivity breadth. Traditional banking software distributors are losing ground to specialized API infrastructure vendors that bundle technical support and compliance tooling into subscription pricing. This behavioral shift is most visible in the United Kingdom, where mature fintech ecosystems have conditioned buyers to expect consumer-grade developer portals from B2B financial infrastructure providers.
API Banking Market Segmentation
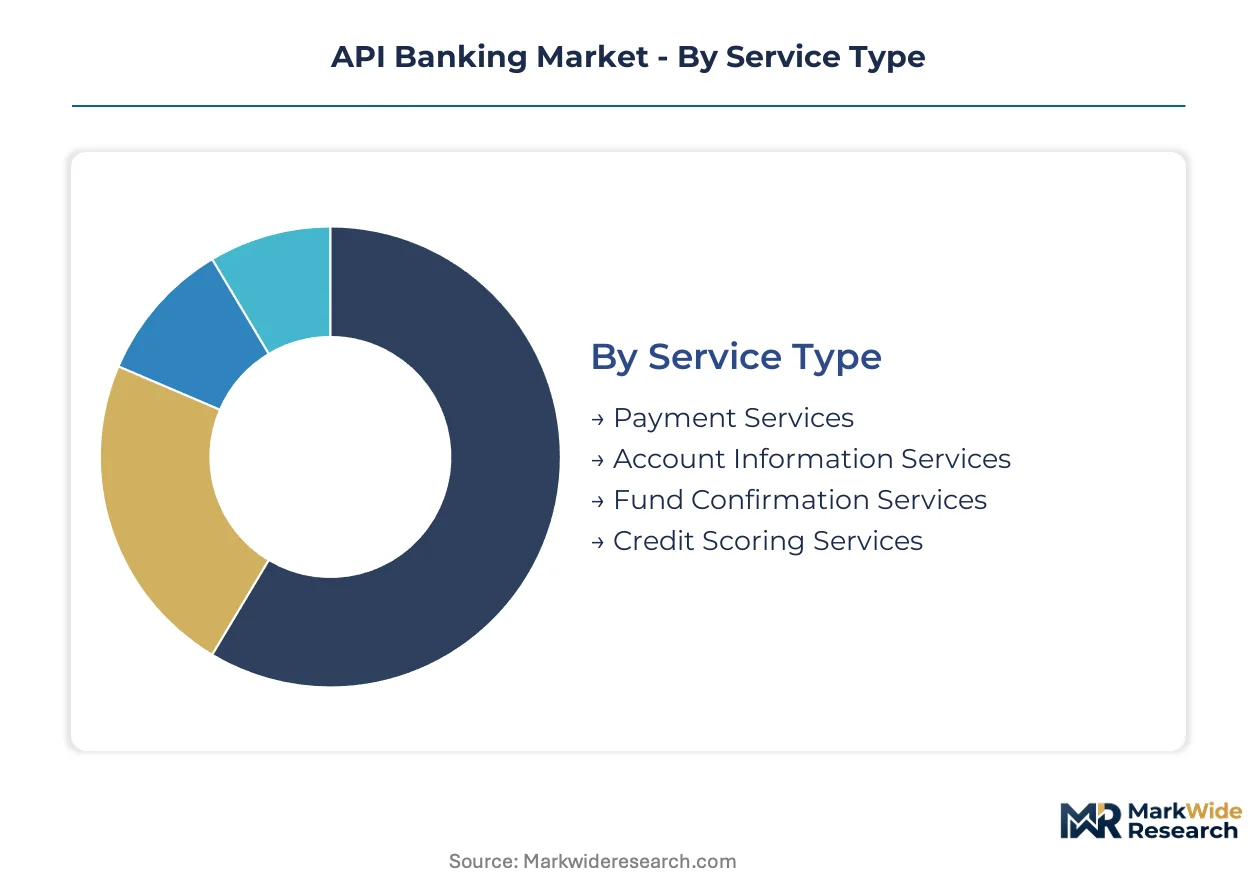
API banking segmentation reveals how infrastructure requirements diverge across regulatory exposure levels, integration complexity, and data sensitivity. Each dimension carries distinct certification burdens and capital intensity profiles that reshape vendor selection criteria.
Service Type:
Payment Services and Account Information Services face the heaviest PSD2 compliance obligations, while Fund Confirmation and Credit Scoring operate under lighter supervisory frameworks.
- Payment Services:Real-time payment initiation APIs demand Strong Customer Authentication under PSD2 Article 97, with liability for unauthorized transactions shifting to providers. UK neobanks and German direct banks concentrate procurement here, driven by instant settlement rail adoption.
- Account Information Services:Multi-bank data aggregation requires eIDAS-qualified trust service provider status for certificate issuance. French fintech aggregators and Dutch accounting software vendors dominate demand, constrained by GDPR Article 32 encryption mandates.
- Fund Confirmation Services:Balance verification APIs face lighter PSD2 scope but require ISO 20022 message standardization.
- Credit Scoring Services:Alternative data APIs operate outside core open-banking mandates, subject to national credit bureau regulations.
Payment Services sits at the top of the volume ranking, with Credit Scoring Services climbing the fastest.
End User:
Cost tier stratification separates enterprise-grade deployments from mid-market SaaS consumption patterns.
- Financial Institutions:Tier-one banks demand dedicated infrastructure with 99.99% SLA guarantees and FCA operational resilience certification. UK clearing banks and French mutuals anchor this segment, absorbing premium pricing for bespoke compliance tooling.
- Fintech Companies:Licensed payment institutions prioritize sandbox-to-production velocity over raw connectivity breadth. Berlin and Stockholm neobanks concentrate here, constrained by capital-light business models that favor consumption-based API pricing.
- E-commerce Platforms:Merchant acquirers seek embedded checkout orchestration with minimal engineering overhead.
- Retail Banks:Regional institutions favor phased modernization through middleware abstraction layers.
Financial Institutions command the largest deployment scale, with E-commerce Platforms expanding most quickly.
Integration Level:
Application maturity determines whether buyers pursue end-to-end control or incremental capability grafting.
- Full Stack Integration:End-to-end core banking replacement demands ISO 27001 and SOC 2 Type II certification with annual penetration testing. UK challenger banks and Brazilian digital lenders concentrate procurement here, driven by regulatory pressure to sunset legacy mainframe dependencies.
- Middleware Solutions:API abstraction layers bridge COBOL-based cores to modern REST interfaces without full replacement. Italian cooperative banks and Spanish cajas favor this approach, constrained by capital rationing that prevents wholesale infrastructure overhaul.
- Partial Integration:Selective API adoption for specific product lines requires lighter governance overhead.
- Sandbox APIs:Non-production environments carry minimal certification burden but limited revenue conversion.
Full Stack Integration leads absolute spending, with Middleware Solutions gaining share fastest.
Deployment:
Geography and data sovereignty requirements fragment infrastructure topology across residency mandates.
- Public Cloud:Multi-tenant AWS, Azure, and GCP deployments face BaFin and ACPR scrutiny over data localization. Nordic fintechs and Dutch payment startups concentrate here, driven by elastic scaling requirements and limited capital reserves.
- Private Cloud:Single-tenant dedicated infrastructure satisfies FCA and Banque de France operational resilience mandates for critical payment APIs. UK clearing banks and French systemic institutions anchor demand, constrained by audit requirements that prohibit shared tenancy.
- On-Premises:Air-gapped installations serve defense and government banking clients with classified data handling needs.
- Hybrid Cloud:Burst capacity configurations blend resident transaction processing with cloud analytics.
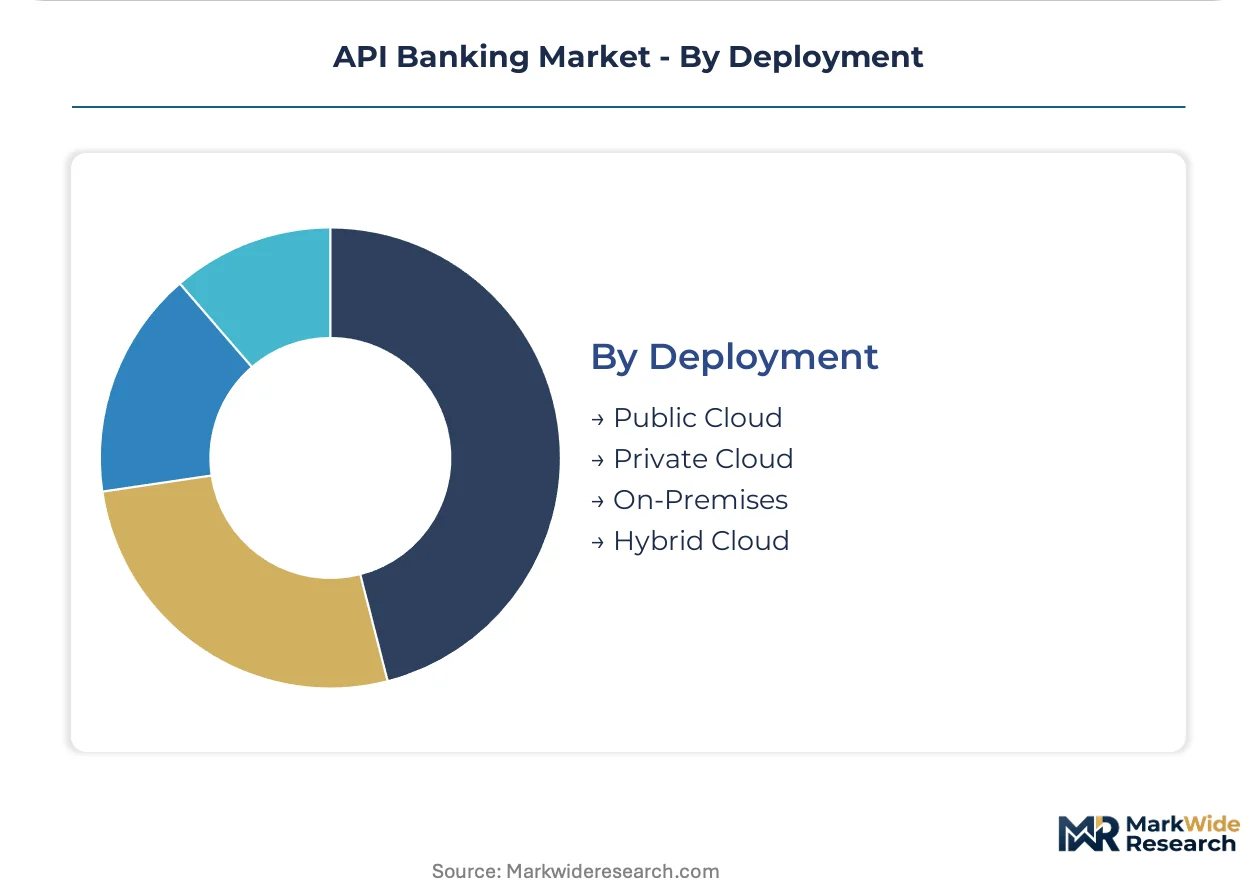
Public Cloud dominates transaction volume, with Hybrid Cloud showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom and Germany demonstrate divergent API banking maturities, with London's fintech density enabling real-time payment orchestration while Berlin's neobank cluster navigates stricter BaFin operational resilience timelines. Brazil and Australia represent emerging regulatory frontiers where open-finance expansion is rewriting data portability rules.
United Kingdom
The Financial Conduct Authority's 99.99% uptime mandate for critical payment APIs has concentrated infrastructure investment among clearing banks and challenger institutions. London's fintech corridor anchors procurement demand, with neobanks in Shoreditch and Canary Wharf driving sandbox-to-production velocity requirements. The Competition and Markets Authority's open-banking remedies continue to shape connectivity pricing.
Germany
BaFin's operational resilience standards and PSD2 Strong Customer Authentication enforcement have elevated compliance tooling to a primary vendor selection criterion. Berlin's neobank cluster and Frankfurt's incumbent banks diverge in procurement patterns, with the former favoring consumption-based API pricing and the latter demanding dedicated private cloud deployments. The German Banking Act amendments are tightening liability frameworks for payment initiation providers.
United States
The Consumer Financial Protection Bureau's Section 1033 rulemaking is forcing regional banks to expose transaction data through standardized interfaces, creating mandatory upgrade cycles. San Francisco's fintech aggregators and New York's merchant acquirers dominate demand, with embedded finance adoption compressing intermediary layers in e-commerce checkout stacks. State-level data privacy fragmentation complicates multi-jurisdiction API deployment.
Brazil
Banco Central do Brasil's PIX instant payment rail and open-finance roadmap are multiplying addressable API endpoints beyond traditional banking scopes. São Paulo's fintech ecosystem anchors demand, with digital lenders and payment processors building direct banking connectivity to bypass legacy aggregator networks. The Central Bank's regulatory sandbox is accelerating licensed payment institution formation.
Australia
The Consumer Data Right's expansion into energy and telecommunications is conditioning financial services participants for broader open-finance data sharing. Sydney's neobanks and Melbourne's accounting software vendors concentrate procurement, with the Australian Competition and Consumer Commission enforcing consent-driven data portability standards. Regional banks are favoring middleware abstraction layers to avoid core replacement costs.
API Banking Market Vendor Landscape
North American providers anchor the connectivity density tier; European specialists hold the regulatory compliance tier. The vendor base separates into three strategic archetypes: bank coverage aggregators, jurisdictional compliance specialists, and embedded finance infrastructure providers. Consolidation pressure is intensifying as mid-market fintech aggregators reduce vendor counts, while geographic expansion and developer experience differentiation represent the dominant competitive vectors.
Within the bank coverage archetype, Plaid exemplifies North American connectivity scale, while TrueLayer occupies a parallel position in European open-banking payment initiation. Salt Edge represents the multi-jurisdiction compliance specialist tier, spanning emerging and developed market regulatory frameworks simultaneously. These three anchors illustrate how vendor selection criteria diverge between raw connectivity breadth, API latency performance, and cross-border compliance tooling depth.
| Leading Market Players |
|---|
| Yapily |
| Salt Edge |
| Plaid |
| Finicity |
| Bud Financial |
| Tink |
| Token |
| MX Technologies |
| TrueLayer |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FCA-mandated 99.99% uptime tiers and standard SLA offerings manifests in both subscription pricing stratification and infrastructure deployment geography. Premium private cloud commitments in the United Kingdom and Germany absorb threefold cost multiples against public cloud consumption patterns in the Netherlands and Nordic markets, with compliance tooling bundling driving vendor selection toward capital-intensive dedicated deployments.
Pricing Analysis
Capacity additions in Ireland and the Netherlands are reshaping price floors for middleware abstraction layers as regional banks seek phased modernization without core replacement. The dominant pricing structure stratifies across premium certified tiers, standard regulated offerings, and economy sandbox environments, with FCA operational resilience certification and BaFin Strong Customer Authentication compliance as primary price differentiation drivers. Pricing pressure stems from screen-scraping persistence in jurisdictions without active PSD2 enforcement, compressing margins for authorized access providers. Mid-market fintech aggregators in Berlin and Stockholm exhibit highest price sensitivity, while UK clearing banks absorb premium pricing for bespoke compliance tooling.
Supply Chain Analysis
Cloud engineering talent scarcity in London and Frankfurt constrains infrastructure deployment velocity for API providers serving FCA and BaFin regulated institutions. Geographic supply concentrates in Ireland, the Netherlands, and the United Kingdom for hyperscaler data center capacity, with raw material dependencies spanning specialized encryption hardware, eIDAS-qualified trust service certificates, and ISO 20022 message standardization libraries. Supply chain risk centers on single-source vulnerability for qualified certificate issuance under eIDAS frameworks. Distribution runs through direct enterprise sales teams for tier-one banks and self-serve developer portals for neobank and fintech aggregator segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The API banking market functions as a geographic-arbitrage play where regulatory lag between European PSD2 enforcement and nascent open-finance frameworks in Brazil and Australia creates 18-24 month capability windows for infrastructure providers.
For Market Incumbents: Hedge against embedded finance compression by acquiring middleware specialists that bridge legacy COBOL cores to modern REST interfaces, while building private cloud capacity in Frankfurt and London to satisfy BaFin and FCA data residency mandates before regulatory deadlines harden. For New Entrants and Emerging Players: Launch via regulatory sandbox pathways in São Paulo and Sydney where open-finance expansion multiplies addressable endpoints beyond payment and account information scopes, targeting Brazilian digital lenders and Australian accounting software vendors with consumption-based API pricing that bypasses upfront certification burdens. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-market fintech aggregators reduce vendor counts from five-plus connectivity providers to two strategic partners. Long-term viability favors acquisition targets with multi-jurisdiction compliance tooling spanning emerging and developed markets simultaneously, with PSD3 framework progression in Europe as the critical inflection signal for infrastructure valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Abstraction Layer Development | Enables Italian cooperative banks to modernize without core replacement costs. |
| Multi-Region Failover Architecture Engineering | Satisfies German and French data sovereignty requirements without cross-border functionality loss. |
| Developer Portal Experience Investment | Captures UK mid-market fintech aggregator procurement consolidation toward unified documentation. |
| Regulatory Sandbox Licensing Acceleration | Positions providers for Brazilian Central Bank payment institution formation growth. |
| Event-Driven Webhook Infrastructure Deployment | Displaces polling-based retrieval for Nordic neobanks seeking instant balance updates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with API infrastructure CTOs, open-banking compliance officers at tier-one banks, fintech aggregator platform engineers, and regulatory sandbox program directors with secondary validation against PSD2 implementation reports, FCA operational resilience disclosures, BaFin banking act amendments, and Banco Central do Brasil open-finance roadmaps. Bottom-up transaction volume modeling and top-down regulatory mandate sizing were triangulated against hyperscaler capex disclosures and cloud region expansion announcements.
Historical reference periods anchored the forecast window to pre-PSD2 implementation baselines and post-mandate adoption curves across European markets. The analytical framework modeled segmentation across service type, integration level, deployment topology, and regional regulatory maturity. CAGRs were derived from adoption velocity differentials between mandatory open-banking regimes and permissive open-finance expansions. Industry-specific forecast inputs included instant payment rail penetration rates and Strong Customer Authentication enforcement timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PSD3 framework acceleration or delayed CFPB Section 1033 rulemaking in the United States. Forecasts reflect documented assumptions regarding regulatory boundary extensions and bank IT modernization budget allocations. Material deviation in open-finance mandate timing or core system replacement cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Banking ERP Software Market
Banking
Cloud-Based Core Banking Market
Banking
Embedded Banking Market
Banking
Blockchain in Retail Banking Market
Banking
Europe Neobanking Market
Banking
Latin America Neo Banking Services Market
Banking
China Retail Banking System Market
Banking
North America Machine Learning in Banking Market
Banking
Investment Banking Market
Banking
Banking Wearable Market
Banking
France Data Analytics in Banking Market
Banking
Spain Data Analytics in Banking Market
Banking
Germany Banking As a Service Market
Banking
AI and Automation in Banking Market
Banking
Australia Neobanking Market
Banking
Banking Credit Analytics Market