
 Mercury (I) Sulphate Market | 2026-2036
Mercury (I) Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Mercury (I) Sulphate Market Outlook
Green synthesis pathways for mercury-based compounds is narrowing the viable production methods open to legacy manufacturers. Merck KGaA leverages its analytical standards portfolio to dominate laboratory-grade supply chains in Europe. Alfa Chemistry specializes in custom synthesis contracts for research institutions requiring non-standard purity specifications. Shanghai Zhihua ChemTech Inc. competes on manufacturing scale, serving bulk industrial orders across Asian battery material labs.
Mercury (I) sulphate, with the chemical formula Hg₂SO₄, consists of mercury in its +1 oxidation state combined with the sulphate anion; this dimeric mercury structure imparts distinct electrochemical properties that make the compound indispensable as a reference electrode material in chloride-free potentiometric measurements. Laboratory grade commands premium positioning due to stringent certification requirements for analytical applications, while industrial grade anchors volume demand from electrochemical manufacturing. Catalyst usage within the usage-type taxonomy is maturing as solid-state alternatives displace liquid mercury systems, yet reagent applications sustain growth in metrology and environmental testing protocols.
The EPA regulates mercury compound emissions and waste handling under the Resource Conservation and Recovery Act, compelling U.S. handlers to maintain closed-loop recovery systems. ECHA enforces REACH authorization requirements for mercury substances, restricting market access to registered suppliers with documented safety dossiers. India's Central Pollution Control Board monitors mercury waste disposal through state-level hazardous waste management rules. Stakeholders must weigh regulatory compliance investments against the shrinking addressable market for mercury-based chemistries as electrode technologies evolve.
Market Dynamics
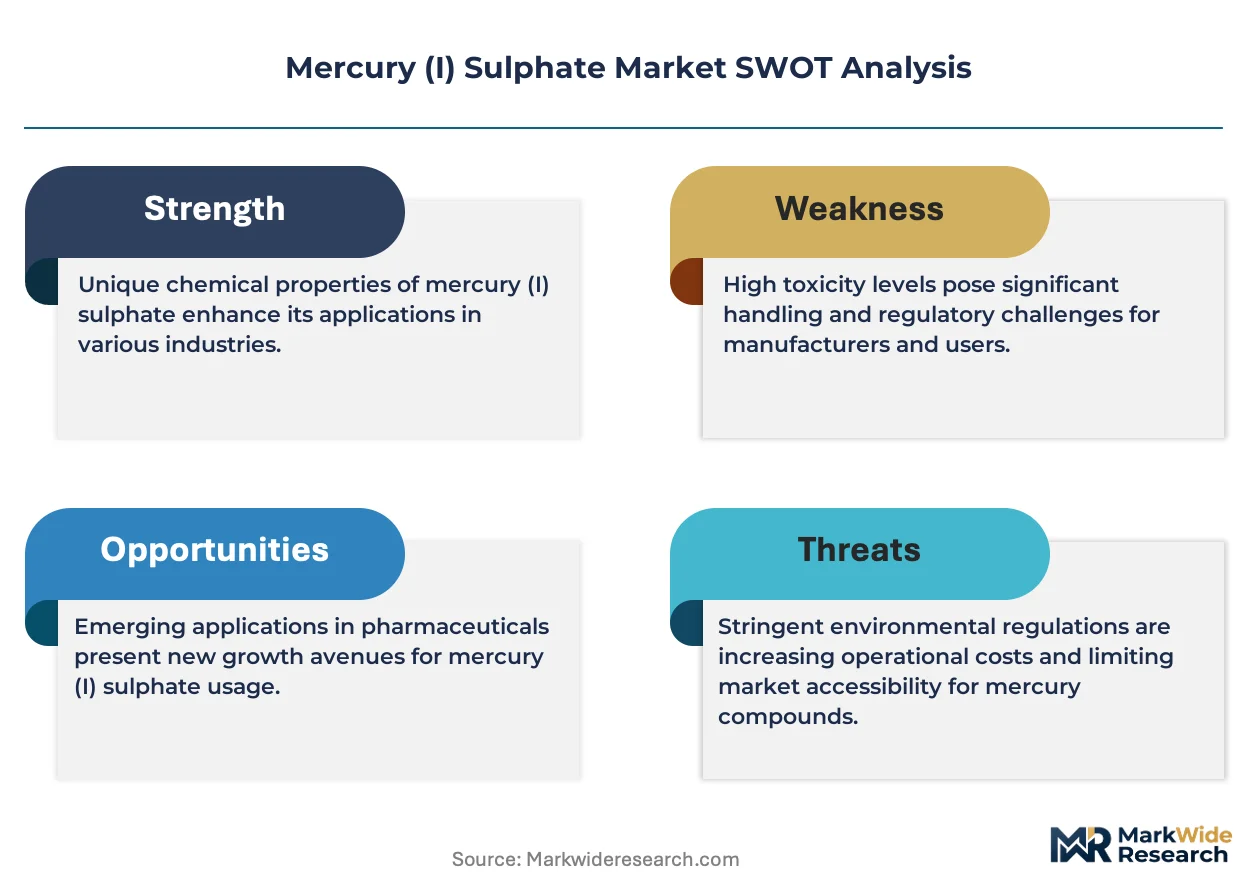
REACH authorization requirements under ECHA are compressing the supplier base for mercury (I) sulphate, redirecting procurement toward registered handlers with closed-loop recovery capabilities and documented safety dossiers.
Growth Catalysts
- Potentiometric calibration demand:Chloride-free reference electrode protocols in analytical chemistry laboratories sustain steady consumption of laboratory-grade material. Metrology institutes in Germany and Switzerland anchor this demand segment.
- REACH-compliant supplier consolidation:Authorization bottlenecks eliminate unregistered competitors, expanding margin capture for certified European producers with validated handling infrastructure.
- Battery materials R&D:Electrochemical cell manufacturers require mercury (I) sulphate for half-cell testing of novel cathode formulations, particularly solid-state electrolyte research programs.
Market Restraints
- Mercury feedstock volatility:Primary mercury supply concentrates in Kyrgyzstan and Algeria, exposing processors to geopolitical disruption and export quota uncertainty.
- Solid-state electrode substitution:Silver-silver chloride and ion-selective polymer references are displacing mercury-based systems in environmental monitoring applications.
- ECHA authorization friction:Sunset date reviews for mercury compounds create investment paralysis among potential market entrants lacking grandfathered registrations.
Strategic Opportunities
- Pharmaceutical-grade certification:USP and EP monograph compliance opens access to quality control laboratories in regulated drug manufacturing, commanding substantial premia over industrial grades.
- Closed-loop service contracts:Waste recovery and material return programs align with EPA RCRA requirements while generating recurring revenue streams from captive laboratory relationships.
- Custom synthesis specialization:Non-standard purity specifications for isotope ratio mass spectrometry and nuclear magnetic resonance calibration represent underserved niches with limited competition.
Industry Challenges
- Specialized waste handling certification:Operators must maintain hazardous waste transporter licenses and treatment facility permits, extending compliance timelines for new market entrants.
- Analytical chemist talent scarcity:Mercury compound expertise is concentrating among retiring specialists, complicating quality control and synthesis protocol development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mercury (I) Sulphate Market |
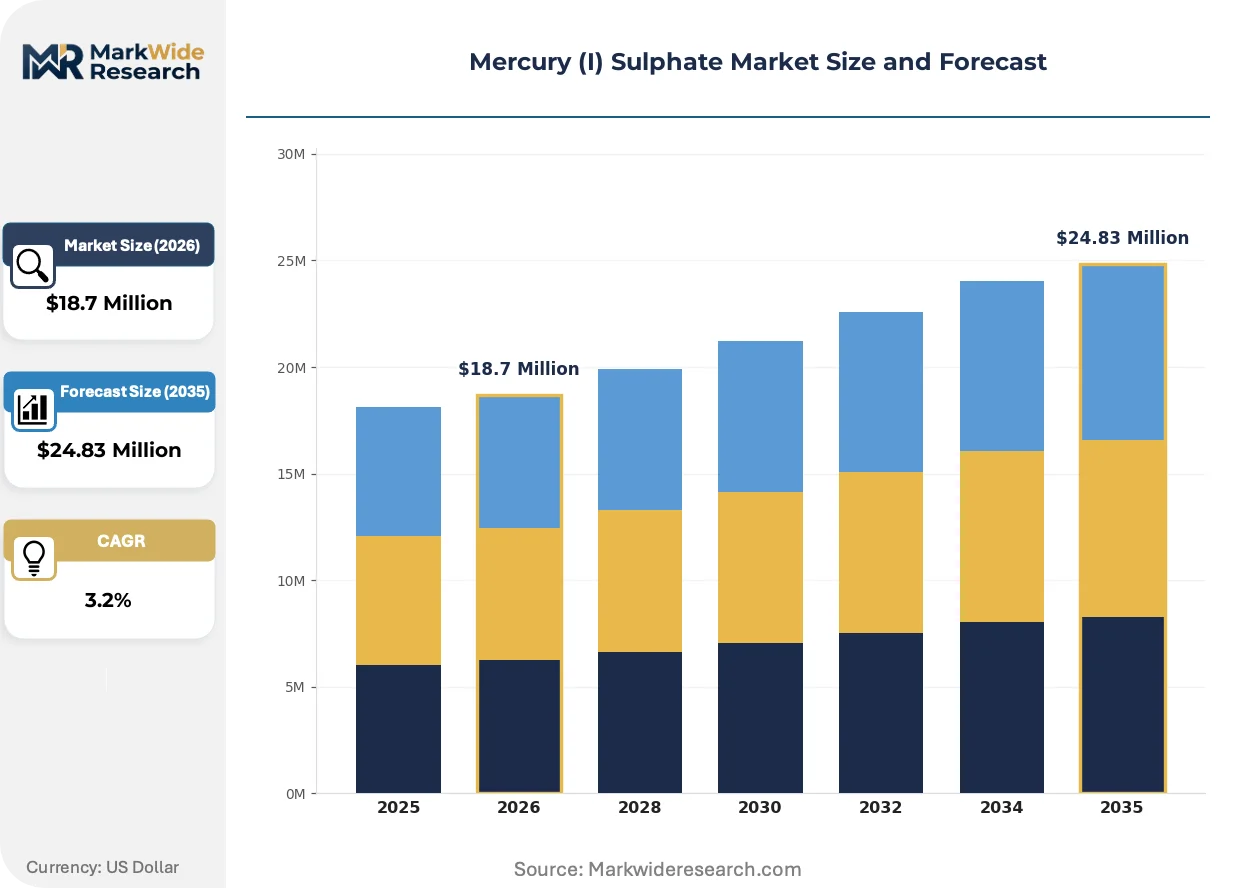
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $24.83 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Laboratory Grade, Specialty Grade Usage Type: Catalyst, Reagent, Additive, Intermediate Packaging Type: Bags, Drums, Bottles, Containers Distribution Channel: Direct Sales, Wholesale, Online Retail, Distributors |
| Companies Covered | AK Scientific Inc, Chemical Technology Ltd, Yogi Dye Chem Industries, Shanghai Zhihua ChemTech Inc., Alfa Chemistry, Cfm Oskar Tropitzsch GmbH, Sigma-Aldrich, Merck KGaA, Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mercury (I) Sulphate Market Strategic Shifts
Mercury (I) sulphate applications are fragmenting between legacy electrochemical uses and precision metrology niches, with innovation concentrating on containment technologies and alternative reference systems that preserve measurement accuracy while reducing exposure risk.
Mercury (I) sulphate serves as the definitive reference standard for chloride-free potentiometric measurements in analytical chemistry. Research institutions and pharmaceutical quality control laboratories in Germany and Switzerland continue specifying this compound for high-precision calibration protocols. The technology is migrating from open-cell liquid junction designs toward encapsulated microelectrode formats that minimize handling exposure while preserving electrochemical stability.
REACH authorization reviews for mercury substances are tightening substance dossier requirements and accelerating sunset date evaluations. ECHA's systematic assessment of mercury compound essential uses is forcing reauthorization investments from remaining suppliers. Laboratory-grade handlers with grandfathered registrations are consolidating market position while industrial-grade suppliers face progressive exclusion from the authorized supplier list.
Certificate-of-analysis requirements are hardening procurement specifications across regulated industries. Pharmaceutical manufacturers and contract testing laboratories now mandate full chain-of-custody documentation and batch-specific purity certifications. German distributors with integrated analytical capabilities are displacing commodity chemical traders by bundling certification services with material supply.
Mercury (I) Sulphate Market Segmentation
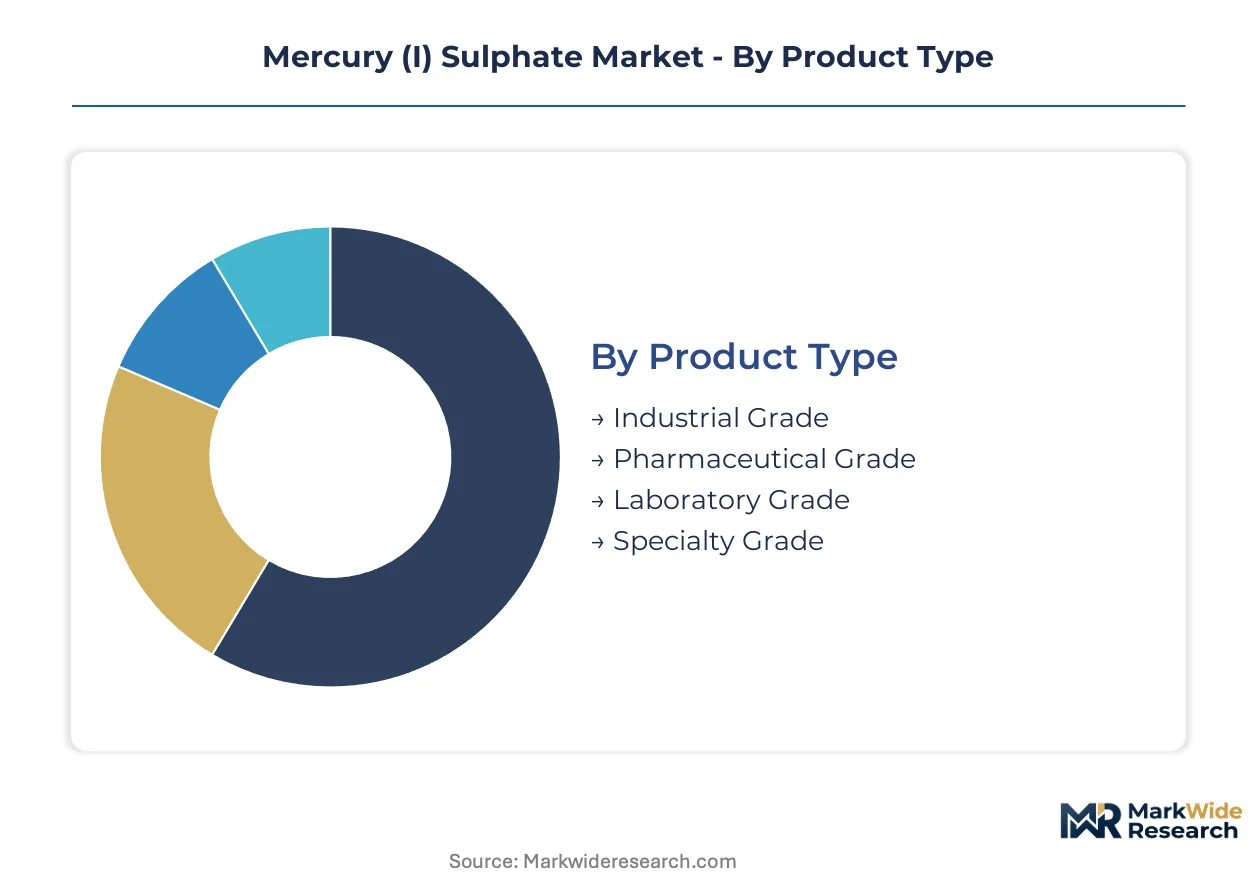
Mercury (I) sulphate procurement patterns diverge sharply across certification tiers, with laboratory and pharmaceutical grades commanding intensive technical support while industrial volumes flow through commodity channels. Understanding these segment boundaries clarifies where margin capture concentrates versus where price competition dominates.
Product Type:
After-sales service intensity escalates dramatically from industrial bulk shipments through to laboratory-grade certification support, creating distinct commercial models within each tier.
- Laboratory Grade:This segment demands batch-specific certificates of analysis and chain-of-custody documentation for metrology applications. German and Swiss analytical institutes anchor consumption, with procurement contingent on full REACH dossier availability from registered handlers.
- Pharmaceutical Grade:USP and EP monograph compliance opens access to quality control laboratories in regulated drug manufacturing, commanding substantial premia over industrial grades. Certification maintenance requires ongoing stability testing and regulatory file updates.
- Industrial Grade:Volume demand from electrochemical manufacturing prioritizes consistent specification over documentation depth.
- Specialty Grade:Custom synthesis for non-standard purity specifications serves isotope ratio mass spectrometry calibration.
Laboratory grade holds the largest share; momentum sits with pharmaceutical grade as drug manufacturing quality control requirements tighten.
Usage Type:
Application maturity varies from declining catalyst volumes through expanding reagent demand, reshaping supplier portfolio priorities.
- Reagent:Chloride-free reference electrode protocols in analytical chemistry laboratories sustain steady consumption. Metrology institutes in Germany specify this compound for high-precision calibration, with encapsulated microelectrode formats reducing handling exposure while preserving electrochemical stability.
- Catalyst:Liquid mercury systems face displacement by solid-state alternatives in environmental monitoring, compressing addressable volume for legacy suppliers.
- Additive:Minor applications in specialty electrochemical cell formulations.
- Intermediate:Downstream processing into other mercury compounds for niche industrial processes.
Reagent applications hold the largest share; catalyst usage is contracting most rapidly as substitution accelerates.
Packaging Type:
Containment specifications scale with hazard classification, with premium packaging formats required for laboratory and pharmaceutical shipments.
- Bottles:Laboratory-grade material ships in amber glass with tamper-evident seals and desiccant integration. German distributors bundle certification services with unit-dose packaging for precision instrument calibration laboratories.
- Drums:Industrial-grade bulk shipments to battery material labs require UN-certified containment and closed-loop return logistics.
- Bags:Lower-volume industrial applications with reduced containment specifications.
- Containers:Intermediate volumes for specialty synthesis operations.
Drum packaging holds the largest share; bottle formats are expanding most quickly as laboratory demand concentrates.
Distribution Channel:
Channel selection reflects buyer sophistication, with certified handlers displacing commodity traders in regulated segments.
- Distributors:German specialty chemical distributors with integrated analytical capabilities serve precision instrument calibration laboratories. These intermediaries bundle REACH-compliant documentation, waste recovery programs, and technical consultation.
- Direct Sales:Large electrochemical cell manufacturers negotiate closed-loop service contracts directly with registered producers.
- Wholesale:Industrial-grade volume transactions with reduced service attachment.
- Online Retail:Limited to small-quantity reagent purchases for research institutions with established supplier relationships.
Distributor channels hold the largest share; direct sales are gaining share fastest as battery R&D procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision instrument calibration laboratories in Germany and Switzerland anchor laboratory-grade procurement, while battery R&D programs in China and electrochemical manufacturing clusters in the United States concentrate industrial-grade demand. REACH-compliant handlers with closed-loop recovery capabilities command premium positioning across European supply chains.
Germany
Metrology institutes in Berlin and Düsseldorf sustain steady consumption of laboratory-grade mercury (I) sulphate for chloride-free reference electrode protocols. ECHA enforces REACH authorization requirements that eliminate unregistered competitors from the supplier base. Specialty chemical distributors in the Rhine-Ruhr region bundle certification services with waste recovery programs for captive laboratory relationships.
Switzerland
Pharmaceutical quality control laboratories in Basel specify this compound for high-precision calibration under stringent documentation requirements. Swissmedic maintains pharmaceutical-grade certification standards that exceed baseline EU regulatory thresholds. The Basel-Land industrial cluster concentrates demand from contract testing laboratories serving multinational drug manufacturers.
United States
Electrochemical cell manufacturers in the Boston and San Francisco corridors require mercury (I) sulphate for half-cell testing of novel cathode formulations. The EPA regulates mercury compound emissions under the Resource Conservation and Recovery Act, compelling handlers to maintain closed-loop recovery systems. Battery materials R&D programs in the Pacific Northwest generate concentrated procurement from solid-state electrolyte research initiatives.
China
Shanghai Zhihua ChemTech Inc. and competing bulk manufacturers serve industrial-scale orders from Asian battery material laboratories. The Ministry of Ecology and Environment monitors mercury waste disposal through state-level hazardous substance management rules. The Yangtze River Delta manufacturing belt concentrates production capacity for electrochemical testing reagents.
India
Yogi Dye Chem Industries addresses regional demand from specialty chemical distributors serving precision instrument calibration requirements. The Central Pollution Control Board monitors mercury waste disposal through state-level hazardous waste management rules. Gujarat's chemical manufacturing corridor hosts handlers navigating compliance investments against shrinking addressable markets.
Mercury (I) Sulphate Market Competitive Environment
Channel-controlling players compete with product-specialist players across a bifurcated supplier base shaped by regulatory authorization bottlenecks. REACH-registered handlers with grandfathered dossiers consolidate position in laboratory-grade segments, while scale-driven manufacturers anchor industrial bulk transactions. Three archetypes dominate: analytical standards portfolio holders, custom synthesis specialists, and bulk commodity producers. Competitive moves concentrate on certification maintenance investments and closed-loop service contract expansion.
Among European-registered analytical suppliers, Merck KGaA and Alfa Chemistry exemplify divergent strategic positioning within the compliance-intensive tier. Merck KGaA occupies a position representing the analytical standards portfolio archetype, leveraging integrated capabilities to serve precision instrument calibration laboratories. Alfa Chemistry sits within the custom synthesis specialization archetype, addressing research institutions requiring non-standard purity specifications. Shanghai Zhihua ChemTech Inc. anchors the scale-driven manufacturing end, competing on production volume for industrial-grade electrochemical applications.
| Leading Market Players |
|---|
| AK Scientific Inc |
| Chemical Technology Ltd |
| Yogi Dye Chem Industries |
| Shanghai Zhihua ChemTech Inc. |
| Alfa Chemistry |
| Cfm Oskar Tropitzsch GmbH |
| Sigma-Aldrich |
| Merck KGaA |
| Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Ruhr logistics corridor connects primary mercury processing in Kyrgyzstan and Algeria to European laboratory markets, with freight cost volatility amplifying margin compression at the industrial-grade tier while reinforcing premium capture among REACH-registered handlers serving German metrology institutes.
Pricing Analysis
Cost-plus contracts indexed to primary mercury spot quotations dominate industrial-grade transactions, with laboratory and pharmaceutical grades commanding fixed-price premia tied to USP and EP certification maintenance. Price differentiation separates pharmaceutical-grade monograph compliance from industrial bulk shipments, with certification depth and chain-of-custody documentation as primary tiering mechanisms. Cost compression in industrial-grade material intensifies because Shanghai Zhihua ChemTech Inc. and competing Asian producers compete on manufacturing scale. Electrochemical cell manufacturers exhibit highest price sensitivity, while Swiss pharmaceutical quality control laboratories demonstrate inelastic demand for certified reference materials.
Supply Chain Analysis
Primary mercury feedstock concentrates in Kyrgyzstan and Algeria, with secondary refining and compound synthesis anchored in Germany and China. Mercury (I) sulphate production draws from elemental mercury inputs, sulphuric acid, and specialized containment materials for hazardous chemical handling. Single-source vulnerability in primary mercury supply exposes processors to export quota disruption and geopolitical friction. Distribution runs through REACH-registered specialty chemical distributors in Europe and direct sales contracts for Asian battery material laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated electrochemical cell manufacturers and pharmaceutical quality control laboratories, with procurement consolidation among battery R&D programs and metrology institutes reducing supplier leverage.
For Market Incumbents: Harden closed-loop service contract penetration to lock in captive laboratory relationships before silver-silver chloride substitution accelerates in environmental monitoring. Deepen backward integration into primary mercury recovery to offset feedstock volatility from Kyrgyzstani supply concentration. Prioritize ECHA reauthorization investments to maintain grandfathered positioning against sunset date exclusions. For New Entrants and Emerging Players: Pursue custom synthesis specialization for isotope ratio mass spectrometry calibration, where non-standard purity specifications face limited competition. Target pharmaceutical-grade certification gaps in Indian and Southeast Asian quality control laboratories. Deploy bundled certification-and-logistics service models to differentiate from commodity traders lacking analytical capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized mercury compound handling infrastructure and dormant REACH registrations. Long-term viability hinges on regulatory authorization durability rather than volume growth, given progressive substitution in catalyst applications. Watch ECHA essential-use review timelines as the critical inflection signal for authorization renewal risk.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Reauthorization Investment | ECHA dossier maintenance preserves market access against sunset date exclusions for grandfathered handlers. |
| Closed-Loop Recovery Program Expansion | EPA RCRA-compliant waste return contracts generate recurring revenue from captive pharmaceutical laboratories. |
| Pharmaceutical-Grade Certification Pathway | USP and EP monograph compliance opens quality control demand from Basel drug manufacturing clusters. |
| Custom Synthesis Capability Buildout | Non-standard purity specifications for NMR calibration address underserved niches with limited competition. |
| Direct Sales Channel Development | Battery R&D procurement consolidation favors closed-loop service contracts with electrochemical cell manufacturers. |
Study Parameters
A spread of perspectives from plant managers at mercury compound processors, procurement leads at electrochemical cell manufacturers, distribution channel partners in German specialty chemical networks, and technical R&D directors at analytical standards suppliers converged on the working assumptions. These primary insights combined with secondary validation from ECHA authorization databases, EPA RCRA compliance filings, customs and trade flow data, and SEC disclosures from diversified chemical conglomerates. Bottom-up volume builds across grade tiers and usage types triangulated against top-down market sizing from industry association reports.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning laboratory-pharmaceutical-industrial-specialty grade tiers, reagent-catalyst-additive-intermediate usage types, and bottle-drum-bag-container packaging formats. CAGRs derived from regression analysis against historical authorization timelines and substitution elasticity parameters. Forecast inputs incorporated ECHA sunset date probability assessments and solid-state electrode technology maturity curves.
Sensitivities concentrate around ECHA essential-use review outcomes, primary mercury export quota adjustments, and silver-silver chloride substitution rates in environmental monitoring applications. Forecasts reflect documented assumptions regarding regulatory authorization durability and feedstock supply continuity. Cross-checking against ECHA's published authorization list and EPA RCRA handler registrations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Europe Biguanide Market
Chemicals
Acetophenone Market
Chemicals
Ethyl Chloride Market
Chemicals
Global Methylene Chloride Market
Chemicals
Ruthenium Tetroxide Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Precious Metal Plating Chemicals Market
Chemicals
Ferric Fluoride Market
Chemicals
Hydrophobing Agents Market
Chemicals
Inorganic Chemicals Market
Chemicals
Chromium Trioxide Market
Chemicals
Triethanolamine Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Lauryl Myristyl Alcohol Market