
 Sulfate Free Body Wash Market | 2026-2036
Sulfate Free Body Wash Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfate Free Body Wash Market Analytics
The capital-intensity divergence between contract manufacturers and in-house formulators is reorganizing competitive tiers in sulfate-free body wash production. Formula Corp leverages its private-label infrastructure to serve mid-market retailers across North America. RainShadow Labs anchors its position through small-batch botanical extraction capabilities that appeal to artisanal brands. Xiran Skincare differentiates via integrated R&D labs focused on fermented surfactant technologies.
Sulfate-free body wash denotes a cleansing formulation that excludes sodium lauryl sulfate and sodium laureth sulfate, typically substituting coconut-derived glucosides or amino acid-based surfactants that maintain a skin-friendly pH between 5.0 and 6.5. These products serve consumers with compromised skin barriers, allergy sensitivities, or preference for milder cleansing chemistry. Gel formats dominate volume through dispenser-compatible viscosity and transparent aesthetic appeal, while botanical formulations command premium positioning as ingredient transparency becomes a purchase determinant. Refill pouches represent the fastest-expanding packaging segment as retailers impose single-use plastic reduction mandates.
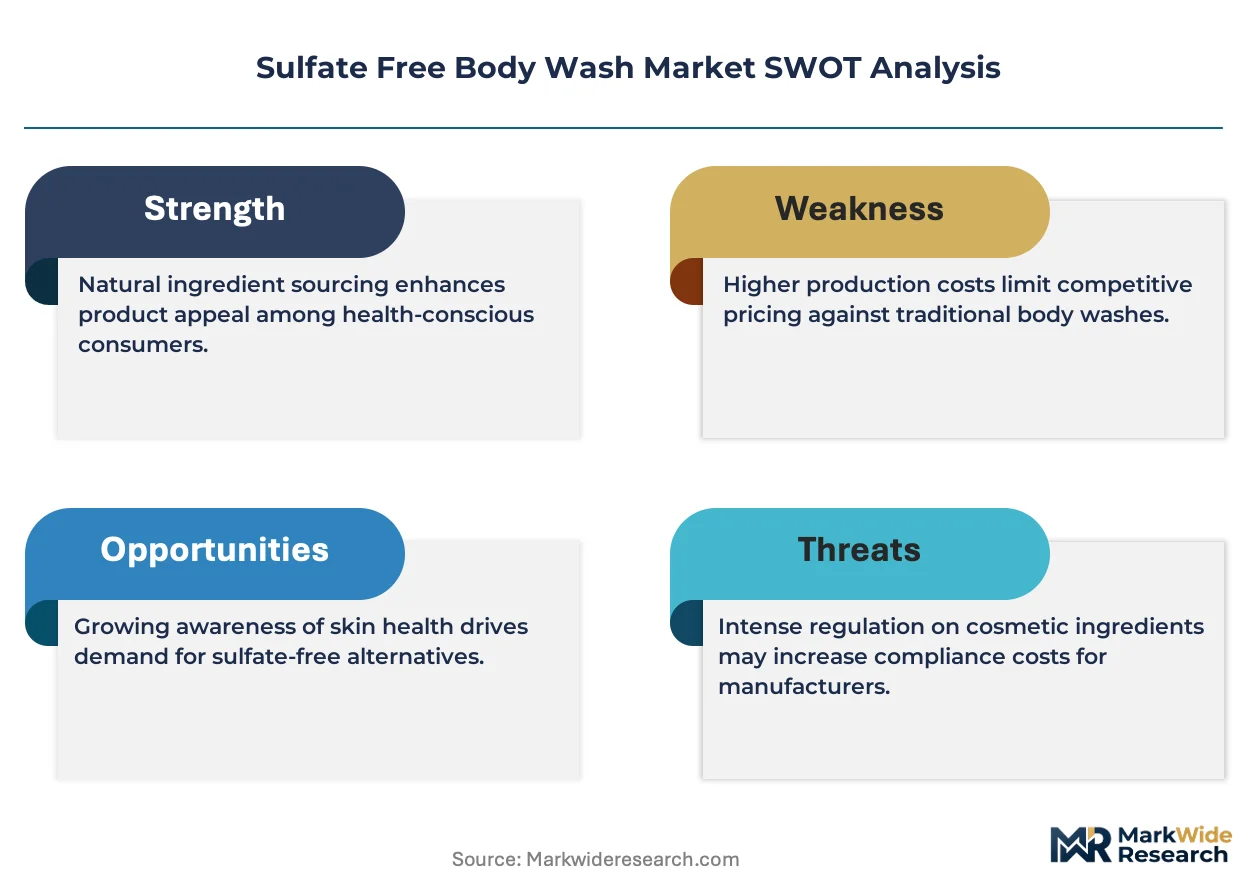
FDA cosmetic labeling requirements and EU REACH annex restrictions on ethoxylated surfactants compel reformulation investments, while ECHA hazard classifications for traditional sulfates accelerate ingredient substitution timelines. The EU Green Deal chemical sustainability targets further tighten acceptable surfactant profiles, pushing manufacturers toward bio-based feedstocks. Stakeholders must monitor evolving microbiome-friendly certification standards and decide whether to pursue third-party dermatological validation ahead of anticipated regulatory harmonization.
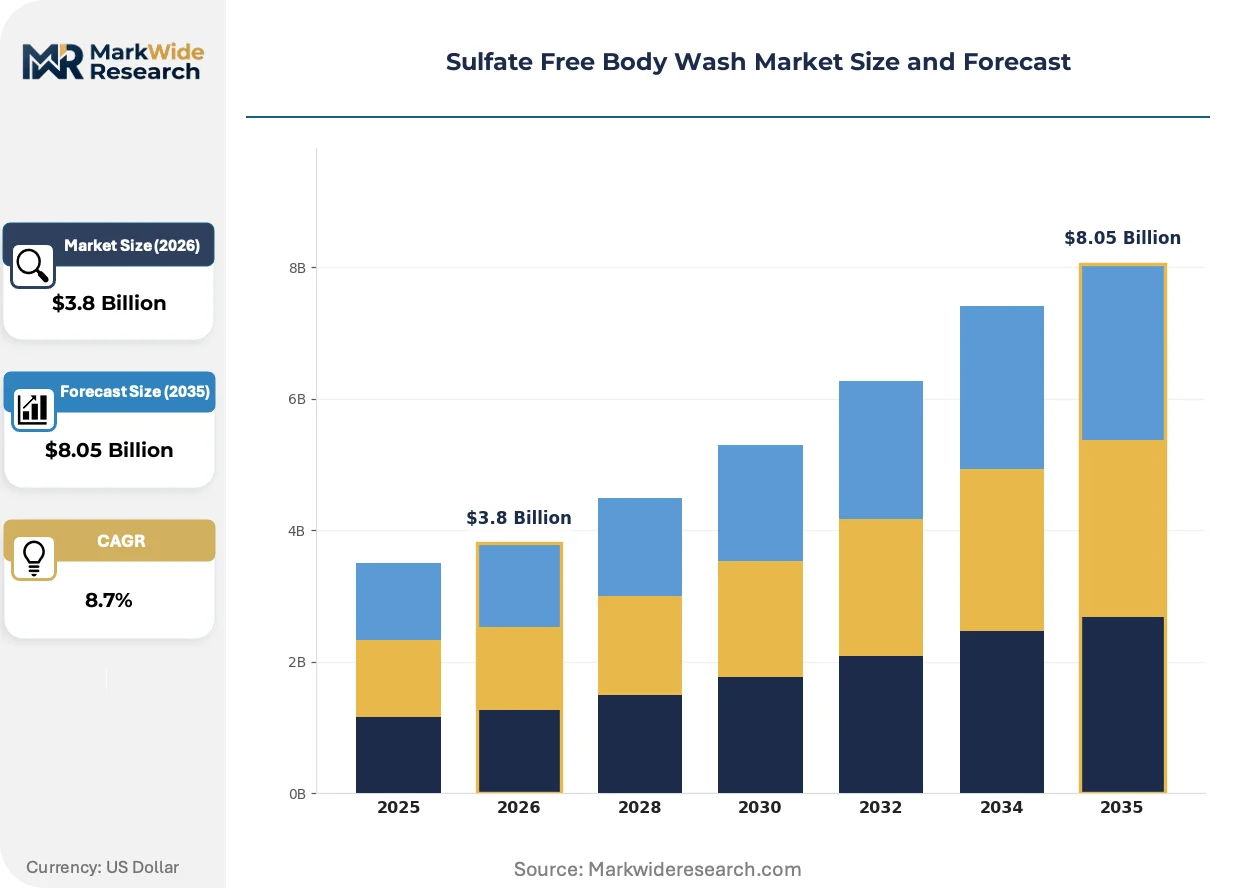
Market Dynamics
EU REACH annex restrictions on ethoxylated surfactants are forcing manufacturers to rebuild supply chains around plant-derived glucosides and fermented amino acid alternatives. This regulatory compression is accelerating R&D timelines while fragmenting the supplier base between legacy petrochemical surfactant producers and emerging bio-based specialists.
Growth Catalysts
- Dermatology Clinic Prescription Patterns:Clinicians in Germany and the United States increasingly prescribe mild cleansers for eczema and rosacea patients, creating institutional demand pull that bypasses traditional retail marketing.
- EU Green Deal Chemical Sustainability Targets:The framework's tightening surfactant profiles push manufacturers toward bio-based feedstocks, advantaging early movers with certified supply chains.
- Refill Pouch Mandates:Retailer-imposed single-use plastic reduction requirements in France and the United Kingdom are converting fixed-format buyers to flexible packaging systems.
Market Restraints
- Coconut-Derived Glucoside Supply Concentration:Southeast Asian plantation capacity constraints create input volatility for formulators dependent on lauryl glucoside and decyl glucoside.
- Fermented Surfactant Scale-Up Costs:Bioreactor capacity limitations and batch consistency challenges inflate per-unit production costs versus petrochemical alternatives.
- ECHA Hazard Reclassifications:Ongoing reviews of traditional sulfate surfactants create formulation uncertainty as manufacturers await final annex listings.
Strategic Opportunities
- Microbiome-Friendly Certification Standards:Third-party dermatological validation programs in development across Germany and Switzerland offer first-mover positioning ahead of anticipated regulatory harmonization.
- Medical Spa Channel Expansion:Post-treatment skincare protocols in clinical wellness settings represent underpenetrated institutional demand for pH-balanced cleansers.
- Botanical Extraction Convergence:Integration of supercritical CO2 extraction with small-batch surfactant production enables terroir-positioned artisanal brands.
Industry Challenges
- Fermentation Process Engineering Talent:Scarcity of bioprocess engineers with surfactant-specific expertise constrains scale-up timelines for bio-based alternatives.
- Cross-Border Formulation Registration:Divergent FDA cosmetic labeling requirements and EU REACH compliance timelines force parallel submission strategies that extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfate Free Body Wash Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Cream, Foam, Liquid Formulation Type: Organic, Natural, Botanical, Synthetic Packaging Type: Tube, Bottle, Jar, Refill Pouch Target Audience: Men, Women, Teens, Sensitive Skin |
| Companies Covered | Formula Corp, Xiran Skincare, Pravada Private Label, TY Cosmetic, Bo International, RainShadow Labs, Global Cosmetis, Biocrown, Botanie Soap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfate Free Body Wash Market Evolving Landscape
Fermented surfactant technologies are compressing the performance gap between bio-based and petrochemical cleansers. Formulators now pursue integrated R&D pipelines that combine upstream fermentation with downstream formulation science.
Amino acid-based surfactants derived from glutamic acid and sarcosine are supplanting coconut glucosides in premium positioning tiers. Dermatology clinics in Hamburg and Zürich specify these chemistries for barrier-compromised patients. The shift is enabling price stratification that separates clinical-grade formulations from mass-market alternatives.
EU REACH annex restrictions on ethoxylated surfactants are compelling manufacturers to eliminate polyethylene glycol derivatives from rinse-off products. German formulators in Düsseldorf chemistry clusters lead substitution efforts with alkyl polyglucoside systems. The regulatory pressure is compressing formulation cycles from thirty-six months to eighteen months for European market entry.
Ingredient transparency requirements are converting anonymous bulk procurement to certified-chain purchasing. Clean beauty retailers in California and Paris now require batch-level documentation for surfactant origins. This verification burden falls most heavily on contract manufacturers serving private-label clients across North America.
Sulfate Free Body Wash Market Segmentation
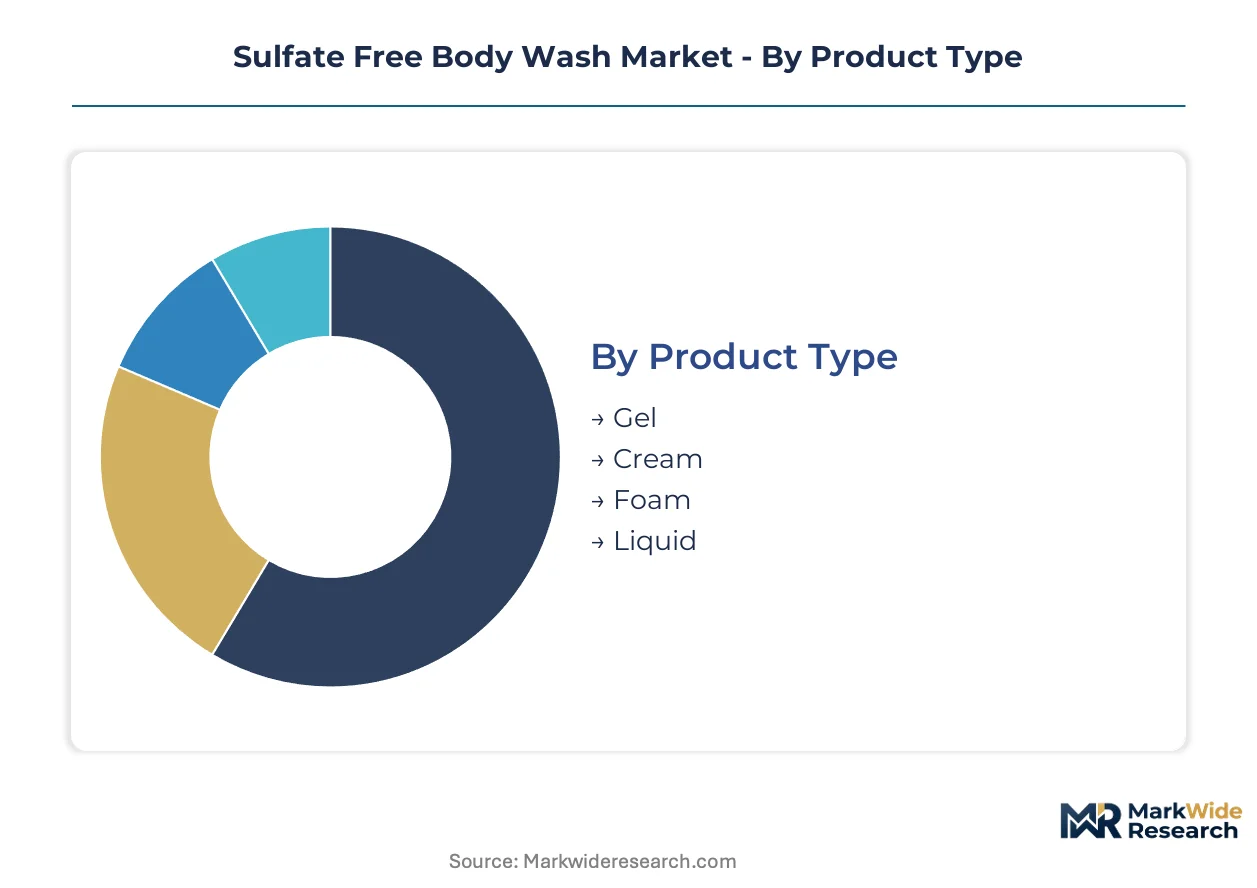
Sulfate-free body wash segmentation reveals how formulation chemistry and packaging innovation create distinct margin architectures. Manufacturers optimize across these dimensions to capture premium positioning while meeting divergent regulatory and retail requirements.
Product Type:
Margin pools concentrate in formats that balance manufacturing simplicity with dispenser compatibility and visual differentiation at shelf.
- Gel:Transparent aqueous formulations with carbomer-thickened viscosity between 5,000 and 15,000 cP. Demand concentrates in Germany and the United States through mass-market retail dispensers, driven by consumer preference for visible purity indicators and pump-compatible flow characteristics.
- Cream:Oil-in-water emulsions incorporating cationic conditioning polymers for post-wash skin feel. Medical spas in Hamburg and Zürich specify these formats for post-procedure protocols, where barrier-supporting lipids command institutional procurement premiums.
- Foam:Dilute surfactant solutions packaged with mechanical or propellant-driven dispensers. Asian markets favor this format for sensorial density and water-scarcity washing efficiency.
- Liquid:Low-viscosity pourable formulations with minimal thickener loading. Economy-tier positioning and refill-pouch compatibility drive volume concentration in French and UK supermarket private labels.
The dominant share belongs to Gel, while Refill Pouch compatibility is converting Liquid formats fastest in regulated packaging markets.
Formulation Type:
Certification tiering separates clinical-grade positioning from mass-market alternatives, with fermentation-derived actives commanding the steepest price premiums.
- Organic:Formulations certified to USDA NOP or EU Organic standards with minimum 95% organic content excluding water and salt. Supply chains anchor in German green chemistry clusters where bio-based feedstock verification meets retailer documentation requirements.
- Natural:Plant-derived surfactant systems without synthetic petrochemical inputs, though lacking formal organic certification. California clean beauty retailers and Parisian concept stores drive demand through ingredient transparency mandates.
- Botanical:Supercritical CO2 extracts and cold-pressed oils positioned for terroir storytelling. Small-batch production in RainShadow Labs-style facilities serves artisanal brand portfolios.
- Synthetic:Amino acid-based surfactants produced through fermentation or petrochemical routes. Dermatology clinics specify these chemistries for eczema and rosacea patients where batch consistency outweighs origin claims.
Organic certification captures the highest per-unit margins, though Synthetic formulations are expanding most quickly through institutional prescription channels.
Packaging Type:
Regulatory pressure on single-use plastics is restructuring procurement patterns, with flexible formats gaining share fastest in jurisdictions with mandated reduction timelines.
- Tube:Laminated aluminum-plastic multilayer constructions with flip-top or screw-cap closures. Standard for travel-size and premium positioning tiers across North American specialty retail.
- Bottle:PET or HDPE rigid containers with pump or disc-top dispensers. Dominates volume through familiarity and shelf stability, though facing displacement pressure in EU markets.
- Jar:Wide-mouth PET or glass containers for cream and balm formats. Medical spa and clinical channels favor this packaging for controlled dispensing in treatment room settings.
- Refill Pouch:Flexible multilayer films with spout fitments for at-home decanting. French and UK retailer mandates are accelerating adoption fastest among sustainability-positioned brands.
Bottle retains volume leadership, yet Refill Pouch is climbing the fastest as regulatory deadlines approach in major European markets.
Target Audience:
Demographic specialization enables price stratification, with clinical need-state segmentation outpacing gender-based targeting in margin contribution.
- Men:pH-balanced formulations with masculine-coded fragrance profiles and minimalist packaging aesthetics. German and US mass-market retailers dedicate expanding shelf space to this segment.
- Women:Broadest formulation variety spanning premium botanical to clinical synthetic positioning. Represents the historical revenue base now facing fragmentation into need-state subsegments.
- Teens:Acne-safe, non-comedogenic surfactant systems with social media-compatible visual branding. Influencer-driven discovery channels concentrate demand in UK and US digital-native retail.
- Sensitive Skin:pH 5.0-5.5 formulations with minimal ingredient lists and dermatological validation. Clinician prescription in German dermatology clinics creates institutional demand pull unmatched by marketing expenditure.
Women's formulations hold the dominant revenue position, though Sensitive Skin targeting is gaining share fastest through medical channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German buyers accept steep premiums for certified organic formulations, while French supermarket private labels compete aggressively on per-liter cost through refill pouch systems.
Germany
Dermatology clinics in Hamburg and Zürich prescribe pH-balanced cleansers for eczema and rosacea patients, creating institutional demand that bypasses retail marketing. EU REACH annex restrictions on ethoxylated surfactants force manufacturers toward alkyl polyglucoside systems. Green chemistry clusters in Hamburg and Düsseldorf drive innovation in plant-derived surfactant alternatives, compressing formulation cycles from thirty-six to eighteen months.
United States
Clean beauty retailers in California mandate batch-level documentation for surfactant origins, converting anonymous bulk procurement to certified-chain purchasing. FDA cosmetic labeling requirements compel parallel submission strategies alongside EU compliance. Mid-market retailers across North America rely on contract manufacturers with private-label infrastructure to serve price-sensitive segments.
France
Retailer-imposed single-use plastic reduction mandates accelerate refill pouch adoption fastest among sustainability-positioned brands. EU Green Deal chemical sustainability targets tighten acceptable surfactant profiles, pushing manufacturers toward bio-based feedstocks. Parisian concept stores drive demand for ingredient transparency through natural formulation positioning.
United Kingdom
Supermarket private labels concentrate volume in low-viscosity liquid formats compatible with flexible packaging systems. ECHA hazard reclassifications of traditional sulfates create formulation uncertainty as manufacturers await final annex listings. Digital-native retail channels concentrate teen segment demand through influencer-driven discovery.
Switzerland
Third-party dermatological validation programs in development across Germany and Switzerland offer first-mover positioning ahead of anticipated regulatory harmonization. Medical spas in Zürich specify cream formats for post-procedure protocols where barrier-supporting lipids command institutional procurement premiums. Swissmedic oversight maintains stringent quality thresholds for clinical-grade formulations.
Sulfate Free Body Wash Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence reorganizing competitive tiers in sulfate-free body wash production. The upper tier combines fermentation capabilities with downstream formulation science, while mid-market players leverage private-label infrastructure for scale. Three archetypes dominate: integrated R&D laboratories, small-batch botanical extractors, and contract manufacturers serving retailer private labels. Capacity expansion and portfolio diversification represent the dominant competitive moves as regulatory compression accelerates R&D timelines.
Within the integrated R&D tier, Xiran Skincare exemplifies players pursuing fermented surfactant technologies through captive laboratory infrastructure. RainShadow Labs occupies a position among small-batch botanical specialists, appealing to artisanal brands through supercritical CO2 extraction capabilities. Formula Corp anchors the contract manufacturing segment, leveraging private-label infrastructure to serve mid-market retailers across North America. These three represent distinct strategic postures rather than direct competitors, each capturing margin pools through different combinations of scale, specialization, and vertical control.
| Leading Market Players |
|---|
| Formula Corp |
| Xiran Skincare |
| Pravada Private Label |
| TY Cosmetic |
| Bo International |
| RainShadow Labs |
| Global Cosmetis |
| Biocrown |
| Botanie Soap |
| Others |
Value Network & Pricing Analysis
Coconut glucoside substitution for ethoxylated surfactants simultaneously relocates procurement geography toward Southeast Asian plantations and compresses margin structures for European formulators facing EU REACH compliance deadlines. This input shift rewards manufacturers with long-term lauryl glucoside contracts while exposing spot-market buyers to plantation capacity volatility.
Pricing Analysis
Refill pouch after-sales revenue drives lifetime value as French and UK retailer mandates convert fixed-format buyers to flexible systems. Three-tier pricing structure across premium organic certification, standard natural positioning, and economy private-label tiers separates clinical-grade amino acid formulations from mass-market alternatives. Cost compression in the synthetic surfactant tier intensifies because fermented amino acid scale-up inflates per-unit production expenses. Supermarket private labels in France exhibit highest price sensitivity, while German dermatology clinics accept steep premiums for Swissmedic-validated formulations.
Supply Chain Analysis
Southeast Asian plantation concentration for lauryl glucoside and decyl glucoside feedstocks creates a chokepoint that constrains European formulator flexibility. Supply draws from Indonesian and Malaysian coconut processing clusters, with German green chemistry facilities and North American contract manufacturers anchoring downstream formulation. Single-source vulnerability runs through plantation capacity constraints amid climate-induced yield variability. Distribution runs through specialty retailers in California and Paris, medical spa channels in Hamburg and Zürich, and supermarket private labels across France and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional procurement as dermatology clinic prescription patterns consolidate demand pull for pH-balanced cleansers, fragmenting traditional retail marketing effectiveness.
For Market Incumbents: Shield formulation portfolios against ECHA hazard reclassification uncertainty by accelerating alkyl polyglucoside substitution ahead of final annex listings. Deepen backward integration into certified coconut glucoside supply through long-term Southeast Asian plantation partnerships, securing input priority over spot-market competitors.
For New Entrants and Emerging Players: Lead with microbiome-friendly certification programs in development across Germany and Switzerland, capturing first-mover positioning before regulatory harmonization closes the window. Medical spa channel expansion in Zürich and Hamburg represents the most penetrable institutional segment, accessible through clinician education partnerships rather than retail slotting fees.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed contract manufacturers serving North American private-label retailers, where portfolio diversification into fermented surfactant capabilities would extend holding value. Fermentation process engineering talent scarcity signals long-term viability for bio-based specialists with captive bioprocess expertise. Watch ECHA final annex listings as the inflection indicator that would accelerate ingredient substitution timelines and reward early movers.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Bioreactor investment compresses per-unit costs for amino acid surfactants versus petrochemical alternatives. |
| Refill Pouch Manufacturing Transition | Flexible packaging lines capture French and UK retailer mandates ahead of regulatory deadlines. |
| Microbiome Certification Program | Third-party dermatological validation differentiates clinical-grade positioning in German prescription channels. |
| Plantation Supply Agreement | Long-term coconut glucoside contracts insulate against Southeast Asian capacity volatility. |
| Medical Spa Channel Partnership | Post-procedure protocol integration builds institutional demand pull unmatched by retail marketing expenditure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the sulfate-free body wash value chain, including brand managers at clean beauty retailers, category buyers at French and UK supermarkets, formulation chemists at German green chemistry clusters, procurement leads at contract manufacturers, and clinicians at Hamburg dermatology clinics. Secondary validation drew from EU REACH annex documentation, ECHA hazard classification databases, FDA cosmetic labeling guidance, and customs records tracking coconut-derived surfactant trade flows. Bottom-up volume modeling triangulated against top-down value estimates across product type, formulation chemistry, packaging format, and target audience segments.
Across the analysis window, the analytical framework modeled volume and value outputs through segmented demand projection and supply-side capacity assessment. Segmentation dimensions included gel-cream-foam-liquid formats, organic-natural-botanical-synthetic certification tiers, tube-bottle-jar-refill pouch packaging types, and men-women-teens-sensitive skin demographics. CAGRs were derived from trend extrapolation adjusted for regulatory compression effects and channel shift dynamics. Forecast inputs incorporated EU Green Deal chemical sustainability targets and refill pouch mandate implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU REACH enforcement or accelerated ECHA reclassification would require recalibration. Forecasts reflect documented assumptions regarding plantation capacity expansion, fermentation scale-up feasibility, and clinician prescription pattern continuity. Practitioners should keep alternative scenarios live as regulatory harmonization and bio-based feedstock availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Polymer Surfactants Market
Surfactants
Emulsifying Wax Market
Surfactants
Sodium Cocoyl Isethionate Market
Surfactants
Specialty Surfactants Market
Surfactants
Global Amphoteric Surfactants Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Micellar Water Market
Surfactants
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Disodium Laureth Sulfosuccinate Market
Surfactants
Global Oilfield Surfactants Market
Surfactants
Cocomonoethanolamide (CMEA) Market
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Sodium Lauroyl Glycinate Market