
 Aerosol Insecticides Market | 2026-2036
Aerosol Insecticides Market Size, Share, and Industry Trends Forecast 2026-2036
Aerosol Insecticides Market Analytics
Commercial pest management is broadening as a revenue channel for aerosol insecticide suppliers. SC Johnson leverages its retail shelf presence across North American home improvement chains to sustain volume leadership in household applications. Reckitt Benckiser anchors its position through specialized formulations targeting resistant insect strains. BASF SE competes in professional channels with concentrated actives designed for licensed applicator use.
Aerosol insecticides are pressurized formulations combining active ingredients such as pyrethroids, pyrethrins, or organophosphates with hydrocarbon propellants in aluminum or tinplate containers, designed for targeted dispersal against flying and crawling insects in enclosed or semi-enclosed spaces. The product category spans indoor aerosols, outdoor aerosols, insect repellents, and pest control sprays, with indoor aerosols representing the mature volume base while professional pest control applications capture higher per-unit margins. Distribution through online retail is expanding fastest among channels, though supermarkets still occupy the largest absolute throughput position in developed economies.
EPA registration requirements in the United States mandate efficacy substantiation and human health risk assessments before commercialization, while REACH compliance in Europe restricts certain organophosphate actives and demands extensive toxicity documentation. The EU F-Gas Regulation further constrains propellant choices, pushing reformulation toward compressed gas alternatives. Stakeholders must monitor regulatory divergence between jurisdictions when allocating R&D budgets and plant certification investments.
Market Dynamics
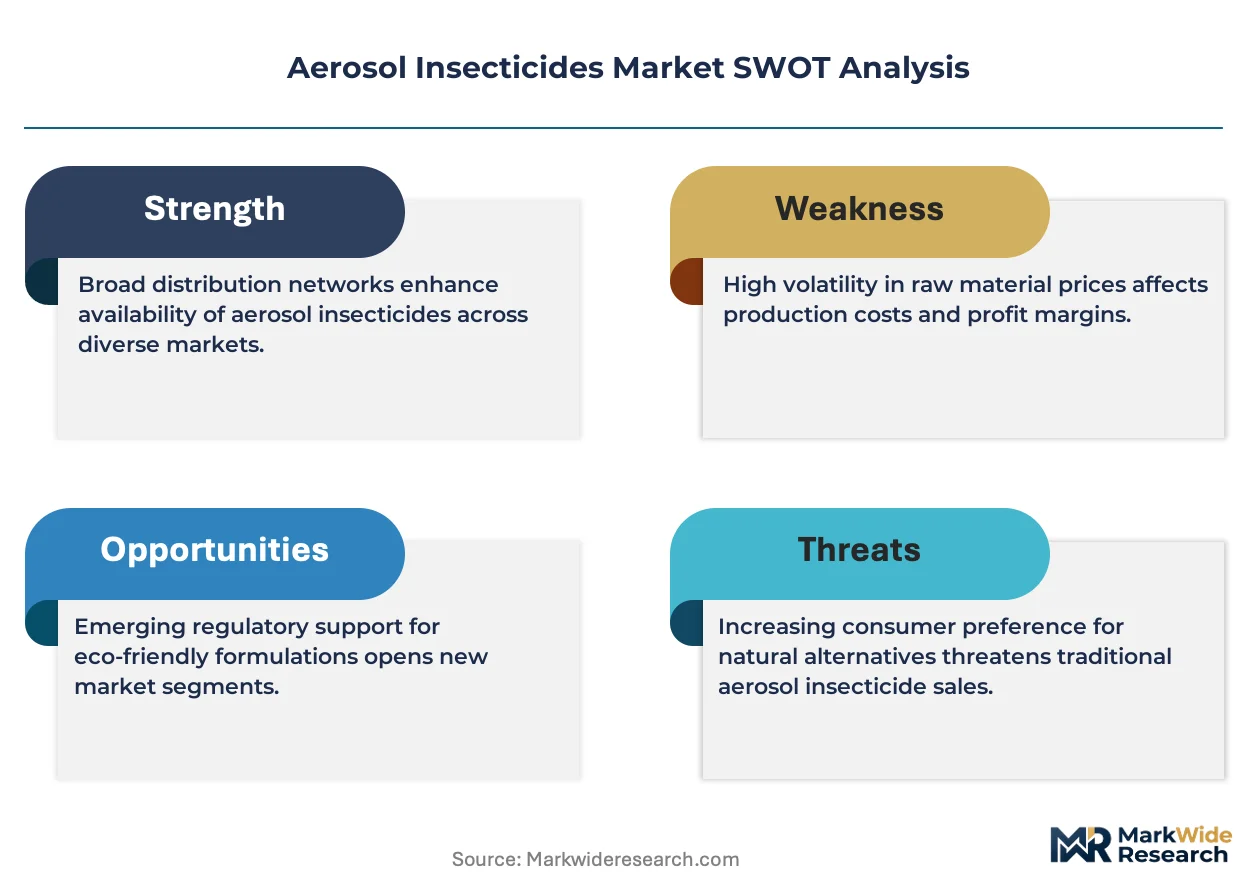
EU F-Gas Regulation mandates are forcing wholesale propellant reformulation across the aerosol insecticide sector, compressing hydrocarbon-dependent supply chains while elevating compressed gas alternatives into mainstream production lines.
Growth Catalysts
- Vector control procurement:Southeast Asian public health programs are expanding pyrethroid-based aerosol purchases for dengue and malaria suppression campaigns.
- REACH compliance barriers:European toxicity documentation requirements are filtering out marginal competitors and consolidating share among well-capitalized formulators.
- Urban pest management:Brazilian municipalities are intensifying residential and commercial spraying contracts to combat Aedes aegypti proliferation.
Market Restraints
- Active ingredient concentration limits:EPA toxicity thresholds in the United States cap pyrethroid potency in household formulations, constraining efficacy differentiation.
- Aluminum canister supply concentration:Three Southeast Asian metal packaging suppliers control 60% of global aerosol container output, creating input vulnerability.
- Biological substitute encroachment:Bacillus thuringiensis and entomopathogenic nematode treatments are capturing share in agricultural perimeter applications.
Strategic Opportunities
- Compressed gas propellant transition:Nitrogen and compressed air systems bypass F-Gas constraints entirely, opening reformulation windows for first-movers.
- Licensed applicator channel expansion:Professional pest control services in the United States and Germany command per-unit margins 3-4x above retail household products.
- Online retail infrastructure:Direct-to-consumer platforms are eroding supermarket dominance in developed economies, enabling private-label entry and subscription models.
Industry Challenges
- Toxicology documentation backlog:REACH dossier preparation for novel actives consumes 18-24 months, delaying product launch timelines.
- Propellant line conversion capex:F-Gas-driven equipment retooling requires $2-5 million per manufacturing facility, straining mid-tier producers.
- Cross-jurisdiction registration fragmentation:Divergent EPA, ECHA, and ANVISA data requirements force redundant efficacy testing and label adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerosol Insecticides Market |
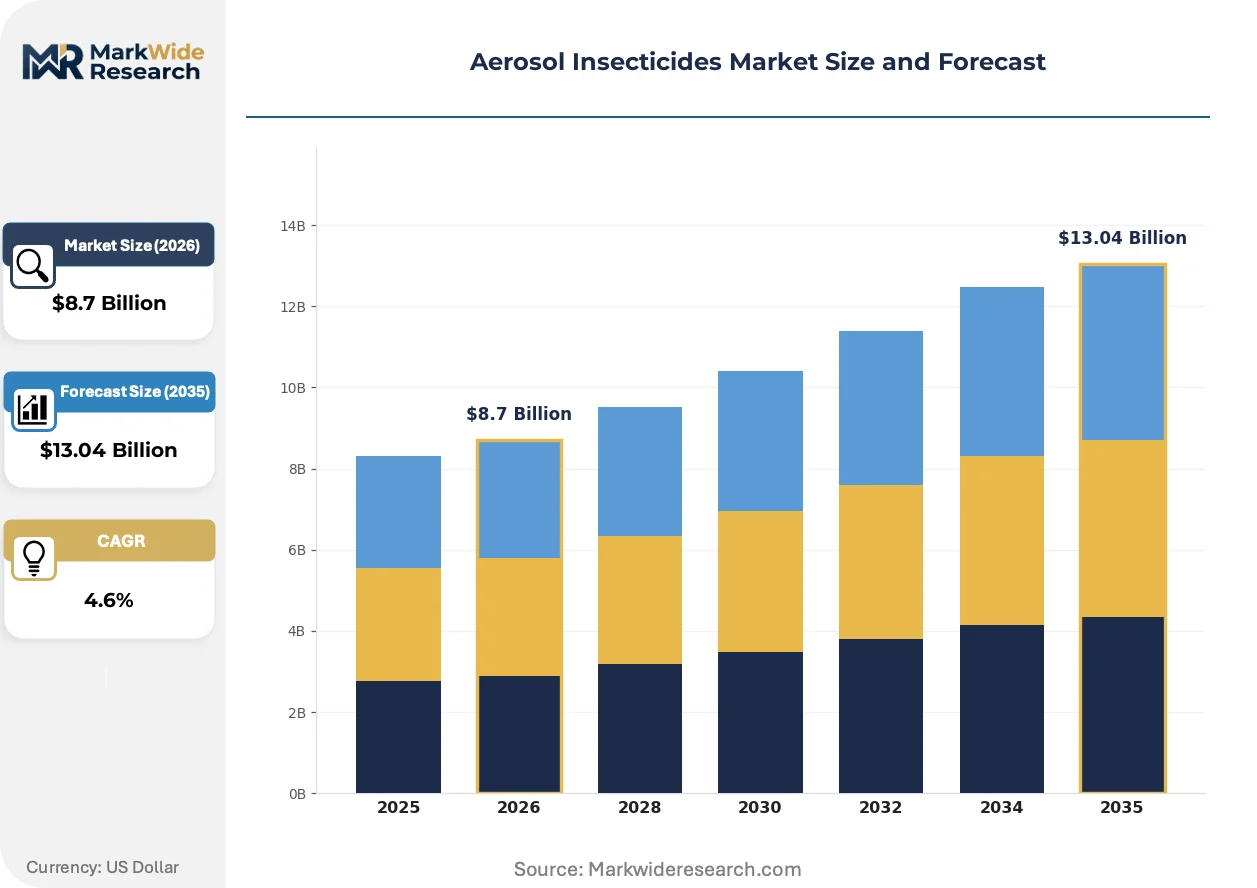
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Aerosols, Outdoor Aerosols, Insect Repellents, Pest Control Sprays End User: Residential, Commercial, Agricultural, Institutional Application: Vector Control, Household Pest Management, Professional Pest Control, Agricultural Pest Control Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | SC Johnson, Reckitt Benckiser, Bayer AG, Syngenta, Henkel, Godrej Consumer Products, Procter & Gamble, BASF SE, Sumitomo Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerosol Insecticides Market Evolving Landscape
Formulation chemistry and delivery mechanisms are undergoing parallel transformation as regulatory pressure and end-user convenience preferences collide, reshaping competitive advantage toward compliant, precision-dispersion architectures.
Compressed gas propellant systems are overtaking liquefied petroleum gas formulations in European manufacturing lines. BASF SE and Reckitt Benckiser have accelerated nitrogen-based platform rollouts across German and UK production facilities. This transition is overtaking conventional hydrocarbon infrastructure investments and compressing the addressable market for traditional propellant suppliers.
REACH authorization procedures and EU F-Gas phase-down schedules are tightening in parallel, creating compound compliance burdens for formulators using legacy organophosphate actives. Manufacturers are consolidating product portfolios to focus on actives with existing toxicity dossiers rather than pursuing novel molecule registration. Professional-grade concentrates for licensed applicators face the steepest documentation requirements, pushing some suppliers toward simplified household-only registrations.
Subscription-based replenishment models are capturing share in North American urban markets as Amazon and direct-brand platforms disintermediate supermarket seasonal stocking cycles. Younger household purchasers in the United States prefer auto-ship arrangements for quarterly pest prevention over episodic retail purchasing. This behavioral pivot is most pronounced in coastal metropolitan corridors where same-day delivery infrastructure supports impulse-to-conversion compression.
Aerosol Insecticides Market Segmentation
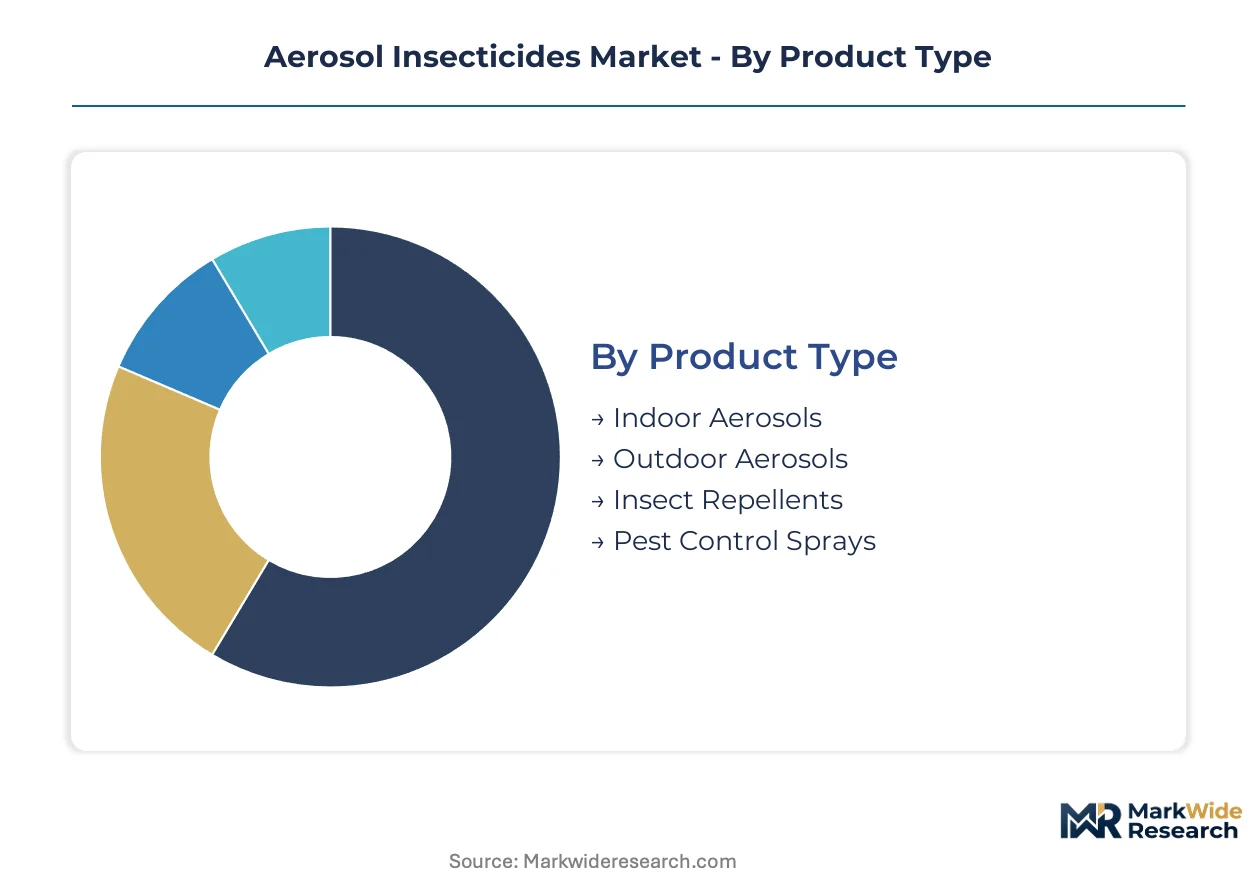
Aerosol insecticide suppliers calibrate formulation potency, propellant chemistry, and packaging format against distinct use environments and regulatory exposure. Segment boundaries are hardening as EPA and REACH tighten active ingredient approvals separately.
Product Type:
Replacement cycles accelerate where F-Gas Regulation forces propellant reformulation, compressing legacy product lifespans.
- Indoor Aerosols:Pyrethroid-based pressurized formulations in aluminum canisters dominate household pantries. Demand concentrates in Brazil's urban centers where Aedes aegypti suppression drives quarterly replenishment.
- Outdoor Aerosols:Higher-concentration permethrin formulations withstand weather exposure on patios and perimeter zones. German municipalities are expanding procurement for public space mosquito abatement programs.
- Insect Repellents:DEET and picaridin sprays for personal application bypass propellant constraints through pump mechanisms.
- Pest Control Sprays:Trigger-spray formats with concentrated actives target crawling insects in commercial kitchens and food processing facilities.
Indoor Aerosols sits at the top of the volume ranking, with Outdoor Aerosols climbing the fastest.
End User:
Margin structures diverge sharply between price-sensitive household purchasers and compliance-burdened institutional buyers.
- Residential:Episodic retail purchases of single-unit aerosols generate thin margins but massive throughput. Subscription auto-ship models in United States coastal metros are compressing seasonal demand spikes.
- Commercial:Licensed pest control services in Germany and the United States command per-unit margins multiple times above retail. Documentation requirements for professional-grade actives filter out smaller competitors.
- Agricultural:Perimeter treatments around livestock facilities and grain storage face encroachment from biological substitutes.
- Institutional:Hospitals, schools, and government facilities mandate low-toxicity formulations with extensive safety dossiers.
Residential dominates absolute volume, with Commercial expanding most quickly.
Application:
Vector control procurement cycles operate on public health emergency timelines distinct from seasonal household purchasing.
- Vector Control:Southeast Asian public health programs purchase pyrethroid aerosols in bulk for dengue and malaria suppression. Procurement volumes spike following outbreak declarations.
- Household Pest Management:Cockroach and ant treatments in kitchens and bathrooms represent the mature revenue base. Shelf placement in United States home improvement chains determines volume leadership.
- Professional Pest Control:Concentrated actives for licensed applicators face REACH documentation backlogs stretching 18-24 months.
- Agricultural Pest Control:Perimeter applications around greenhouses and livestock housing compete with Bacillus thuringiensis alternatives.
Household Pest Management anchors revenue stability, with Vector Control showing the steepest expansion trajectory.
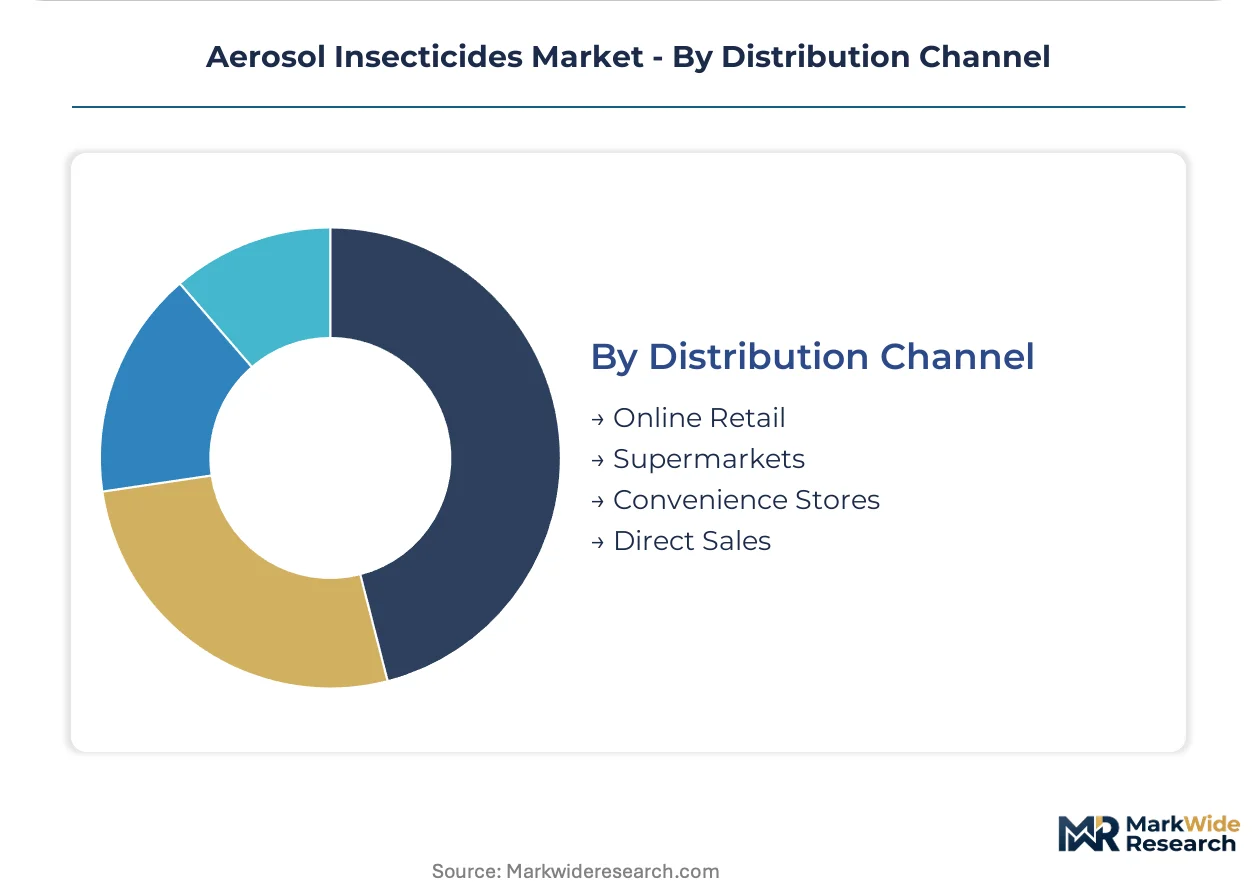
Distribution Channel:
Channel selection determines margin capture and regulatory exposure for formulation suppliers.
- Online Retail:Direct-to-consumer platforms erode supermarket dominance in developed economies. Private-label entry and subscription models flourish where same-day delivery infrastructure exists.
- Supermarkets:Seasonal stocking cycles in North American and European chains still command the largest absolute throughput position.
- Convenience Stores:Emergency purchase occasions for immediate infestation response support premium pricing.
- Direct Sales:Bulk procurement contracts with municipalities and vector control agencies bypass retail markup entirely.
Supermarkets maintain volume leadership, with Online Retail gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propellant reformulation costs are driving manufacturing migration toward jurisdictions with lighter compliance burdens. Southeast Asian production clusters absorb volume as European facilities retool for compressed gas systems.
United States
Vector control contracts with municipal agencies in Florida and Texas sustain pyrethroid aerosol demand. EPA registration timelines for novel actives stretch 24-36 months, filtering out smaller formulators. SC Johnson maintains formulation facilities in Wisconsin and distribution dominance through home improvement retail chains.
Germany
Professional pest control services in North Rhine-Westphalia command premium pricing for licensed applicator-grade products. ECHA REACH dossier requirements and EU F-Gas Regulation phase-downs are compressing legacy product lifespans. BASF SE has accelerated nitrogen-based propellant rollouts across Ludwigshafen production lines.
Brazil
Urban pest management contracts in São Paulo and Rio de Janeiro municipalities intensified following Aedes aegypti outbreak declarations. ANVISA toxicity documentation requirements for professional formulations create compliance barriers for imported products. Godrej Consumer Products anchors manufacturing presence through local formulation partnerships.
India
Household aerosol penetration in Maharashtra and Karnataka rises with urban middle-class expansion. Central Insecticides Board registration procedures for new actives lag 18-22 months behind commercial launch targets. Reckitt Benckiser leverages distribution infrastructure in Delhi-NCR and Mumbai to capture retail shelf space.
Thailand
Public health ministry procurement of pyrethroid aerosols spikes following dengue season declarations in Bangkok and Chiang Mai. Thai FDA efficacy substantiation requirements align with WHO prequalification standards for vector control products. Sumitomo Chemical supplies actives to local formulators serving Southeast Asian export markets.
Aerosol Insecticides Market Competitive Landscape
Propellant system retooling dominates the current landscape as manufacturers confront EU F-Gas mandates. The vendor base separates into three tiers: multinational FMCG conglomerates with retail shelf dominance, agrochemical specialists with professional channel access, and regional formulators serving price-sensitive emerging markets. Consolidation pressure intensifies as compliance costs rise. M&A activity targets mid-tier producers with established registration dossiers, while capacity expansion concentrates in Southeast Asian low-cost manufacturing zones.
Within the diversified conglomerate tier, SC Johnson, Reckitt Benckiser, and Godrej Consumer Products exemplify divergent geographic anchoring strategies. The Wisconsin-based SC Johnson leverages century-old retail relationships across North American home improvement chains. British-domiciled Reckitt Benckiser concentrates formulation expertise on resistant insect strain targeting. Mumbai-headquartered Godrej Consumer Products captures emerging market volume through localized production and distribution density in South Asian urban corridors.
| Leading Market Players |
|---|
| SC Johnson |
| Reckitt Benckiser |
| Bayer AG |
| Syngenta |
| Henkel |
| Godrej Consumer Products |
| Procter & Gamble |
| BASF SE |
| Sumitomo Chemical |
| Others |
Value Network & Pricing Analysis
Captive aluminum canister production in Thailand, Vietnam, and Indonesia anchors supply position and pricing power for aerosol insecticide suppliers serving Southeast Asian vector control programs. Three metal packaging suppliers control the majority of global container output, compressing procurement leverage for mid-tier formulators while elevating input costs for hydrocarbon-dependent legacy lines.
Pricing Analysis
Retailer markup compression in North American home improvement chains distinguishes volume leaders from private-label entrants. Three-tier pricing structure across professional-grade concentrates, standard household aerosols, and economy repellent tiers reflects certification burden and concentration potency. Pricing pressure stems from F-Gas-driven propellant reformulation capex absorbing margin in European manufacturing. Licensed applicator channels in Germany and the United States exhibit lowest price sensitivity due to per-job billing pass-through.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian aluminum canister foundries concentrated in Thailand, Vietnam, and Indonesia. Active ingredient supply draws from Chinese pyrethroid manufacturers and Indian pyrethrin extractors, with propellant chemistry resting on Middle Eastern hydrocarbon feedstocks. Tariff exposure on aluminum sheet imports threatens cost stability for European formulators retooling compressed gas lines. Distribution runs through supermarket seasonal stocking cycles in developed economies alongside expanding direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerosol insecticides market functions as a regulatory compounder, with EU F-Gas phase-down schedules and REACH authorization timelines forcing successive reformulation investments that consolidate share among well-capitalized incumbents.
For Market Incumbents: Deepen backward integration into aluminum canister production to offset Southeast Asian supplier concentration and secure input cost stability. Accelerate nitrogen-based propellant platform certification across multiple jurisdictions to capture first-mover margin before F-Gas deadlines compress legacy product lifespans. Prioritize REACH dossier consolidation on actives with existing toxicity documentation rather than novel molecule registration.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models in United States coastal metropolitan corridors where same-day delivery infrastructure supports auto-ship customer acquisition. Target private-label supply agreements with Amazon and regional e-commerce platforms as the most penetrable channel entry point. Avoid professional-grade concentrate segments where documentation backlogs stretch eighteen to twenty-four months.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier regional formulators with established ANVISA, EPA, or Central Insecticides Board registrations because regulatory filing assets compound in value as approval timelines lengthen. Focus acquisition screening on Brazilian and Indian manufacturing assets serving vector control procurement cycles. Watch Southeast Asian dengue outbreak declaration frequency as the inflection indicator for pyrethroid aerosol demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Compressed Gas Propellant Transition | Nitrogen-based systems bypass EU F-Gas constraints entirely, opening reformulation windows for compliant suppliers. |
| Licensed Applicator Channel Expansion | Professional pest control services in Germany and the United States command per-unit margins multiple times above retail household products. |
| Backward Integration into Canister Production | In-house aluminum container manufacturing mitigates Southeast Asian supplier concentration risk and stabilizes input costs. |
| Subscription-Based Replenishment Models | Auto-ship arrangements in United States coastal metros compress seasonal demand spikes and reduce customer acquisition costs. |
| Regulatory Dossier Consolidation | Focus on actives with existing REACH toxicity documentation accelerates product launch timelines versus novel molecule registration. |
Research Methodology
Multiple input streams — formulation chemists at multinational suppliers, procurement officers at Southeast Asian vector control agencies, regulatory affairs leads at ECHA and EPA, and retail category buyers at North American home improvement chains — were reconciled against customs trade data, SEC 10-K filings, and Central Insecticides Board registration databases. Bottom-up volume estimates from aluminum canister production and active ingredient trade flows were triangulated with top-down market sizing derived from public health ministry procurement disclosures.
Data-stream reconciliation across product type, end user, application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by absolute throughput position. Forecast inputs incorporated F-Gas phase-down schedules, REACH authorization timelines, and vector control procurement cycle patterns specific to dengue-endemic regions.
Several conditions sit outside the modeled scope, including unannounced regulatory bans on specific pyrethroid actives, breakthrough biological substitute efficacy in agricultural perimeter applications, and abrupt aluminum supply disruptions from Southeast Asian foundry consolidation. Forecasts reflect assumptions about propellant transition capex absorption and documentation backlog resolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Cummene Derivatives Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Egypt Acidulants Market
Chemicals
Scouring Agents Market
Chemicals
Flooring Chemicals Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Naturally Derived Fatty Alcohol Market
Chemicals
Cold Phosphating Chemicals Market
Chemicals
Paint Stripper Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
North America Isopropyl Alcohol Market
Chemicals
Chemical Distribution Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Global Syringaldehyde Market
Chemicals
China Methanol Market
Chemicals
Aluminium Chloride Market