
 Biodegradable Spray Tank Line-Cleaning Chemistry Market | 2026-2036
Biodegradable Spray Tank Line-Cleaning Chemistry Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Spray Tank Line-Cleaning Chemistry Market Insights
Petrochemical surfactant formulations is rebalancing toward plant-derived alkyl polyglucoside bases as feedstock volatility and biodegradability thresholds tighten product economics. BASF leverages its integrated surfactant supply chain to anchor European manufacturing scale for agricultural cleaning chemistry. Nutrien Ag Solutions sustains broad North American distribution through its retail agronomy network, while Helena Agri-Enterprises differentiates through technical service bundling with precision application programs.
Biodegradable spray tank line-cleaning chemistry comprises aqueous cleaning formulations engineered to degrade microbial residues, pesticide deposits, and fertilizer films from spray equipment interior surfaces, typically achieving >60% biodegradation within 28 days under OECD 301 test protocols. These chemistries prevent cross-contamination between sequential crop protection applications and maintain nozzle calibration integrity across seasonal spray cycles. Alkaline cleaners dominate current volume due to proven efficacy against organophosphate residues, while enzymatic agents represent the fastest-expanding category as protein-specific degradation reduces re-entry interval constraints. Surfactant-based solutions concentrate margin pools where concentrated formulations enable dilution ratios that cut per-acre cleaning costs for large-scale operators.
EPA container and containment regulations mandate triple-rinse or equivalent cleaning protocols that biodegradable formulations satisfy without hazardous waste generation, while REACH restrictions on nonylphenol ethoxylates redirect European formulation sourcing toward compliant alternatives. OECD 301 biodegradability standards and EPA Design for the Environment certification shape product registration pathways and distributor stocking decisions across major agricultural markets. Stakeholders must monitor evolving state-level neonicotinoid restrictions that will expand tank-cleaning frequency requirements and shift demand toward specialized residue-targeting chemistries.
Market Dynamics
EPA's revised pesticide container and containment regulations are forcing agricultural service providers to abandon conventional solvent-based cleaners, compressing the transition timeline for biodegradable alternatives across intensive farming corridors.
Growth Catalysts
- REACH restrictions on nonylphenol ethoxylates:European formulation sourcing is redirecting toward compliant alkyl polyglucoside alternatives, expanding addressable demand for biodegradable tank-cleaning chemistry.
- California's Central Valley agricultural corridor:Specialty crop protection service providers in this intensive farming zone are expanding adoption of residue-limit-compliant cleaning protocols ahead of seasonal spray cycles.
- Enzymatic degradation technology:Protein-specific cleaning agents are reducing re-entry interval constraints for farm labor, accelerating replacement of alkaline-only cleaning regimens.
Market Restraints
- Plant-derived feedstock volatility:Corn and palm kernel oil price swings destabilize alkyl polyglucoside production economics, squeezing margin pools for concentrated formulation suppliers.
- European surfactant supply concentration:BASF's integrated manufacturing scale creates dependency risk for mid-tier formulators lacking backward integration into raw material production.
- Performance gaps against chlorinated solvents:Biodegradable alternatives require extended contact times for synthetic pyrethroid residues, limiting adoption in high-throughput commercial spraying operations.
Strategic Opportunities
- Germany's Rhine region intensive farming zones:Comparable agricultural density to California's Central Valley creates parallel demand expansion for OECD 301-compliant cleaning protocols.
- Precision application program bundling:Technical service integration with drone and variable-rate spraying systems opens recurring revenue streams beyond commodity chemical sales.
- State-level neonicotinoid restrictions:Expanding tank-cleaning frequency mandates in jurisdictions with pollinator protection laws will shift demand toward specialized residue-targeting chemistries.
Industry Challenges
- OECD 301 biodegradability certification timelines:28-day test protocol documentation delays product registration and distributor stocking decisions across major agricultural markets.
- Formulation chemist talent scarcity:Specialized expertise in surfactant-biocide synergy for agricultural equipment cleaning concentrates at legacy petrochemical suppliers, constraining new entrant R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Spray Tank Line-Cleaning Chemistry Market |
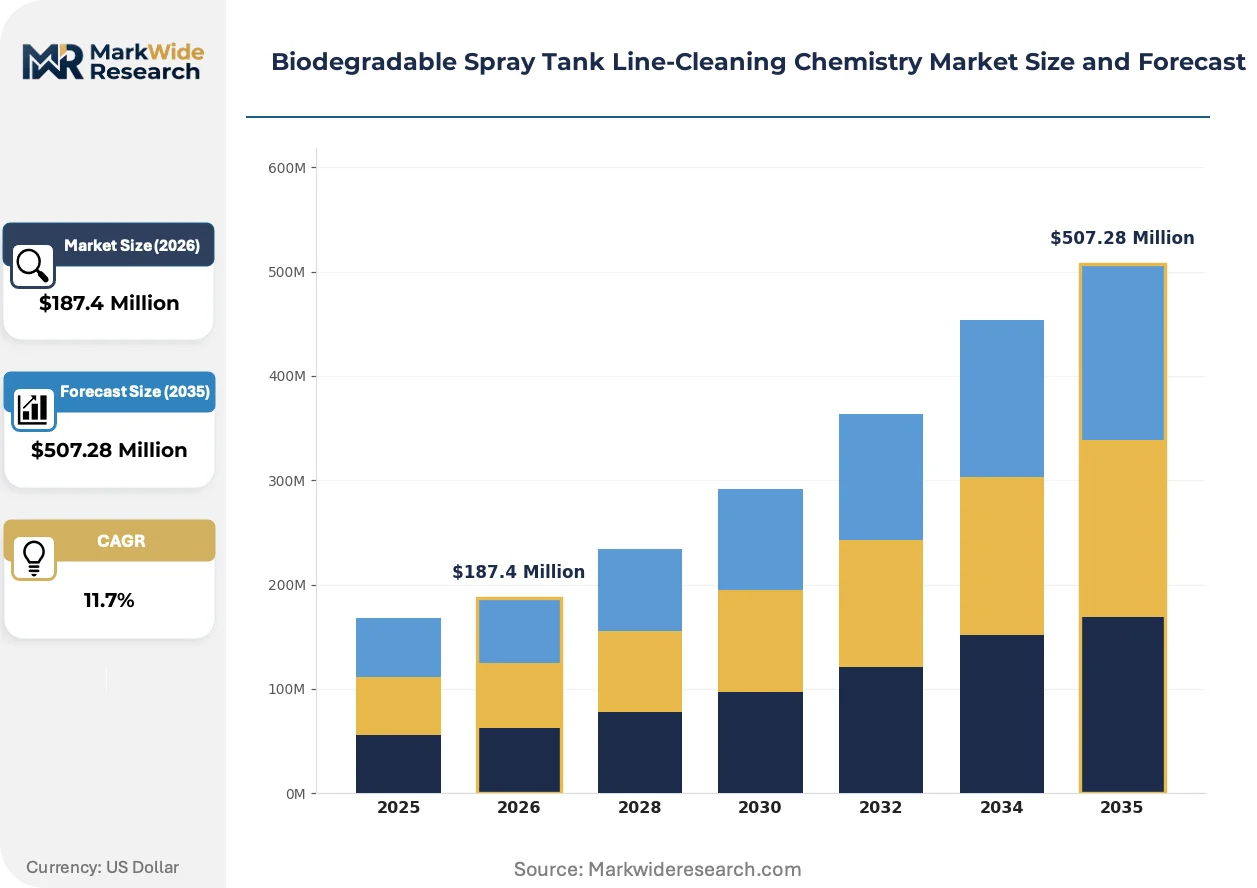
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acid Cleaners, Alkaline Cleaners, Enzymatic Agents, Surfactant-based Solutions, Chelating Agents Application: Beverage Processing, Dairy Equipment, Pharmaceutical Manufacturing, Food Processing, Chemical Production End User: Contract Manufacturers, Food & Drink Processors, Pharmaceutical Producers, Chemical Plants, Beverage Facilities Deployment: Automated Cleaning Systems, Manual Application, In-Line Cleaning, Batch Cleaning, Ultrasonic Cleaning |
| Companies Covered | UPL, BRANDT, Nutrien Ag Solutions, Helena Agri-Enterprises, WinField United, Precision Laboratories, Wilbur-Ellis, Ecolab, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Spray Tank Line-Cleaning Chemistry Market Trends and Innovations
Enzymatic cleaning agents are compressing the competitive window for incumbent alkaline formulations, while regulatory pressure on hazardous waste generation accelerates chemistry substitution timelines across both North American and European agricultural markets.
Alkaline cleaners is overtaking solvent-based alternatives as the dominant volume category for organophosphate residue removal. Large-scale operators in California's Central Valley are adopting concentrated formulations that enable aggressive dilution ratios, cutting per-acre cleaning costs while maintaining nozzle calibration integrity across seasonal spray cycles. This technology shift is compressing margin pools for legacy chlorinated solvent suppliers.
REACH restrictions on nonylphenol ethoxylates are mandating reformulation across European agricultural chemistry supply chains. Industrial consequence includes accelerated sourcing redirection toward compliant surfactant alternatives, with formulators absorbing certification costs to maintain distributor relationships. Specialty crop protection service providers in Germany's Rhine region face the most acute compliance pressure, driving fastest adoption of alkyl polyglucoside-based alternatives.
Buyer concentration among retail agronomy networks is consolidating procurement decisions for tank-cleaning chemistry. Helena Agri-Enterprises and comparable technical service providers are unbundling after-sales support from commodity chemical transactions, replacing traditional distributor relationships with direct formulation partnerships. This channel restructuring is most visible across North American corn and soybean belts, where co-operative buying groups negotiate multi-season supply contracts.
Biodegradable Spray Tank Line-Cleaning Chemistry Market Segmentation
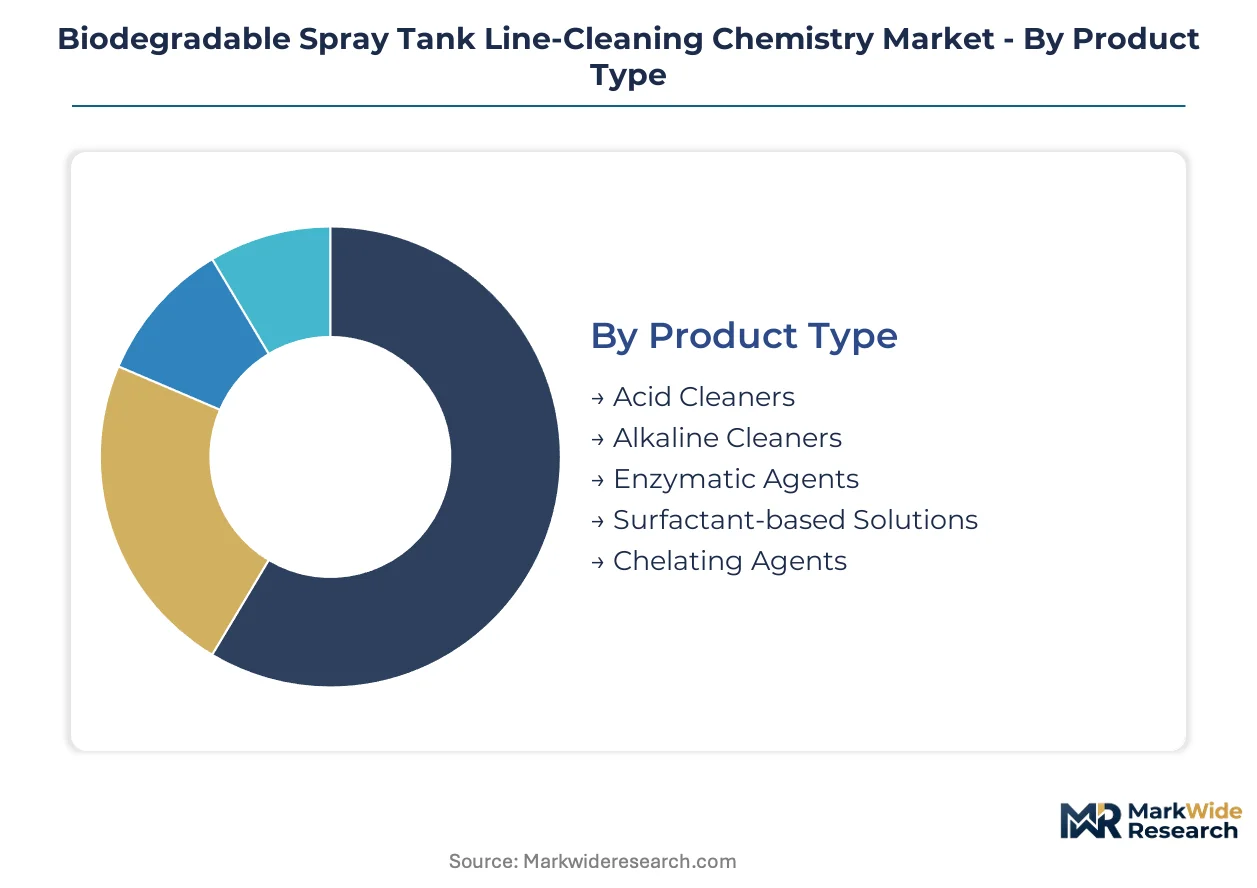
Segmentation in biodegradable spray tank line-cleaning chemistry reveals distinct capital requirements and performance specifications that shape supplier positioning. Formulation complexity and equipment integration demands vary sharply across product categories and deployment modes.
Product Type:
Capital intensity concentrates in enzymatic and surfactant-based segments where bioreactor infrastructure and precision blending equipment dominate upfront investment.
- Alkaline Cleaners:Sodium hydroxide and potassium hydroxide formulations with pH 11-13 specifications deliver proven efficacy against organophosphate residues. California's Central Valley specialty crop operators specify these for seasonal spray equipment maintenance where rapid residue breakdown matters. Formulation requires moderate capital outlay for caustic handling systems.
- Enzymatic Agents:Protein-specific cleaning formulations leverage lipase and protease biocatalysts engineered for 28-day OECD 301 biodegradability compliance. Protein-specific degradation reduces farm labor re-entry interval constraints, accelerating replacement of alkaline-only regimens. Bioreactor cultivation and enzyme stabilization infrastructure demands the highest capital commitment among all product categories.
- Surfactant-based Solutions:Alkyl polyglucoside concentrates enable aggressive dilution ratios that cut per-acre cleaning costs for large-scale operators.
- Acid Cleaners:Phosphoric and citric acid formulations target mineral deposit and fertilizer film removal from spray equipment.
- Chelating Agents:EDTA-free alternatives bind metal ions without persistent environmental accumulation.
Alkaline cleaners absorb the bulk of installed capacity; enzymatic agents are expanding most quickly.
Application:
Regulatory stringency varies by application, with pharmaceutical and food processing segments imposing the most demanding residue-limit protocols.
- Food Processing:USDA and FDA residue-limit mandates drive adoption of OECD 301-compliant cleaning protocols for spray equipment used in post-harvest fungicide applications. Equipment cleaning frequency requirements intensify under state-level neonicotinoid restrictions, expanding addressable demand for specialized residue-targeting chemistries.
- Pharmaceutical Manufacturing:cGMP validation requirements and EPA Design for the Environment certification shape procurement specifications for tank-cleaning chemistry. FDA containment regulations mandate triple-rinse or equivalent cleaning protocols that biodegradable formulations satisfy without hazardous waste generation.
- Beverage Processing:Brewery and winery spray equipment cleaning prioritizes flavor-neutral biodegradable formulations.
- Dairy Equipment:Milk residue and sanitizer compatibility requirements dictate specialized alkaline-enzymatic hybrid formulations.
- Chemical Production:Pesticide synthesis and formulation facilities require tank-cleaning chemistry compatible with active ingredient handling.
Food processing commands the largest share of volume demand; pharmaceutical manufacturing is climbing the fastest on regulatory compliance spending.
End User:
Procurement sophistication separates contract manufacturers from captive processing operations, with co-operative buying groups consolidating purchasing power across agricultural belts.
- Food & Drink Processors:Co-operative buying groups across North American corn and soybean belts negotiate multi-season supply contracts for tank-cleaning chemistry. Direct formulation partnerships replace traditional distributor relationships as technical service bundling gains preference.
- Contract Manufacturers:Third-party spray application services face acute EPA container and containment compliance pressure, compressing transition timelines for biodegradable alternatives.
- Pharmaceutical Producers:cGMP validation documentation requirements extend procurement cycles for cleaning chemistry suppliers.
- Chemical Plants:Pesticide active ingredient manufacturers specify tank-cleaning protocols that prevent cross-contamination between synthesis batches.
- Beverage Facilities:Winery and brewery operators prioritize cleaning chemistry that leaves no sensory residue on spray equipment.
Food and drink processors absorb the bulk of installed capacity; contract manufacturers are gaining share fastest on outsourced spray service expansion.
Deployment:
Automation capital requirements create tiered adoption patterns, with large-scale operators investing in integrated cleaning systems while smaller farms retain manual protocols.
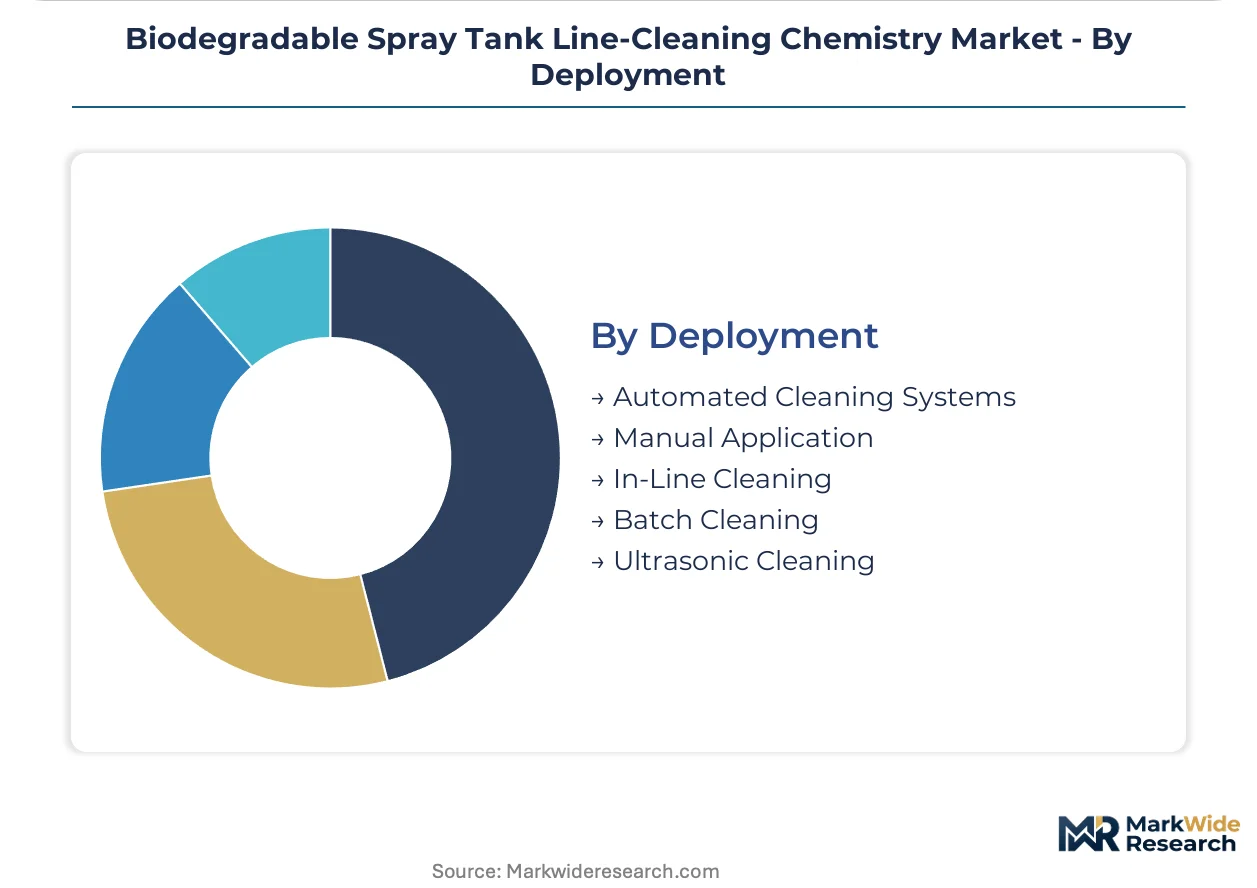
- Automated Cleaning Systems:CIP (clean-in-place) skid systems with programmable wash cycles and conductivity sensors dominate California Central Valley and Germany Rhine region intensive farming zones. Integration with precision application programs opens recurring revenue streams beyond commodity chemical sales for technical service providers.
- In-Line Cleaning:Continuous spray equipment flushing during seasonal operations reduces downtime between sequential crop protection applications.
- Manual Application:Bucket-and-brush protocols persist among smaller specialty crop operators with limited equipment fleets.
- Batch Cleaning:Seasonal end-of-cycle tank cleaning concentrates demand in discrete purchasing windows.
- Ultrasonic Cleaning:High-frequency cavitation systems target nozzle orifice restoration where calibration integrity maintenance matters.
Automated cleaning systems absorb the bulk of installed capacity; in-line cleaning is expanding most quickly on labor cost pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in agricultural corridors where intensive specialty crop production intersects with stringent residue-limit enforcement. California's Central Valley and Germany's Rhine region anchor installed capacity for biodegradable tank-cleaning chemistry. Regulatory pressure on hazardous waste generation accelerates substitution timelines across these intensive farming zones.
United States
EPA container and containment regulations mandate triple-rinse protocols that biodegradable formulations satisfy without hazardous waste generation. Specialty crop protection service providers in California's Central Valley specify OECD 301-compliant cleaning chemistry ahead of seasonal spray cycles. The state's Department of Pesticide Regulation enforces residue limits that compress transition timelines for conventional solvent alternatives.
Germany
REACH restrictions on nonylphenol ethoxylates redirect formulation sourcing toward compliant alkyl polyglucoside alternatives. BASF leverages integrated surfactant supply chains to anchor European manufacturing scale for agricultural cleaning chemistry. The Rhine region's intensive farming zones face acute compliance pressure, driving fastest adoption of plant-derived cleaning protocols among specialty crop operators.
Brazil
Expanding soybean and sugarcane production intensifies spray equipment utilization rates across Mato Grosso and São Paulo states. ANVISA pesticide residue regulations are tightening alignment with OECD biodegradability standards for imported cleaning formulations. Large-scale contract applicators in the Cerrado agricultural frontier specify tank-cleaning chemistry that prevents cross-contamination between sequential crop protection applications.
India
FSSAI residue-limit mandates for food-grade agricultural inputs expand addressable demand for biodegradable cleaning protocols in Punjab and Haryana wheat belts. The Central Insecticides Board regulates pesticide container handling standards that favor aqueous cleaning formulations over solvent-based alternatives. Co-operative buying groups across Maharashtra's cotton-growing districts negotiate multi-season supply contracts for concentrated tank-cleaning chemistry.
Australia
APVMA re-registration requirements for agricultural chemical handlers emphasize environmental fate characteristics of spray equipment cleaning agents. Queensland and New South Wales broadacre operators face seasonal labor constraints that favor enzymatic cleaning agents with reduced re-entry intervals. TGA-aligned state environmental protection agencies audit tank-cleaning documentation for compliance with water quality protection mandates.
Biodegradable Spray Tank Line-Cleaning Chemistry Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers race to secure feedstock integration for alkyl polyglucoside production. The vendor base stratifies across three tiers: integrated petrochemical majors with captive surfactant supply, regional formulators with distributor anchoring relationships, and specialty enzymatic technology developers. Strategic archetypes include backward-integrated raw material suppliers, technical service bundlers, and precision application integrators. Geographic expansion and portfolio diversification represent the dominant competitive moves as players seek defensible positions in agricultural corridors.
Among integrated chemical suppliers, BASF exemplifies the backward-integrated archetype through its European manufacturing scale for agricultural cleaning chemistry. Nutrien Ag Solutions occupies a position within the retail agronomy network tier, sustaining broad North American distribution infrastructure. Helena Agri-Enterprises represents the technical service bundling archetype, differentiating through precision application program integration rather than commodity chemical transactions alone.
| Leading Market Players |
|---|
| UPL |
| BRANDT |
| Nutrien Ag Solutions |
| Helena Agri-Enterprises |
| WinField United |
| Precision Laboratories |
| Wilbur-Ellis |
| Ecolab |
| BASF |
| Others |
Pricing and Supply Chain Analysis
Alkyl polyglucoside feedstock costs transmit directly from palm kernel oil and corn starch volatility through to concentrated formulation pricing tiers, with large-scale operators in California's Central Valley capturing scale discounts that mid-tier formulators cannot match against BASF's integrated European supply base.
Pricing Analysis
Volume-margins split sharply between commodity alkaline cleaners and premium enzymatic formulations. Three-tier pricing structure across premium OECD 301-certified, standard REACH-compliant, and economy solvent-replacement tiers reflects certification investment and bioreactor infrastructure recovery timelines. Pricing pressure stems from plant-derived feedstock volatility squeezing concentrated formulation suppliers. Contract manufacturers show highest price sensitivity due to thin application-service margins, while pharmaceutical producers absorb premium tiers for cGMP validation documentation.
Supply Chain Analysis
OECD 301 biodegradability certification and EPA Design for the Environment qualification gate supplier entry, with documentation timelines extending procurement cycles for new entrants. Manufacturing concentrates in Germany, the United States, and Brazil where REACH and EPA regulatory alignment anchor formulation standards. Raw material sourcing draws from palm kernel oil plantations in Southeast Asia, corn starch processors in the US Midwest, and European petrochemical surfactant streams. Single-source vulnerability concentrates in BASF's German alkyl polyglucoside production. Distribution runs through retail agronomy networks and direct technical service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase where enzymatic cleaning agents displace legacy alkaline-only regimens, with protein-specific biocatalysts reducing farm labor re-entry intervals and compressing the competitive window for incumbent formulations.
For Market Incumbents: Lock in backward integration into palm kernel oil and corn starch supply streams to insulate margin pools from feedstock volatility. Secure multi-season supply contracts with co-operative buying groups across North American corn and soybean belts before channel restructuring completes. Prioritize bioreactor capacity addition in Germany's Rhine region to anchor European enzymatic production scale against emerging specialty technology developers. For New Entrants and Emerging Players: Retail agronomy networks represent the most accessible channel anchor for formulation partnerships replacing traditional distributor relationships. Target automated CIP system integrators in California's Central Valley as the most penetrable deployment segment where precision application bundling opens recurring revenue streams. Pursue white-space opportunities in Brazil's Cerrado frontier where ANVISA alignment with OECD standards creates first-mover positioning for imported biodegradable formulations. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier formulators with captive surfactant blending capabilities in Germany's Rhine region where REACH compliance costs strain undercapitalized competitors. Long-term viability over a 5-10 year window hinges on enzymatic technology acquisition or licensing rather than alkaline commodity exposure. Watch state-level neonicotinoid restriction expansion as the inflection signal for specialized residue-targeting chemistry demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plant-Derived Feedstocks | BASF's captive palm kernel oil sourcing insulates European manufacturing from commodity volatility. |
| Bioreactor Capacity Expansion | Enzymatic agent producers in Germany capture OECD 301 certification scale advantages. |
| Precision Application Program Bundling | Helena Agri-Enterprises replaces commodity transactions with technical service integration. |
| Direct Formulation Partnerships | Nutrien Ag Solutions' retail network restructuring consolidates procurement decisions. |
| Regulatory Certification Investment | EPA Design for the Environment qualification gates distributor stocking decisions. |
Research Methodology
Document review covered EPA pesticide container regulations, REACH restriction filings, OECD 301 test protocol documentation, and agricultural chemical trade data, complemented by interviews with formulation chemists at specialty surfactant suppliers, procurement leads at retail agronomy networks, technical service directors at precision application providers, and regulatory affairs managers at crop protection distributors. Secondary validation drew from SEC 10-K filings of integrated chemical suppliers, customs import records for alkyl polyglucoside feedstocks, and state-level pesticide residue enforcement reports. Bottom-up volume modeling triangulated against top-down agricultural spray equipment installed base estimates.
Cross-referencing historical adoption curves for solvent-to-aqueous cleaner transitions against expert panel input on enzymatic technology penetration timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, deployment automation level, end-use regulatory stringency, and regional agricultural intensity cluster. CAGRs derived from weighted scenario analysis incorporating feedstock price elasticity and certification timeline probability distributions. Industry-specific inputs captured California Department of Pesticide Regulation enforcement patterns and ANVISA alignment trajectory with OECD biodegradability standards.
Caveats apply where palm kernel oil supply disruptions, accelerated neonicotinoid restriction timelines, or enzymatic stabilization breakthroughs could materially shift the outlook. Forecasts reflect assumptions on regulatory enforcement consistency and feedstock price mean-reversion. A model refresh is warranted upon material change in EPA container regulation amendment schedules or REACH surfactant restriction expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
Global Antiseptic Products Market
Cleaning Chemicals
Dry Electrostatic Wipes Market
Cleaning Chemicals
Europe Metal Cleaning Chemicals Market
Cleaning Chemicals
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market
Cleaning Chemicals
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Cement Surface Treatment Chemicals Market