
 Allyl Chloride Market | 2026-2036
Allyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Allyl Chloride Market Analysis
Epichlorohydrin is restructuring product economics across allyl chloride value chains as manufacturers pivot from glycerin-based routes back to propylene-derived chemistry. Sumitomo Chemical Co., Ltd leverages captive chlorine integration across Kashima and Chiba to sustain cost discipline. Olin Corporation anchors North American supply through chlor-alkali co-location. Dow competes on process intensification, while INEOS controls logistics corridors linking Rotterdam crackers to derivative output.
Allyl chloride (3-chloropropene, C₃H₅Cl) is an organochlorine intermediate produced via high-temperature chlorination of propylene at 480-510°C, yielding a reactive monomer with a boiling point of 45°C that serves primarily as a precursor to epichlorohydrin, allylamines, and allyl ethers. Pharmaceutical intermediates command premium pricing due to cGMP compliance burdens and batch traceability requirements, while agricultural chemicals represent the fastest-expanding application segment driven by glyphosate adjuvant demand. Purity grades stratify sharply: ultra-pure material captures margin pools in electronics-grade epichlorohydrin, whereas industrial grade feeds bulk polymer production with thinner spreads.
EPA oversight of chlorinated organic emissions shapes US plant siting and abatement capex, while REACH registration deadlines in Europe constrain non-compliant import volumes. China's MEE enforces dual carbon goals that elevate energy-efficiency thresholds for chlor-alkali-derivative complexes. Stakeholders must monitor feedstock propylene spread volatility and regional carbon-border adjustment mechanics to calibrate capacity commitments.
Market Dynamics
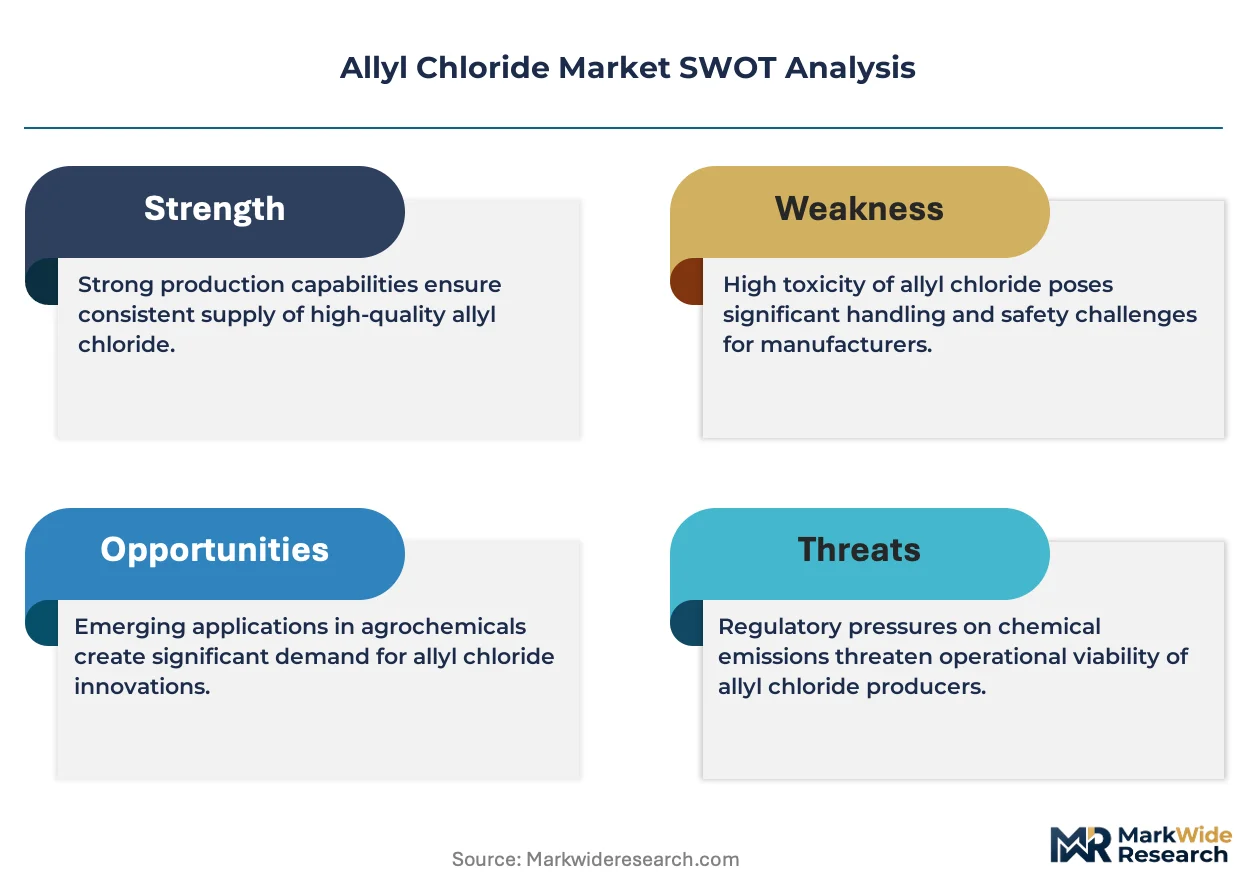
Propylene-chlorine integration economics are compressing margins for non-integrated producers while REACH compliance deadlines in Europe force feedstock certification upgrades across derivative supply chains.
Growth Catalysts
- Glyphosate adjuvant demand:Agricultural chemical formulators in China are expanding allyl chloride offtake for herbicide synthesis, pulling volume through integrated propylene derivatives clusters.
- Electronics-grade epichlorohydrin:Ultra-pure material specifications for printed circuit board laminates are creating premium pricing tiers that reward chlorine-captive producers.
- India's PLI scheme:Domestic chemical manufacturing incentives are attracting chlor-alkali capacity expansions that lower input costs for regional allyl chloride output.
Market Restraints
- Propylene spread volatility:Naphtha-cracker economics and shale-gas differentials inject cost instability that integrated players absorb better than merchant buyers.
- Jiangsu province concentration:Over half of China's allyl chloride derivative capacity sits within single-province chemical parks, exposing buyers to localized environmental enforcement actions.
- Glycerin-to-epichlorohydrin substitution:Bio-based routes in Southeast Asia compete for epichlorohydrin demand, compressing propylene-derived allyl chloride offtake in certain end-uses.
Strategic Opportunities
- Brazilian agrochemical localization:ANVISA registration pathways for imported intermediates create openings for allyl chloride-based herbicide precursor manufacturing within Mercosur trade zones.
- Carbon border adjustment mechanics:EU CBAM phase-in rewards low-carbon chlor-alkali sourcing, advantaging producers with renewable power integration.
- Allylamine pharmaceutical intermediates:cGMP-certified batch production for oncology and cardiovascular APIs commands 40-60% pricing premiums over industrial grades.
Industry Challenges
- Chlorinated organic emissions abatement:EPA Maximum Achievable Control Technology standards require US producers to deploy thermal oxidizers and scrubber upgrades that extend project timelines.
- cGMP batch traceability systems:Pharmaceutical-grade production demands serialization infrastructure and audit trails that legacy ERP platforms cannot support without multimillion-dollar overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allyl Chloride Market |
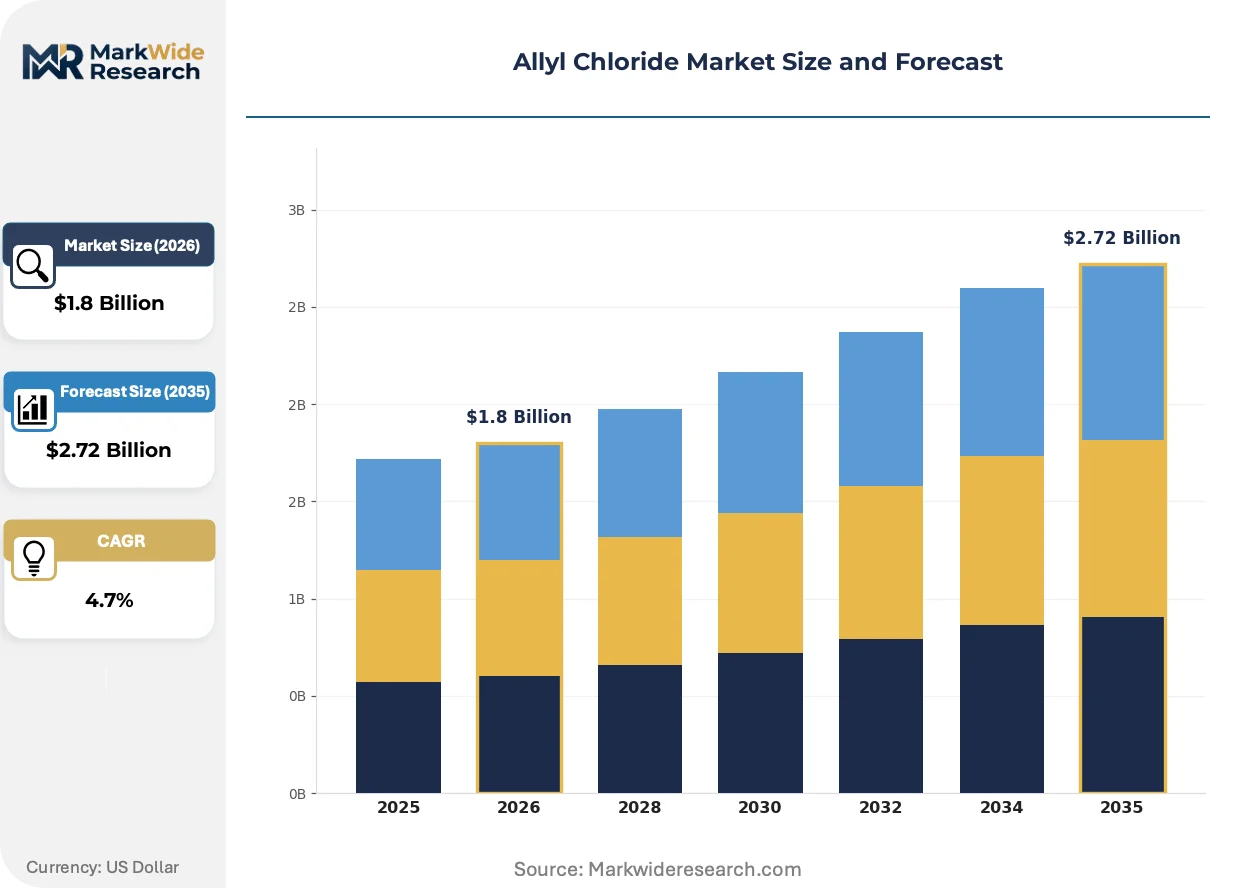
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purity Grade, Technical Grade, Ultra-Pure Grade, Industrial Grade Application: Chemical Synthesis, Pharmaceutical Intermediates, Agricultural Chemicals, Polymer Production End Use Industry: Pharmaceuticals, Agriculture, Coatings, Textiles Delivery Mode: Bulk Supply, Packaged Supply, Direct Supply, Scheduled Delivery |
| Companies Covered | Sumitomo Chemical Co., Ltd, Befar Group Co. Ltd., Olin Corporation, Dow, Kashima Chemical Co., Ltd, Solvay, OSAKA SODA, Gelest, Inc., INEOS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allyl Chloride Market Emerging Trajectories
Process intensification and digital twin deployment are compressing reactor residence times while tightening purity control, altering competitive moats for established chlor-alkali derivative producers.
Membrane chlor-alkali technology is converging with real-time spectroscopic monitoring to enable continuous allyl chloride purification that eliminates intermediate storage and reduces contamination risk. Electronics-grade epichlorohydrin manufacturers in Japan and South Korea are piloting these integrated systems, collapsing batch cycle times from hours to minutes while tightening purity specifications.
REACH registration deadlines for chlorinated intermediates are forcing European importers to document substance identity and hazard profiles across full supply chains. Non-compliant volumes face port-of-entry rejection, redirecting trade flows toward registered producers in the United States and Gulf Coast chemical corridors who have completed dossier submissions.
Specification-driven procurement now dominates pharmaceutical and agrochemical offtake, with buyers unbundling volume commitments from technical service packages. Formulators in India and China are negotiating direct chlor-alkali tie-ups that bypass traditional distributor networks, compressing margin capture for merchant traders in these markets.
Allyl Chloride Market Segmentation
Purity specifications and delivery logistics determine contract structures across allyl chloride procurement. Buyers in pharmaceutical and electronics applications impose certification requirements that fragment supplier pools by technical capability.
Product Type:
Specification thresholds separate captive chlor-alkali producers from merchant traders in contract negotiations.
- Purity Grade:Material meeting 99.5%+ assay standards serves cGMP pharmaceutical synthesis and electronics-grade epichlorohydrin. Formulators in Japan and South Korea pay premiums for certificates of analysis with full impurity profiling.
- Ultra-Pure Grade:Sub-ppm contamination limits for halogenated byproducts enable printed circuit board laminate production. Demand concentrates near semiconductor fabrication clusters in Taiwan and South Korea where surface resistivity specifications are tightening.
- Technical Grade:Standard industrial specifications for allylamine and allyl ether production.
- Industrial Grade:Bulk polymer feedstock with wider assay tolerances and lower unit pricing.
Ultra-Pure Grade leads on scale; Purity Grade leads on momentum.
Application:
End-use margins vary by regulatory burden and batch traceability requirements.
- Pharmaceutical Intermediates:cGMP-compliant production for oncology and cardiovascular APIs demands serialization infrastructure and audit trails. CDSCO registration requirements in India and FDA oversight in the United States constrain supplier qualification timelines.
- Agricultural Chemicals:Glyphosate adjuvant synthesis pulls volume through integrated propylene derivatives clusters in Jiangsu province. ANVISA registration pathways in Brazil are redirecting some formulation activity toward Mercosur manufacturing zones.
- Chemical Synthesis:Allylamine and specialty ether production for industrial markets.
- Polymer Production:Epichlorohydrin precursor demand for epoxy resin manufacturing.
Agricultural Chemicals leads on scale; Pharmaceutical Intermediates leads on momentum.
End Use Industry:
Customer concentration and technical service intensity shape channel economics.
- Pharmaceuticals:Batch traceability and serialization infrastructure requirements favor long-term supplier relationships over spot purchasing.
- Agriculture:Formulators in China negotiate direct chlor-alkali tie-ups that bypass traditional distributor networks.
- Coatings:Epoxy resin manufacturers source industrial-grade material with thinner technical service overlays.
- Textiles:Allyl ether derivatives for fabric finishing applications.
Agriculture leads on scale; Pharmaceuticals leads on momentum.
Delivery Mode:
Inventory carrying costs and security-of-supply priorities determine contract structures.
- Bulk Supply:Tanker deliveries to integrated chemical parks minimize handling costs for high-volume polymer producers.
- Direct Supply:Pipeline or dedicated logistics corridors from chlor-alkali complexes to derivative plants eliminate intermediate storage.
- Packaged Supply:Drum and tote configurations for pharmaceutical and specialty chemical formulators requiring smaller lot sizes.
- Scheduled Delivery:Just-in-time replenishment systems for customers with limited on-site storage capacity.
Bulk Supply leads on scale; Direct Supply leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province anchors the world's most concentrated allyl chloride derivative manufacturing footprint, with integrated propylene-chlorine complexes driving feedstock economics across Asia-Pacific. European REACH compliance deadlines and US EPA emissions standards are reshaping trade flows and capacity siting decisions.
China
Glyphosate adjuvant synthesis and electronics-grade epichlorohydrin demand pull volume through Yangtze River Delta chemical parks. MEE dual carbon goals enforce energy-efficiency thresholds that disadvantage smaller chlor-alkali operators. Nantong and Zhangjiagang clusters concentrate over half of national derivative capacity, exposing buyers to localized environmental enforcement actions.
United States
Shale-gas propylene economics and chlor-alkali co-location sustain cost-competitive epichlorohydrin output for epoxy resin manufacturers. EPA Maximum Achievable Control Technology standards mandate thermal oxidizer deployments that extend project timelines for new capacity. Gulf Coast chemical corridors linking Houston and Lake Charles dominate merchant supply to Latin American formulators.
Germany
REACH registration deadlines for chlorinated intermediates force feedstock certification upgrades across specialty chemical supply chains. ECHA substance identity documentation requirements redirect trade flows toward dossier-compliant producers. Ludwigshafen and Marl industrial complexes maintain captive integration for pharmaceutical-grade allylamine derivatives.
Japan
Electronics-grade specifications for printed circuit board laminates create premium pricing tiers that reward membrane chlor-alkali technology adopters. METI industrial decarbonization roadmaps incentivize renewable power integration at Kashima and Chiba production sites. Osaka Soda and Sumitomo Chemical facilities supply ultra-pure material to semiconductor fabrication clusters in Kyushu and Hiroshima.
India
PLI scheme incentives attract chlor-alkali capacity expansions that lower input costs for regional allyl chloride output targeting agrochemical formulators. CDSCO registration requirements for pharmaceutical intermediates constrain supplier qualification timelines for cGMP-compliant batches. Gujarat and Maharashtra chemical parks host emerging propylene derivative complexes serving domestic herbicide manufacturers.
Allyl Chloride Market Vendor Landscape
Global majors compete with regional champions across chlorine integration economics and regulatory compliance capabilities. The vendor base stratifies between chlor-alkali-captive producers with pipeline logistics and merchant traders dependent on spot propylene sourcing. Three archetypes dominate: integrated petrochemical conglomerates with propylene-chlorine control, specialty chemical houses with cGMP certification infrastructure, and regional agrochemical suppliers with direct formulator relationships. Capacity expansion and backward integration into membrane chlor-alkali technology represent the dominant competitive vectors.
Within the integrated conglomerate tier, Sumitomo Chemical Co., Ltd and Dow exemplify chlorine-captive positioning that sustains cost discipline across Kashima, Chiba, and Gulf Coast production sites. Olin Corporation anchors North American supply architecture through chlor-alkali co-location, while INEOS occupies a logistics-control position linking Rotterdam crackers to derivative output. Befar Group Co. Ltd represents the regional champion archetype with integrated propylene derivatives clustering in Shandong province. These named entities illustrate how feedstock integration and regulatory dossier completion separate sustainable operators from margin-compressed merchant competitors.
| Leading Market Players |
|---|
| Sumitomo Chemical Co., Ltd |
| Befar Group Co. Ltd. |
| Olin Corporation |
| Dow |
| Kashima Chemical Co., Ltd |
| Solvay |
| OSAKA SODA |
| Gelest, Inc. |
| INEOS |
| Others |
Supply Flow & Price Mechanics
cGMP batch serialization mandates from FDA and EMA are forcing pharmaceutical formulators to consolidate supplier pools toward certified producers, compressing merchant trader margins while rewarding chlorine-captive operators with pricing power anchored in compliance infrastructure.
Pricing Analysis
Propylene-chlorine spread pass-through dominates contract structures, with integrated Kashima and Chiba producers capturing margin stability that merchant buyers forfeit during naphtha-cracker volatility. Three-tier pricing structure across ultra-pure, pharmaceutical-grade, and industrial specifications separates electronics laminates manufacturers paying premiums for sub-ppm halogen limits from bulk polymer feedstock purchasers. Pricing pressure stems from glycerin-to-epichlorohydrin substitution in Southeast Asia, eroding propylene-derived allyl chloride offtake in certain epoxy resin applications. Agricultural chemical formulators in Jiangsu province exhibit highest price sensitivity due to direct chlor-alkali tie-ups that bypass distributor markups, while oncology API manufacturers accept 40-60% premiums for cGMP-certified batches.
Supply Chain Analysis
Direct pipeline corridors from Rotterdam crackers to derivative output anchor European logistics, while tanker deliveries to Yangtze River Delta chemical parks handle Asia-Pacific volume concentration. Feedstock propylene draws from shale-gas economics in the United States, naphtha-cracker output in Japan, and integrated refinery streams in China. Single-province concentration risk looms as over half of China's derivative capacity clusters within Jiangsu, exposing buyers to localized MEE environmental enforcement actions. Distribution runs through captive chlor-alkali complexes for high-volume polymer producers, with drum and tote configurations serving pharmaceutical formulators requiring smaller lot traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where electronics-grade epichlorohydrin specifications and cGMP pharmaceutical intermediates are displacing commodity-tier production.
For Market Incumbents: Anticipate glycerin-based epichlorohydrin substitution by securing long-term propylene offtake agreements and deploying membrane chlor-alkali technology at Kashima-scale facilities. Backward integration into renewable-powered chlorine production addresses EU CBAM phase-in mechanics while defending margin position against carbon-border-adjusted imports. For New Entrants and Emerging Players: Capture Brazilian agrochemical localization opportunities through ANVISA-registered allyl chloride-based herbicide precursor manufacturing within Mercosur trade zones. India's PLI scheme incentives offer the most penetrable entry point, with direct chlor-alkali tie-ups to Gujarat agrochemical formulators bypassing established distributor networks. For Investors and Strategic Acquirers: Asymmetric upside sits with membrane chlor-alkali technology adopters possessing cGMP certification infrastructure and pipeline logistics control. Long-term viability favors producers with captive propylene-chlorine integration across multi-site footprints capable of serving both electronics and pharmaceutical grade demand. Watch EU CBAM implementation pace as inflection indicator for carbon-adjusted competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Chlor-Alkali | Captive chlorine supply at Kashima and Chiba sites eliminates merchant feedstock volatility exposure. |
| cGMP Certification Investment | FDA and EMA serialization compliance unlocks 40-60% pricing premiums in oncology API intermediates. |
| Long-term Supply Agreement with Electronics Laminates Producers | Taiwan and South Korea PCB manufacturers demand sub-ppm purity with multi-year volume commitments. |
| Joint Venture in Mercosur Manufacturing Zone | ANVISA registration pathways enable Brazilian agrochemical formulator bypass of import dependency. |
| Renewable Power Integration | EU CBAM phase-in rewards low-carbon chlor-alkali sourcing with carbon-border-adjusted competitiveness. |
Methodological Framework
Direct dialogue with chlor-alkali plant managers, pharmaceutical procurement leads at oncology API manufacturers, agrochemical formulators in Jiangsu province, and specialty chemical distribution channel partners grounded qualitative findings. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of integrated petrochemical conglomerates, and ECHA REACH registration databases. Bottom-up capacity modeling and top-down demand segmentation triangulation ensured cross-verified outputs.
Bottom-up volume builds aggregated named production capacities across Kashima, Chiba, Rotterdam, Gulf Coast, and Yangtze River Delta clusters, while top-down approaches calibrated against end-use consumption in epichlorohydrin, allylamine, and pharmaceutical intermediate applications. Segmentation dimensions spanned purity grade tiers, end-use industry verticals, and regional production hub economics. CAGRs derived from slope-consistency checks against historical propylene derivative demand elasticity and regulatory-driven specification upgrade timelines.
Underlying measurement precision varies by segment; ultra-pure electronics-grade and cGMP pharmaceutical batches carry tighter precision than industrial-grade polymer feedstock given certification audit trail availability. Forecasts reflect assumptions around REACH compliance deadline adherence, MEE dual carbon goal enforcement intensity, and propylene spread volatility persistence. Periodic stress-testing of base assumptions is recommended against chlorinated organic emissions abatement cost trajectories and glycerin-based epichlorohydrin technology diffusion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
India Methanol Market
Chemicals
Formalin Market
Chemicals
1, 4 Butanediol Market
Chemicals
Glyoxal Market
Chemicals
Europe Tertiary Amines Market
Chemicals
Fluoroboric Acid Market
Chemicals
Chemical As a Service Market
Chemicals
Phenothiazine Market
Chemicals
Para Cresol Market
Chemicals
Global Phenoxyethanol Market
Chemicals
6 Hexanediol Market
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Calcium Hydride Market
Chemicals
Aluminum Chemicals Market
Chemicals
Global Cresols Market