
 United States Pharmaceutical 3PL Market | 2026-2036
United States Pharmaceutical 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pharmaceutical 3PL Market Analytics
Market Context
Good Distribution Practice certification is reorganizing competitive access in pharmaceutical logistics, raising the barrier to serve FDA-regulated drug shipments. Cencora leverages its specialty pharmacy roots to dominate temperature-controlled distribution for oncology and rare-disease therapies. McKesson Corporation anchors the wholesale-linked 3PL segment through direct integration with hospital purchasing networks. FedEx competes aggressively on time-definite cold-chain delivery, extending its pharma-certified station footprint across domestic hubs.
Technical Definition and Structural Segments
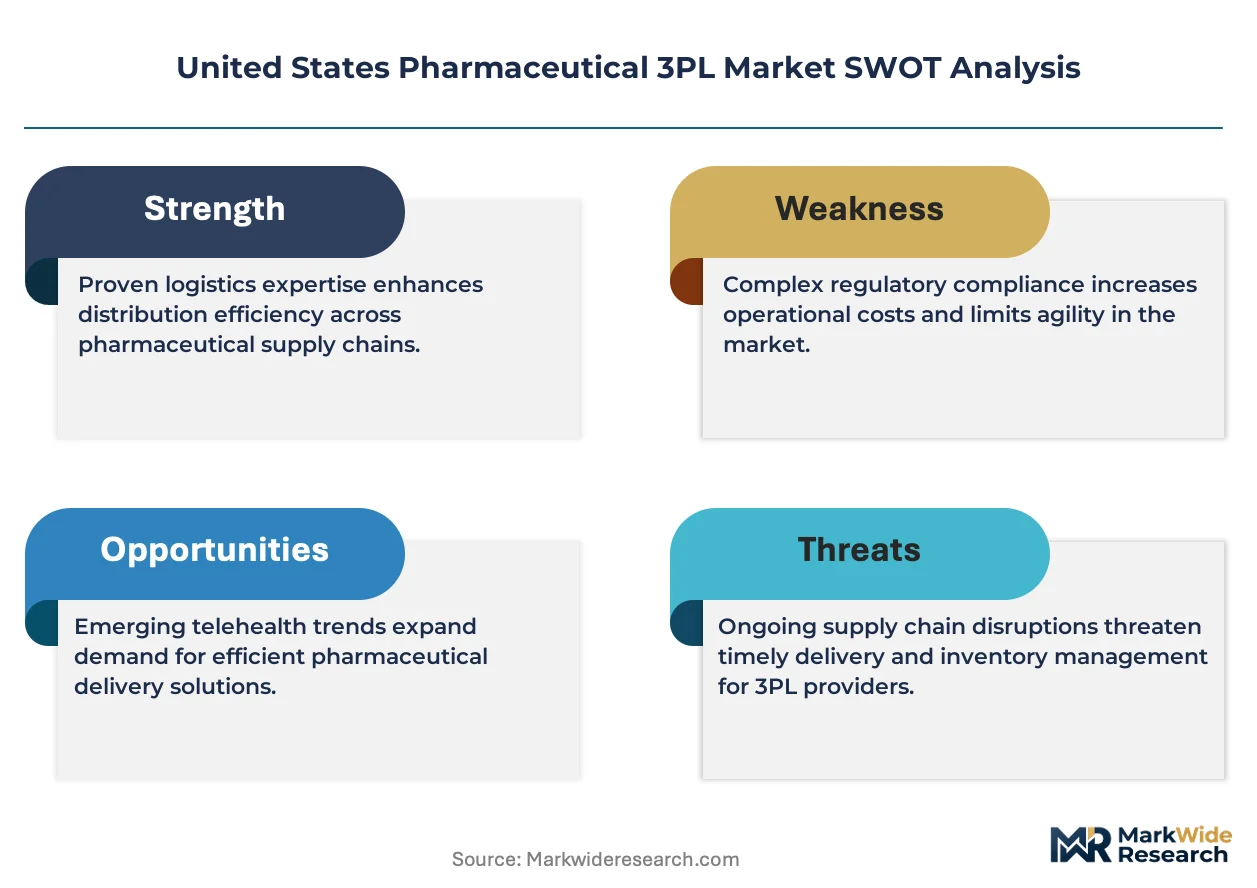
Pharmaceutical third-party logistics encompasses outsourced supply chain management for temperature-sensitive, serialized, and regulated drug products, requiring validated cold-chain infrastructure, real-time track-and-trace capability, and compliance with cGMP distribution standards. The primary commercial purpose centers on reducing capital intensity for drug manufacturers while ensuring chain-of-custody integrity from production through patient administration. Warehousing and cold-chain application segments command the deepest margin pools due to specialized infrastructure requirements, while automation and RFID technology investments are expanding fastest as DSCSA interoperability deadlines force serialization upgrades. Order fulfillment for hospital and clinic end users remains structurally mature, with pricing power concentrated among operators holding VAWD accreditation.
Regulatory Framework and Outlook
FDA enforcement of DSCSA track-and-trace mandates, DEA controlled-substance distribution rules, and state-level pharmacy board licensing requirements collectively determine which 3PL operators can access pharmaceutical freight. HIPAA and state privacy statutes add data-governance layers to logistics platforms handling patient-specific specialty medications. Stakeholders must monitor how FDA guidance on advanced manufacturing and distributed production models reshapes hub-and-spoke distribution requirements for outsourced logistics providers.
Market Dynamics
FDA serialization mandates under DSCSA are forcing wholesale infrastructure replacement across pharmaceutical distribution networks, compressing timelines for 3PL operators to achieve interoperable track-and-trace systems.
Growth Catalysts
- Specialty biologics expansion:Cell and gene therapy manufacturers require validated cold-chain infrastructure that most in-house logistics teams cannot replicate, driving outsourced volume to certified 3PL networks.
- DSCSA interoperability deadlines:The FDA's electronic track-and-trace mandate creates immediate compliance demand for serialization-capable warehouse management systems and data-exchange platforms.
- Northeast manufacturing density:Concentrated FDA-registered drug production across New Jersey, Pennsylvania, and Massachusetts generates captive freight pools that anchor regional 3PL profitability.
Market Restraints
- Refrigeration energy cost volatility:Cold-chain warehouses face margin pressure from electricity rate fluctuations that operators cannot fully pass through in long-term pharma contracts.
- Qualified infrastructure scarcity:Limited availability of cGMP-certified facilities with redundant temperature zones restricts network expansion in high-demand corridors.
- Dry ice supply concentration:Carbon dioxide capture plant outages in the Gulf Coast region disrupt ultra-cold vaccine shipment continuity during peak demand windows.
Strategic Opportunities
- Cell therapy logistics white space:Autologous CAR-T manufacturing requires patient-specific chain-of-custody systems that few 3PLs have deployed, opening premium service tiers.
- IRA domestic manufacturing incentives:Reshoring tax credits for active pharmaceutical ingredient production will expand warehouse demand near new synthesis facilities.
- Real-time location system convergence:Integration of Bluetooth Low Energy beacons with cloud-based temperature monitoring enables predictive intervention before excursions occur.
Industry Challenges
- Pharma-qualified technician scarcity:Recruitment of personnel trained in both cGMP compliance and automated warehouse systems lags facility commissioning schedules.
- Legacy WMS integration friction:DSCSA-mandated serialization upgrades require costly middleware development to connect aging enterprise platforms with new aggregation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pharmaceutical 3PL Market |
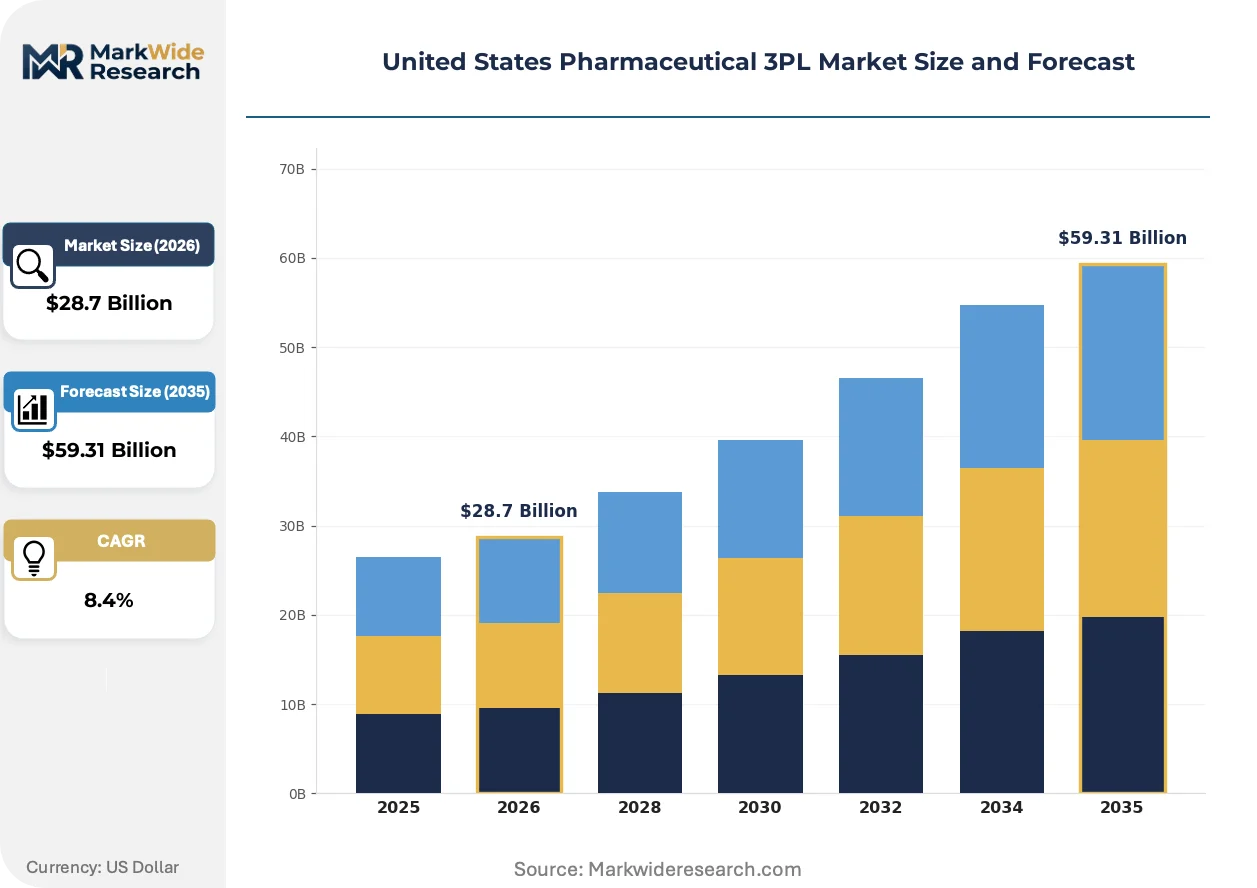
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Order Fulfillment, Inventory Management, Distribution End User: Pharmaceutical Manufacturers, Clinics, Hospitals, Wholesalers Technology: Automation, RFID, Cloud Computing, WMS Application: Cold Chain, Drug Storage, Shipping, Packaging |
| Companies Covered | Kuehne+Nagel, Cencora, DHL Group, McKesson Corporation, Cardinal Health, United Parcel Service, C.H. Robinson, DB Schenker, FedEx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pharmaceutical 3PL Market Evolving Landscape
Automation and sensor technologies are compressing the gap between pharmaceutical production and patient delivery, eliminating manual handoffs that previously introduced temperature excursion risks.
Autonomous mobile robots equipped with integrated temperature sensors are supplanting conventional forklift-based putaway and retrieval in validated warehouses. Specialty oncology distributors are deploying these systems fastest, driven by lot-level traceability requirements for high-value biologics. The shift is compressing labor cost structures while raising the capital barrier for new market entrants.
FDA enforcement discretion letters on advanced manufacturing are reshaping distribution network design for continuous processing facilities. Real-time release testing eliminates traditional quarantine holds, requiring 3PLs to synchronize outbound shipping with production cadence rather than batch-based schedules. Oral solid dose manufacturers with continuous lines are the most affected, pressuring regional warehouses to adopt dock-to-stock automation.
Hospital purchasing cooperatives are consolidating specialty pharmacy referrals to single-source 3PL arrangements, displacing fragmented distributor relationships. Health system GPOs negotiate directly with cold-chain operators for oncology and rare-disease therapies, capturing volume rebates previously retained by wholesale intermediaries. This concentration is most visible in the Mid-Atlantic and Upper Midwest, where integrated delivery networks control substantial specialty medication spend.
United States Pharmaceutical 3PL Market Segmentation
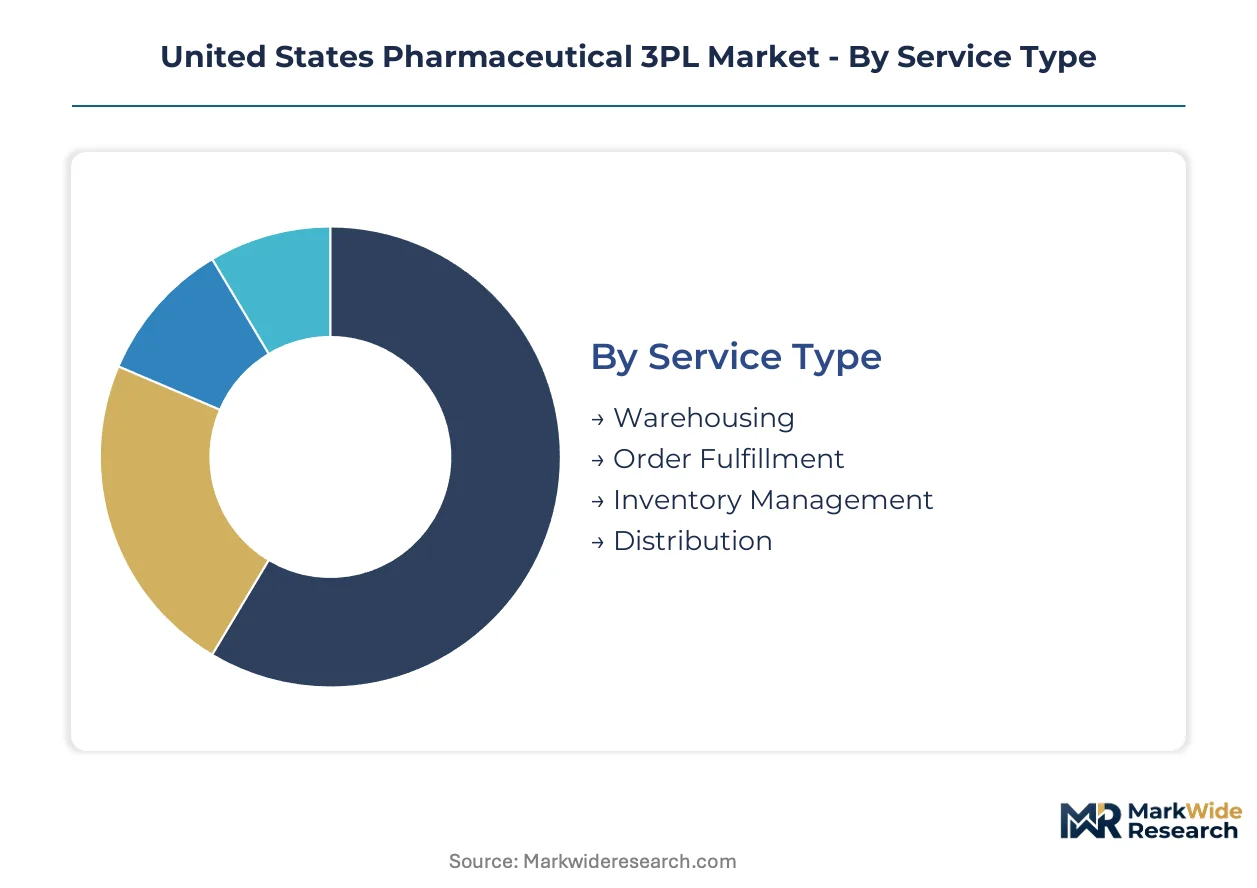
Pharmaceutical 3PL segmentation reveals where capital deployment and regulatory compliance intersect. Service type determines infrastructure intensity, while end-user concentration shapes regional network economics.
Service Type:
Substitute pressure from in-house logistics teams varies sharply across service categories, with some functions proving harder to replicate internally than others.
- Warehousing:Temperature-validated facilities with redundant cold-chain zones require cGMP certification and continuous monitoring infrastructure. Northeast corridor demand from New Jersey and Massachusetts biologics manufacturers absorbs the majority of qualified square footage, constrained by FDA inspection backlogs for new facility approvals.
- Distribution:Time-definite transportation networks with pharma-qualified drivers and serialized chain-of-custody documentation. Hospital purchasing cooperatives in the Mid-Atlantic consolidate volume through fewer distribution partners, compressing intermediary margins.
- Order Fulfillment:Lot-level traceability and patient-specific packaging for specialty therapies.
- Inventory Management:DSCSA-compliant serialization tracking and expiry-date rotation protocols.
Warehousing retains volume leadership; distribution holds the steepest expansion curve.
End User:
Cost tier stratification separates high-complexity specialty logistics from commodity pharmaceutical freight, with accreditation requirements widening the gap.
- Pharmaceutical Manufacturers:Outsourced supply chain management for FDA-regulated production facilities, spanning raw material receipt through finished goods release. Cell and gene therapy producers in Pennsylvania and New Jersey drive demand for patient-specific chain-of-custody systems that in-house teams cannot scale.
- Hospitals:Direct-to-site delivery of temperature-sensitive biologics with dock-to-stock automation requirements. Integrated delivery networks in the Upper Midwest negotiate single-source 3PL arrangements, displacing fragmented distributor relationships.
- Clinics:Smaller-volume specialty medication distribution with higher per-unit handling costs.
- Wholesalers:Bulk consolidation and redistribution with VAWD accreditation mandates.
Pharmaceutical manufacturers command the premium tier; hospitals are climbing fastest on automation requirements.
Technology:
Application maturity separates proven deployments from experimental pilots, with integration costs determining adoption sequencing.
- Automation:Autonomous mobile robots with integrated temperature sensors replacing forklift-based operations in validated warehouses. Oncology distributors deploy these systems fastest, driven by lot-level traceability mandates for high-value biologics.
- RFID:Real-time location tracking with Bluetooth Low Energy beacon integration for predictive excursion intervention.
- WMS:Warehouse management platforms with DSCSA-mandated serialization aggregation and interoperability protocols.
- Cloud Computing:Distributed data architecture for multi-site inventory visibility and regulatory audit trails.
Automation leads capital deployment; RFID is gaining share fastest on sensor convergence.
Application:
Margin concentration follows infrastructure specialization, with temperature requirements creating the steepest differentiation.
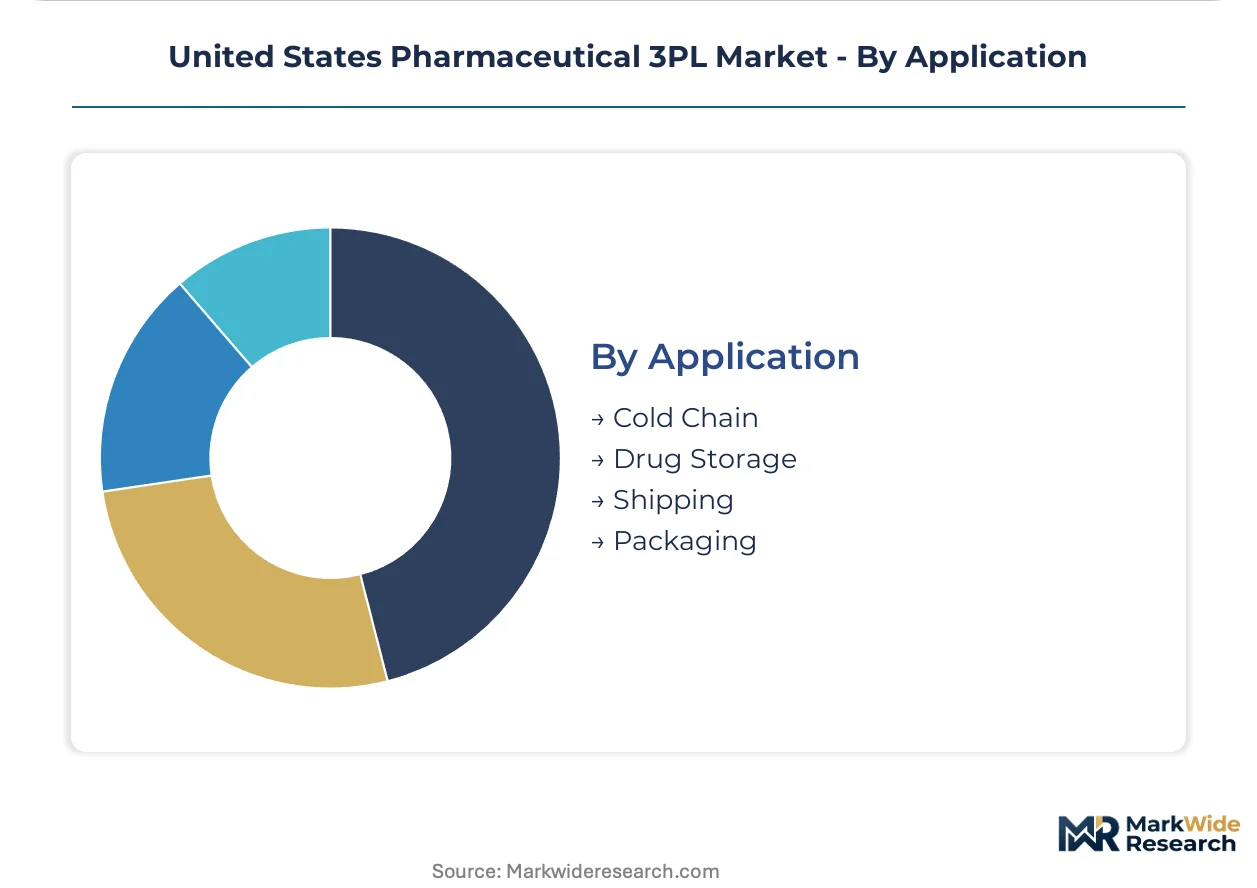
- Cold Chain:Validated transportation and storage infrastructure maintaining 2-8°C, -20°C, and ultra-cold -80°C zones with continuous monitoring. Dry ice supply disruptions from Gulf Coast carbon capture plant outages expose vulnerability in vaccine shipment continuity.
- Drug Storage:cGMP-compliant warehousing with quarantine segregation and real-time release testing synchronization for continuous manufacturing facilities.
- Shipping:Time-definite delivery with temperature excursion liability and chain-of-custody documentation.
- Packaging:Patient-specific labeling and serialization aggregation for DSCSA compliance.
Cold chain captures the deepest margins; drug storage is expanding most quickly on continuous manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA DSCSA compliance deadlines and IRA domestic manufacturing incentives are redistributing pharmaceutical logistics capacity toward states with dense biologics production clusters and qualified cold-chain infrastructure.
Northeast Corridor
New Jersey, Pennsylvania, and Massachusetts host the densest concentration of FDA-registered drug manufacturers in the United States. DSCSA serialization mandates force wholesale infrastructure replacement across this corridor, compressing timelines for 3PL operators to achieve interoperable track-and-trace systems. The I-95 pharmaceutical belt from Trenton to Boston anchors regional profitability through captive freight pools generated by specialty biologics manufacturers.
Southeast
Florida and Georgia are emerging as distribution hubs for temperature-sensitive cell therapies targeting the Sun Belt's expanding hospital networks. State pharmacy board licensing requirements in Florida add compliance layers for logistics platforms handling patient-specific specialty medications. The Miami-Dade cold-chain corridor serves Latin American export routes while supporting domestic oncology distribution.
Midwest
Illinois and Ohio benefit from hospital purchasing cooperative consolidation that concentrates specialty pharmacy referrals to single-source 3PL arrangements. Integrated delivery networks in the Upper Midwest negotiate directly with cold-chain operators, capturing volume rebates previously retained by wholesale intermediaries. Chicago's central rail and air infrastructure supports hub-and-spoke distribution for continuous manufacturing facilities.
Texas
The Houston-Dallas corridor leverages energy sector logistics expertise to address dry ice supply vulnerabilities affecting ultra-cold vaccine shipments. Carbon dioxide capture plant concentration in the Gulf Coast region exposes shipment continuity risks during peak demand windows. Texas Medical Center density drives demand for patient-specific chain-of-custody systems in autologous CAR-T logistics.
California
The San Francisco Bay Area and San Diego biotech clusters generate premium cold-chain demand for gene therapy clinical trials and commercial distribution. California's energy cost volatility pressures cold-chain warehouse margins that operators cannot fully pass through in long-term pharma contracts. The state's advanced manufacturing initiatives reshape distribution network design for continuous processing facilities requiring real-time release testing synchronization.
United States Pharmaceutical 3PL Market Competitive Landscape
Player mix skews toward wholesale-integrated distributors and express carriers with pharma-certified infrastructure. Market structure concentrates among operators holding VAWD accreditation and cGMP-certified facilities, creating tiered access based on regulatory compliance depth. Two strategic archetypes dominate: wholesale-linked 3PLs leveraging hospital purchasing networks, and time-definite carriers competing on cold-chain delivery speed. Competitive moves center on DSCSA-mandated serialization upgrades and autonomous warehouse automation deployments.
Within the wholesale-integrated tier, McKesson Corporation and Cardinal Health exemplify operators anchoring distribution through direct hospital network integration. Cencora occupies a position representing specialty pharmacy-rooted dominance in temperature-controlled oncology and rare-disease logistics. Among express carriers with pharma-certified station footprints, FedEx and United Parcel Service sit within the time-definite delivery archetype, competing on serialized chain-of-custody documentation and temperature excursion liability. DHL Group and Kuehne+Nagel represent European-headquartered 3PLs with established United States pharmaceutical infrastructure, while C.H. Robinson and DB Schenker exemplify freight forwarders expanding validated cold-chain capabilities.
| Leading Market Players |
|---|
| Kuehne+Nagel |
| Cencora |
| DHL Group |
| McKesson Corporation |
| Cardinal Health |
| United Parcel Service |
| C.H. Robinson |
| DB Schenker |
| FedEx |
| Others |
Value Network & Pricing Analysis
Cold-chain warehouse utilization rates above 85 percent in the Northeast corridor generate scale economies that compress per-unit handling costs while establishing price floors for new market entrants. FDA cGMP certification backlogs constrain qualified facility supply, allowing incumbent operators to command premium contract terms from specialty biologics manufacturers seeking validated infrastructure.
Pricing Analysis
Certification level creates the primary spread between contract tiers, with VAWD-accredited and cGMP-certified operators capturing 40-60 percent handling premiums over general freight equivalents. Three-tier pricing structure across certified cold-chain, standard temperature-controlled, and ambient pharmaceutical logistics reflects infrastructure investment differentials. Cost compression in the ambient tier is intensifying because hospital purchasing cooperatives consolidate volume through single-source arrangements. Generic drug distributors exhibit the highest price sensitivity, while cell and gene therapy manufacturers prioritize chain-of-custody integrity over unit economics.
Supply Chain Analysis
Inventory velocity requirements for continuous manufacturing facilities have compressed lead times from batch-based quarantine holds to dock-to-stock synchronization measured in hours rather than days. Domestic pharmaceutical logistics draws from concentrated FDA-registered manufacturing clusters in New Jersey, Pennsylvania, and Massachusetts, with secondary capacity emerging in Texas and California. Dry ice supply from Gulf Coast carbon capture plants represents a critical single-source vulnerability for ultra-cold vaccine distribution. Distribution runs through hub-and-spoke networks anchored by regional cold-chain warehouses with last-mile delivery via pharma-qualified courier fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Serialization compliance services and real-time temperature monitoring subscriptions are expanding faster than baseline warehousing revenue, creating service-attach opportunities that compound customer lifetime value beyond transactional freight margins.
For Market Incumbents: Shield market position by accelerating autonomous mobile robot deployment in validated warehouses before DSCSA interoperability deadlines crystallize competitive differentiation. Acquire cGMP-certified facilities in the I-95 corridor to preempt qualified infrastructure scarcity from tightening FDA inspection backlogs. Vertical integration into patient-specific packaging services captures margin pools that wholesale intermediaries currently retain. For New Entrants and Emerging Players: Autologous CAR-T chain-of-custody systems represent a service-layer gap where incumbent 3PLs under-serve patient-specific logistics requirements. Target the Southeast corridor, where Florida and Georgia hospital network expansion outpaces established cold-chain capacity. Lead with Bluetooth-enabled real-time location systems as a differentiated technology wedge rather than competing on warehouse scale. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with deployed serialization infrastructure and established FDA enforcement discretion relationships. Five-to-ten year viability hinges on automation capital efficiency rather than facility count expansion. Monitor FDA guidance on distributed manufacturing and advanced production models as the primary inflection signal for hub-and-spoke network redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| DSCSA Serialization Infrastructure Deployment | FDA-mandated electronic track-and-trace compliance creates immediate upgrade demand across wholesale networks. |
| Autonomous Mobile Robot Integration | Oncology distributors deploy sensor-equipped AMRs fastest to satisfy lot-level biologics traceability requirements. |
| Patient-Specific Chain-of-Custody Systems | Autologous cell therapy logistics opens premium service tiers with limited qualified competitor presence. |
| Continuous Manufacturing Synchronization | Real-time release testing eliminates quarantine holds, requiring dock-to-stock automation investment. |
| Single-Source Hospital GPO Arrangements | Integrated delivery network consolidation displaces fragmented distributor relationships in the Upper Midwest. |
Research Methodology
A spread of perspectives from pharmaceutical logistics directors, regulatory compliance officers, hospital procurement managers, and cold-chain operations heads converged on the working assumptions driving facility utilization and pricing power estimates. Primary fieldwork with 3PL network planners and FDA policy specialists combined with secondary validation against FDA DSCSA guidance documents, DEA controlled-substance distribution records, state pharmacy board licensing databases, and hospital GPO contract disclosures. Bottom-up capacity modeling across cGMP-certified facilities triangulated against top-down pharmaceutical production value flows.
Segmentation dimensions modeled include service type, end-user category, technology application, and temperature requirement tier, cross-referenced with regional manufacturing density and regulatory compliance cluster. CAGRs were derived from facility commissioning schedules, DSCSA deadline impact assessment, and specialty biologics pipeline expansion trajectories. Patient-specific therapy volume forecasts and continuous manufacturing adoption curves provided industry-specific demand inputs across the projection horizon.
Underlying assumptions cover stable FDA enforcement discretion on advanced manufacturing, IRA domestic production incentive continuity, and dry ice supply chain resilience, with deviation risk concentrated in carbon capture plant outages and electricity rate volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Antibodies Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Placental Protein Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
US Hormone Replacement Therapy Market
Pharmaceuticals
US Generic Injectables Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Erectile Dysfunction Market