
 Wood Floor Grinding Machine Market | 2026-2036
Wood Floor Grinding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Floor Grinding Machine Market Analytics
Multi-source procurement among rental fleets and contractor cooperatives is expanding as buyers seek equipment availability across seasonal demand cycles. Husqvarna Group leverages its integrated battery platform to cross-sell dust extractors and grinders through unified dealer networks. Tyrolit Group anchors its position through specialized diamond tooling that pairs with OEM-agnostic machine mounts. SASE Company competes on aftermarket parts accessibility, sustaining repeat revenue from independent flooring contractors across North American metropolitan markets.
A wood floor grinding machine is a motorized surface preparation device employing rotating abrasive heads—typically 200-400 mm in diameter operating at 300-1,500 RPM—to remove existing finishes, level subfloors, and expose bare timber for refinishing. Walk-behind units dominate rental channel inventories due to operator safety and transportability, while ride-on configurations capture margin pools in large-scale commercial and industrial deployments where labor cost reduction drives fleet decisions. Diamond abrasive technology leads technology segmentation for hardwood refinishing applications, displacing silicon carbide in premium contractor segments where finish quality and tool longevity determine total cost of ownership.
OSHA silica exposure limits and EPA regional haze regulations shape dust-collection system specifications, compelling manufacturers to integrate HEPA filtration as standard rather than optional equipment. The EU F-Gas Regulation and REACH chemical restrictions influence abrasive bonding agent formulations imported into European markets. Stakeholders must monitor evolving cordless power platform standards and regional certification requirements for battery-operated industrial equipment as electrification commitments from major construction markets redefine product roadmaps and distribution investments.
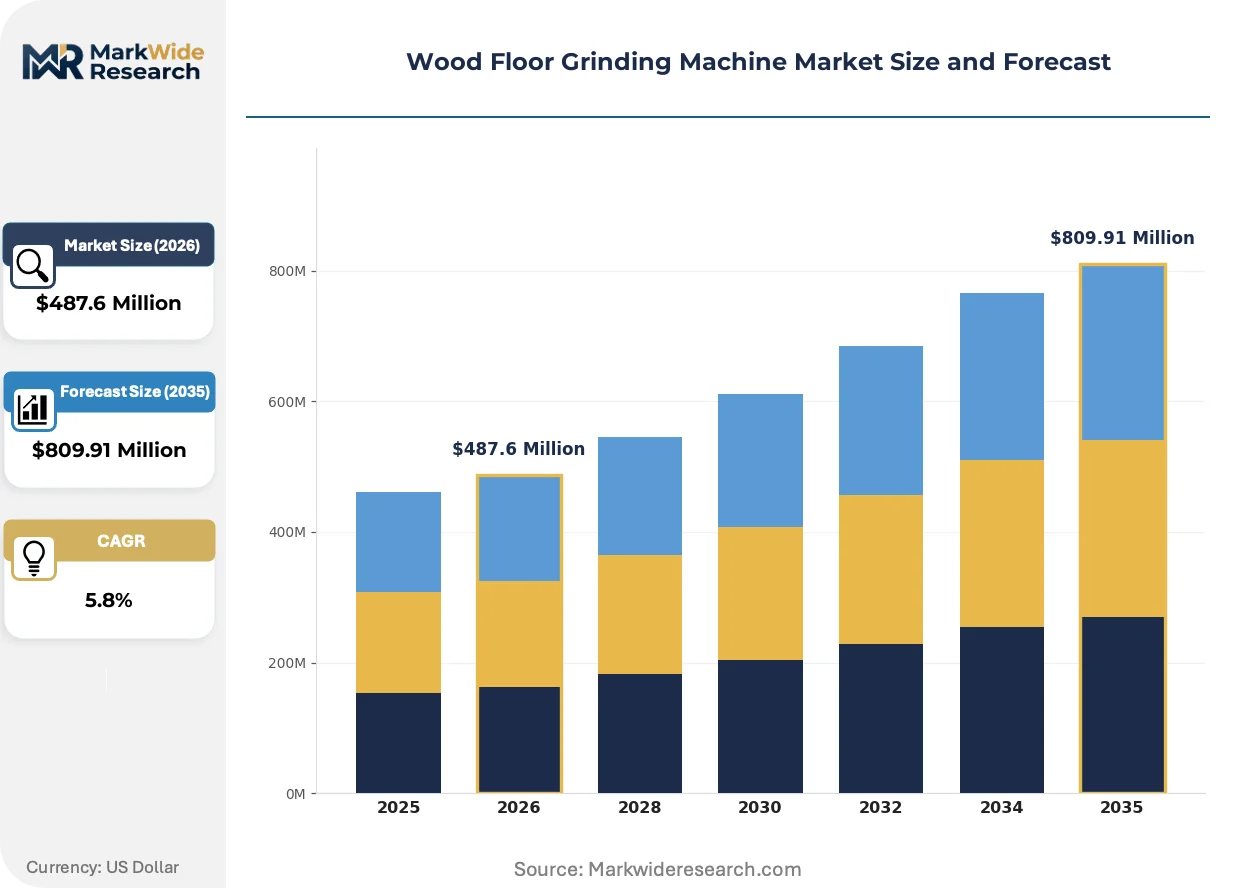
Market Dynamics
LEED certification mandates and silica exposure enforcement are compressing equipment replacement cycles while battery platform standardization is redrawing supplier loyalty patterns across contractor fleets.
Growth Catalysts
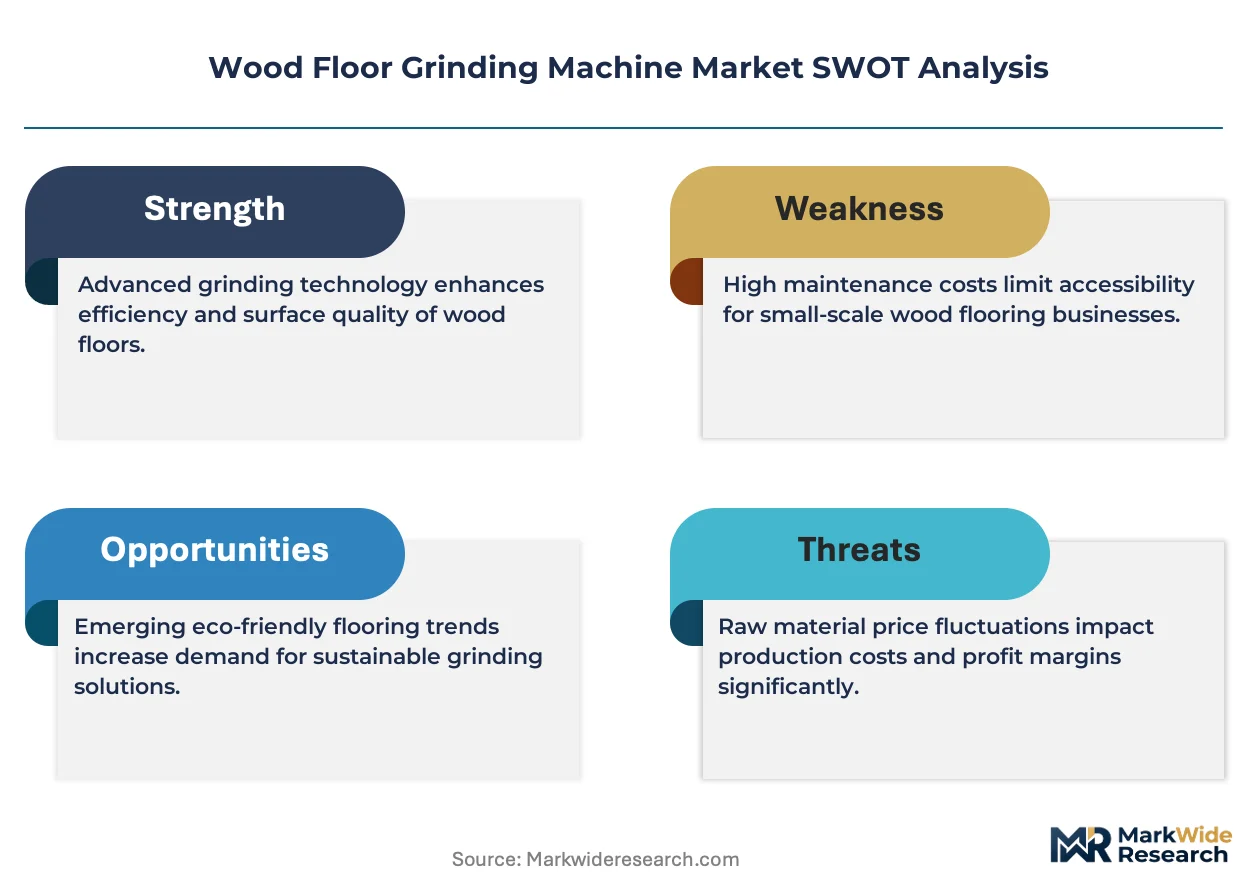
- OSHA silica rule enforcement:Commercial property managers in the United States face mandatory dust-collection upgrades, accelerating grinder fleet turnover in multi-site maintenance operations.
- Battery platform convergence:Unified 18V-54V cordless ecosystems are reducing total cost of ownership for flooring contractors managing mixed equipment portfolios.
- Hardwood restoration demand:Heritage building renovation pipelines in Germany and Austria are sustaining premium diamond abrasive consumption for parquet refinishing.
Market Restraints
- Copper and rare-earth input volatility:Permanent magnet motor costs fluctuate with Chinese export quotas, compressing margins on battery-powered grinder SKUs.
- HEPA filtration compliance costs:EPA regional haze regulations and EU F-Gas bonding agent restrictions add certification overhead for abrasive imports.
- Surface preparation robot substitution:Autonomous floor-scraping systems threaten walk-behind grinder rental volumes in large-format retail and logistics warehouse deployments.
Strategic Opportunities
- India commercial real estate buildout:LEED-India and GRIHA certification adoption in Mumbai and Bangalore office stock creates first-mover positioning for dust-integrated grinder suppliers.
- Equipment-as-a-service models:Subscription-based maintenance-inclusive leasing is penetrating North American metropolitan contractor cooperatives.
- EU Green Deal renovation wave:Building performance standards across member states mandate floor-level energy efficiency upgrades, linking grinder demand to insulation retrofit timelines.
Industry Challenges
- Diamond tooling technician scarcity:Specialized abrasive mounting and segment replacement skills are concentrating among aging European contractor workforces.
- Battery interoperability certification delays:Regional safety standards for industrial cordless equipment fragment platform roadmaps across export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Floor Grinding Machine Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-Behind, Ride-On, Handheld, Edger Technology: Diamond Abrasive, Silicon Carbide, Ceramic, Resin Bond Application: Residential, Commercial, Industrial, Hardwood Refinishing End User: Flooring Contractors, Homeowners, Property Managers, Woodworkers |
| Companies Covered | Husqvarna Group, Tyrolit Group, SASE Company, Terrco Inc., Scanmaskin Sverige AB, Achilli S.r.l., Klindex s.r.l., National Flooring Equipment, Bartell Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Floor Grinding Machine Market Evolving Landscape
Electrification and connected fleet management are compressing equipment procurement cycles while regulatory enforcement hardens dust-control specifications as baseline rather than premium features.
Brushless DC motor architecture paired with lithium-iron-phosphate battery packs is decentralizing power distribution in walk-behind grinder designs. Regional rental fleets in Germany and the United States are standardizing on swappable battery configurations to eliminate generator transport. This shift is decentralizing maintenance revenue from engine rebuilds toward cell replacement and firmware update streams.
REACH chemical restrictions on abrasive bonding agents are forcing reformulation of phenolic resin matrices used in diamond segment production. European importers now require third-party toxicity documentation for tooling sourced from Asian manufacturers. Hardwood refinishing contractors in Austria and Switzerland face extended procurement lead times as bonded abrasive suppliers requalify supply chains.
Multi-source equipment procurement through digital rental marketplaces is fragmenting traditional dealer relationships. Flooring contractor cooperatives in North American metropolitan markets aggregate seasonal demand across member fleets, bypassing single-brand distribution agreements. This pattern concentrates price transparency pressure in Chicago, Toronto, and Dallas-Fort Worth where cooperative membership exceeds five hundred active contractors.
Wood Floor Grinding Machine Market Segmentation
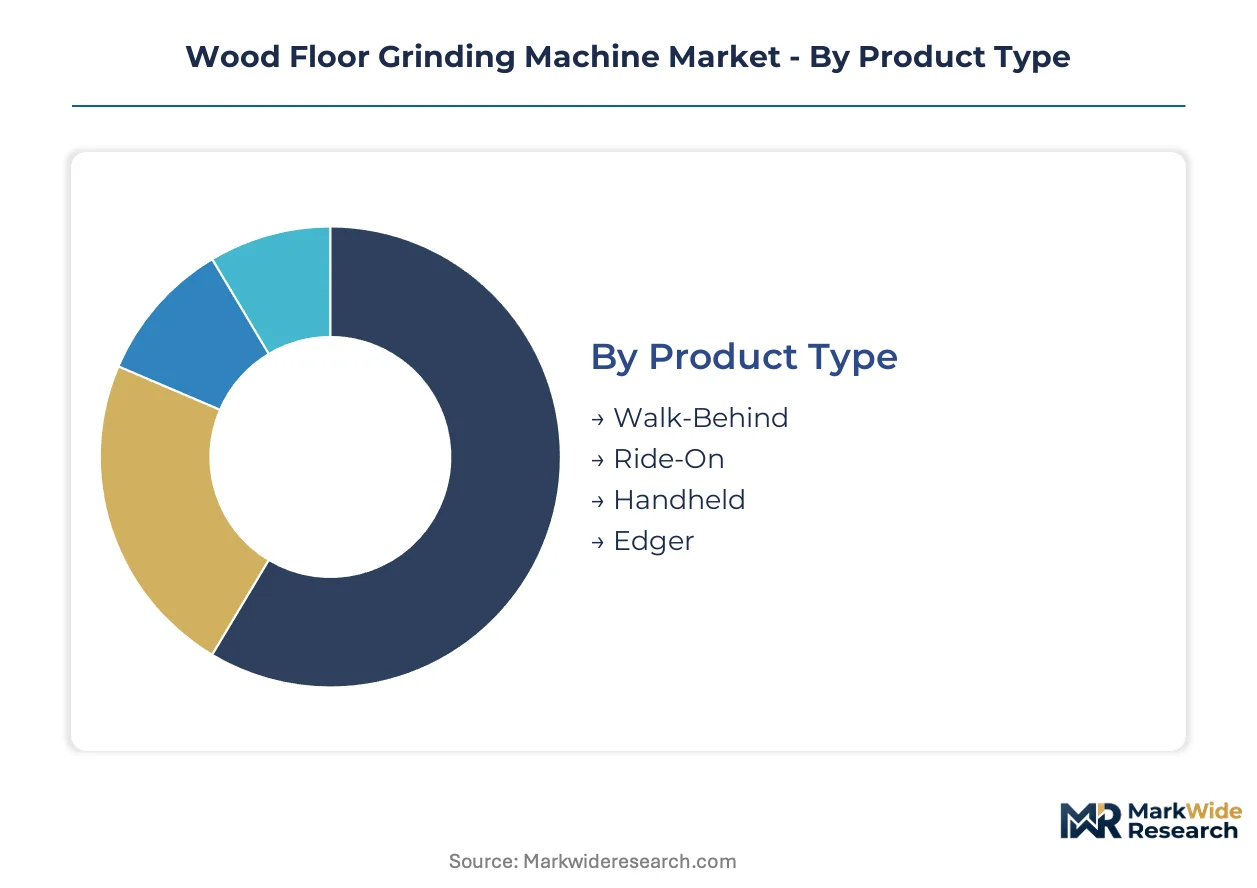
Equipment replacement cycles vary dramatically across grinder configurations, with regulatory pressure and labor economics forcing divergent upgrade timelines for walk-behind versus ride-on fleets. Segmentation reveals how dust-extraction mandates and battery platform investments are redrawing procurement priorities among contractor segments.
Product Type:
Upgrade cycles compress where OSHA silica enforcement and rental fleet standardization converge, stretching replacement intervals where corded equipment dominates legacy inventories.
- Walk-Behind:Units spanning 200-400 mm abrasive heads at 300-1,500 RPM dominate rental channel inventories across Germany and the United States. Demand concentrates among flooring contractor cooperatives in Chicago and Dallas-Fort Worth where transportability and operator safety certification ease seasonal staffing fluctuations.
- Ride-On:Configurations with 600-1,000 mm working widths capture margin pools in large-format retail and logistics warehouse deployments. Property managers at multi-site commercial portfolios in California and Texas prioritize these units where labor cost reduction drives fleet decisions across 50,000+ square foot refinishing contracts.
- Handheld:Compact units serve edge work and stair refinishing where walk-behind access proves impossible.
- Edger:Specialized perimeter equipment pairs with primary grinders in hardwood restoration pipelines across Austrian heritage building renovations.
Walk-Behind sits at the top of the volume ranking, with Ride-On climbing the fastest as commercial property managers consolidate multi-site maintenance contracts.
Technology:
Cost tier separation sharpens where tool longevity and finish quality determine total cost of ownership across premium contractor segments versus price-sensitive rental channels.
- Diamond Abrasive:Synthetic diamond segments bonded to metal matrices deliver 10-20x tool life versus conventional abrasives. REACH chemical restrictions on phenolic resin bonding agents are forcing European importers to requalify Asian supply chains, extending procurement lead times for hardwood refinishing contractors in Austria and Switzerland.
- Silicon Carbide:Conventional abrasive technology retains position in economy-tier rental fleets and homeowner-grade equipment. Cost volatility in Chinese silicon carbide production is compressing margins for OEMs serving North American big-box retail channels.
- Ceramic:Alumina-zirconia blends occupy mid-tier positioning for contractors balancing performance and consumable cost.
- Resin Bond:Polymer-matrix bonding systems face reformulation pressure under EU F-Gas Regulation and REACH toxicity documentation requirements.
Diamond Abrasive commands the premium tier by margin contribution, with Ceramic gaining share fastest among mid-cap flooring contractors seeking performance upgrades without full premium positioning.
Application:
Volume concentration tracks renovation spending intensity, with certification mandates and building age profiles dictating equipment specification requirements across end-use segments.
- Commercial:Office, hospitality, and retail floor maintenance drives demand for dust-integrated systems meeting LEED-certified building standards. Property managers in Mumbai and Bangalore are expanding equipment fleets as LEED-India and GRIHA certification adoption accelerates in commercial real estate buildouts.
- Hardwood Refinishing:Heritage building restoration and premium residential parquet work sustains diamond abrasive consumption. German and Austrian renovation pipelines favor specialized tooling for engineered and solid hardwood surfaces where finish quality determines contractor reputation.
- Residential:Single-family and multi-family refinishing projects concentrate in suburban metropolitan markets with housing stock turnover.
- Industrial:Manufacturing and warehouse floor preparation demands ride-on configurations with extended duty cycles.
Commercial leads absolute volume, with Hardwood Refinishing expanding most quickly as EU Green Deal renovation wave mandates link floor-level upgrades to building performance standards.
End User:
Customer type stratification reflects equipment utilization rates, with professional contractors driving technology adoption and homeowners remaining price-sensitive in sporadic purchase patterns.
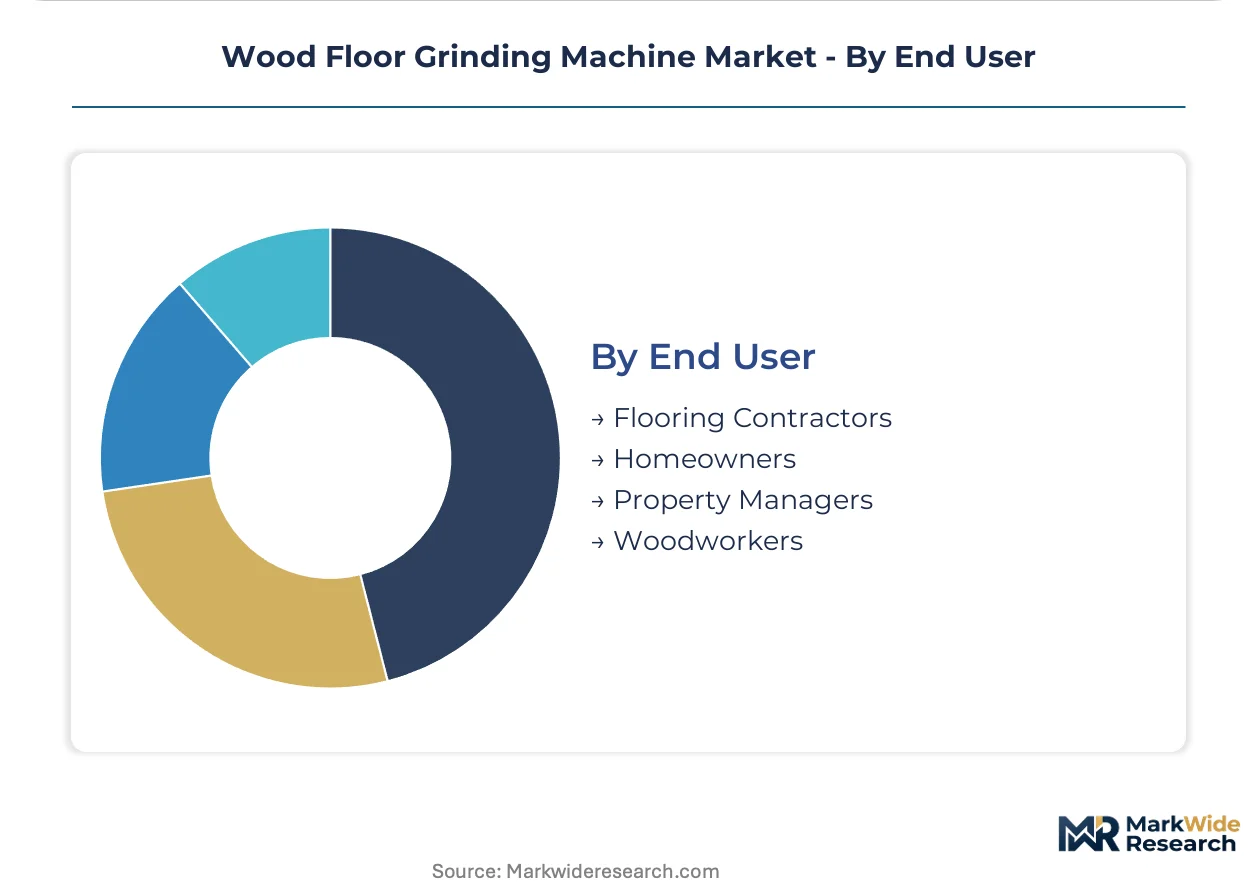
- Flooring Contractors:Independent and cooperative members manage mixed equipment portfolios across seasonal demand cycles. North American metropolitan cooperatives aggregate procurement through digital rental marketplaces, fragmenting traditional dealer relationships in Toronto and Chicago where membership exceeds five hundred active contractors.
- Property Managers:Multi-site commercial and residential portfolio operators standardize fleets to reduce training and maintenance complexity. Silica exposure enforcement by OSHA is accelerating grinder turnover in United States multi-site maintenance operations.
- Homeowners:DIY refinishing projects drive handheld and small walk-behind sales through retail channels.
- Woodworkers:Specialty craftsmen require precision edge equipment for custom installation and restoration work.
Flooring Contractors anchor the volume base, with Property Managers gaining procurement influence fastest as commercial portfolio consolidation centralizes equipment decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German flooring equipment clusters anchor renovation demand across heritage building corridors. Battery platform standardization and silica enforcement are redrawing procurement geography toward regulatory-lead markets.
Germany
Heritage parquet restoration in Bavaria and Baden-Württemberg sustains premium abrasive consumption. EU F-Gas Regulation and REACH bonding agent restrictions force requalification of Asian supply chains. Stuttgart-based contractor cooperatives aggregate seasonal demand through digital procurement platforms.
United States
OSHA silica rule enforcement accelerates grinder turnover in multi-site commercial maintenance. EPA regional haze regulations mandate HEPA filtration integration as baseline specification. Chicago and Dallas-Fort Worth metropolitan cooperatives fragment traditional dealer relationships through aggregated procurement.
China
Commercial real estate buildout in Shanghai and Shenzhen drives equipment fleet expansion. GB standards for industrial cordless equipment fragment battery platform roadmaps across export markets. Guangdong manufacturing clusters supply diamond abrasive segments to European importers facing REACH documentation requirements.
India
LEED-India and GRIHA certification adoption in Mumbai and Bangalore office stock creates first-mover positioning for dust-integrated suppliers. BIS equipment safety standards intersect with state-level building codes. Maharashtra-based property managers standardize fleets across multi-site commercial portfolios.
Austria
Vienna heritage building renovation pipelines sustain specialized diamond tooling demand for engineered hardwood surfaces. REACH chemical restrictions extend procurement lead times for bonded abrasive imports. Salzburg contractor workforces concentrate specialized abrasive mounting skills among aging technician pools.
Wood Floor Grinding Machine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue battery platform specialization and dust-extraction integration. Market structure reflects moderate consolidation around integrated tooling suppliers and fragmented regional fabrication. Three archetypes dominate: full-system integrators bundling extractors and grinders; specialized abrasive manufacturers with OEM-agnostic mounts; and aftermarket-focused service networks sustaining repeat revenue. Capacity expansion and strategic partnerships represent the dominant competitive vectors.
Among Nordic-origin equipment fabricators, Scanmaskin Sverige AB exemplifies the integrated-system archetype through unified battery and dust-extraction platforms. Klindex s.r.l. occupies a position within the specialized tooling tier, reflecting Italian precision manufacturing heritage. National Flooring Equipment anchors the North American service-network model, sustaining contractor relationships through parts accessibility and metropolitan distribution density.
| Leading Market Players |
|---|
| Husqvarna Group |
| Tyrolit Group |
| SASE Company |
| Terrco Inc. |
| Scanmaskin Sverige AB |
| Achilli S.r.l. |
| Klindex s.r.l. |
| National Flooring Equipment |
| Bartell Global |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in German and Austrian heritage restoration markets anchor premium pricing discipline through captive diamond tooling production and long-term contractor relationships. Their ownership structure insulates margin pools from quarterly earnings pressure while sustaining investment in REACH-compliant abrasive bonding formulations.
Pricing Analysis
Copper and rare-earth input volatility passes through to battery-powered grinder SKUs with 3-6 month lag structures, compressing margins on cordless units faster than corded equivalents. Three-tier pricing structure across premium, standard, and economy levels separates diamond abrasive systems with HEPA integration from silicon carbide rental fleet units and handheld homeowner equipment. Price differentiation hinges on certification grade—OSHA silica compliance and EU F-Gas bonding agent documentation—and volume scale in cooperative procurement. Pricing pressure stems from Chinese silicon carbide cost volatility and permanent magnet motor quota uncertainty. Rental channel buyers in North American metropolitan markets exhibit highest price sensitivity, while heritage restoration contractors in Bavaria and Vienna prioritize tool longevity over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from multi-site commercial property managers, while independent dealer networks serve fragmented flooring contractor cooperatives. Manufacturing concentrates in Germany, China, and Italy, with Guangdong clusters supplying diamond abrasive segments and Stuttgart-area fabricators producing precision grinder chassis. Raw material dependencies span copper windings, lithium-iron-phosphate battery cells, and phenolic resin bonding agents. Supply chain risk centers on REACH documentation requirements extending procurement lead times for Asian abrasive imports. Distribution runs through unified dealer networks for integrated system vendors and digital rental marketplaces fragmenting traditional channel control in Chicago and Toronto.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wood floor grinding machine demand functions as a stable compounder, with regulatory enforcement of silica exposure limits and LEED certification mandates driving predictable equipment replacement cycles across commercial property portfolios.
For Market Incumbents: Deepen backward integration into diamond abrasive production to capture tooling margin pools and insulate supply chains from REACH requalification delays. Expand battery platform standardization investments to lock in contractor fleet loyalty before interoperability certification fragments cordless ecosystems. Prioritize HEPA filtration R&D to maintain specification leadership as EPA regional haze regulations harden dust-control baselines. For New Entrants and Emerging Players: Independent flooring contractors in India's LEED-India buildout represent the most penetrable buyer archetype, with Mumbai and Bangalore property managers standardizing fleets ahead of established vendor relationships. Target dust-integrated grinder supply gaps in Maharashtra commercial portfolios through equipment-as-a-service subscription models. Pursue first-mover positioning in GRIHA-certified building maintenance before incumbent distribution networks consolidate. For Investors and Strategic Acquirers: Construction equipment rental consolidators are the most active acquirer in this space, seeking aftermarket service density and battery platform assets. Long-term viability rests on regulatory tailwinds for silica compliance and electrification mandates sustaining replacement demand. Target specialized abrasive manufacturers with OEM-agnostic mounting systems and REACH-qualified supply chains. Watch battery interoperability certification timelines as inflection indicator for platform consolidation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Unified 18V-54V ecosystems reduce contractor total cost of ownership across mixed fleets. |
| HEPA Filtration Integration | OSHA silica enforcement and EPA regional haze regulations mandate dust-control as baseline specification. |
| Backward Integration into Tooling | Captive diamond abrasive production insulates margins from REACH requalification delays. |
| Equipment-as-a-Service Launch | Subscription maintenance-inclusive leasing penetrates North American metropolitan contractor cooperatives. |
| REACH-Compliant Supply Chain Requalification | Third-party toxicity documentation requirements extend procurement lead times for European importers. |
Research Methodology
Bottom-up flooring contractor demand modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with maintenance directors at multi-site commercial portfolios, aftermarket service heads at rental fleet operators, OEM procurement teams, and diamond tooling technicians were validated against secondary sources including OSHA enforcement databases, EU ECHA REACH registrations, and SEC filings from construction equipment manufacturers. Trade flow data from German and Chinese customs authorities and BIS equipment safety standard disclosures provided supply-side calibration.
Input-output matrix framing links abrasive consumption rates to grinder fleet deployment across walk-behind, ride-on, and handheld configurations. Segmentation dimensions span product type, abrasive technology tier, application end-use, and end-user archetype across the analysis window. CAGRs were derived from equipment replacement cycle compression rates and regulatory enforcement timelines. Forecast inputs incorporate LEED certification adoption curves, silica rule compliance deadlines, and battery platform migration patterns.
Inputs from primary fieldwork and regulatory filing databases were available through the study window; gaps in real-time contractor cooperative procurement data introduce uncertainty bands around rental channel volume estimates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and battery chemistry cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Europe Stump Cutter/Grinder Market
Tools
Sanding Machine Market
Tools
Flooring Tools Market
Tools
Multi Spindle Machines Market
Tools
Power Drill Market
Tools
Tool Hammer Market
Tools
Portable Heat Press Machine Market
Tools
Aluminum Folding Ladders Market
Tools
Belt File Sander Market
Tools
Woodcarving Tool Market
Tools
Surface Planer Market
Tools
Shredder Blades Market
Tools
Nail Gun Market
Tools
Vertical Milling Machine Market
Tools
Concrete Saw Market
Tools
Gear Honing Machines Market