
 Digital Oil Rigs Market | 2026-2036
Digital Oil Rigs Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Oil Rigs Market Outlook
Aftermarket service revenue is reconfiguring margin pools across the digital oilfield value chain. SLB leverages its integrated drilling portfolio to capture recurring software licensing income from offshore operators. Halliburton anchors its position through dense sensor networks and edge-computing deployments on floating rigs. Baker Hughes Company differentiates via turbine-to-bit digital threads that sustain long-term service contracts.
A digital oil rig integrates industrial IoT sensors, SCADA systems, and AI-driven control loops to automate drilling parameters, maintain wellbore stability, and optimize rate of penetration in real time. Its primary purpose is to reduce non-productive time and enhance safety through remote monitoring of downhole conditions. The technology dimension spans IoT, AI, and machine learning, with machine learning representing the fastest-expanding layer as operators train models on historical failure data. Application segments cluster around predictive maintenance and real-time monitoring, where margin pools deepen for vendors offering integrated diagnostics rather than point solutions.
The US Coast Guard enforces safety regulations for offshore installations, while the Bureau of Safety and Environmental Management mandates blowout preventer testing protocols that digital systems must document automatically. IEC 61508 and API RP 75 shape functional safety requirements for automated drilling controls, creating compliance barriers for non-certified entrants. Stakeholders must weigh the capital cost of full-stack digital integration against modular upgrades that preserve operational flexibility.
Market Dynamics
Offshore operators face mounting pressure from IEC 61508 functional safety mandates that force wholesale replacement of legacy control systems rather than incremental upgrades, compressing vendor qualification timelines and reshaping procurement risk allocation.
Growth Catalysts
- API RP 75 Blowout Preventer Protocols:Automated documentation requirements under US Bureau of Safety and Environmental Enforcement rules are compelling rig operators to deploy integrated sensor-to-cloud architectures that capture real-time BOP test data.
- Deepwater Project Density:The US Gulf Coast concentration of high-pressure high-temperature wells is driving demand for AI-driven wellbore stability systems that reduce non-productive time in formations where traditional manual control fails.
- Edge Computing Maturation:Latency-sensitive drilling parameter optimization is pulling compute resources onto floating platforms, creating infrastructure pull-through for ruggedized hardware vendors serving harsh marine environments.
Market Restraints
- Specialized Component Supply Concentration:Subsea-rated pressure sensors and fiber-optic telemetry modules rely on a narrow base of North Sea and Norwegian suppliers, exposing procurement to marine logistics bottlenecks.
- Functional Safety Certification Costs:IEC 61508 SIL 3 validation for automated drilling controls demands 18-24 month qualification cycles that freeze out non-incumbent vendors lacking capital reserves for sustained compliance investment.
- Legacy SCADA Interoperability:Proprietary communication protocols from 1990s-era distributed control systems create technical debt that resists API standardization, forcing expensive gateway layers or full-stack replacement.
Strategic Opportunities
- Brazil Pre-Salt Development:Petrobras-led ultra-deepwater projects in the Santos Basin are procuring integrated digital drilling platforms with 15-year service contracts, opening recurring revenue streams for full-stack vendors.
- Digital Twin Convergence:Physics-based simulation is merging with machine learning failure prediction to create unified asset models that span design, construction, and operational phases of rig lifecycle management.
- US Inflation Reduction Act Methane Monitoring:Tax credit eligibility now requires continuous emissions verification, pulling optical gas imaging and IoT leak detection onto platforms previously exempt from granular environmental reporting.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Control systems engineers with simultaneous expertise in drilling hydraulics, functional safety engineering, and machine learning deployment command premium compensation that strains operator OPEX budgets.
- Retrofit Integration Complexity:Brownfield installations must maintain API-certified safety instrumented systems while overlaying new AI control loops, creating verification conflicts that delay commissioning.
- Intellectual Property Fragmentation:Predictive maintenance algorithms draw on wellbore data ownership disputes between operators, drilling contractors, and software licensors, complicating model training access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Oil Rigs Market |
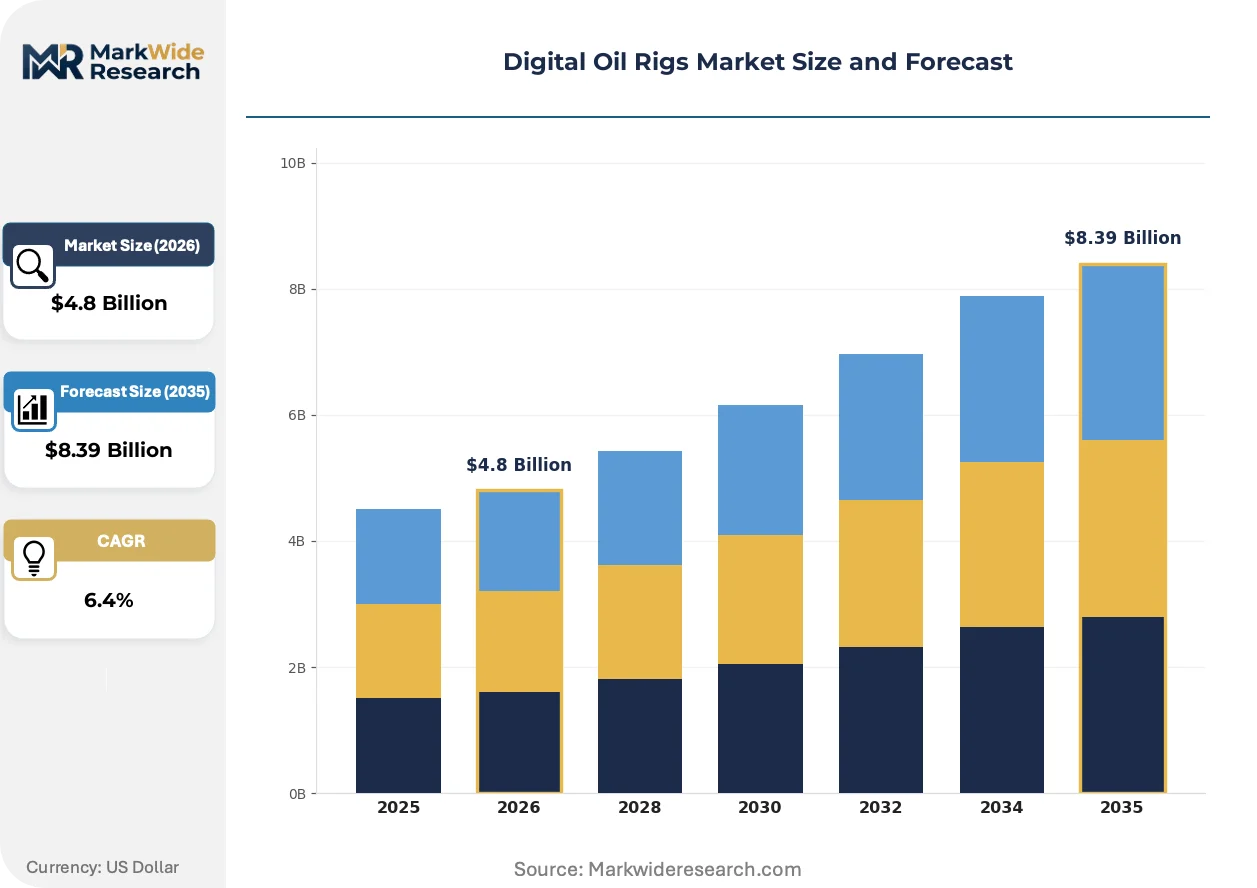
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Cloud Computing, Machine Learning Application: Real-time Monitoring, Predictive Maintenance, Data Analytics, Performance Optimization End User: Oil & Gas Operators, Service Providers, Equipment Manufacturers, Contractors Deployment: Onshore, Offshore, Hybrid, Remote |
| Companies Covered | SLB, Halliburton, Baker Hughes Company, Weatherford, NOV Inc., Emerson Electric Co., Nabors Industries Ltd., Pason Systems Corp., Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Oil Rigs Market Strategic Shifts
Drilling automation is accelerating past isolated point solutions toward unified control architectures that collapse the traditional separation between downhole telemetry and topside process management.
Digital drilling control systems are migrating from discrete SCADA modules toward integrated edge-to-cloud platforms that consolidate wellbore monitoring, managed pressure drilling, and automated rig floor operations under single vendor responsibility. North Sea operators are piloting these architectures on harsh-environment semisubmersibles where manual intervention costs exceed $500,000 per weather-delayed day. This consolidation is compressing the addressable market for standalone sensor vendors while expanding margin capture for full-stack automation providers.
EU CSRD sustainability disclosure mandates are forcing offshore contractors to document Scope 1 emissions at the asset level, requiring digital oil rigs to embed continuous fuel consumption metering and methane leak detection into standard control system configurations. The regulation applies to EU-registered operators regardless of drilling location, extending European compliance burden to West African and Southeast Asian contract markets. Vendors are responding by pre-certifying integrated environmental monitoring suites as standard rather than optional equipment packages.
Aftermarket service unbundling is disrupting traditional bundled maintenance contracts as national oil companies in the Middle East demand itemized visibility into software licensing, spare parts, and field engineering charges. Saudi Aramco and ADNOC are leading this shift through competitive tendering that separates digital system procurement from decade-long service agreements. This transparency pressure is most acute in the Persian Gulf, where state-backed operators leverage scale to extract performance-based pricing from automation vendors.
Digital Oil Rigs Market Segmentation
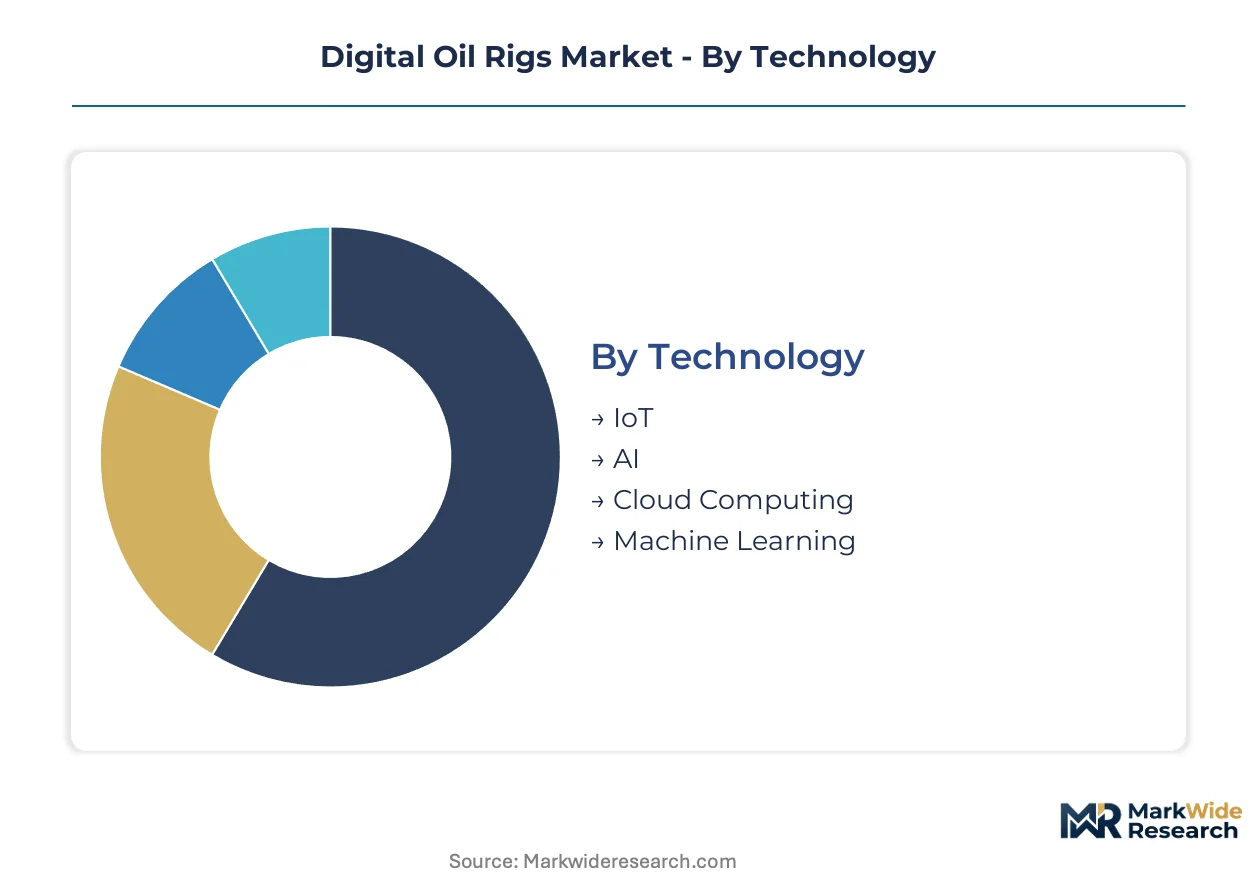
Digital oil rig procurement fractures across four distinct dimensions that reshape vendor go-to-market strategies. Technology choices determine capital intensity and integration complexity. Application priorities separate maintenance-focused buyers from real-time optimization seekers. Deployment modes dictate environmental hardening requirements and connectivity architectures.
Technology:
Cost tier stratification separates foundational connectivity infrastructure from premium intelligence layers that command recurring software fees.
- IoT:Industrial sensor networks form the connectivity backbone, linking downhole pressure transducers, topside vibration monitors, and BOP position encoders through ruggedized edge gateways. Demand concentrates in the US Gulf Coast where deepwater operators retrofit legacy jack-ups with wireless telemetry to satisfy Bureau of Safety and Environmental Enforcement automated documentation mandates.
- Machine Learning:Predictive algorithms trained on historical failure data enable automated drilling parameter optimization and wellbore stability forecasting. Norwegian North Sea operators deploy these models on floating production platforms where manual intervention costs exceed $500,000 per weather-delayed day, driving fastest adoption in high-labor-cost environments.
- AI:Neural architectures for autonomous drilling control.
- Cloud Computing:Centralized data lakes and remote visualization platforms.
IoT commands the established base. The steepest expansion runs through Machine Learning.
Application:
Volume concentration splits between defensive maintenance spending and offensive performance gains that directly lift barrel economics.
- Predictive Maintenance:Condition-based monitoring systems analyze vibration spectra, thermal signatures, and hydraulic fluid degradation to forecast equipment failures before unplanned downtime occurs. Middle East national oil companies in Saudi Arabia and the UAE unbundle these capabilities from bundled service contracts, demanding itemized visibility into software licensing and field engineering charges.
- Real-time Monitoring:Continuous wellbore telemetry streams bottom-hole pressure, temperature, and drilling dynamics to shore-based operations centers enabling remote intervention. Brazil's pre-salt Santos Basin projects procure integrated platforms with 15-year service contracts, embedding monitoring as standard rather than optional equipment.
- Data Analytics:Historical pattern recognition for reservoir characterization and drilling efficiency benchmarking.
- Performance Optimization:Automated rate-of-penetration and managed pressure drilling control loops.
Predictive Maintenance anchors current procurement budgets. Performance Optimization is climbing the fastest as operators prioritize rate-of-penetration gains over cost reduction.
End User:
Customer type determines contract structure, with asset owners demanding integration accountability while service providers seek component modularity.
- Oil & Gas Operators:Integrated majors and independents that own drilling assets and bear full-stack digital transformation risk. US independents in the Permian Basin prioritize modular upgrades that preserve operational flexibility against volatile commodity prices.
- Service Providers:Drilling contractors and integrated oilfield services firms that layer digital capabilities atop owned rig fleets. These buyers favor interoperable sensor networks that transfer across contract mobilizations.
- Equipment Manufacturers:OEMs embedding digital threads into newbuild rig specifications.
- Contractors:Project-specific construction and commissioning specialists.
Oil & Gas Operators dominate capital deployment. Service Providers are gaining share fastest through rental and performance-based contracting models.
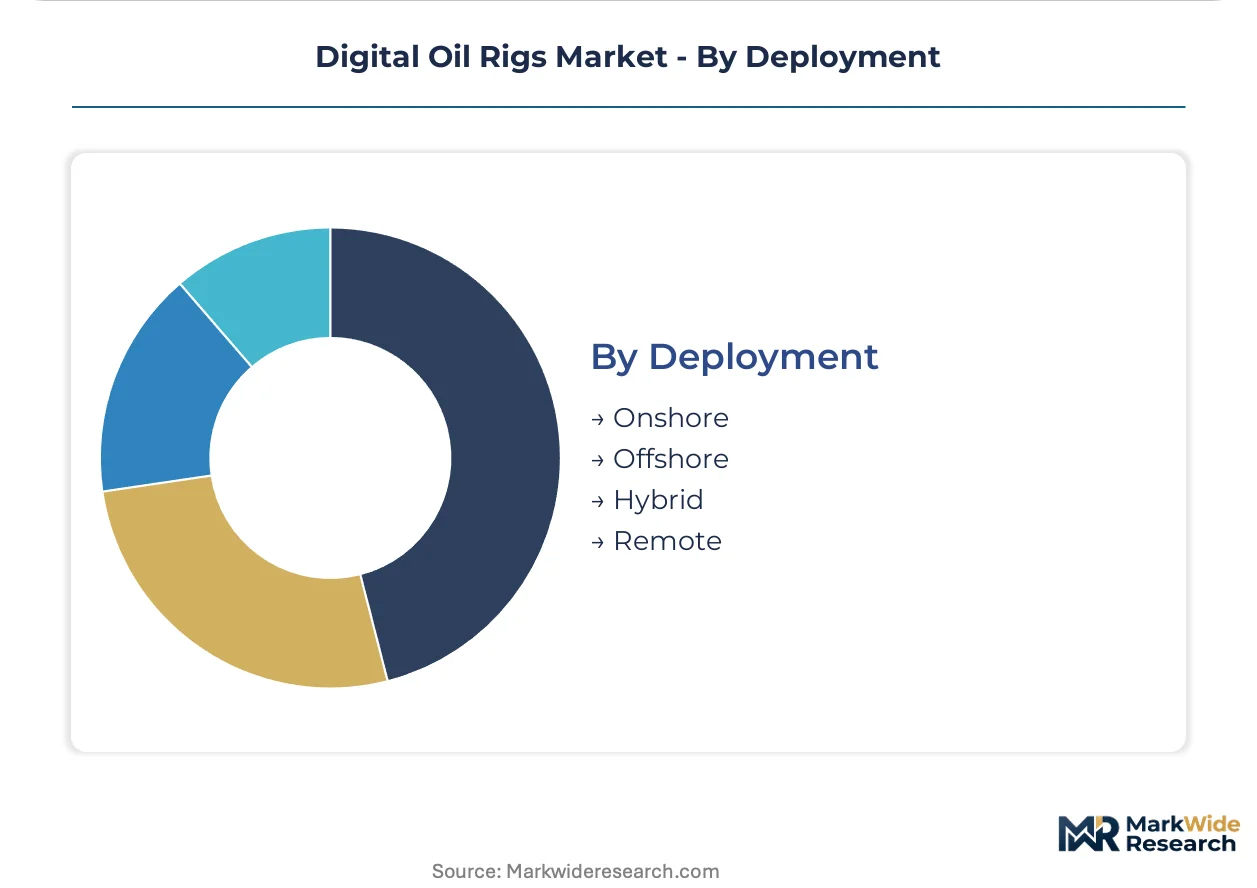
Deployment:
Maturity gradients separate established onshore digital adoption from frontier offshore architectures that must survive harsh marine environments.
- Offshore:Floating and fixed platform installations requiring subsea-rated pressure sensors, fiber-optic telemetry, and edge computing nodes hardened against salt spray and explosive atmospheres. Supply concentrates among North Sea and Norwegian component vendors, exposing procurement to marine logistics bottlenecks.
- Onshore:Land-based drilling rigs with simpler connectivity and less severe environmental protection requirements. Permian Basin and Eagle Ford operators drive standardization through high-density pad drilling that amortizes digital infrastructure across multiple wells.
- Hybrid:Architectures blending local edge processing with intermittent cloud synchronization.
- Remote:Fully autonomous or minimally-manned installations dependent on satellite or microwave backhaul.
Onshore deployments hold the installed base. Offshore configurations are expanding most quickly as deepwater project density concentrates investment in integrated digital drilling platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys digital oil rigs for deepwater automation and regulatory compliance, while Norway and Brazil prioritize predictive maintenance for harsh-environment operations, and Middle Eastern national oil companies unbundle service contracts to extract pricing transparency.
United States
Deepwater projects in the Gulf of Mexico drive demand for integrated digital drilling platforms that automate blowout preventer documentation. The Bureau of Safety and Environmental Enforcement mandates API RP 75 protocols requiring real-time sensor-to-cloud architectures. Houston anchors the vendor ecosystem, where SLB and Halliburton deploy edge computing nodes on floating production platforms.
Norway
North Sea operators deploy machine learning models to reduce weather-delayed intervention costs exceeding $500,000 per day on semisubmersible rigs. The Norwegian Petroleum Safety Authority enforces IEC 61508 functional safety standards that compress vendor qualification timelines. Stavanger concentrates subsea-rated sensor suppliers and fiber-optic telemetry specialists serving harsh marine environments.
Brazil
Petrobras-led pre-salt development in the Santos Basin procures integrated platforms with 15-year service contracts embedding real-time monitoring as standard equipment. The National Petroleum Agency regulates ultra-deepwater safety systems requiring automated wellbore stability controls. Rio de Janeiro hosts the procurement headquarters for these long-term automation agreements.
Saudi Arabia
Saudi Aramco demands itemized visibility into software licensing and field engineering charges, unbundling digital maintenance from bundled service contracts. The Ministry of Energy's localization requirements push vendors toward in-country technical support capabilities. Dhahran anchors the operator's digital transformation procurement, with competitive tendering extracting performance-based pricing from automation suppliers.
United Arab Emirates
ADNOC follows Saudi Aramco's lead in separating digital system procurement from decade-long service agreements to improve cost transparency. The Supreme Petroleum Council mandates emissions monitoring capabilities that pull optical gas imaging onto offshore platforms. Abu Dhabi concentrates the national oil company's digital rig modernization programs targeting ultra-deepwater fields.
Digital Oil Rigs Market Competitive Environment
Capability concentration sits with full-stack automation providers; scale advantage sits with diversified energy technology conglomerates. The market structures around three tiers: integrated drilling portfolio vendors capturing recurring software licensing, sensor network specialists deploying dense edge-computing architectures, and component suppliers serving narrow subsea-rated niches. Dominant competitive moves include portfolio consolidation through integrated platform offerings and geographic expansion via long-term service contracts in frontier deepwater basins.
Within the integrated tier, SLB, Halliburton, and Baker Hughes Company exemplify the full-stack archetype that collapses downhole telemetry and topside process management under single vendor responsibility. These entities occupy positions where aftermarket service revenue reconfigures margin pools through recurring software licensing rather than discrete hardware sales. Weatherford and NOV Inc. represent the drilling contractor-aligned tier, favoring interoperable sensor networks that transfer across contract mobilizations. Emerson Electric Co. and Nabors Industries Ltd. sit within the automation-hardware specialist segment, supplying ruggedized control systems and edge infrastructure to operators pursuing modular upgrade paths.
| Leading Market Players |
|---|
| SLB |
| Halliburton |
| Baker Hughes Company |
| Weatherford |
| NOV Inc. |
| Emerson Electric Co. |
| Nabors Industries Ltd. |
| Pason Systems Corp. |
| Schlumberger Limited |
| Others |
Value Chain & Pricing Dynamics
Norwegian and North Sea component vendors controlling subsea-rated pressure sensors and fiber-optic telemetry modules capture disproportionate margin pools downstream, as rig operators face 18-24 month IEC 61508 SIL 3 qualification cycles that freeze out alternative suppliers.
Pricing Analysis
Long-term service contracts with 15-year terms anchor pricing structures for integrated digital drilling platforms, while modular component procurement follows project-based spot arrangements. Price differentiation hinges on functional safety certification tier and after-sales service bundling, with IEC 61508 SIL 3 validated systems commanding substantial premiums over uncertified alternatives. Cost compression in the sensor tier intensifies as Middle East national oil companies unbundle maintenance contracts and demand itemized visibility into software licensing charges. National oil companies exhibit highest price sensitivity through competitive tendering, whereas US Gulf Coast independents prioritize operational flexibility over unit cost minimization.
Supply Chain Analysis
Contract manufacturing capacity for ruggedized edge computing nodes concentrates with Emerson Electric and specialized marine electronics foundries serving harsh-environment specifications. Geographic supply concentration centers on Norway, the United Kingdom, and the United States for subsea-rated components, drawing from rare earth elements for sensor magnetics and high-purity optical fiber for downhole telemetry. Single-source vulnerability runs through North Sea sensor suppliers exposed to marine logistics bottlenecks. Distribution runs through integrated oilfield services firms that bundle hardware with commissioning and long-term field engineering support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors that control scarce cross-disciplinary talent spanning drilling hydraulics, functional safety engineering, and machine learning deployment, while operators struggle to staff integrated control system upgrades.
For Market Incumbents: Insulate recurring revenue streams by embedding predictive maintenance algorithms within long-term service contracts that resist unbundling pressure from Middle East national oil companies. Prioritize in-country technical support capabilities to satisfy Saudi and UAE localization mandates. Deepen backward integration into subsea-rated sensor manufacturing to reduce exposure to Norwegian supply concentration. For New Entrants and Emerging Players: Build out specialized capabilities in brownfield retrofit integration, where verification conflicts between legacy SCADA and new AI control loops delay commissioning and create demand for niche system integrators. Target the Permian Basin modular upgrade segment, where US independents prioritize operational flexibility over full-stack replacement. Lead with API RP 75 compliance documentation as a differentiated entry point. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed drilling automation specialists holding IEC 61508 certification but lacking scale for integrated platform competition. Long-term viability favors full-stack vendors with recurring software licensing exposure over hardware-centric component suppliers. Watch for inflection in Petrobras procurement patterns, where 15-year service contract renewals signal sustained demand for integrated digital drilling platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | IEC 61508 SIL 3 qualification compresses vendor timelines and reshapes procurement risk allocation. |
| Backward Integration into Sensor Manufacturing | In-house production of subsea-rated pressure transducers reduces exposure to North Sea supply bottlenecks. |
| Long-Term Service Contract Expansion | Brazilian pre-salt projects embed 15-year automation agreements that sustain recurring revenue visibility. |
| Edge Computing Infrastructure Deployment | Ruggedized hardware nodes on floating platforms enable latency-sensitive drilling parameter optimization. |
| Environmental Monitoring Suite Integration | EU CSRD mandates and US IRA methane credits pull emissions verification into standard control configurations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry association datasets, and operator procurement disclosures. Primary interviews engaged drilling automation directors, functional safety engineers, offshore project procurement leads, and digital transformation executives at national oil companies. Secondary sources encompassed Bureau of Safety and Environmental Enforcement documentation, Norwegian Petroleum Safety Authority standards, Petrobras technical specifications, and API RP 75 protocol updates. Bottom-up segment sizing triangulated against top-down market aggregation across technology, application, and deployment dimensions.
Forecast inputs incorporate capital expenditure patterns from deepwater project pipelines, regulatory mandate implementation timelines, and technology adoption curves for machine learning deployment. Segmentation modeling spans IoT infrastructure, machine learning algorithms, AI control systems, and cloud computing platforms crossed with predictive maintenance, real-time monitoring, and performance optimization applications. CAGRs derive from regression analysis of historical investment cycles and projected project sanctioning activity. Offshore project density in the US Gulf Coast and Brazil pre-salt basins provides demand-side calibration.
Sensitivities concentrate around IEC 61508 certification timeline extensions, commodity price volatility affecting operator capital allocation, and marine logistics disruptions impacting Norwegian sensor supply. Forecasts embed assumptions regarding regulatory enforcement consistency and deepwater project sanctioning momentum. Quarterly review of Petrobras procurement announcements, US Gulf Coast rig utilization rates, and Middle East competitive tendering patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Well Abandonment Services Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Well Test Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Iran Oil and Gas Exploration and Production Market