
 Oman Oil and Gas Pipeline Market | 2026-2036
Oman Oil and Gas Pipeline Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Oil and Gas Pipeline Market Analytics
Advanced composite lining and automated welding protocols are reshaping how trunk lines and gathering systems are fabricated and commissioned across Oman's mature fields. Galfar Engineering & Contracting S.A.O.G. leverages its integrated EPC capability to anchor large-diameter desert crossings in the interior. Larsen & Toubro Oman LLC sustains competitive positioning through specialized corrosion-resistant coating applications for sour-gas service. OQ Gas Networks S.A.O.C. controls the strategic downstream interface, operating the national gas transmission grid that links upstream producers to industrial zones and export facilities at Sur.
Oman oil and gas pipelines are high-pressure steel conduit systems, typically API 5L-grade with cement-weight or fusion-bonded epoxy coatings, engineered to transport hydrocarbons across ambient temperatures exceeding 50°C and seismic zones. Their primary purpose is to move crude, natural gas, and refined products from production headers to processing trains, storage terminals, and marine loading points with minimal fugitive loss. Crude oil pipelines occupy the largest installed base given the Sultanate's sustained heavy-oil production from Block 6 and adjacent concessions. Natural gas gathering lines represent the fastest-expanding category as tight-gas and unconventional development in the Khazzan-Makarem fields requires new field-to-plant connectivity. Smart Pipeline Systems within the technology dimension concentrate margin pools, since operators prioritize real-time leak detection and pressure monitoring to satisfy tightening safety mandates and reduce unplanned shutdowns.
Petroleum Development Oman LLC operates under licence terms set by the Ministry of Energy and Minerals, while pipeline construction and materials must conform to standards issued by the Directorate General of Specifications and Measurements and align with international API specifications for pressure-boundary integrity. The Ministry of Regional Municipalities and Water Resources enforces environmental impact assessments for cross-wadi routing, directly shaping project timelines and material selection for watercourse crossings. Stakeholders must monitor how Oman's domestic gas obligation policy evolves, since preferential allocation to power generation and industrial zones could redirect pipeline investment away from export corridors toward inland distribution networks.
Market Dynamics
The Ministry of Energy and Minerals is tightening pipeline integrity codes following desert corrosion incidents, forcing operators to accelerate replacement schedules for aging gathering networks and driving capital allocation toward advanced coating systems and automated inspection technologies.
Growth Catalysts
- Tight-gas development mandates:The Khazzan-Makarem fields require extensive new gathering infrastructure to connect unconventional production to processing facilities, creating sustained demand for high-pressure steel conduit systems.
- Domestic gas obligation policy:Preferential allocation to power generation and industrial zones redirects investment toward inland distribution networks, expanding the addressable market beyond export corridors.
- Smart Pipeline Systems:Real-time leak detection and pressure monitoring technologies satisfy tightening safety mandates while reducing unplanned shutdowns, creating technology-driven replacement cycles.
Market Restraints
- Specialized coating material costs:Fusion-bonded epoxy and corrosion-resistant applications for sour-gas service command premium input pricing, compressing margins on fixed-price EPC contracts.
- Desert construction labor concentration:Skilled welding and automated inspection specialists cluster in Muscat and Sohar, creating bottlenecks for interior province projects.
- Cross-wadi environmental compliance:The Ministry of Regional Municipalities and Water Resources enforces extended impact assessments for watercourse routing, elongating project timelines.
Strategic Opportunities
- Dhofar Governorate tight-gas:New field developments in southern provinces lack dedicated gathering infrastructure, presenting first-mover advantages for integrated EPC providers.
- Composite lining convergence:Advanced polymer liners combined with automated welding protocols enable thinner-wall designs that reduce steel tonnage and transport costs.
- Industrial zone connectivity:The Batinah coastal corridor's refining and petrochemical expansion requires dedicated feedstock pipelines, diverting investment from mature export routes.
Industry Challenges
- API 5L-grade welding certification:The Directorate General of Specifications and Measurements mandates specialized qualifications for pressure-boundary integrity that exceed regional training capacity.
- Seismic zone engineering complexity:Pipeline routing through active fault zones requires advanced stress analysis and flexible joint systems that extend design cycles.
- Legacy SCADA integration:Smart monitoring systems must interface with decades-old control architectures at Petroleum Development Oman facilities, creating commissioning delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Oil and Gas Pipeline Market |
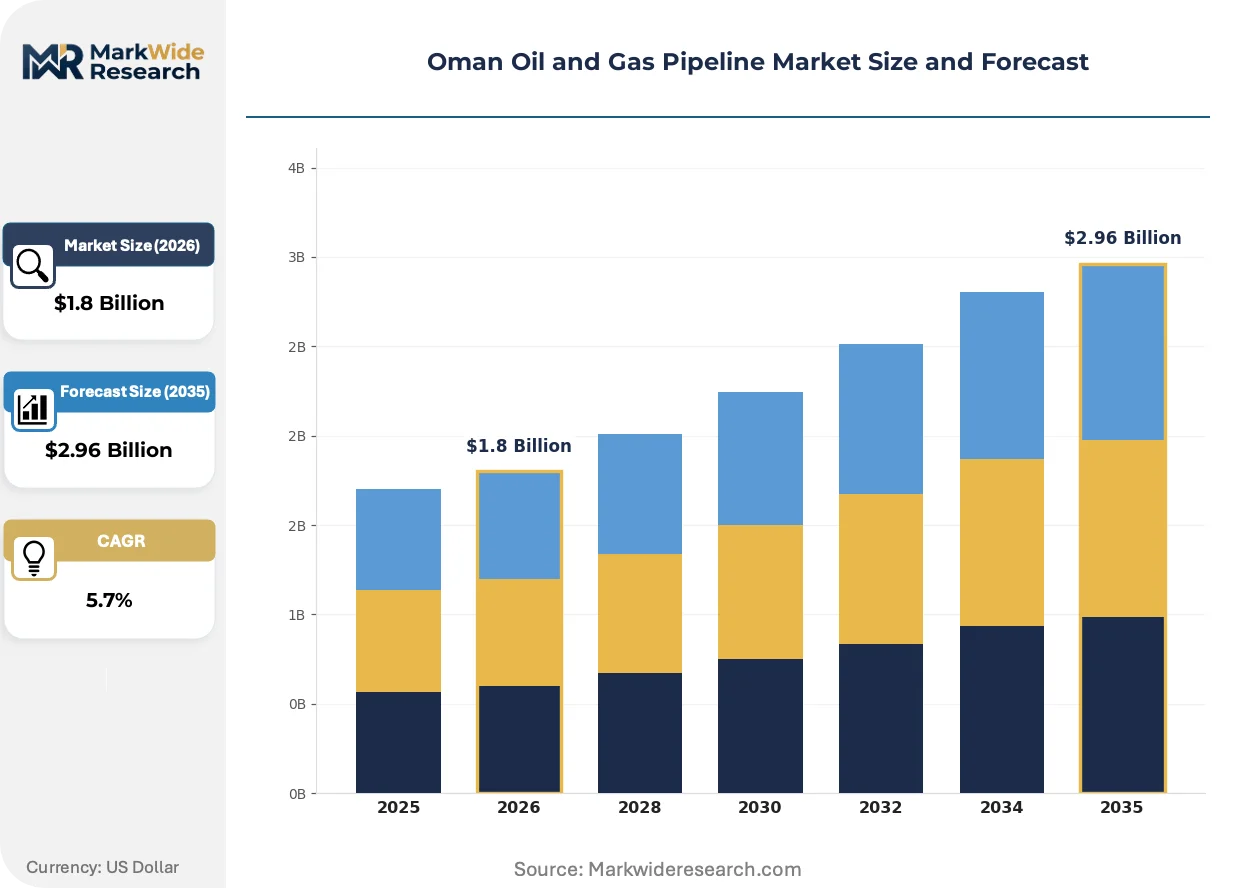
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pipeline Type: Crude Oil, Natural Gas, Refined Products, Water End User: Petroleum Companies, Utilities, Industrial Facilities, Exporters Service Type: Transportation, Storage, Maintenance, Inspection Technology: Smart Pipeline Systems, Compression Technology, Monitoring Solutions, Pipe Materials |
| Companies Covered | Galfar Engineering & Contracting S.A.O.G., Larsen & Toubro Oman LLC, OQ Gas Networks S.A.O.C., Mott MacDonald, TMK Group, Petroleum Development Oman LLC, Al Hassan Engineering Co. S.A.O.G., Pipelife Nederland B.V., OQ S.A.O.C., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Oil and Gas Pipeline Market Evolving Landscape
Pipeline construction across Oman's mature fields is experiencing fundamental fabrication evolution, with digital inspection protocols and material science advances compressing commissioning timelines while raising safety thresholds.
Automated ultrasonic testing (AUT) is migrating from manual radiography for girth-weld inspection in high-stakes sour-gas service. PDO and tight-gas operators are mandating AUT on all new gathering lines to eliminate film interpretation delays. This technology is compressing weld acceptance cycles from days to hours while generating machine-readable quality archives.
The Ministry of Energy and Minerals has aligned national integrity codes with API 1160 and ASME B31.8S standards, creating unified compliance frameworks for both onshore trunk lines and subsea tiebacks. This regulatory convergence eliminates redundant inspection protocols that previously duplicated operator and contractor efforts. Offshore-to-onshore integrated projects now face streamlined certification paths, accelerating sanction-to-first-metal timelines.
Buyers are consolidating maintenance contracts under performance-based frameworks that tie contractor payments to availability metrics rather than delivered labor hours. This procurement evolution disrupts traditional time-and-materials relationships between OQ Gas Networks and regional service providers. The shift is most visible in the Sur industrial corridor, where integrated downstream operators now demand guaranteed throughput uptime with penalty clauses for unplanned isolation events.
Oman Oil and Gas Pipeline Market Segmentation
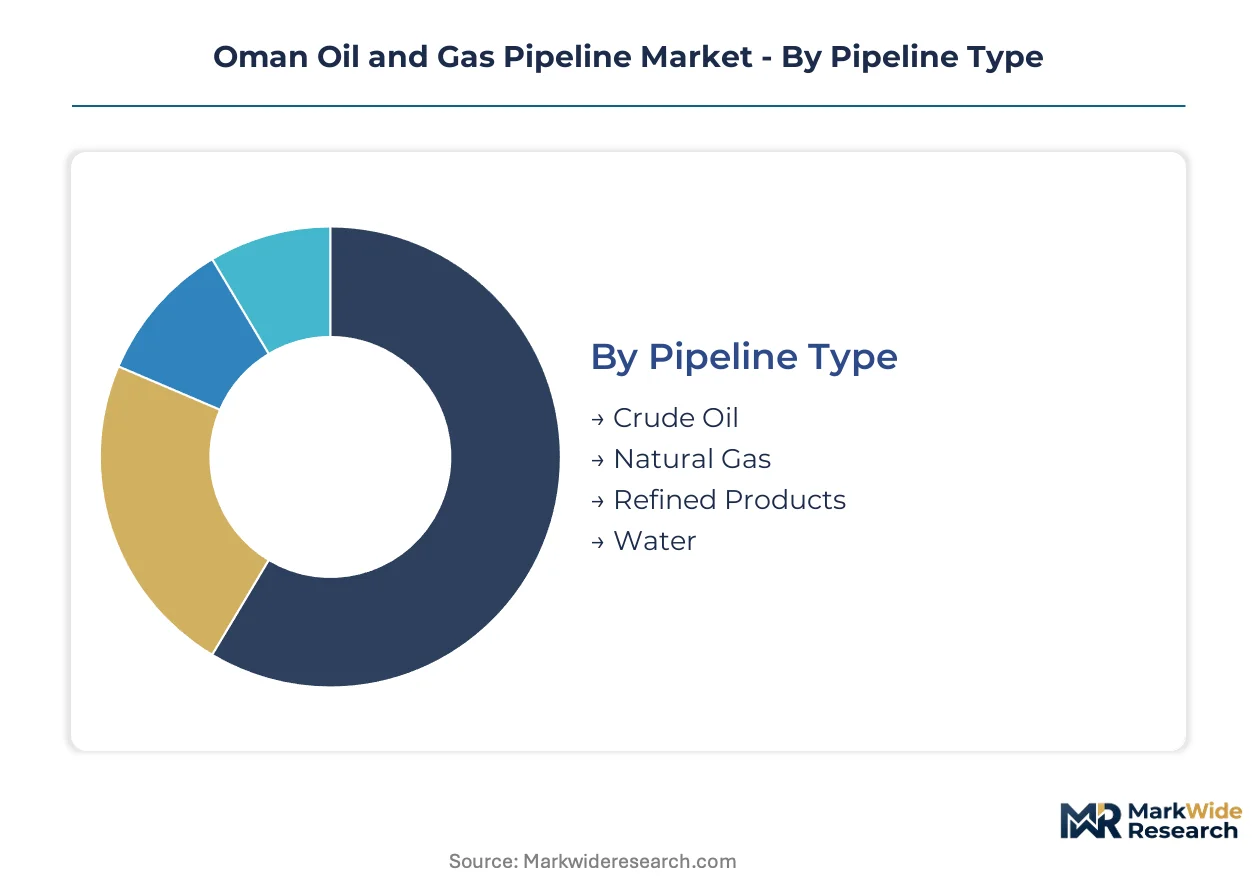
Segmentation reveals how capital cycles differ dramatically across Oman's pipeline infrastructure. Replacement schedules for mature crude networks run decades longer than technology refresh cycles for smart monitoring systems, creating distinct investment rhythms for suppliers and contractors.
Pipeline Type:
Cycle times range from 40-year asset lives for trunk crude lines to sub-decade refresh rates for water disposal networks in tight-gas fields.
- Crude Oil:High-pressure steel conduit systems, typically API 5L X65-grade with fusion-bonded epoxy coatings, engineered for Block 6 heavy-oil production corridors. Demand concentrates in northern interior concessions where PDO operates aging gathering networks requiring integrity-driven replacement programs.
- Natural Gas:Sour-gas-rated pipelines with specialized corrosion-resistant metallurgy connecting Khazzan-Makarem tight-gas developments to processing trains. Dhofar Governorate field expansions drive the steepest capacity additions as southern provinces lack existing gathering infrastructure.
- Refined Products:Smaller-diameter carbon steel lines serving Sohar Refinery distribution to Batinah coastal terminals.
- Water:Produced water and injection lines with shorter asset lives due to corrosive formation fluid exposure.
Crude oil anchors the volume base while natural gas gains share at the steepest rate.
End User:
Contract structures diverge sharply between state-operated upstream assets and privately financed industrial offtake agreements.
- Petroleum Companies:PDO and international concession holders dominate capital deployment, with procurement governed by Ministry of Energy and Minerals integrity mandates and extended field-life obligations.
- Utilities:State power generation entities under domestic gas obligation policy, requiring dedicated distribution networks to inland generation complexes rather than export corridors.
- Industrial Facilities:Petrochemical operators in Sur industrial corridor demanding guaranteed throughput contracts with penalty structures for supply interruption.
- Exporters:LNG terminal operators at Qalhat and marine loading facilities prioritizing high-availability trunk lines with minimal unplanned isolation events.
Petroleum companies command the largest project pipeline while industrial facilities expand most quickly.
Service Type:
Revenue stability varies from volatile construction cycles to recurring maintenance streams with multi-year performance contracts.
- Transportation:Core pipeline construction and commissioning services, including desert crossing engineering and automated welding protocols for high-stakes sour-gas applications.
- Storage:Terminal connectivity and tank farm integration, concentrated at coastal export facilities and inland processing hubs.
- Maintenance:Shift toward availability-based contracts tying contractor payments to throughput metrics rather than labor hours, visible across OQ Gas Networks procurement frameworks.
- Inspection:Automated ultrasonic testing and smart pigging services replacing manual radiography, compressing weld acceptance cycles from days to hours.
Transportation absorbs the dominant share of annual capital while inspection services climb the fastest.
Technology:
Adoption timelines separate proven materials from emerging digital layers requiring SCADA integration with legacy control architectures.
- Smart Pipeline Systems:Real-time leak detection and pressure monitoring infrastructure satisfying tightened Ministry of Energy and Minerals safety mandates. Commissioning delays persist where PDO legacy control systems require interface engineering.
- Compression Technology:High-pressure boosting stations for tight-gas gathering networks, with demand clustering at Khazzan-Makarem field boundaries where reservoir pressures decline rapidly.
- Monitoring Solutions:Fiber-optic distributed temperature sensing and acoustic leak detection, increasingly specified for watercourse crossings under Ministry of Regional Municipalities environmental compliance requirements.
- Pipe Materials:Advanced composite lining and polymer liners enabling thinner-wall designs that reduce steel tonnage for remote interior province projects.
Pipe materials constitute the foundational spend layer while smart pipeline systems expand most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oman exports liquefied natural gas through the Strait of Hormuz to Asian buyers in Japan, South Korea, and India, while crude shipments head to China and Southeast Asian refineries. Pipeline infrastructure investment tracks these trade corridors, with gathering networks expanding in interior provinces to feed coastal liquefaction terminals.
Dhofar Governorate
Khazzan-Makarem tight-gas developments require extensive new gathering infrastructure where no legacy pipelines exist. The Ministry of Energy and Minerals has designated southern provinces as priority zones for unconventional production allocation. Salalah anchors this expansion, with new field-to-plant connectivity projects bypassing the mountainous interior through coastal routing.
Al Batinah South Governorate
Sohar Refinery expansion and downstream petrochemical clustering drive feedstock pipeline demand along the coastal corridor. The Ministry of Regional Municipalities enforces strict environmental impact assessments for cross-wadi routing through this densely populated zone. Liwa and Saham industrial zones concentrate contract awards for refined product distribution networks.
Ad Dakhiliyah Governorate
Block 6 heavy-oil production corridors require integrity-driven replacement programs for aging gathering networks. The Directorate General of Specifications and Measurements mandates API 5L-grade welding certification that exceeds regional training capacity. Nizwa serves as the logistical hub for interior province projects facing skilled labor bottlenecks.
Ash Sharqiyah South Governorate
Sur industrial corridor operators demand guaranteed throughput contracts with penalty structures for supply interruption. OQ Gas Networks controls the strategic downstream interface linking upstream producers to LNG export facilities at Qalhat. Ras al-Jinz marine loading points prioritize high-availability trunk lines with minimal unplanned isolation events.
Al Wusta Governorate
Central desert crossings present engineering challenges for large-diameter pipeline construction across seismic zones and extreme temperature environments. The Ministry of Energy and Minerals has tightened integrity codes following corrosion incidents in remote interior installations. Duqm Special Economic Zone attracts investment for new export corridor alternatives reducing Hormuz dependency.
Oman Oil and Gas Pipeline Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Oman's pipeline infrastructure market. State-linked entities dominate downstream transmission and grid operation, while engineering contractors fragment across upstream gathering and construction segments. Two archetypes prevail: integrated EPC providers with desert crossing capability, and specialized coating and inspection service firms. Competitive moves center on performance-based contract consolidation and technology licensing for automated welding protocols.
Among integrated EPC providers, Galfar Engineering & Contracting S.A.O.G. and Larsen & Toubro Oman LLC exemplify the scale-driven archetype, anchoring large-diameter projects through established in-country execution platforms. OQ Gas Networks S.A.O.C. occupies a distinct channel-control position, representing the national grid operator archetype that links upstream producers to industrial zones and export terminals. These three entities collectively illustrate how market position derives from either construction execution scale or strategic asset ownership rather than product differentiation.
| Leading Market Players |
|---|
| Galfar Engineering & Contracting S.A.O.G. |
| Larsen & Toubro Oman LLC |
| OQ Gas Networks S.A.O.C. |
| Mott MacDonald |
| TMK Group |
| Petroleum Development Oman LLC |
| Al Hassan Engineering Co. S.A.O.G. |
| Pipelife Nederland B.V. |
| OQ S.A.O.C. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Asian steel plate mills compresses input costs for API 5L-grade line pipe while tightening margin pools for coating applicators and inspection specialists serving Oman's sour-gas pipeline projects. This utilization imbalance rewards buyers with procurement leverage on commodity steel tonnage while squeezing service providers on fixed-price EPC contracts.
Pricing Analysis
Current-generation fusion-bonded epoxy coating commands premium positioning against prior-generation cement-weight systems and next-generation polymer liner technologies still in qualification trials. Project-based long-term offtake contracts dominate procurement, with price differentiation hinging on API 5L grade certification and sour-gas metallurgy requirements. Pricing pressure stems from fixed-price EPC competition for Khazzan-Makarem gathering networks, compressing contractor margins. International oil companies exhibit lowest price sensitivity given field-life obligations, while local industrial offtakers in Sur demand penalty-clause protection against supply interruption.
Supply Chain Analysis
Tariff exposure between China and Gulf Cooperation Council members dominates supply chain risk planning for Oman pipeline projects, with Chinese steel mills supplying roughly half of API 5L plate demand. Manufacturing concentrates in China, South Korea, and Japan, with raw material dependencies spanning iron ore from Australia, nickel for corrosion-resistant alloys from Indonesia, and specialty welding consumables from Germany. Single-source vulnerability persists for automated ultrasonic testing equipment. Distribution runs through Jebel Ali port consolidation before desert logistics to interior province sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through OQ Gas Networks procurement consolidation, with performance-based contracts displacing time-and-materials relationships across the national transmission grid. This shift extracts value from service providers while transferring throughput risk to contractor balance sheets.
For Market Incumbents: Build switching-cost moats through SCADA integration expertise that locks in recurring maintenance revenue at PDO legacy facilities. Defend against specialized coating entrants by securing exclusive API 5L-grade welding certification capacity at Nizwa training centers. Anchor capacity addition in Dhofar Governorate to capture tight-gas infrastructure deployment ahead of competitor mobilization.
For New Entrants and Emerging Players: Establish a beachhead in automated inspection services where AUT penetration remains below potential across aging Block 6 gathering networks. Target the water disposal pipeline segment with polymer liner technology that reduces steel tonnage for remote interior projects. Pursue licensing partnerships with European composite lining specialists to bypass metallurgy capability gaps.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated-utility play because OQ Gas Networks grid control creates durable cash flow visibility under domestic gas obligation policy. Acquisition targets should emphasize inspection technology providers with smart pigging capabilities. Watch Khazzan-Makarem production plateau as the inflection signal for replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Application | EPC contractors capture margin pools currently flowing to third-party corrosion specialists serving sour-gas projects. |
| Technology Licensing for Automated Welding | European protocol providers secure recurring royalty streams from Oman contractors facing API 5L certification bottlenecks. |
| Joint Venture for Dhofar Infrastructure | Integrated partnerships with regional operators accelerate first-mover positioning in tight-gas gathering construction. |
| Long-term Supply Agreement with Steel Mills | Fixed-price plate contracts hedge tariff exposure while securing priority allocation during Asian mill capacity crunches. |
| Green Certification Program for Desert Construction | Environmental compliance differentiation wins Ministry of Regional Municipalities approval for cross-wadi routing projects. |
Research Methodology
The analysis maps crude oil trunk lines, natural gas gathering systems, refined product distribution, and smart monitoring technologies, each validated through interviews with EPC project directors, pipeline integrity engineers, Ministry of Energy and Minerals regulatory officials, and OQ Gas Networks procurement leads. Secondary sources include Directorate General of Specifications and Measurements standards filings, API specification documentation, and customs records for API 5L-grade steel imports. Bottom-up project aggregation triangulates against top-down infrastructure investment assessments from national development plans.
Assumptions held fixed include Ministry of Energy and Minerals integrity code enforcement timelines and domestic gas obligation policy allocation ratios, while Khazzan-Makarem production ramp rates and Duqm Special Economic Zone export corridor development were varied across scenarios. Segmentation modeling spans pipeline type, end-user contract structure, service category, and technology adoption tier. CAGRs derive from capacity addition schedules and replacement cycle analysis across the projection horizon, with inputs from seismic zone engineering complexity and desert construction labor availability.
Macroeconomic conditions sit as an overlay; deviation in Asian steel pricing, Gulf Cooperation Council tariff policy, or Omani fiscal capacity would shift the trajectory. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory enforcement intensity and tight-gas reservoir performance. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
Injection Well Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Oil and Gas Pipeline Management Software Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market