
 Southeast Asia Oil and Gas Upstream Market | 2026-2036
Southeast Asia Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Oil and Gas Upstream Market Analytics
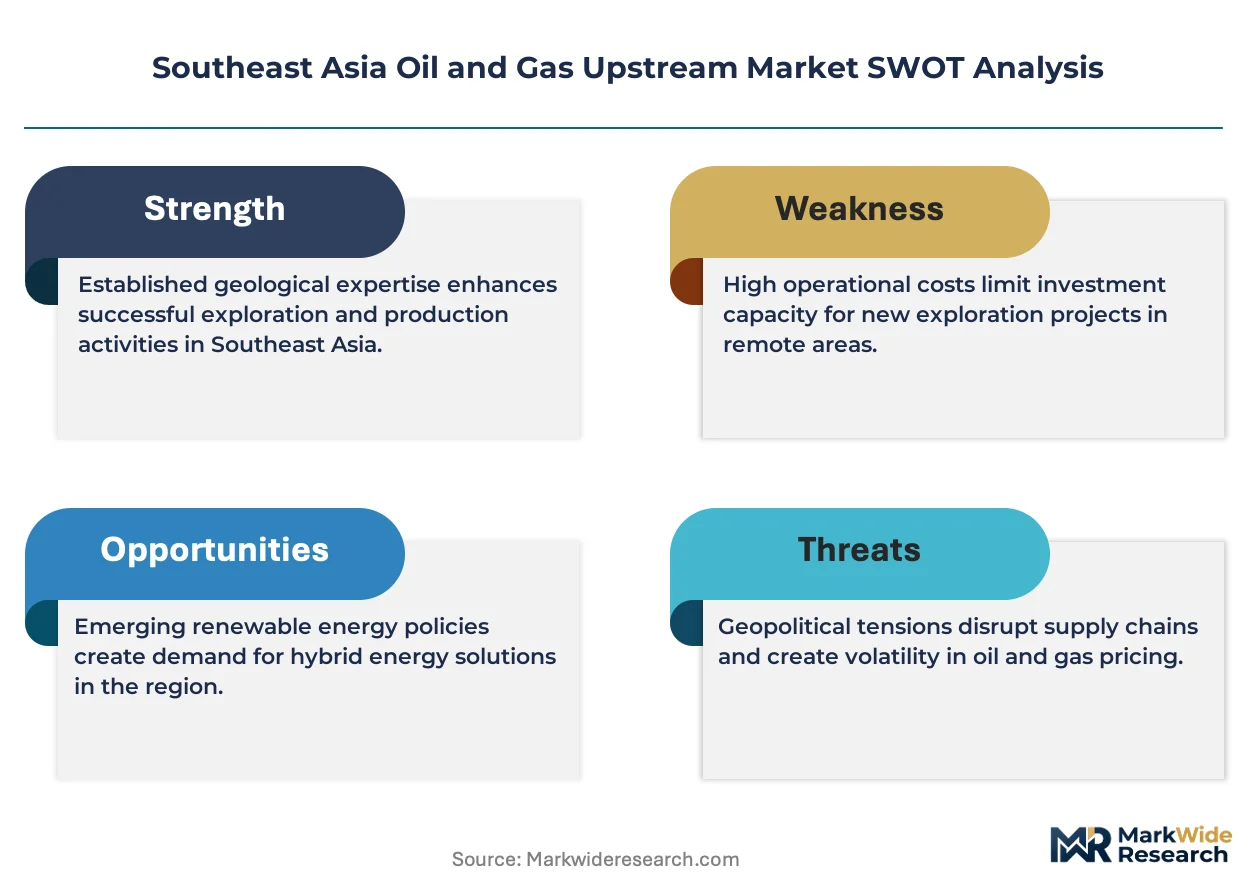
Production-sharing contract financing with back-loaded cost recovery terms is reconfiguring which operators can sustain field development in marginal basins. PTTEP leverages its Thai-dominated portfolio to anchor shallow-water gas production across the Gulf of Thailand. Petronas competes through integrated upstream-downstream control that extends from offshore Sarawak to LNG export terminals. Shell navigates aging assets in Brunei and Malaysia by specializing in late-life field optimization and enhanced recovery techniques.
Southeast Asia oil and gas upstream encompasses the exploration, drilling, and production of crude oil and natural gas from subsurface reservoirs, typically involving well depths from hundreds to several thousand meters and operating pressures exceeding 10,000 psi in deepwater environments. The primary purpose is to extract hydrocarbons for processing into fuels, feedstocks, and power generation inputs serving regional and export markets. Exploration and drilling services command the largest current revenue share due to sustained commitment to frontier basins off Indonesia and Myanmar, while enhanced oil recovery technology represents the fastest-expanding segment as mature fields in Malaysia and Thailand require pressure maintenance and tertiary methods to sustain output. Offshore deployment dominates capital allocation, though shallow water activity still occupies the majority of active rig days.
Indonesia's Ministry of Energy and Mineral Resources governs upstream licensing through the Gross Split scheme, altering how contractors recover costs and report reserves. Malaysia's PETRONAS sets technical standards and local content mandates that shape supplier qualification and equipment procurement across its concession areas. Vietnam's National Assembly periodically revises petroleum legislation to attract foreign operators to its deepwater blocks. Stakeholders must monitor how regulatory shifts in each jurisdiction alter contract economics and determine which technical capabilities warrant fresh investment.
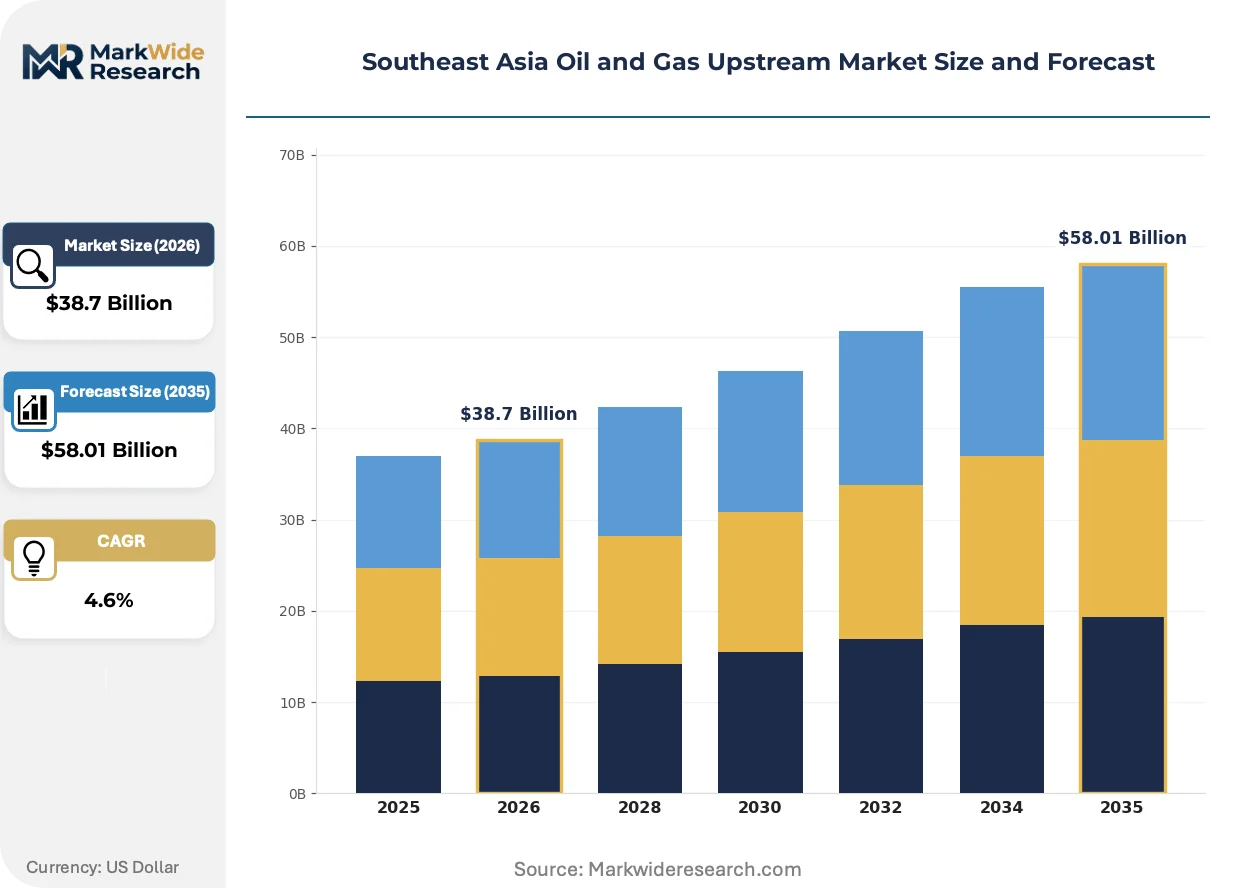
Market Dynamics
Malaysia's tightened local content mandates under the Petroleum Development Act are forcing foreign operators to restructure procurement and joint-venture arrangements, compressing margins for integrated service providers while creating openings for domestic fabrication yards and engineering houses.
Growth Catalysts
- Deepwater frontier commitment:Indonesia's Natuna Sea blocks are absorbing concentrated exploration capital from national oil companies and their foreign partners, sustaining rig demand and subsea installation activity.
- Enhanced recovery mandates:Thailand's mature Gulf of Thailand gas fields require pressure maintenance and tertiary extraction methods, pulling investment toward artificial lift and gas injection technologies.
- Downstream integration pull:Refining and petrochemical complexes across Vietnam and Thailand are expanding crude intake capacity, anchoring offtake agreements that underwrite upstream development economics.
Market Restraints
- Capital intensity barrier:Deepwater drilling and subsea production systems require specialized vessels and riser equipment, concentrating project execution among a handful of global contractors.
- Local content compliance cost:PETRONAS mandates for domestic supplier participation inflate procurement timelines and engineering overhead, particularly for marginal field developments.
- Reserve replacement pressure:Mature basins in Malaysia and Brunei exhibit declining natural productivity, forcing operators toward expensive enhanced oil recovery rather than conventional primary extraction.
Strategic Opportunities
- Carbon capture integration:Indonesia's Sunda Strait and Natuna fields contain high-CO2 reservoirs where capture and reinvestment infrastructure can unlock stranded gas while qualifying for emission reduction credits.
- Decommissioning service expansion:Malaysia's aging Sarawak and Sabah offshore platforms require plug-and-abandonment and topside removal capabilities, a service segment currently underserved by regional contractors.
- Floating LNG offtake solutions:Vietnam's deepwater blocks lack pipeline connectivity to shore, creating demand for floating production and liquefaction units that bypass onshore infrastructure bottlenecks.
Industry Challenges
- Subsea engineering talent scarcity:Specialized skills in riser design, flow assurance, and subsea controls are concentrated among a small pool of expatriate engineers, constraining project staffing.
- Legacy platform integration:Brownfield developments in the Gulf of Thailand require connecting new wellhead platforms to aging processing facilities, complicating hookup and commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Oil and Gas Upstream Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Drilling, Production, Well Services Technology: Enhanced Oil Recovery, Seismic Survey, Offshore Platforms, Multilayer Reservoirs End User: Independent Oil Companies, National Oil Companies, Contractors, Service Providers Deployment: Onshore, Offshore, Deepwater, Shallow Water |
| Companies Covered | PTTEP, BP, Petronas, Murphy Oil, Chevron, Shell, Pertamina, Eni, TotalEnergies, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Oil and Gas Upstream Market Evolving Landscape
Digital reservoir characterization and modular production systems are compressing field development timelines, while regulatory pressure on flaring and venting is forcing reinvestment in gas capture infrastructure across Southeast Asian concession areas.
Subsea processing technology is migrating from shallow-water template installations to deepwater standalone configurations. Operators in Myanmar's offshore blocks and Indonesia's frontier basins are piloting subsea boosting and separation units that eliminate surface platform requirements. This migration from topside-dependent to seabed-based production architecture is reshaping contracting strategies and equipment supplier qualification criteria.
Indonesia's Gross Split scheme has eliminated cost recovery mechanisms in favor of fixed production shares, altering how contractors book reserves and finance development. International operators now front-load capital efficiency measures and accelerate production ramp schedules to preserve project returns. This policy shift most affects deepwater and remote gas projects where development costs exceed shallow-water benchmarks.
Integrated service contracting is displacing discrete equipment procurement across Southeast Asian offshore developments. National oil companies in Vietnam and Thailand now bundle drilling, completion, and subsea installation under single-source agreements that transfer execution risk to contractors. This consolidation is most visible in the Gulf of Thailand, where PTTEP has compressed supplier panels and extended contract durations to secure rate commitments.
Southeast Asia Oil and Gas Upstream Market Segmentation
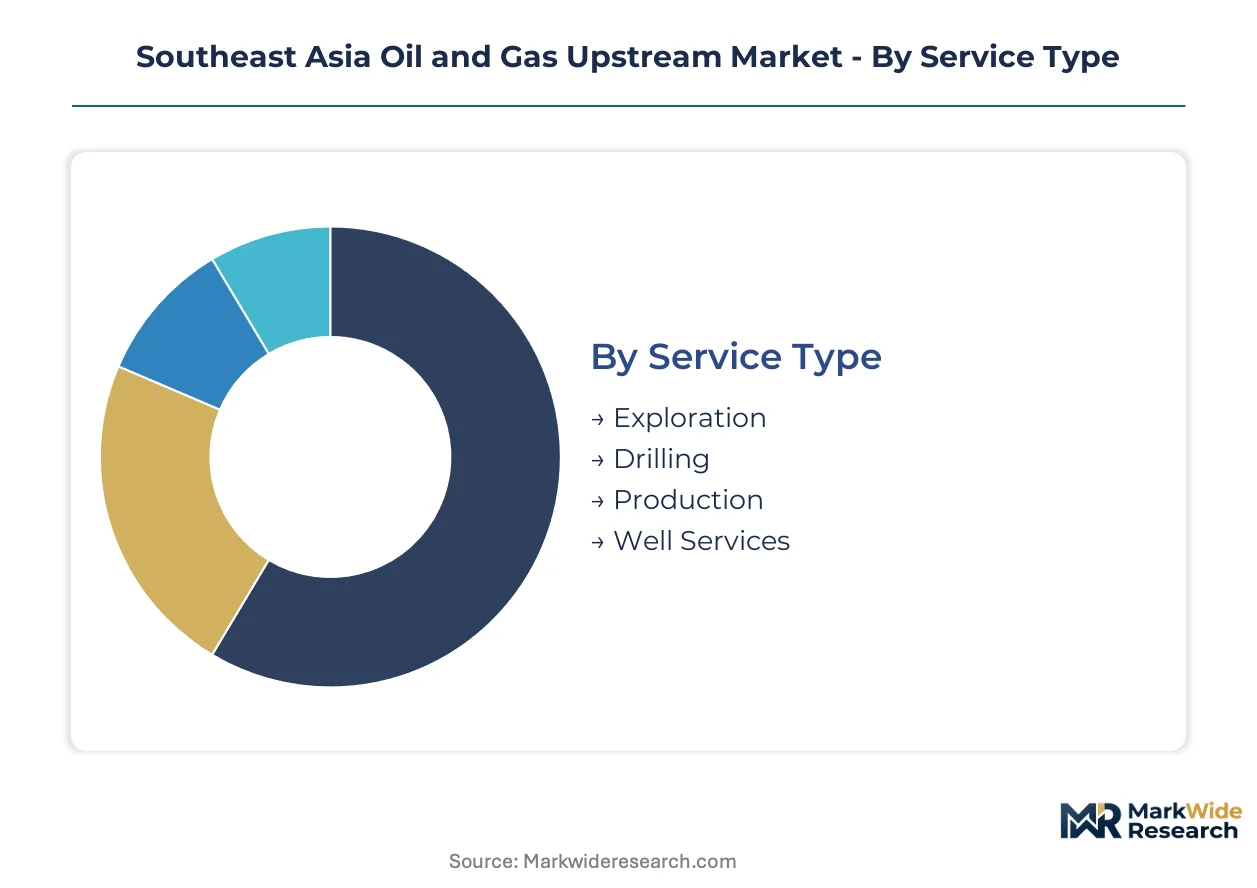
Segmentation in Southeast Asia's upstream market reveals how capital cycles, technical complexity, and regulatory exposure vary across service lines and deployment modes. Operators allocate budgets differently depending on whether they are chasing frontier discoveries or sustaining mature field output.
Service Type:
Exploration and drilling services turn over fastest as operators front-load capital to secure acreage and prove reserves, while production and well services run on longer maintenance cycles tied to field life.
- Exploration:Seismic acquisition and frontier basin surveying absorb the largest single-year capital commitments across Indonesia's Natuna Sea and Myanmar's offshore blocks. Frontier commitments in these geographies pull investment toward high-specification vessels and subsurface imaging capabilities.
- Drilling:Rig contracting spans jackup platforms for shallow water and dynamically positioned drillships for deepwater targets. Malaysia's PETRONAS and Indonesia's Pertamina anchor rig demand through multi-year term contracts that secure availability ahead of licensing rounds.
- Production:Field development engineering and surface facility construction operate on 3-5 year project timelines. Thailand's PTTEP concentrates production spending on Gulf of Thailand gas hub expansions.
- Well Services:Completion, intervention, and workover activity tracks producing well counts across mature basins. Malaysia's Sarawak and Sabah fields generate steady demand for artificial lift and stimulation services.
Drilling anchors the volume base while exploration gains share at the steepest rate.
Technology:
Cost tiers separate proven surface technologies from capital-intensive subsea systems, with margins compressing on standardized equipment and expanding on proprietary recovery methods.
- Enhanced Oil Recovery:Tertiary extraction methods including CO2 injection, chemical flooding, and thermal recovery target declining reservoirs in Malaysia's Dulang field and Brunei's Champion complex. These technologies command premium pricing due to specialized chemical supply chains and reservoir engineering expertise.
- Seismic Survey:3D and 4D seismic acquisition underpins exploration portfolio decisions across Indonesia's frontier basins. Contractors concentrate acquisition assets where licensing activity is most intense.
- Offshore Platforms:Fixed-leg jackets, compliant towers, and floating production systems serve water depths from 20 to 1,500 meters. Vietnam's shallow-water Ca Mau gas province relies on standardized platform designs.
- Multilayer Reservoirs:Commingled production from stacked pay zones maximizes recovery from complex geology. Thailand's Bongkot field exemplifies multilayer development with separate completions across Miocene sandstone intervals.
Offshore platforms anchor the volume base while enhanced oil recovery climbs the fastest.
End User:
Customer type determines procurement leverage, with national oil companies extracting local content concessions and independents prioritizing capital efficiency over supplier development.
- Independent Oil Companies:Smaller explorers with concentrated asset portfolios in Vietnam's Cuu Long basin and Indonesia's Mahakam block. These operators favor turnkey contracting to limit overhead.
- National Oil Companies:PETRONAS, PTTEP, Pertamina, and PetroVietnam control majority equity positions across Southeast Asian concessions. Their procurement mandates shape supplier qualification and local partnership requirements.
- Contractors:International oil companies operating under production-sharing contracts in Indonesia's Gross Split regime and Malaysia's risk-service arrangements. Shell, ExxonMobil, and Chevron navigate evolving fiscal terms.
- Service Providers:Schlumberger, Halliburton, and regional specialists delivering integrated drilling and completion packages. These firms absorb execution risk under lump-sum contracts in Thailand's Gulf developments.
National oil companies anchor the volume base while independents gain share at the steepest rate.
Deployment:
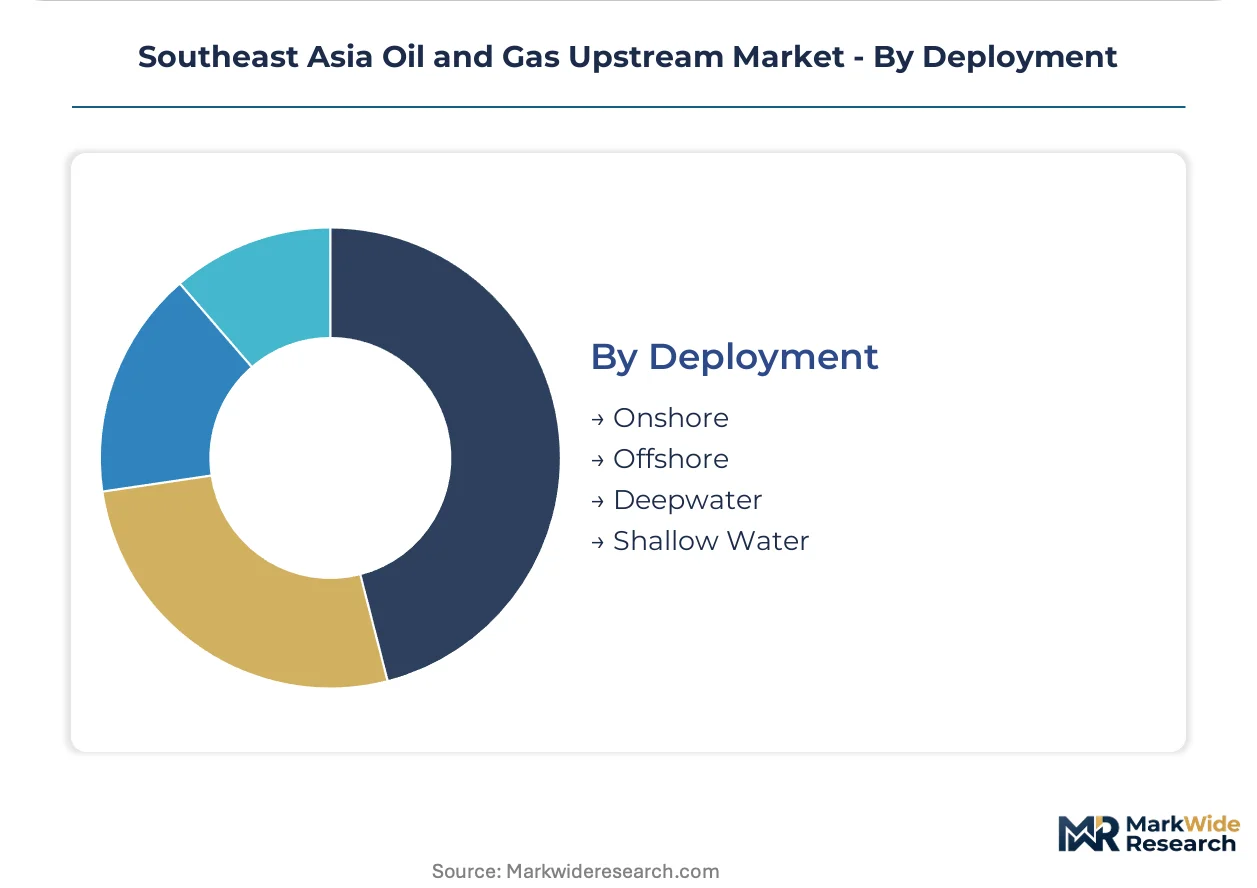
Water depth correlates directly with capital intensity and project duration, shallow water permitting faster payback while deepwater developments extend commitment horizons.
- Onshore:Limited to Indonesia's Sumatra and Java basins, onshore drilling employs conventional land rigs with lower day rates than offshore equivalents. Pertamina operates mature onshore fields with established infrastructure.
- Offshore:The dominant deployment mode encompassing fixed platforms and floating systems across Malaysia, Thailand, and Vietnam. Offshore activity commands the majority of regional upstream capital allocation.
- Deepwater:Water depths exceeding 400 meters in Indonesia's East Natuna and Myanmar's ultra-deepwater blocks. Subsea production systems and dynamic positioning drillships concentrate execution capability among a handful of global contractors.
- Shallow Water:Depths below 400 meters across the Gulf of Thailand and Malaysia's Peninsular Malaysia offshore. Jackup rigs and fixed platforms dominate this segment with shorter mobilization times.
Shallow water anchors the volume base while deepwater gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asia's upstream sector balances domestic supply security against LNG export commitments, with import dependency rising in Thailand and Vietnam even as Indonesia and Malaysia retain net exporter status. The region's crude trade flows increasingly favor medium-sour grades from Middle Eastern suppliers to feed new refinery capacity.
Indonesia
East Natuna's high-CO2 gas reserves and Mahakam block transition dominate investment calendars, with Pertamina assuming operatorship from international legacy holders. The Ministry of Energy and Mineral Resources applies Gross Split PSC terms that eliminate cost recovery in favor of fixed equity shares, compressing contractor margins. Riau Islands province hosts concentrated exploration drilling targeting pre-salt analogs beneath the Natuna Sea.
Malaysia
Sarawak's deepwater Kikeh and Gumusut-Kakap complexes sustain production plateau through subsea tiebacks, while marginal field clusters off Peninsular Malaysia require enhanced recovery to maintain output. PETRONAS enforces Petroleum Development Act local content thresholds that mandate domestic fabrication yard participation in platform construction. Miri and Bintulu anchor the supply chain, with Bintulu's LNG export terminal underwriting gas field development economics.
Thailand
Gulf of Thailand gas hubs at Bongkot and Erawan face natural decline rates exceeding 15% annually, forcing PTTEP toward artificial lift and infill drilling programs. The Department of Mineral Fuels regulates concession extensions contingent on minimum work program commitments. Songkhla and Rayong provinces concentrate offshore service vessel activity and onshore gas processing infrastructure.
Vietnam
Cuu Long basin oil production and Nam Con Son gas pipeline throughput define upstream priorities, with PetroVietnam seeking foreign partners for ultra-deepwater blocks lacking pipeline connectivity. The National Assembly's periodic petroleum law revisions aim to improve fiscal terms for complex developments. Ba Ria-Vung Tau province hosts the regional drilling supply base and fabrication yards serving southern offshore concessions.
Myanmar
Yetagun and Yadana gas field depletion accelerates despite sanctions-constrained investment, with operators navigating US Treasury Department restrictions on financial transactions. The national energy planner prioritizes offshore licensing rounds for deepwater blocks in the Rakhine Basin. Yangon retains administrative functions while supply chain activity concentrates in Singapore due to infrastructure limitations.
Southeast Asia Oil and Gas Upstream Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a supply chain shaped by national oil company procurement consolidation. The competitive structure exhibits moderate concentration, with PETRONAS and PTTEP anchoring domestic demand and international contractors filling capability gaps in deepwater and subsea segments. Three archetypes dominate: integrated national oil companies with full value chain control, international oil companies operating under production-sharing contracts, and integrated service providers absorbing execution risk through lump-sum contracting. Competitive dynamics center on strategic partnerships for frontier basin access and portfolio high-grading to concentrate capital in core positions.
Among Southeast Asian national oil companies, PTTEP exemplifies the integrated domestic operator archetype, leveraging captive offshore acreage to anchor Gulf of Thailand gas production. Petronas occupies a distinctive position through upstream-downstream integration extending from Sarawak deepwater fields to Bintulu LNG export capacity. Shell represents the international operator archetype, navigating late-life asset optimization in Brunei and Malaysia through specialized enhanced recovery techniques rather than frontier exploration commitment.
| Leading Market Players |
|---|
| PTTEP |
| BP |
| Petronas |
| Murphy Oil |
| Chevron |
| Shell |
| Pertamina |
| Eni |
| TotalEnergies |
| Others |
Value Network & Pricing Analysis
The Singapore-Johor Strait marine logistics corridor anchors equipment mobilization costs for subsea installation fleets, concentrating pricing power among integrated service providers while forcing differentiation between premium deepwater-capable contractors and standard shallow-water operators serving Thailand's Gulf of Thailand gas fields.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in rig day rates and fabrication yard slots across multi-year development programs. Price differentiation hinges on water depth capability and local content certification tier under PETRONAS mandates. Cost compression in shallow-water jackup contracting is intensifying because Malaysian fabrication yards compete for limited platform orders. National oil companies exhibit lowest price sensitivity due to supply security mandates, while independent operators in Vietnam's Cuu Long basin demand turnkey pricing to limit capital exposure.
Supply Chain Analysis
Keppel Sembcorp Marine and Hyundai Heavy Industries anchor offshore platform fabrication capacity across Singapore and South Korea, with subsea tree assembly concentrating in Houston and Aberdeen. Raw material dependencies center on high-grade structural steel, subsea umbilical thermoplastics, and dynamic riser composites. Single-source vulnerability runs through specialized forging houses producing blowout preventer stacks. Distribution runs through integrated service contracting that bundles engineering, procurement, and construction under lump-sum arrangements transferring execution risk to tier-one contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where integrated well intervention and artificial lift contracts expand faster than standalone drilling hardware, capturing recurring revenue from Thailand's mature Gulf of Thailand gas fields requiring sustained pressure maintenance.
For Market Incumbents: Pre-empt margin erosion in shallow-water drilling by securing exclusive subsea installation partnerships with PETRONAS for Sarawak deepwater tiebacks. Consolidate position through backward integration into riser manufacturing to offset procurement timeline inflation from local content mandates. Lock in multi-year platform maintenance contracts before independent operators enter Malaysia's decommissioning segment. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's ultra-deepwater blocks lacking pipeline connectivity, where floating LNG offtake solutions bypass infrastructure bottlenecks. Target carbon capture integration projects in Indonesia's high-CO2 Natuna fields as the most penetrable frontier. Pursue joint-venture structures with Pertamina to navigate Gross Split PSC terms that compress standalone contractor margins. For Investors and Strategic Acquirers: Carve-out targets emerge from international oil companies divesting late-life assets in Brunei and Malaysia's Peninsular Malaysia offshore, where enhanced recovery specialization unlocks residual value. Five-to-ten year viability hinges on reservoir engineering capability scarcity and regulatory stability in Indonesian licensing. Watch PETRONAS local content threshold adjustments as the signal for procurement cost inflection across regional supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Bundles drilling, completion, and subsea installation under single-source agreements that transfer execution risk to contractors across PTTEP's Gulf of Thailand developments. |
| Carbon Capture Infrastructure Buildout | Unlocks stranded gas in Indonesia's Sunda Strait and Natuna high-CO2 reservoirs while qualifying operators for emission reduction credits under evolving frameworks. |
| Decommissioning Capability Expansion | Addresses underserved demand for plug-and-abandonment and topside removal across Malaysia's aging Sarawak and Sabah offshore platforms. |
| Subsea Processing Technology Licensing | Migrates production architecture from topside-dependent to seabed-based configurations in Myanmar's offshore blocks and Indonesia's frontier basins. |
| Local Content Joint Venture Formation | Satisfies PETRONAS Petroleum Development Act mandates by partnering with domestic fabrication yards and engineering houses in Miri and Bintulu. |
Research Methodology
Operator-level perspectives from upstream project managers, drilling contract negotiators, subsea engineering leads, and national oil company procurement officers anchored the qualitative base. Primary interview findings were cross-validated against secondary sources including Indonesia Ministry of Energy and Mineral Resources licensing disclosures, PETRONAS annual activity reports, Vietnam National Assembly petroleum law revisions, and ASEAN customs trade data for offshore equipment imports. Bottom-up field development cost modeling was triangulated with top-down regional production forecasts.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning service type, water depth deployment, technology tier, and end-user procurement leverage. CAGRs were derived from regression analysis against historical capital commitment patterns and forward project sanctioning timelines. Industry-specific forecast inputs incorporated rig day rate trajectories, local content compliance cost indices, and LNG offtake contract durations underwriting upstream field economics.
Stress conditions across crude price bands, regulatory local content threshold adjustments, and deepwater drilling cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding project sanctioning cadence and fiscal term stability. Quarterly review of licensing round participation rates, rig mobilization schedules, and production-sharing contract signature timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Connected Oil and Gas Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
Cased Hole Logging Services Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Ecuador Wireline Logging Services Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Tight Gas Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
South Korea Oil and Gas Market