
 Europe Well Intervention Market | 2026-2036
Europe Well Intervention Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Well Intervention Market Analysis
Independent operators and national oil companies with aging North Sea portfolios is rotating toward higher-frequency light intervention campaigns. Schlumberger Limited leverages its integrated wireline and coiled tubing platform to anchor long-term frame agreements across Norwegian shelf assets. Baker Hughes Company competes through proprietary electrohydraulic tool suites designed for subsea well access. Weatherford International PLC specializes in riserless light well intervention vessels, occupying a differentiated niche in UK and Dutch sectors.
Europe well intervention encompasses engineered services deployed to restore, enhance, or maintain hydrocarbon production from existing wellbores, typically involving real-time downhole diagnostics, chemical stimulation, or mechanical remediation at pressures up to 15,000 psi. Wireline logging and intervention commands the largest revenue pool due to its repeatability and lower marginal cost per intervention, while coiled tubing represents the fastest-expanding segment as operators push live-well milling and plug removal in depleted reservoirs. Electrohydraulic technology leads capital deployment in subsea contexts where mechanical intervention risks escalate with water depth.
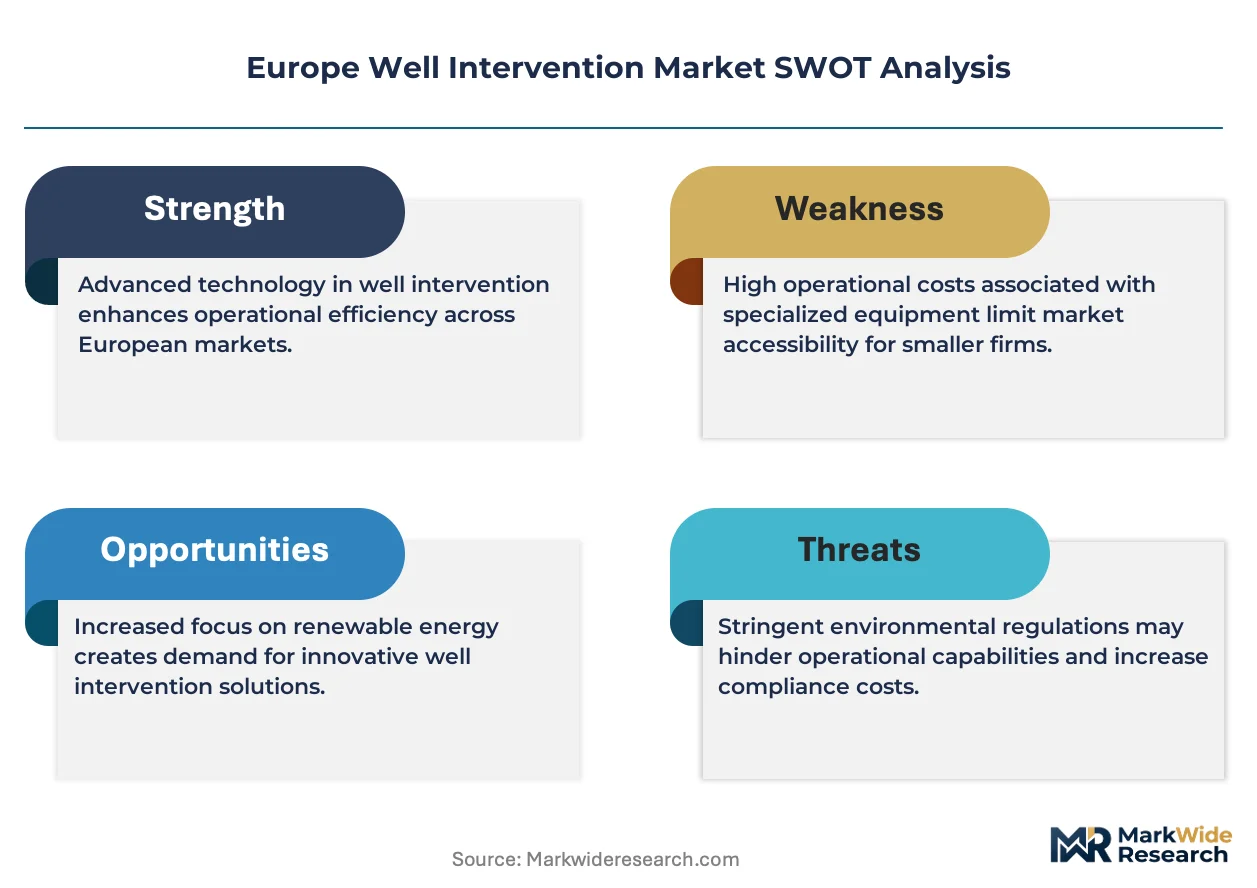
REACH restricts chemical disclosure and hazard classification for stimulation fluids deployed in EU waters, compelling service firms to reformulate additives or source alternatives. The EU Green Deal methane emissions framework pressures operators to prioritize well integrity and leak detection interventions, directly expanding demand for pressure maintenance and troubleshooting applications. Stakeholders must monitor how Norway's Petroleum Safety Authority integrates climate performance criteria into intervention permitting timelines.
Market Dynamics
REACH chemical disclosure mandates and the EU Green Deal methane framework are forcing service firms to reformulate stimulation fluids and prioritize well integrity interventions across Norwegian and UK Continental Shelf assets.
Growth Catalysts
- EU Green Deal methane emissions framework:The regulation pressures operators to accelerate leak detection and pressure maintenance campaigns, directly expanding demand for troubleshooting applications in mature North Sea fields.
- Norwegian brownfield redevelopment programs:National oil companies are rotating capital allocation toward higher-frequency light intervention campaigns to sustain output from aging subsea installations.
- Electrohydraulic tool advancement:Subsea well access technology enables mechanical intervention at extreme water depths where riser-based methods face escalating operational risks.
Market Restraints
- Specialized vessel supply concentration:Riserless light well intervention vessel availability concentrates among a limited pool of North Sea operators, creating capacity bottlenecks during seasonal demand peaks.
- REACH compliance costs:Chemical additive reformulation and hazard classification documentation impose recurring R&D expenditure on service firms operating across EU member states.
- Depleted reservoir technical limitations:Live-well milling and plug removal in low-pressure formations encounter reduced hydrostatic head control, constraining coiled tubing application scope.
Strategic Opportunities
- Dutch sector underpenetration:Smaller independent operators in the southern North Sea present untapped demand for wireline logging and repeatability-focused intervention services.
- Real-time downhole diagnostics convergence:Integration of fiber-optic sensing with electrohydraulic actuation creates differentiated service bundles for subsea well monitoring.
- CSRD sustainability reporting mandate:The directive creates procurement preference for intervention providers with verified emissions tracking and transparent chemical supply chain documentation.
Industry Challenges
- Subsea systems engineering talent scarcity:Deepwater intervention planning requires hybrid expertise in pressure control, marine operations, and real-time data interpretation that outpaces European training pipeline output.
- Legacy well data integration complexity:Decades-old North Sea asset records exist in incompatible formats, delaying diagnostic accuracy and intervention design timelines for brownfield operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Well Intervention Market |
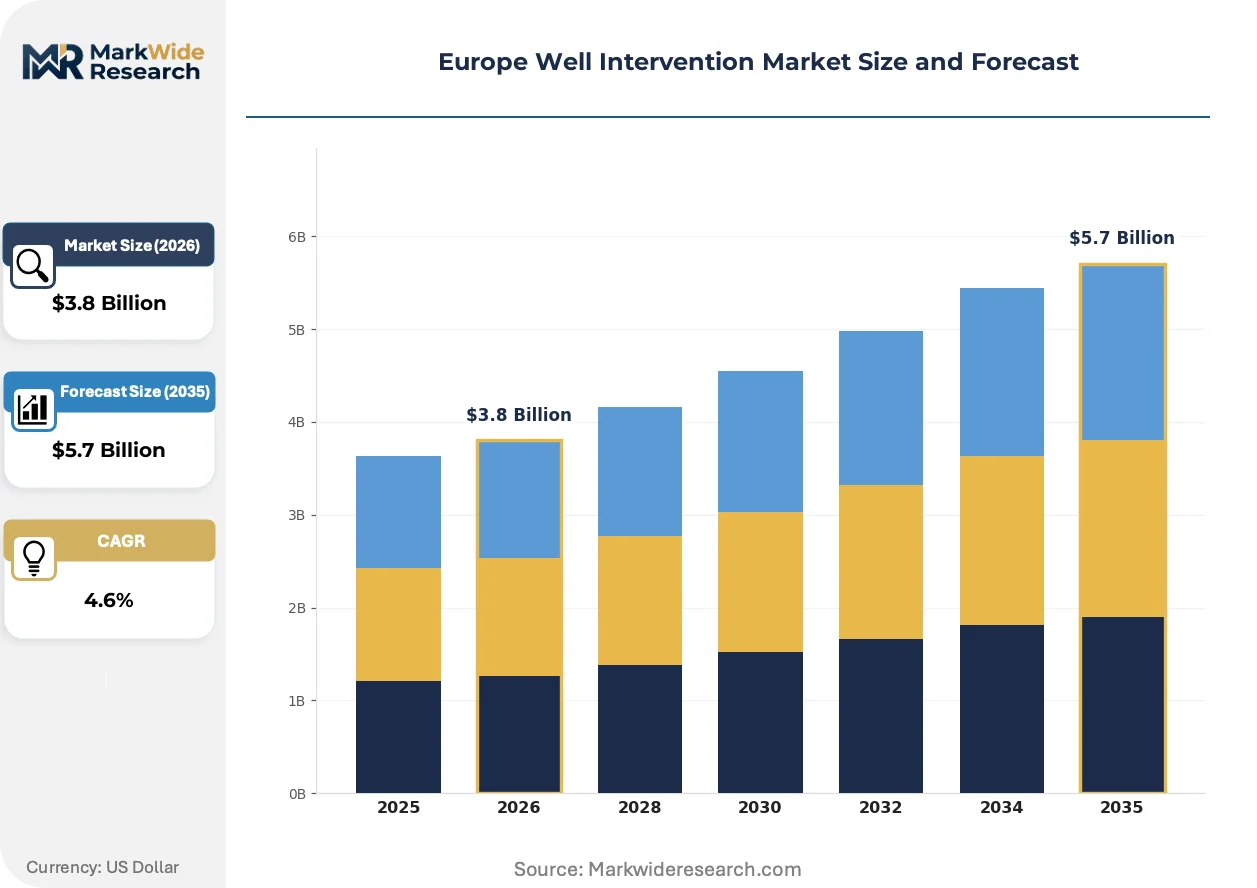
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wireline, Coiled Tubing, Drilling, Snubbing Technology: Electrohydraulic, Mechanical, Chemical, Thermal End User: Oil & Gas, Offshore Exploration, Onshore Production, Consulting Firms Application: Production Enhancement, Troubleshooting, Well Integrity, Pressure Maintenance |
| Companies Covered | Weatherford International PLC, Archer, Schlumberger Limited, Expro Group, Oceaneering International, Halliburton Company, China Oilfield Services, Altus Intervention, Baker Hughes Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Well Intervention Market Emerging Trajectories
Technology trajectories across the European well intervention sector center on subsea access capabilities, chemical transparency mandates, and evolving contractor-operator commercial relationships.
Coiled tubing intervention technology is bifurcating between high-pressure live-well applications in Norwegian deepwater assets and lower-cost, riserless deployments in UK shallow-platform decommissioning campaigns. National oil companies in the northern North Sea are adopting the premium tier fastest, while independent operators in the UK sector prioritize the standardized variant. This split is compressing mid-tier service margins and forcing equipment suppliers to choose specialization over portfolio breadth.
REACH restrictions on chemical disclosure and hazard classification for stimulation fluids are compelling service firms to source bio-based additive alternatives or establish captive formulation laboratories within EU jurisdiction. The industrial consequence is a restructuring of chemical supply relationships, with integrated service companies internalizing previously outsourced blending operations. Wireline and coiled tubing providers with North Sea frame agreements face the most immediate compliance timeline pressure.
Operator procurement of well intervention services is fragmenting from bundled long-term contracts toward discrete campaign-based sourcing with transparent unit pricing. This shift disrupts the traditional frame agreement model that Schlumberger and Baker Hughes have anchored in Norwegian shelf assets. The behavioral change is most visible among UK Continental Shelf independents, who now prioritize intervention flexibility over volume commitment discounts to match erratic production decline curves.
Europe Well Intervention Market Segmentation
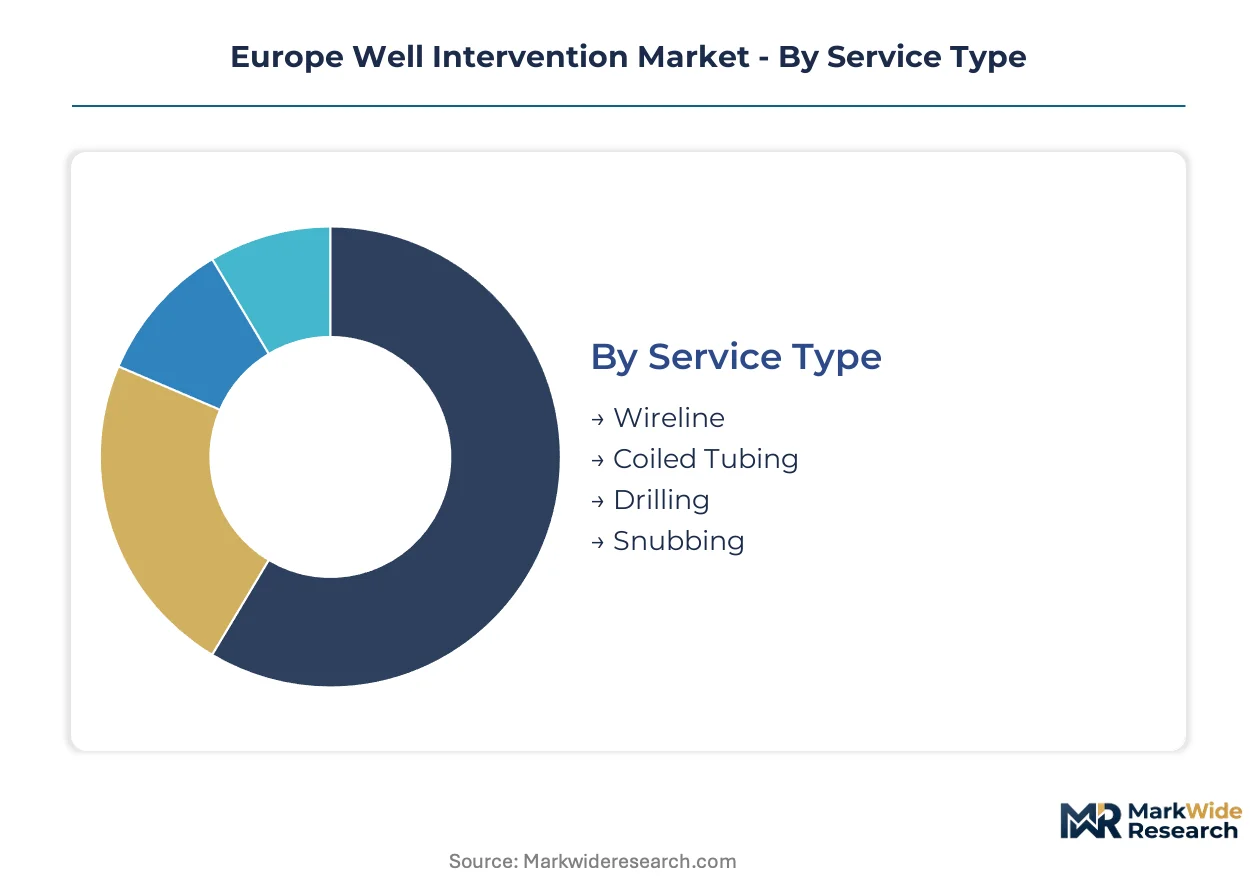
Service differentiation across the European well intervention sector reflects divergent pressure regimes, water depths, and regulatory exposure across the Norwegian and UK Continental Shelves. Segment selection directly determines contractor capability requirements, vessel specifications, and REACH compliance obligations.
Service Type:
Wireline and coiled tubing dominate Norwegian North Sea deployment where subsea complexity demands specialized marine assets, while snubbing and drilling services concentrate in UK shallow-platform decommissioning campaigns.
- Wireline:Deploys electric cable-conveyed tools for logging, perforating, and plug setting at pressures up to 15,000 psi. Norwegian national oil companies favor repeatability-focused wireline campaigns for aging subsea installations facing EU Green Deal methane scrutiny.
- Coiled Tubing:Continuous steel tubing enables live-well milling, stimulation, and plug removal without killing the well. UK and Dutch independents are expanding coiled tubing scope for riserless light interventions in depleted reservoirs where hydrostatic control challenges limit conventional methods.
- Drilling:Workover and sidetrack drilling addresses mechanical failures and reservoir bypass in mature fields.
- Snubbing:Hydraulic workover units perform live-well intervention without killing the well, suited for high-pressure gas wells.
Wireline holds the largest share; momentum sits with coiled tubing as live-well applications expand.
Technology:
Cost tiers separate premium electrohydraulic systems for deepwater Norway from standardized mechanical and chemical approaches in UK shallow waters.
- Electrohydraulic:Subsea well access technology transmits power and control signals through seawater to downhole tools, enabling intervention at extreme depths where riser-based methods face insurmountable pressure and fatigue risks. Norwegian operators anchor capital deployment here.
- Mechanical:Direct mechanical force through wireline or coiled tubing conveys jars, pulling tools, and milling assemblies. UK Continental Shelf independents favor mechanical intervention for standardized platform workovers where cost discipline outweighs technical complexity.
- Chemical:Stimulation fluids, scale inhibitors, and corrosion treatments restore or enhance production.
- Thermal:Steam and hot water injection improves heavy oil mobility in specific North Sea formations.
Electrohydraulic commands premium pricing; chemical faces steepest reformulation pressure under REACH.
End User:
Customer type determines procurement rhythm, with national oil companies favoring frame agreements and independents adopting campaign-based sourcing.
- Oil & Gas:Integrated majors and national oil companies with aging North Sea portfolios drive sustained intervention demand. Norwegian operators rotate capital toward higher-frequency light campaigns to sustain output from brownfield assets.
- Offshore Exploration:Frontier drilling programs require contingency intervention capability for well control and completion remediation.
- Onshore Production:Limited European onshore activity concentrates in mature Dutch and German gas fields.
- Consulting Firms:Engineering advisors procure intervention planning and real-time diagnostics for operator clients.
Oil and gas operators dominate volume; consulting firms represent the fastest-climbing customer type as procurement externalizes.
Application:
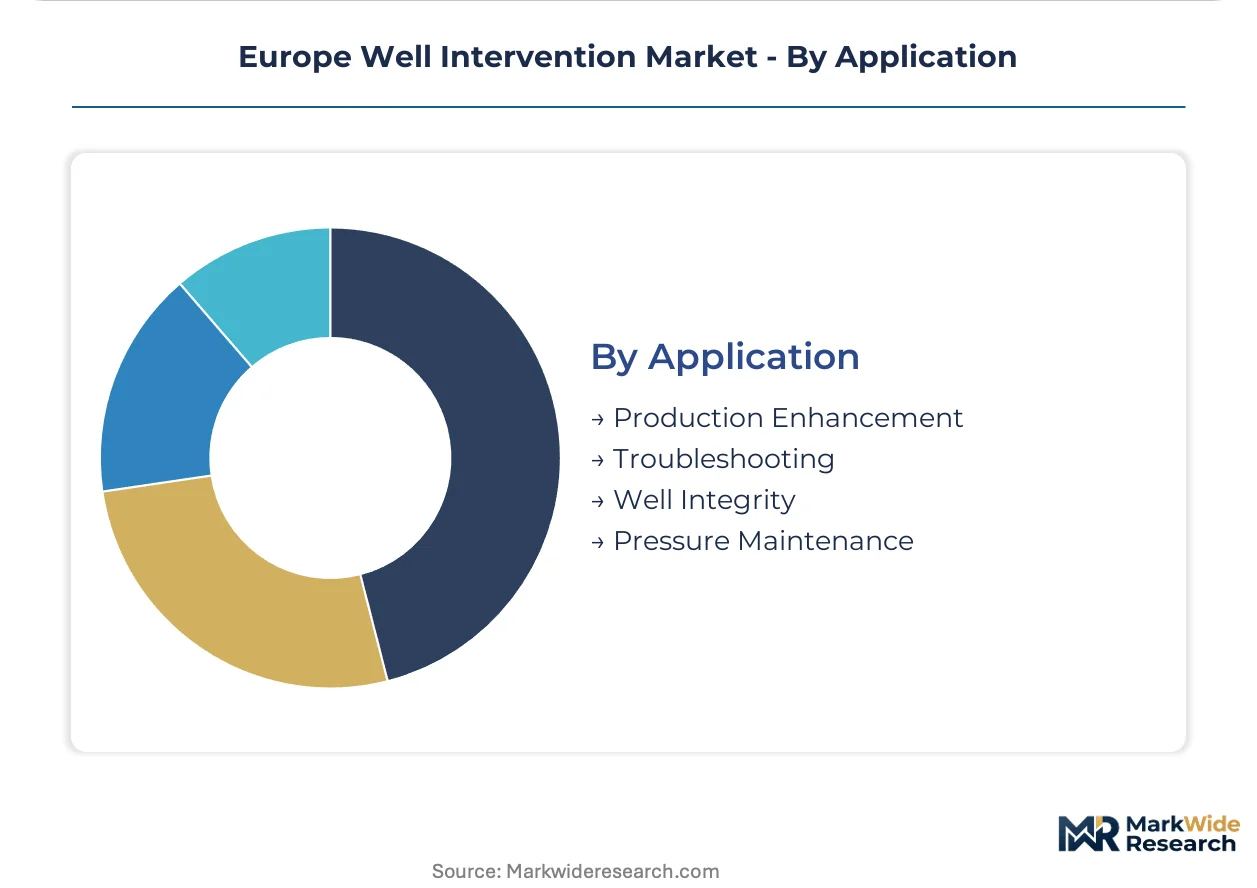
Application mix tracks field maturity, with Norwegian assets prioritizing well integrity and UK fields emphasizing production enhancement.
- Production Enhancement:Stimulation, reperforation, and artificial lift optimization restore or increase hydrocarbon output. UK independents facing erratic decline curves favor flexible production enhancement contracts over long-term volume commitments.
- Well Integrity:Leak detection, corrosion mitigation, and barrier verification ensure containment. EU Green Deal methane frameworks directly expand well integrity demand across Norwegian and UK assets.
- Troubleshooting:Diagnostic intervention resolves unexplained production anomalies or equipment failures.
- Pressure Maintenance:Gas lift, water injection, and chemical injection sustain reservoir energy.
Production enhancement retains the largest application share; well integrity gains share fastest under emissions regulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Johan Sverdrup pipeline and processing complex anchors Norway's position as the primary intervention demand hub. UK North Sea infrastructure at Aberdeen and Great Yarmouth sustains the second-largest service market. Dutch and Danish sectors complete the continental perimeter.
Norway
Equinor's brownfield redevelopment programs drive sustained wireline and coiled tubing demand across the Norwegian Continental Shelf. The Petroleum Safety Authority integrates climate performance criteria into intervention permitting timelines, accelerating well integrity campaign frequency. Stavanger and Bergen host concentrated service contractor clusters executing subsea electrohydraulic deployments.
United Kingdom
Independent operators facing erratic production decline curves favor flexible campaign-based sourcing over long-term frame agreements. The North Sea Transition Authority's decommissioning timelines pressure asset owners to maximize late-life recovery through light intervention. Aberdeen maintains its position as the primary logistics and engineering coordination center for UK shelf operations.
Netherlands
Smaller independents in the southern North Sea present underpenetrated demand for riserless light well intervention vessels and repeatability-focused wireline services. REACH compliance obligations apply fully to Dutch territorial waters, compelling additive reformulation for stimulation campaigns. Rotterdam and Den Helder service clusters support platform-based mechanical intervention workovers.
Denmark
TotalEnergies and INEOS-operated mature fields generate consistent demand for pressure maintenance and troubleshooting applications. The Danish Energy Agency's emissions reporting requirements align with EU Green Deal methane frameworks, expanding leak detection intervention scope. Esbjerg functions as the primary North Sea supply base for Danish offshore operations.
Europe Well Intervention Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology differentiation dimensions. The vendor structure concentrates around integrated service majors with frame agreement dominance, mid-tier regional specialists, and niche vessel operators. Three archetypes define competitive positioning: full-service wireline-coiled tubing integrators, subsea electrohydraulic technology purveyors, and riserless light intervention vessel specialists. Consolidation pressure manifests through strategic partnerships for vessel capacity access and technology licensing arrangements for REACH-compliant chemical formulations.
Among integrated service providers, Schlumberger Limited, Baker Hughes Company, and Weatherford International PLC exemplify divergent specialization vectors. Schlumberger anchors the full-service archetype through combined wireline and coiled tubing platform offerings. Baker Hughes occupies the electrohydraulic technology tier with subsea well access capabilities. Weatherford represents the differentiated vessel-based segment through riserless light intervention specialization.
| Leading Market Players |
|---|
| Weatherford International PLC |
| Archer |
| Schlumberger Limited |
| Expro Group |
| Oceaneering International |
| Halliburton Company |
| China Oilfield Services |
| Altus Intervention |
| Baker Hughes Company |
| Others |
Supply Flow & Price Mechanics
REACH chemical disclosure mandates and EU Green Deal methane frameworks gate both supplier qualification and price differentiation across the European well intervention sector, compelling service firms to absorb reformulation costs while premium electrohydraulic tiers command certification premiums.
Pricing Analysis
Volume-discount tiering structures separate Norwegian national oil company frame agreements from UK independent campaign-based sourcing. Premium electrohydraulic subsea services anchored by Equinor contracts command substantial price premiums over standardized mechanical platform workovers. Cost compression in the mid-tier wireline segment intensifies as REACH compliance expenses accumulate without offsetting differentiation. UK independents exhibit highest price sensitivity, rotating procurement toward transparent unit pricing over bundled long-term commitments.
Supply Chain Analysis
Extended lead times for specialized riserless light well intervention vessels concentrate inventory pressure among North Sea operators during seasonal demand peaks. Equipment manufacturing draws from Norway, the United Kingdom, and the Netherlands for subsea tool assemblies and pressure control systems. High-grade steel tubing, specialized electronics, and REACH-compliant chemical additives constitute critical input dependencies. Single-source vulnerability concentrates in electrohydraulic actuation components sourced from limited European specialty manufacturers. Distribution runs through Stavanger, Aberdeen, and Den Helder service clusters coordinating vessel mobilization and offshore logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity expands as operator procurement shifts from bundled frame agreements toward discrete campaign-based sourcing with transparent unit pricing, creating niche entry points for specialized vessel operators and REACH-compliant chemical formulators.
For Market Incumbents: Fortify frame agreement dominance in Norwegian brownfield assets through captive REACH-compliant formulation laboratories and integrated wireline-coiled tubing platform bundling. Deepen vertical integration into chemical additive manufacturing to neutralize reformulation cost pressures from ECHA disclosure mandates. Prioritize subsea electrohydraulic R&D investment to defend premium pricing tiers against mechanical intervention commoditization in UK shallow waters. For New Entrants and Emerging Players: Differentiate on riserless light well intervention vessel specialization targeting Dutch southern North Sea independents with underpenetrated demand. Capture white-space in real-time fiber-optic diagnostic integration with electrohydraulic actuation for subsea well monitoring. Pursue campaign-based procurement relationships with UK Continental Shelf operators prioritizing intervention flexibility over volume commitment discounts. For Investors and Strategic Acquirers: CSRD sustainability reporting mandates reshape the acquisition landscape toward intervention providers with verified emissions tracking and transparent chemical supply chain documentation. Target mid-tier regional specialists with established Norwegian Petroleum Safety Authority relationships and captive REACH-compliant formulation capabilities. Monitor integration of climate performance criteria into intervention permitting timelines as inflection signal for well integrity service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Chemical Formulation Captive | ECHA disclosure mandates force internalization of previously outsourced additive blending operations. |
| Subsea Electrohydraulic Technology Licensing | Extreme water depth intervention capabilities unlock Norwegian deepwater brownfield redevelopment programs. |
| Riserless Light Well Intervention Vessel Partnership | Capacity access agreements alleviate seasonal bottlenecks for UK and Dutch sector campaign demand. |
| Real-Time Downhole Diagnostics Integration | Fiber-optic sensing convergence with electrohydraulic actuation creates differentiated subsea monitoring bundles. |
| Frame Agreement Reconstitution | Discrete campaign-based sourcing with transparent unit pricing disrupts traditional bundled contract structures. |
Methodological Framework
The analysis maps wireline logging, coiled tubing intervention, electrohydraulic subsea access, and chemical stimulation services, each validated through primary interviews with offshore operations directors, well integrity engineers, procurement managers at national oil companies, and vessel chartering specialists, combined with secondary triangulation against Norwegian Petroleum Safety Authority permitting databases, UK North Sea Transition Authority decommissioning timelines, EU ECHA REACH registration filings, and operator capital expenditure disclosures, with bottom-up service type enumeration cross-checked against top-down regional spend estimates.
Consistency checks validated volume and value outputs against external benchmarks including national oil company reported intervention frequencies, vessel utilization tracking from North Sea supply bases, and chemical additive trade flow data. Segmentation dimensions modeled encompass service type, technology tier, water depth regime, operator ownership structure, and regulatory exposure cluster across the projection horizon. CAGRs derive from trend extrapolation of brownfield redevelopment capital allocation patterns, methane emissions framework compliance cost trajectories, and subsea installation age distribution profiles.
The analysis sits within stated boundaries; outcomes outside sustained Norwegian brownfield investment, stable REACH enforcement timelines, or continued UK late-life recovery prioritization would require recalibration. Forecasts reflect documented assumptions regarding vessel supply concentration, electrohydraulic technology adoption curves, and chemical reformulation cost pass-through elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Global Fracking Fluids and Chemicals Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Desalter Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Qatar Oilfield Chemicals Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Algeria Oil and Gas Downstream Market