
 Aluminium ROPP Closures Market | 2026-2036
Aluminium ROPP Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium ROPP Closures Market Analysis
Multi-source procurement among beverage packagers is expanding as brands seek supply resilience against raw aluminium volatility. Crown Holdings Inc. leverages its integrated coil-to-closure footprint across multiple continents. Silgan Holdings Inc. competes through high-volume stamping lines optimized for carbonated drink bottlers. Guala Closures Group differentiates via anti-counterfeit banding technologies for premium spirits.
Aluminium Roll-On Pilfer-Proof closures are threaded metal caps formed from aluminium sheet, typically 0.20–0.30 mm thick, with an internal liner of pulp-board or polymer bonded to the shell; they seal via compression against a bottle neck finish and provide tamper evidence through a breakable skirt band. Their primary purpose is to preserve product integrity while enabling resealability for beverages, pharmaceuticals, and food oils. Screw Top variants dominate volume in carbonated drinks and spirits where torque consistency matters, while Child Resistant closures command premium positioning in pharmaceutical and personal care segments where ISO 8317 compliance is mandatory. Stamping technology leads production economics at scale, though extrusion gains share in lightweight designs where material thickness reduction is prioritized.
FDA food-contact notifications and EU REACH Annex XVII restrictions on heavy metals shape liner formulation choices and metal sourcing requirements for suppliers accessing North American and European markets. India's BIS certification for packaging materials and China's GB standards for food-contact metals add compliance layers for exporters targeting Asia. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and state-level bottle bill expansions in the US, as these programs increasingly assign closure collection and recycling obligations to manufacturers rather than municipalities.
Market Dynamics
Lightweighting imperatives are compressing material specifications across beverage packaging, forcing closure manufacturers to reconcile thinner aluminium gauges with torque integrity requirements and liner adhesion performance.
Growth Catalysts
- India's FSSAI packaging mandates:Stricter food-contact material standards are accelerating aluminium closure adoption in edible oil and spirits bottling, displacing plastic alternatives in formal retail channels.
- Carbonated drink bottlers:These end-users are specifying screw-top ROPP variants with optimized thread profiles to reduce capping torque variance and line stoppages during high-speed filling operations.
- Extrusion forming:This production technology is enabling 15-20% material thickness reduction versus conventional stamping, aligning with brand owner sustainability targets without compromising seal integrity.
Market Restraints
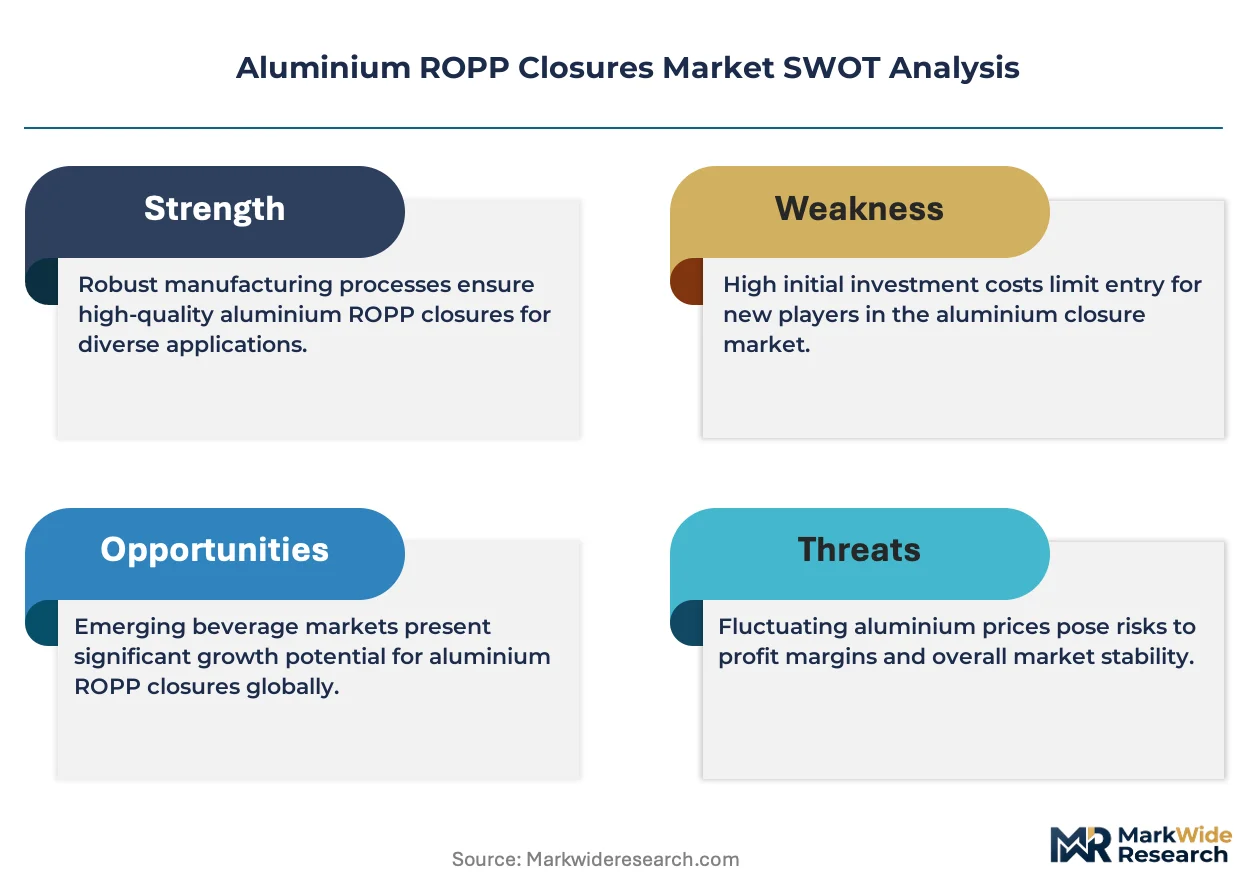
- Primary aluminium price volatility:LME price swings directly compress converter margins, particularly for non-integrated stampers lacking captive coil supply or long-term hedge positions.
- Liner compound concentration:EU REACH Annex XVII restrictions on phthalates and heavy metals have consolidated approved polymer suppliers to three dominant specialty chemical producers, creating single-source risk.
- Polymer closure substitution:Polypropylene screw caps with oxygen-scavenging liners are capturing share in still water and low-acid juice segments where reseal frequency is low and cost minimization dominates.
Strategic Opportunities
- Vietnam's spirits packaging upgrade:Premium local distilleries are importing European capping lines and specifying anti-counterfeit banded closures, creating demand for security-featured ROPP variants.
- Extended producer responsibility frameworks:France's AGEC law and impending EU Packaging and Packaging Waste Regulation revisions will assign closure collection obligations to manufacturers, favoring aluminium's established recycling infrastructure over multi-material alternatives.
- Digital printing convergence:Laser-etched variable data on closure shells combined with NFC-enabled liner inserts is enabling bottle-level traceability for pharmaceutical and high-value food applications.
Industry Challenges
- Tooling and die engineering expertise:The specialized knowledge required for thin-gauge aluminium thread forming is concentrating among aging technician populations in Germany and Japan, constraining capacity expansion.
- ISO 8317 certification timelines:Child-resistant closure validation for pharmaceutical applications requires 12-18 month testing cycles with designated testing laboratories, delaying product launches and freezing design iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium ROPP Closures Market |
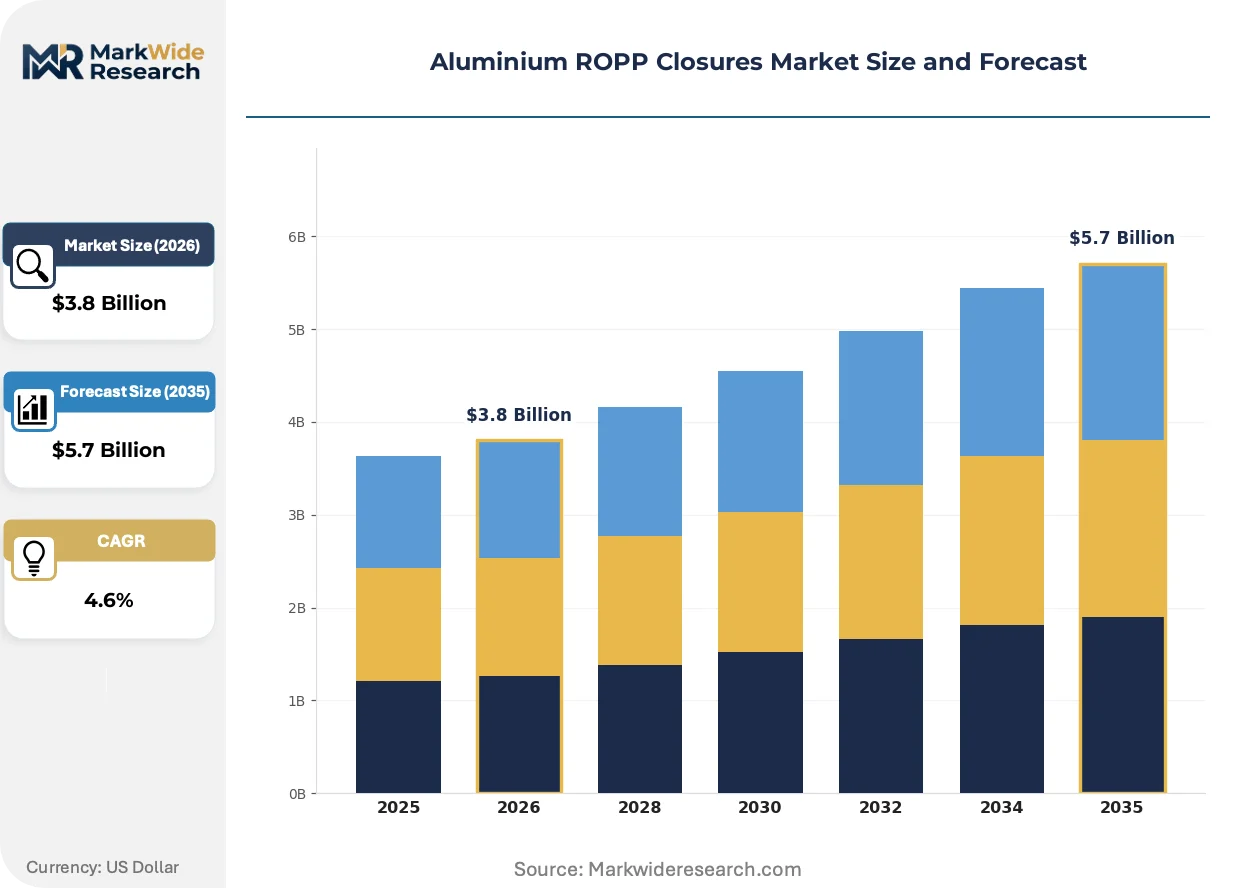
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Closure Type: Standard, Screw Top, Child Resistant, Light-Weight End User: Beverage, Pharmaceutical, Personal Care, Food Production Technology: Stamping, Extrusion, Machining, Die Casting Application: Carbonated Drinks, Oils, Spirits, Juices |
| Companies Covered | Crown Holdings Inc., Oriental Containers Limited, Amcor Limited, Federfin Tech S.r.l., Pelliconi & C. S.p.A., Guala Closures Group, Silgan Holdings Inc., Ramondin S.A., Closure Systems International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium ROPP Closures Market Emerging Trajectories
Material science advances and regulatory precision are converging to redefine closure performance standards. Manufacturers are prioritizing gauge reduction, liner reformulation, and digital traceability as competitive differentiators across beverage and pharmaceutical end-uses.
Micro-perforated tear-band technology is integrating laser scoring patterns with controlled residual thickness to enable consistent tamper-evident fracture at lower opening torque. Premium spirits bottlers in Scotland and Cognac are specifying this variant to balance security with consumer accessibility. The technology is integrating quality control systems that monitor perforation depth in real-time, compressing defect rates and reducing manual inspection labor.
EU REACH Annex XVII restrictions on nickel release and heavy metal content are compelling liner compound reformulations using calcium carbonate-filled polyolefins instead of conventional PVC plastisols. Closure manufacturers serving German and French markets are qualifying alternative polymer systems through EFSA food-contact notifications. Pharmaceutical packaging suppliers face the most stringent migration testing requirements, driving dual-track formulation strategies that segregate EU-compliant from legacy product streams.
Direct-to-contractor procurement models are consolidating purchasing authority at multinational beverage groups, displacing traditional distributor intermediaries in closure supply. Procurement teams at these bottlers are mandating supplier sustainability certifications and carbon footprint disclosures as gate criteria for tender participation. This concentration is most visible in North American carbonated soft drink and Mexican beer export operations, where three buying groups control over half of regional aluminium closure volume.
Aluminium ROPP Closures Market Segmentation
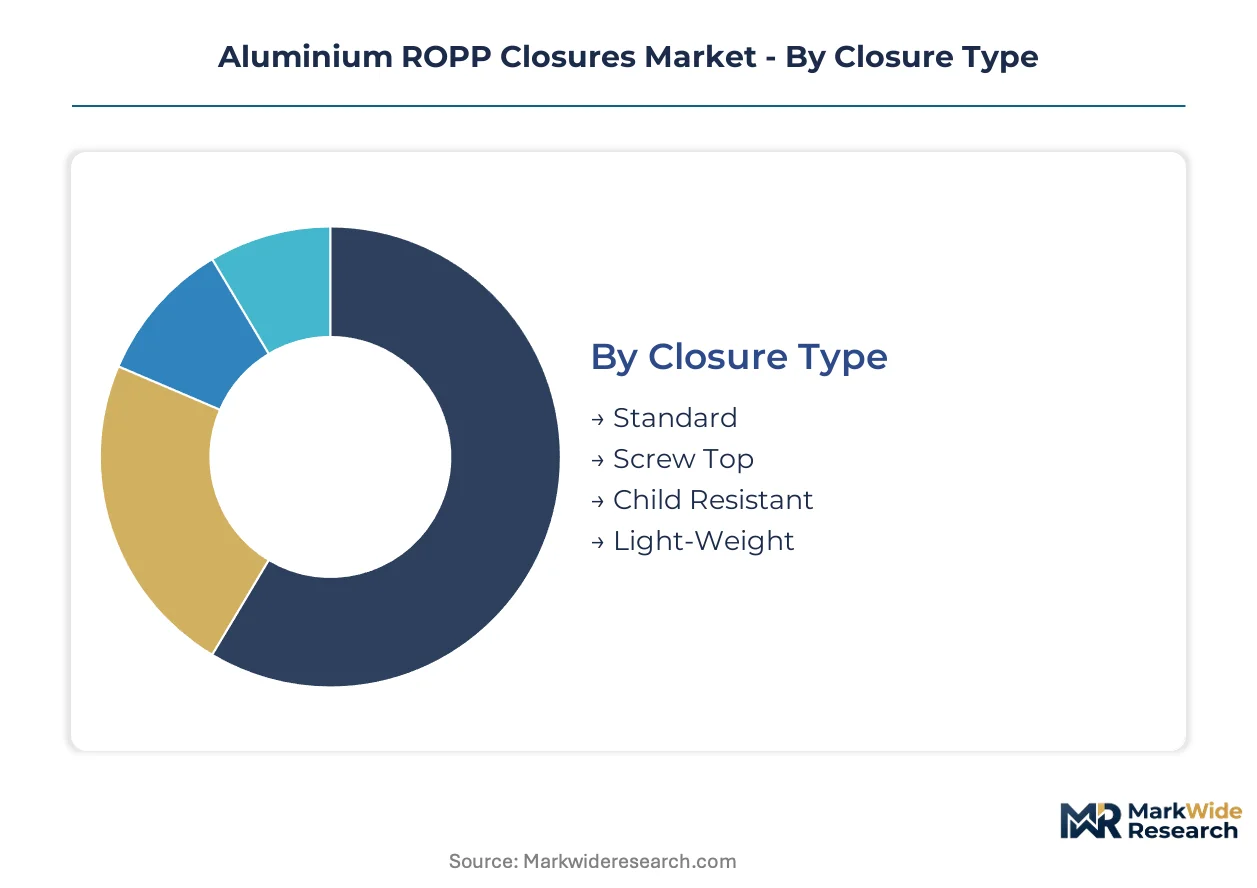
Aluminium ROPP closure specifications diverge sharply across end-use requirements, with pharmaceutical and beverage applications demanding incompatible certification tracks. Material thickness, liner chemistry, and thread geometry must align precisely with target segment torque and migration standards.
Closure Type:
FDA food-contact notifications and EU REACH Annex XVII compliance burdens concentrate most heavily on Child Resistant variants, while Screw Top specifications emphasize torque consistency for high-speed bottling lines.
- Screw Top:Threaded caps with optimized pitch profiles deliver consistent capping torque for carbonated drink bottlers running 60,000+ bottles per hour. Demand concentrates in Mexico and US beer export facilities where Crown Holdings and Silgan operate integrated coil-to-closure plants.
- Child Resistant:Push-and-turn mechanisms meeting ISO 8317 requirements command 12-18 month validation cycles with designated testing laboratories. Pharmaceutical packagers in Germany and Switzerland absorb premium pricing to secure CR certification for analgesic and prescription liquid formulations.
- Standard:Basic threaded shells without tamper-evident bands serve edible oil bottlers in India's formal retail channels where FSSAI mandates displace plastic alternatives.
- Light-Weight:Gauge-reduced shells formed via extrusion rather than stamping align with brand owner sustainability targets; 15-20% material reduction is achievable without seal integrity compromise.
Screw Top sits at the top of the volume ranking, with Light-Weight climbing the fastest.
End User:
Cost tier differentiation separates premium pharmaceutical specifications from commodity beverage volumes, with liner compound costs varying by an order of magnitude across the spectrum.
- Beverage:Carbonated soft drink and spirits bottlers specify high-volume Screw Top variants with pulp-board or polyolefin liners. India's spirits packaging upgrade and Vietnam's premium distillery imports are driving security-featured ROPP demand with anti-counterfeit banding.
- Pharmaceutical:ISO 8317-compliant Child Resistant closures with EFSA-notified liner compounds serve oral liquid and prescription markets. Migration testing requirements in Germany and France enforce dual-track formulation strategies segregating EU-compliant from legacy product streams.
- Personal Care:Cosmetic and fragrance applications prioritize aesthetic finishes and torque consistency over regulatory burden; metal shell decoration capabilities determine supplier selection.
- Food:Edible oil bottlers in India and Southeast Asia specify Standard closures with BIS-certified materials; FSSAI packaging mandates are accelerating aluminium adoption against plastic competitors.
Beverage commands the dominant volume position, with Pharmaceutical expanding most quickly on CR certification premiums.
Production Technology:
Application requirements dictate technology selection, with high-speed beverage lines favoring stamping economics and lightweight premium spirits demanding extrusion precision.
- Stamping:High-speed progressive dies process 0.20-0.30 mm aluminium coil into threaded shells at lowest unit cost for volumes exceeding 500 million units annually. Crown Holdings and Silgan operate continent-scale stamping footprints.
- Extrusion:Material flow forming enables thickness gradients impossible with stamping, reducing shell weight 15-20% for premium spirits and wine applications where sustainability credentials justify equipment investment.
- Machining:Precision thread cutting serves pharmaceutical and small-batch specialty applications where tooling flexibility outweighs speed economics.
- Die Casting:Limited to thick-walled specialty closures requiring complex internal geometries; negligible share in standard ROPP production.
Stamping retains the volume leadership position, with Extrusion gaining share fastest on lightweighting imperatives.
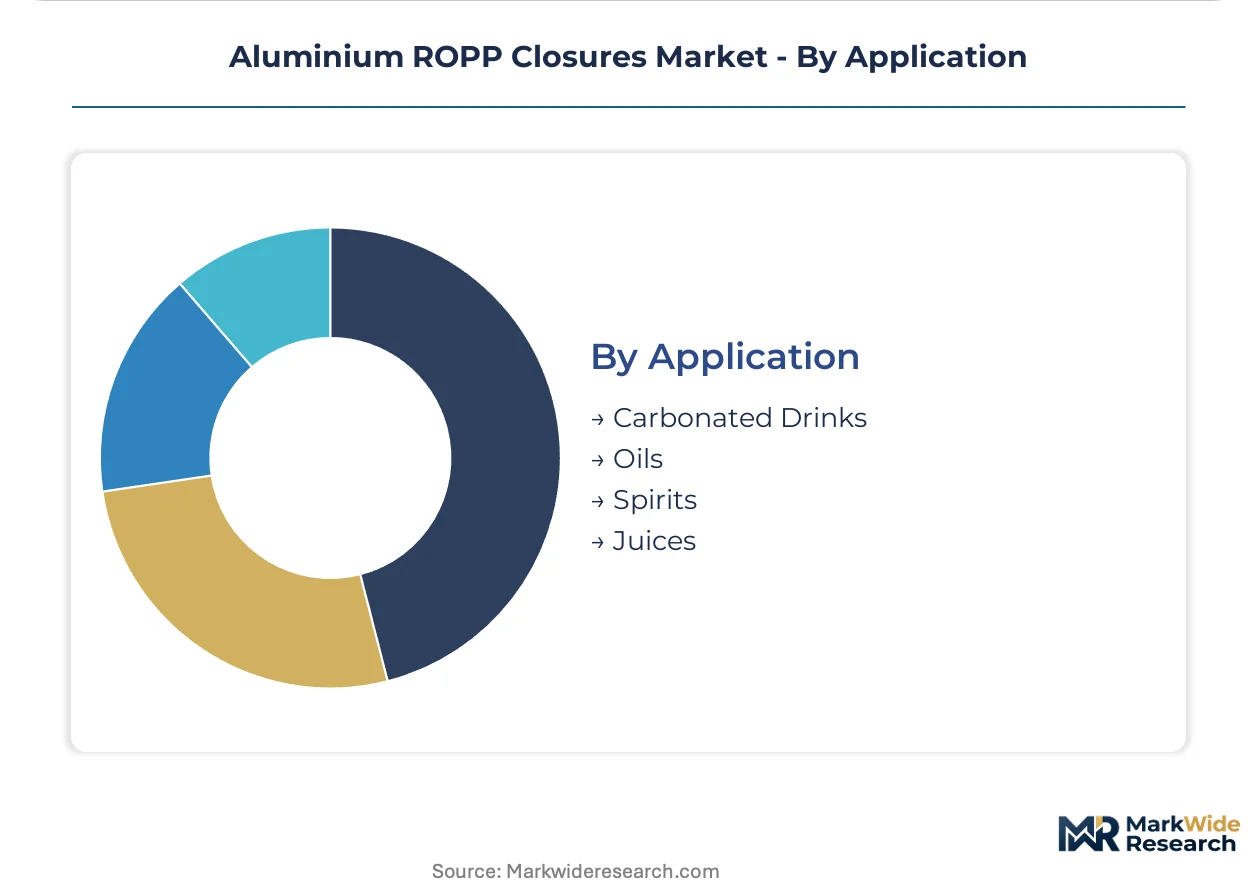
Application:
Geography and customer type intersect sharply here, with spirits and oils concentrating in emerging Asian markets and carbonated drinks dominated by multinational bottler procurement consolidation.
- Carbonated Drinks:Screw Top ROPP variants with optimized thread profiles reduce capping torque variance for high-speed filling operations. North American soft drink and Mexican beer export operations concentrate purchasing authority at three buying groups controlling over half of regional aluminium closure volume.
- Spirits:Premium Scotch, Cognac, and emerging Vietnamese distilleries specify micro-perforated tear-band technology with laser-scored tamper-evident bands. Anti-counterfeit banding technologies from Guala Closures Group command positioning in this segment.
- Oils:Edible oil packaging in India and Southeast Asia is climbing fastest on FSSAI mandates displacing plastic alternatives in formal retail channels.
- Juices:Low-acid still juice segments face polymer closure substitution pressure where reseal frequency is low and polypropylene screw caps with oxygen-scavenging liners compete on cost.
Carbonated Drinks holds the top volume ranking, with Oils expanding most quickly on regulatory displacement of plastic alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Baden-Württemberg region anchors European aluminium closure engineering, hosting precision tooling clusters that supply thread-forming expertise to beverage and pharmaceutical packagers worldwide.
United States
Mexican beer export facilities and carbonated soft drink bottlers in Texas and California drive screw-top ROPP demand for high-speed filling lines. FDA food-contact notifications enforce strict liner compound standards for metal purity. Crown Holdings operates integrated coil-to-closure plants in the Midwest and Southwest, serving consolidated buying groups that control over half of regional aluminium closure procurement.
Germany
Pharmaceutical packagers in Baden-Württemberg and Bavaria absorb premium pricing for ISO 8317-certified child-resistant closures. ECHA REACH Annex XVII restrictions on nickel release and heavy metals compel liner reformulations using calcium carbonate-filled polyolefins. Stuttgart's tooling engineering cluster concentrates specialized knowledge for thin-gauge aluminium thread forming, constraining capacity expansion as technician populations age.
India
FSSAI packaging mandates are accelerating aluminium closure adoption in Maharashtra and Gujarat, displacing plastic alternatives in edible oil and spirits bottling for formal retail channels. BIS certification requirements add compliance layers for domestic suppliers and exporters. Mumbai-Pune industrial corridor hosts stamping operations supplying India's fastest-growing spirits packaging volumes.
Vietnam
Premium local distilleries in Hanoi and Ho Chi Minh City are importing European capping lines and specifying anti-counterfeit banded closures. Security-featured ROPP variants command positioning as Vietnamese spirits producers upgrade packaging for export markets. Northern industrial zones concentrate demand for micro-perforated tear-band technology with laser-scored tamper-evident features.
France
Cognac houses specify micro-perforated tear-band closures to balance security with consumer accessibility for premium spirits exports. France's AGEC law assigns extended producer responsibility obligations to closure manufacturers, favoring aluminium's established recycling infrastructure. Charente-Maritime distilling cluster drives demand for lightweight extrusion-formed shells that align with brand sustainability targets.
Aluminium ROPP Closures Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue security-featured and lightweight variants for premium spirits and sustainability-conscious brands. The market structure concentrates among integrated coil-to-closure operators and high-volume stamping specialists, with differentiation emerging through anti-counterfeit technologies and pharmaceutical certification capabilities. Three strategic archetypes dominate: continent-scale integrated manufacturers, security-technology specialists, and precision pharmaceutical certification players. Competitive moves center on backward integration into aluminium coil supply and geographic expansion into emerging Asian bottling markets.
Within the integrated manufacturing tier, Crown Holdings Inc. and Silgan Holdings Inc. exemplify scale-driven positions spanning multiple continents. Guala Closures Group occupies the security-technology specialist archetype, representing differentiation through anti-counterfeit banding capabilities for premium spirits applications. These three companies anchor the competitive structure, with their respective positions reflecting divergent strategic emphases on volume efficiency, security features, and regulatory compliance depth.
| Leading Market Players |
|---|
| Crown Holdings Inc. |
| Oriental Containers Limited |
| Amcor Limited |
| Federfin Tech S.r.l. |
| Pelliconi & C. S.p.A. |
| Guala Closures Group |
| Silgan Holdings Inc. |
| Ramondin S.A. |
| Closure Systems International |
| Others |
Supply Flow & Price Mechanics
EU REACH Annex XVII compliance on heavy metals and liner compounds gates qualified supply access and premium-tier pricing for aluminium ROPP closures serving pharmaceutical and beverage packagers in Germany and France. Manufacturers lacking EFSA-notified polymer systems or captive coil supply face exclusion from formal procurement channels at multinational bottlers.
Pricing Analysis
LME aluminium price pass-through dominates converter margin dynamics, with non-integrated stampers absorbing volatility that integrated operators hedge through captive coil supply. Three-tier pricing structure across pharmaceutical-certified, beverage-standard, and commodity-economy levels separates ISO 8317-validated child-resistant closures from basic screw-top variants. Cost compression in standard-tier edible oil closures is intensifying because India's FSSAI mandates are accelerating volume shifts from plastic alternatives. Carbonated drink bottlers running high-speed lines exhibit lowest price sensitivity; small edible oil packagers in informal channels show highest.
Supply Chain Analysis
Primary aluminium coil supply rests on smelters in China, Russia, and the Middle East, with European and North American converters drawing from LME-linked traders and captive mining operations. Specialty liner polymers hinge on calcium carbonate-filled polyolefin formulations from German and French chemical producers; thread-forming tooling feeds from Stuttgart and Nagoya engineering clusters. Single-source vulnerability concentrates in approved REACH-compliant polymer suppliers, now consolidated to three dominant specialty chemical producers. Distribution runs through direct-to-contractor procurement at consolidated multinational beverage buying groups, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in aluminium ROPP closures stems from lightweight extrusion technology reducing material intensity 15-20% without seal compromise, enabling premium positioning at sustainability-focused brand owners.
For Market Incumbents: Anchor coil-to-closure integration across multiple continents to defend against LME price volatility and polymer liner supply concentration. Crown Holdings and Silgan demonstrate scale economics through high-volume stamping footprints; Guala Closures Group secures pharmaceutical and spirits positioning through anti-counterfeit banding R&D. Capacity addition in Maharashtra and Gujarat addresses India's FSSAI-driven displacement of plastic alternatives. For New Entrants and Emerging Players: Spirits distributors in Vietnam and premium distilleries in Hanoi represent the most penetrable channel partner type for security-featured ROPP variants with micro-perforated tear-band technology. Target white-space in lightweight extrusion-formed shells for Cognac and Scotch sustainability mandates; pursue ISO 8317 certification partnerships with German testing laboratories to access pharmaceutical premium tiers. For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated stampers lacking captive coil supply or REACH-compliant liner qualification. Long-term viability favors operators with backward integration into primary aluminium and established recycling infrastructure under France's AGEC law and impending EU Packaging and Packaging Waste Regulation revisions. Watch LME price volatility and REACH Annex XVII expansion as inflection triggers for consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminium Coil | Captive smelter or long-term offtake agreements hedge LME volatility for high-volume stampers. |
| REACH-Compliant Liner Compound Qualification | EFSA notification unlocks pharmaceutical and premium beverage procurement at multinational bottlers. |
| Extrusion Technology Deployment | Material flow forming enables 15-20% gauge reduction for sustainability-positioned spirits brands. |
| ISO 8317 Certification Investment | Child-resistant closure validation opens pharmaceutical analgesic and prescription liquid segments. |
| Direct-to-Contractor Procurement Models | Bypassing distributor intermediaries captures margin at consolidated North American and Mexican beer buying groups. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at stamping and extrusion facilities, procurement leads at carbonated drink and spirits bottlers, regulatory affairs specialists navigating REACH and FDA food-contact notifications, and channel partners in Indian edible oil distribution. Secondary validation drew from customs and trade data, SEC 10-K filings of integrated packaging manufacturers, EFSA food-contact substance databases, and BIS certification records. Bottom-up volume modeling triangulated against top-down aluminium coil consumption estimates across beverage, pharmaceutical, and food end-uses.
Segment-weighting across closure type, end user, production technology, and application dimensions shaped volume and value outputs across the projection horizon. Screw Top, Child Resistant, Standard, and Light-Weight variants carried distinct material intensity and certification cost assumptions; Stamping and Extrusion technologies reflected divergent capital intensity and unit economics. CAGRs derived from elasticity-adjusted demand curves incorporating FSSAI mandate implementation timelines and EU extended producer responsibility framework expansion. Primary aluminium price scenarios and liner compound supplier concentration informed sensitivity bounds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH Annex XVII expansion, LME price regime shifts, and polymer closure substitution advances in still water and juice segments. Forecasts reflect documented assumptions on regulatory implementation pacing and brand owner sustainability target adoption. A small set of named triggers—EU Packaging and Packaging Waste Regulation final text, India's FSSAI enforcement intensity, and primary aluminium smelter capacity additions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Saudi Arabia Plastic Caps and Closures Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
South Africa Plastic Caps and Closures Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Flapper Caps Market
Caps and Closures
India Plastic Caps and Closures Market
Caps and Closures
Reverse Cap Bottles Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Low Profile Compact System Closures Market
Caps and Closures
Pharmaceutical Caps and Closures Market