
 Humidity Indicator Plugs Market | 2026-2036
Humidity Indicator Plugs Market Size, Share, and Industry Trends Forecast 2026-2036
Humidity Indicator Plugs Market Foresight
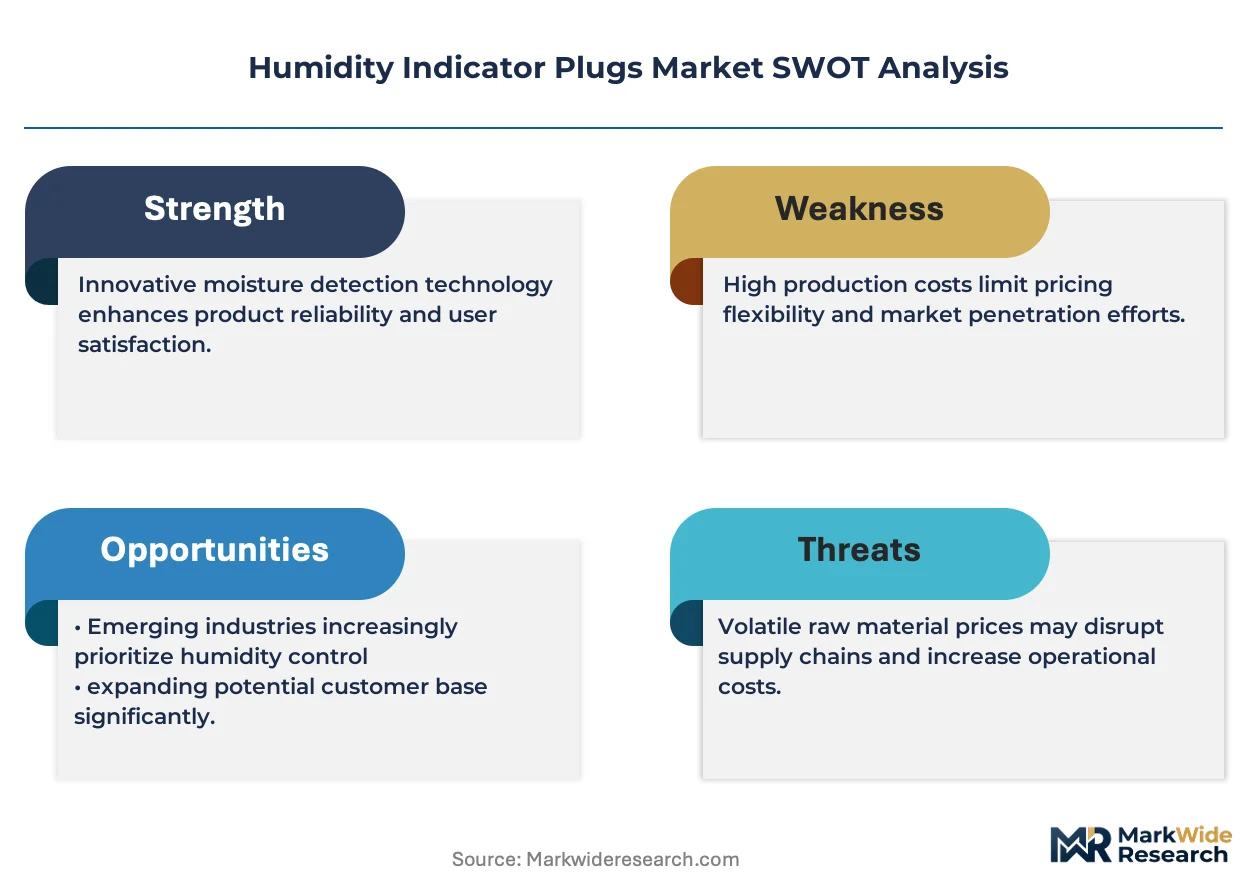
MIL-STD-2073-1E qualification is reorganizing competitive access in the humidity indicator plugs sector, raising barriers for suppliers lacking defense-grade certification. Honeywell International Inc. leverages its aerospace heritage to dominate military and defense logistics channels. AGM Container Controls, Inc. specializes in custom-engineered desiccant systems with integrated humidity monitoring for niche applications. Stream Peak International Pte Ltd anchors Asia-Pacific distribution networks through regional manufacturing partnerships.
Humidity indicator plugs are sealed sensing devices, typically incorporating cobalt chloride or copper chloride indicator media on paper or polymer substrates, designed to provide visual confirmation of moisture intrusion within sealed packaging or environmental enclosures. Their primary purpose is to protect moisture-sensitive goods—pharmaceuticals, semiconductors, archival materials—from degradation by enabling real-time humidity threshold detection without breaching containment. The pharmaceuticals application segment leads current procurement volumes, driven by cold-chain validation requirements and ICH Q1A stability guidelines. Color change indicators sustain the largest installed base due to low cost and operator familiarity, though digital indicators are capturing fastest growth in automated warehouse environments where IoT integration reduces manual inspection labor. Composite material constructions are gaining traction where metal-plastic hybrid designs balance corrosion resistance with electromagnetic compatibility in electronics packaging.
The U.S. FDA enforces container closure integrity standards that directly mandate humidity monitoring for sterile pharmaceutical products, while the EPA regulates cobalt-based indicator formulations under TSCA chemical reporting requirements. In Europe, the EMA's Annex 1 revision on sterile manufacturing and REACH chemical restrictions are pushing manufacturers toward copper-based or halogen-free indicator chemistries. Stakeholders must monitor evolving pharmacopeial standards and material substitution timelines to align R&D pipelines with compliance-driven specification shifts.
Market Dynamics
MIL-STD-2073-1E qualification requirements are restructuring supplier access in humidity indicator plugs, creating a bifurcation between defense-certified manufacturers and commercial-only competitors as pharmaceutical and electronics buyers increasingly specify military-grade reliability standards.
Growth Catalysts
- ICH Q1A Stability Guidelines:Pharmaceutical manufacturers across Germany, Switzerland, and the United States mandate humidity monitoring for drug stability validation, expanding plug procurement for cold-chain packaging.
- Copper Chloride Chemistry Substitution:REACH restrictions on cobalt compounds are accelerating copper-based indicator adoption, opening retrofit demand across existing pharmaceutical packaging lines.
- Electronics Cluster Concentration:Taiwan's semiconductor packaging corridor and Bavaria's precision manufacturing belt drive specialized humidity monitoring procurement for moisture-sensitive component shipments.
Market Restraints
- Raw Material Concentration:Specialty indicator paper substrates depend on Austrian and Japanese pulp suppliers, creating input vulnerability for European and Asian plug manufacturers.
- Defense Certification Barriers:MIL-STD-2073-1E testing timelines and documentation requirements exclude smaller suppliers from military logistics contracts.
- Digital Substitution Pressure:Wireless humidity loggers with continuous data transmission threaten color-change plug volumes in high-value pharmaceutical distribution.
Strategic Opportunities
- Indian Pharmaceutical Export Growth:CDSCO's alignment with ICH standards and expanding generic drug cold-chain infrastructure create untapped demand for validated humidity indicators.
- Halogen-Free Chemistry Development:ECHA's expanding SVHC candidate list positions bromine-free indicator formulations for premium positioning in EU medical device packaging.
- IoT Integration Convergence:Combining color-change visual indicators with NFC-enabled digital readouts addresses both regulatory audit trails and warehouse automation requirements.
Industry Challenges
- Cross-Contamination Control:Pharmaceutical manufacturers require dedicated production lines for cobalt-free indicators, demanding capital allocation for segregated manufacturing capacity.
- Pharmacopeial Harmonization Delays:Divergent USP, EP, and JP monograph requirements for humidity indicator performance create multi-jurisdiction testing burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humidity Indicator Plugs Market |
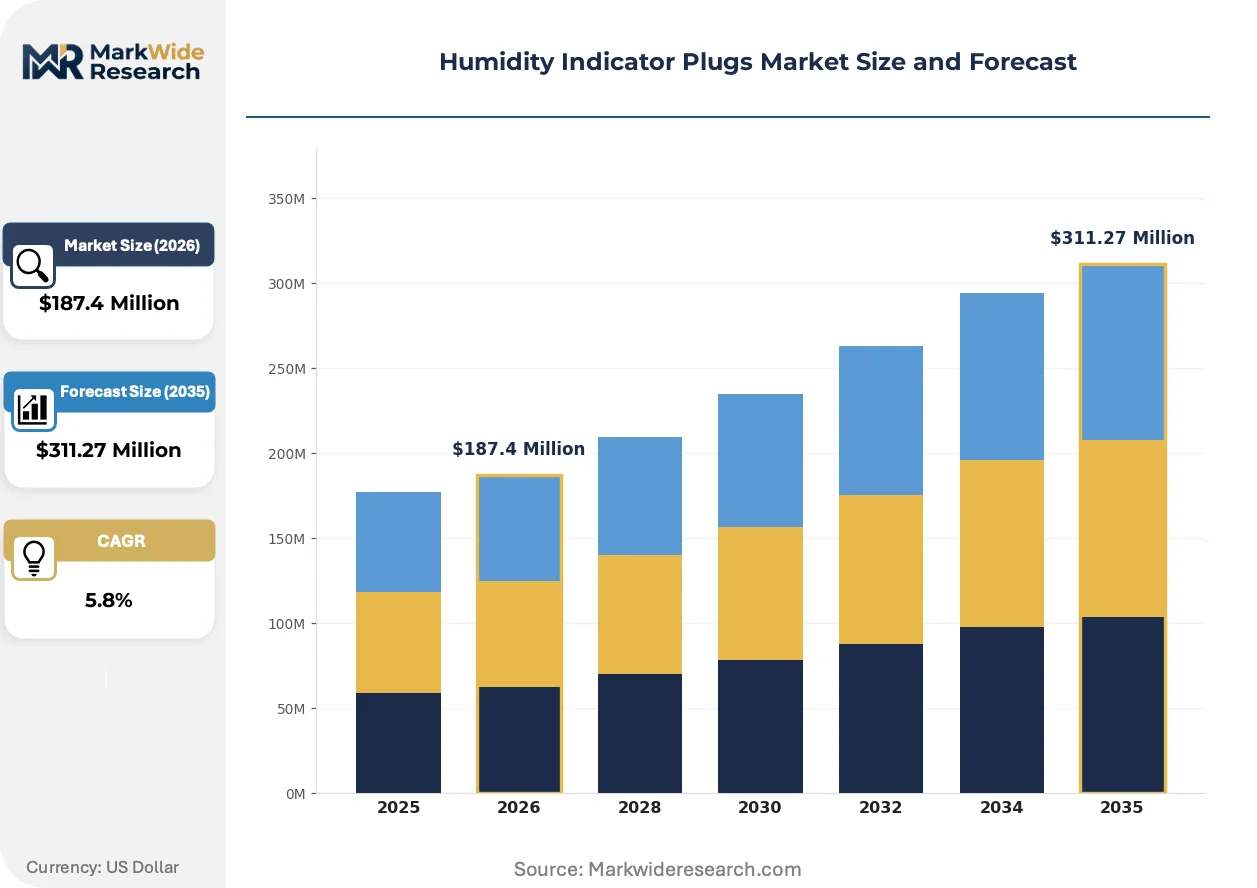
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Plugs, Disposable Plugs, Digital Indicators, Color Change Indicators Application: Pharmaceuticals, Food Packaging, Electronics, Archives End User: Hospitals, Pharmaceutical Companies, Retailers, Research Laboratories Material: Plastic, Paper, Metal, Composite |
| Companies Covered | Desiccare, Inc., Honeywell International Inc., 3M Company, Parker Hannifin Corporation, Clariant AG, AGM Container Controls, Inc., Stream Peak International Pte Ltd, Edco Supply Corporation, IMPAK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humidity Indicator Plugs Market Shifts & Advancements
Digital sensing technologies are penetrating humidity indicator plugs, redefining value capture from disposable consumables toward data-enabled monitoring platforms. This shift compresses traditional color-indicator volumes while opening subscription and analytics revenue streams.
Polymer substrate indicators with reversible color-change chemistry are displacing paper-based cobalt chloride systems in reusable pharmaceutical containers. German packaging engineers specify these materials for returnable active pharmaceutical ingredient totes. The technology is displacing single-use plugs in closed-loop logistics, compressing per-shipment consumable revenue while locking in multi-year service contracts.
REACH Annex XIV authorization requirements for cobalt dichloride are forcing chemistry transitions across EU-manufactured indicators. Copper(II) chloride and iron(III) chloride formulations gain traction despite narrower humidity detection ranges. Swissmedic's pharmaceutical packaging guidance now explicitly recommends cobalt-free alternatives, pressuring suppliers to maintain dual chemistry portfolios.
Pharmaceutical distributors are consolidating humidity monitoring procurement under integrated packaging service agreements rather than discrete plug purchases. Third-party logistics providers in the Netherlands and Belgium bundle indicator supply with temperature-controlled container leasing. This concentration is visible most acutely in Benelux cold-chain hubs where four distributors control majority pharmaceutical warehousing capacity.
Humidity Indicator Plugs Market Segmentation
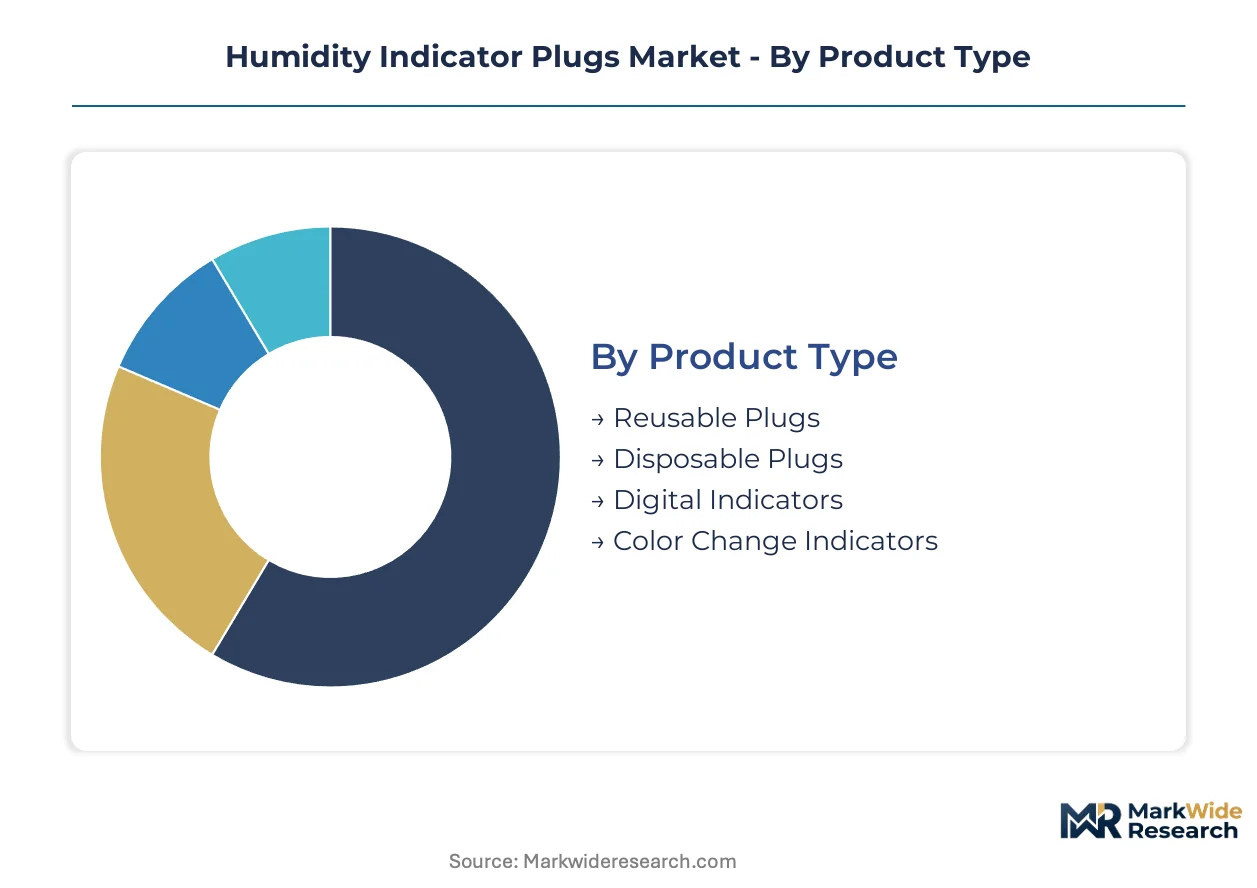
Humidity indicator plugs serve divergent compliance regimes across pharmaceuticals, electronics, and defense logistics. Segment-specific chemistry choices and certification requirements create distinct margin architectures that reshape supplier positioning.
Product Type:
Premium pricing concentrates in digital and reusable formats where validation documentation and IoT integration justify higher unit economics.
- Color Change Indicators:Cobalt chloride or copper chloride impregnated substrates deliver visual humidity threshold detection through reversible color shift. Pharmaceutical cold-chain validation in Germany and Switzerland sustains volume leadership despite regulatory pressure on cobalt formulations.
- Digital Indicators:Semiconductor-based sensors with data logging capability enable continuous monitoring and automated warehouse integration. Demand concentrates in automated pharmaceutical distribution centers where FDA 21 CFR Part 11 compliance requires electronic records.
- Reusable Plugs:Polymer substrate designs with reversible chemistry support closed-loop pharmaceutical container systems. Swiss packaging engineers specify these for active pharmaceutical ingredient totes.
- Disposable Plugs:Single-use paper-based indicators dominate high-volume generic drug shipments from Indian export facilities.
The dominant share belongs to Color Change Indicators, while Digital Indicators are expanding most quickly.
Application:
Regulatory stringency varies sharply across end-uses, with pharmaceutical compliance costs creating the steepest margin premiums.
- Pharmaceuticals:ICH Q1A stability guidelines mandate humidity monitoring for drug shipment validation. FDA container closure integrity requirements and EMA Annex 1 sterile manufacturing standards drive specification intensity.
- Electronics:Moisture-sensitive semiconductor components require humidity control during Taiwan-to-Bavaria shipping corridors. MIL-STD-2073-1E certification opens defense electronics procurement channels.
- Food Packaging:Premium chocolate and dried botanical products use indicators for quality assurance. Swiss and Belgian confectionery exporters specify cobalt-free alternatives.
- Archives:Museum and library conservation applications demand ultra-stable humidity ranges. National archives in France and Japan maintain specialized procurement.
Pharmaceuticals commands the dominant revenue pool, though Electronics is gaining share fastest.
End User:
Procurement sophistication separates institutional buyers from commercial distributors, with direct pharmaceutical manufacturer contracts offering superior margin stability.
- Pharmaceutical Companies:Direct manufacturing integration requires validated indicator systems with batch documentation. Roche, Novartis, and Sanofi facilities specify dual-chemistry portfolios to manage REACH transition risk.
- Hospitals:Pharmacy compounding and sterile preparation areas use plugs for environmental monitoring. US hospital networks consolidate purchasing through group purchasing organizations.
- Research Laboratories:Academic and contract research organizations prioritize low-cost disposable formats. NIH-funded facilities require specific documentation standards.
- Retailers:E-commerce pharmaceutical distributors bundle indicators with temperature-controlled packaging. Dutch and Belgian logistics providers lead service integration.
Pharmaceutical Companies hold the dominant procurement volume, while Hospitals are climbing the fastest.
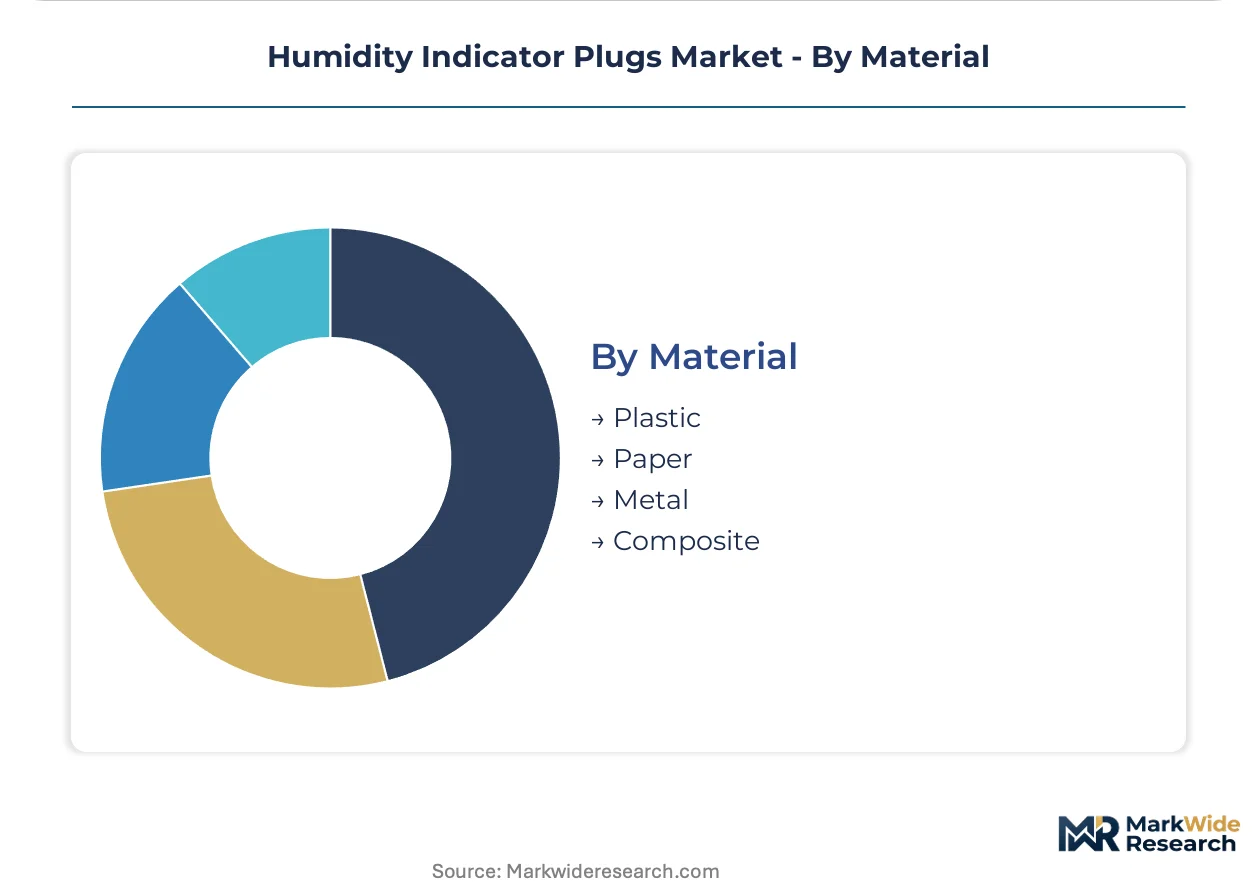
Material:
Substrate selection determines chemical compatibility, electromagnetic properties, and reuse economics across application environments.
- Plastic:Injection-molded polymer housings with integrated viewing windows support reusable pharmaceutical container systems. German engineers favor polyphenylene sulfide for chemical resistance.
- Paper:Indicator-impregnated specialty substrates from Austrian and Japanese pulp suppliers dominate disposable applications. REACH cobalt restrictions are forcing chemistry transitions.
- Metal:Aluminum and brass constructions serve military logistics where MIL-STD-2073-1E durability requirements exclude polymer alternatives.
- Composite:Metal-plastic hybrid designs balance corrosion resistance with electromagnetic compatibility in electronics packaging. Taiwan semiconductor shippers specify these for Faraday cage compatibility.
Paper substrates retain the dominant installed base, though Composite materials are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ICH Q1A stability guidelines and REACH cobalt restrictions are redrawing procurement maps across pharmaceutical and electronics manufacturing corridors. National regulators in Germany, Switzerland, and the United States have tightened humidity monitoring mandates for cold-chain shipments.
United States
FDA container closure integrity standards drive humidity indicator adoption for sterile pharmaceutical distribution. The EPA regulates cobalt-based formulations under TSCA chemical reporting, accelerating copper chloride substitution. New Jersey and Massachusetts pharmaceutical clusters specify dual-chemistry portfolios to manage compliance transition risk.
Germany
Bavaria's precision manufacturing belt anchors European demand for MIL-STD-2073-1E certified plugs in defense electronics. The country's national chemical regulator enforces REACH Annex XIV cobalt restrictions, forcing indicator chemistry transitions. Stuttgart and Munich packaging engineers specify polymer substrate reusable plugs for closed-loop pharmaceutical logistics.
Switzerland
Swissmedic pharmaceutical packaging guidance explicitly recommends cobalt-free alternatives, pressuring suppliers to maintain dual chemistry inventories. Basel's pharmaceutical manufacturing corridor drives specialized procurement for active pharmaceutical ingredient totes. The country's precision engineering heritage supports premium pricing for validated indicator systems.
India
CDSCO alignment with ICH standards and expanding generic drug cold-chain infrastructure create demand acceleration for validated humidity indicators. Maharashtra and Gujarat pharmaceutical export facilities drive disposable plug volumes for high-volume shipments. The country's national pharmaceutical regulator mandates stability validation for temperature-sensitive drug exports.
Taiwan
The semiconductor packaging corridor drives specialized humidity monitoring procurement for moisture-sensitive component shipments. National standards bodies enforce electromagnetic compatibility requirements for electronics packaging. Hsinchu Science Park fabs specify composite material constructions balancing corrosion resistance with Faraday cage compatibility.
Humidity Indicator Plugs Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with defense-grade MIL-STD-2073-1E qualification separating premium-positioned suppliers from commercial-only competitors. The market exhibits moderate concentration around aerospace heritage conglomerates and specialized desiccant system engineers. Three archetypes dominate: defense-certified manufacturers with military logistics access, custom-engineered solution specialists serving niche pharmaceutical applications, and Asia-Pacific distribution anchors leveraging regional manufacturing partnerships. Competitive moves center on chemistry portfolio diversification to manage REACH cobalt transitions and strategic partnerships with third-party logistics providers bundling indicators with temperature-controlled container leasing.
Within the defense-certified tier, Honeywell International Inc. exemplifies aerospace heritage leverage into military logistics channels. AGM Container Controls, Inc. occupies a specialist position in custom-engineered desiccant systems with integrated humidity monitoring. Stream Peak International Pte Ltd anchors Asia-Pacific distribution networks through regional manufacturing partnerships, representing the geography-focused archetype.
| Leading Market Players |
|---|
| Desiccare, Inc. |
| Honeywell International Inc. |
| 3M Company |
| Parker Hannifin Corporation |
| Clariant AG |
| AGM Container Controls, Inc. |
| Stream Peak International Pte Ltd |
| Edco Supply Corporation |
| IMPAK Corporation |
| Others |
Supply & Pricing Matrix
Copper chloride chemistry substitution simultaneously redraws supply geography toward Austrian and Japanese pulp suppliers while compressing margin structures for cobalt-dependent manufacturers facing REACH compliance deadlines. Pharmaceutical buyers in Germany and Switzerland now specify dual-chemistry portfolios, forcing suppliers to absorb inventory carrying costs for parallel production lines.
Pricing Analysis
Certification level creates the primary spread between defense-grade MIL-STD-2073-1E qualified plugs and commercial-only alternatives. Pricing stratifies across premium certified, standard validated, and economy disposable tiers, with FDA-grade documentation adding substantial service premiums. Cost compression in the economy tier intensifies because Indian generic drug exporters consolidate procurement through third-party logistics bundling. Research laboratories exhibit highest price sensitivity due to grant-funded budget constraints, while Swiss pharmaceutical manufacturers show lowest sensitivity given validation documentation requirements.
Supply Chain Analysis
Inventory cycles for specialty indicator paper substrates have extended because Austrian and Japanese pulp suppliers operate on quarterly allocation schedules. Manufacturing concentrates in Germany, the United States, and Taiwan, with assembly drawing from Chinese injection-molded polymer housings. Raw material dependencies center on cobalt and copper chloride indicator chemistries, specialty paper substrates, and polyphenylene sulfide resins. Single-source vulnerability in Japanese pulp supply creates exposure for European plug manufacturers. Distribution runs through pharmaceutical third-party logistics providers in the Netherlands and Belgium who bundle indicators with temperature-controlled container leasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in humidity indicator plugs stems from ICH Q1A stability guideline adoption across Indian pharmaceutical export corridors. Penetration remains shallow in automated warehouse digital integration, leaving substantial runway for IoT-converged product development.
For Market Incumbents: Consolidate chemistry portfolio diversification to manage REACH cobalt transition risk while capturing copper chloride retrofit demand. Deepen backward integration into indicator paper substrate supply through dedicated partnerships with Austrian pulp suppliers. Lock in multi-year service contracts with Swiss and German pharmaceutical manufacturers for reusable polymer substrate systems. For New Entrants and Emerging Players: Anchor in India's CDSCO-aligned pharmaceutical export infrastructure where validated disposable plug demand outpaces domestic supplier capacity. Target Maharashtra and Gujarat generic drug facilities with cobalt-free indicator offerings positioned for EU shipment compliance. Pursue white-label manufacturing partnerships with Dutch and Belgian third-party logistics providers bundling indicators with cold-chain container leasing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed desiccant system specialists holding integrated humidity monitoring capabilities. Long-term viability hinges on chemistry transition execution and digital sensing convergence over the coming decade. Monitor ECHA SVHC candidate list expansion as the inflection signal for halogen-free formulation premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Copper Chloride Chemistry Transition | REACH Annex XIV compliance opens retrofit revenue across existing EU pharmaceutical packaging lines. |
| NFC-Enabled IoT Integration | FDA 21 CFR Part 11 audit trail requirements drive automated warehouse adoption in German distribution centers. |
| Backward Integration into Substrate Supply | Captive sourcing from Austrian pulp suppliers mitigates single-source vulnerability for European manufacturers. |
| Third-Party Logistics Partnership | Benelux cold-chain bundling agreements concentrate procurement under integrated service contracts. |
| Dual-Chemistry Portfolio Maintenance | Swissmedic cobalt-free recommendations force inventory diversification for Basel pharmaceutical corridor access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA regulatory submissions, and REACH authorization databases. Interviews with pharmaceutical packaging engineers, desiccant system procurement leads, cold-chain logistics coordinators, and regulatory affairs directors informed demand-side validation. Customs trade data, SEC 10-K supply chain disclosures, and pharmacopeial monograph databases provided secondary triangulation. Bottom-up unit economics and top-down sector sizing converged through iterative cross-checking.
Segmentation dimensions modeled include product type hierarchy, application vertical, end-user procurement sophistication, and substrate material chemistry across the projection horizon. CAGRs derive from regression analysis against pharmaceutical shipment volumes, semiconductor packaging activity, and defense logistics procurement patterns. Forecast inputs incorporate ICH guideline adoption trajectories, REACH chemical restriction timelines, and cold-chain infrastructure investment flows without year-specific anchoring.
Material uncertainties — pharmacopeial harmonization delays, cobalt substitution cost trajectories, and digital sensing displacement velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and chemistry transition adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
France Plastic Caps and Closures Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
Reverse Cap Bottles Market
Caps and Closures
Smooth Hinge Caps and Closure Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Snap-On Closures Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Global Aluminum Caps and Closures Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Drum Plugs Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Flapper Caps Market