
 North America Metal Caps and Closures Market | 2026-2036
North America Metal Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
North America Metal Caps and Closures Market Insights
Single-source aluminum supply agreements is decoupling from long-term beverage contracts as converters seek tariff resilience. Crown Holdings, Inc. anchors North American beverage can closure production through integrated metal rolling and forming assets. Silgan Closures competes on pharmaceutical and personal care specialization, leveraging multi-site FDA-registered manufacturing. Closure Systems International Inc dominates carbonated soft drink twist-off segments through captive steel-tinplate sourcing relationships.
Metal caps and closures are threaded or crimped sealing devices fabricated from aluminum, tinplate, or steel, typically specifying 28mm to 43mm diameters and 0.18mm to 0.30mm wall thicknesses, designed to preserve contents against oxidation, contamination, and leakage across liquid and semi-solid packaged goods. Screw caps lead volume in beverage applications where aluminum lightweighting yields material cost advantages, while tamper-evident closure designs command premium positioning in pharmaceutical and personal care segments where FDA compliance and consumer safety liability drive specification rigidity. Child-resistant designs represent the fastest-growing closure design category as cannabis legalization expands across US states and Canadian provinces, forcing format adaptation from legacy pharmaceutical standards.
FDA food-contact notification requirements govern aluminum and steel alloy compositions for beverage and food packaging applications, while EPA National Emission Standards for Hazardous Air Pollutants regulate metal finishing operations at closure manufacturing facilities, elevating capital requirements for domestic producers. US OSHA workplace exposure limits and Canadian WHMIS chemical classification standards further shape plant location and automation investment decisions across the region. Stakeholders must monitor state-level extended producer responsibility legislation and deposit-return system expansions, as these programs directly alter closure material specifications and recycling infrastructure economics without federal harmonization.
Market Dynamics
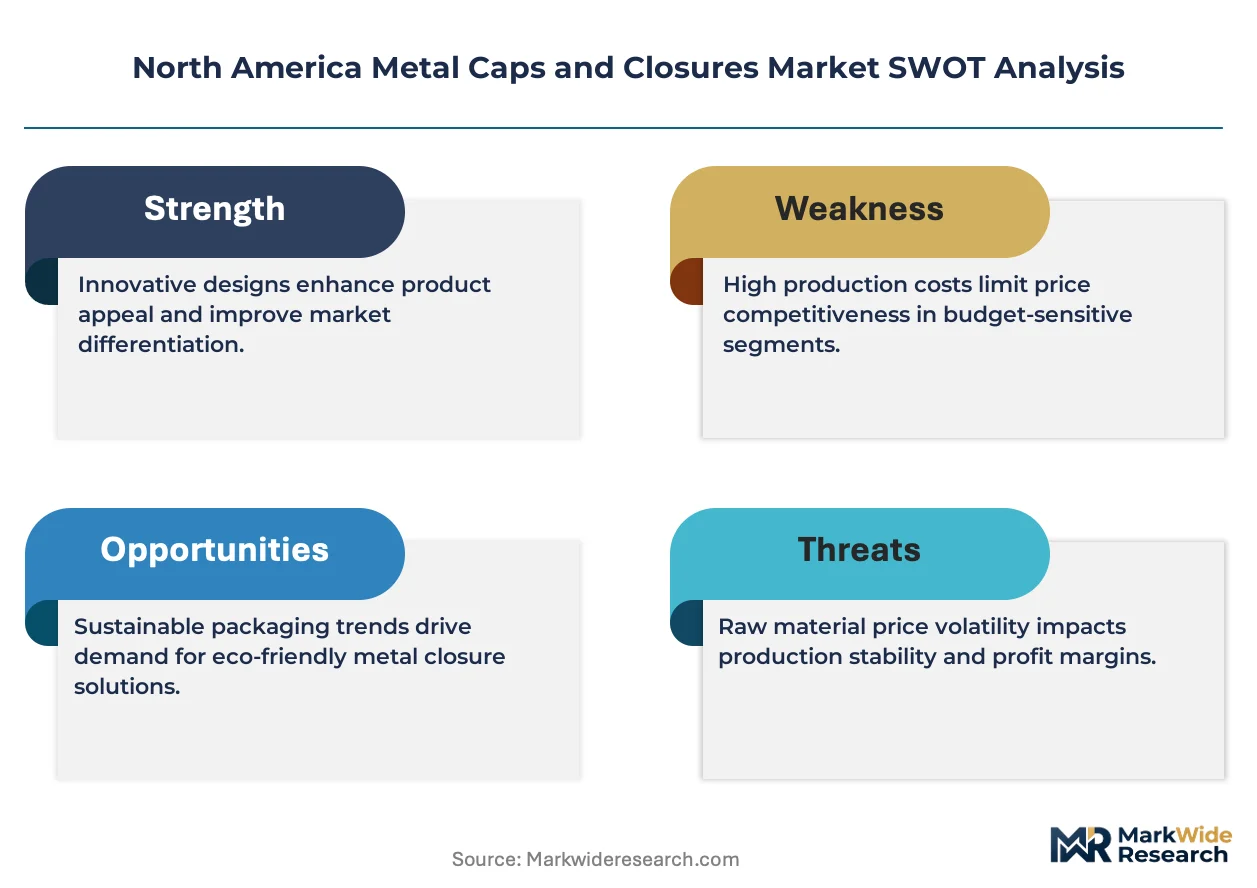
Aluminum lightweighting mandates from beverage bottlers are forcing closure converters to reconfigure supply agreements and metal sourcing strategies across the US Great Lakes manufacturing corridor. This pressure is decoupling single-source aluminum contracts from long-term beverage partnerships as tariff resilience becomes paramount.
Growth Catalysts
- EPA metal finishing standards:Tightening emission controls at closure manufacturing facilities are accelerating capital investment in automated forming and coating lines, elevating barriers for smaller competitors.
- Cannabis legalization:State-level expansion across US markets and Canadian provinces is generating demand for child-resistant closure designs adapted from pharmaceutical standards.
- Deposit-return systems:Extended producer responsibility legislation in multiple US states is driving specification changes toward aluminum alloys with higher post-consumer recycled content.
Market Restraints
- Steel-tinplate supply concentration:Captive sourcing relationships between major carbonated soft drink bottlers and integrated steel producers limit converter flexibility in raw material procurement.
- FDA food-contact notification timelines:Alloy composition approval processes for new aluminum grades create 18-24 month lag between material development and commercial deployment.
- Plastic closure substitution:Polypropylene screw caps in non-carbonated beverage segments erode addressable market for metal alternatives in cost-sensitive applications.
Strategic Opportunities
- Underpenetrated pharmaceutical specialty:Multi-site FDA-registered manufacturing infrastructure in the US Midwest supports expansion into high-margin oncology and biologic drug packaging.
- Smart closure convergence:Integration of NFC-enabled authentication tags with aluminum tamper-evident designs opens premium positioning against counterfeiting in spirits and cannabis.
- Canadian provincial EPR mandates:British Columbia and Ontario deposit-return expansions create first-mover advantage for converters with verified closed-loop aluminum recovery systems.
Industry Challenges
- Tooling and die-making talent scarcity:Precision metal forming expertise concentrated among retiring workforce cohorts in Ohio and Michigan threatens production continuity.
- Legacy coating line integration:Water-based epoxy phenolic interior coatings required for acidic beverage compatibility demand capital-intensive furnace modifications incompatible with 1980s-era plant footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Metal Caps and Closures Market |
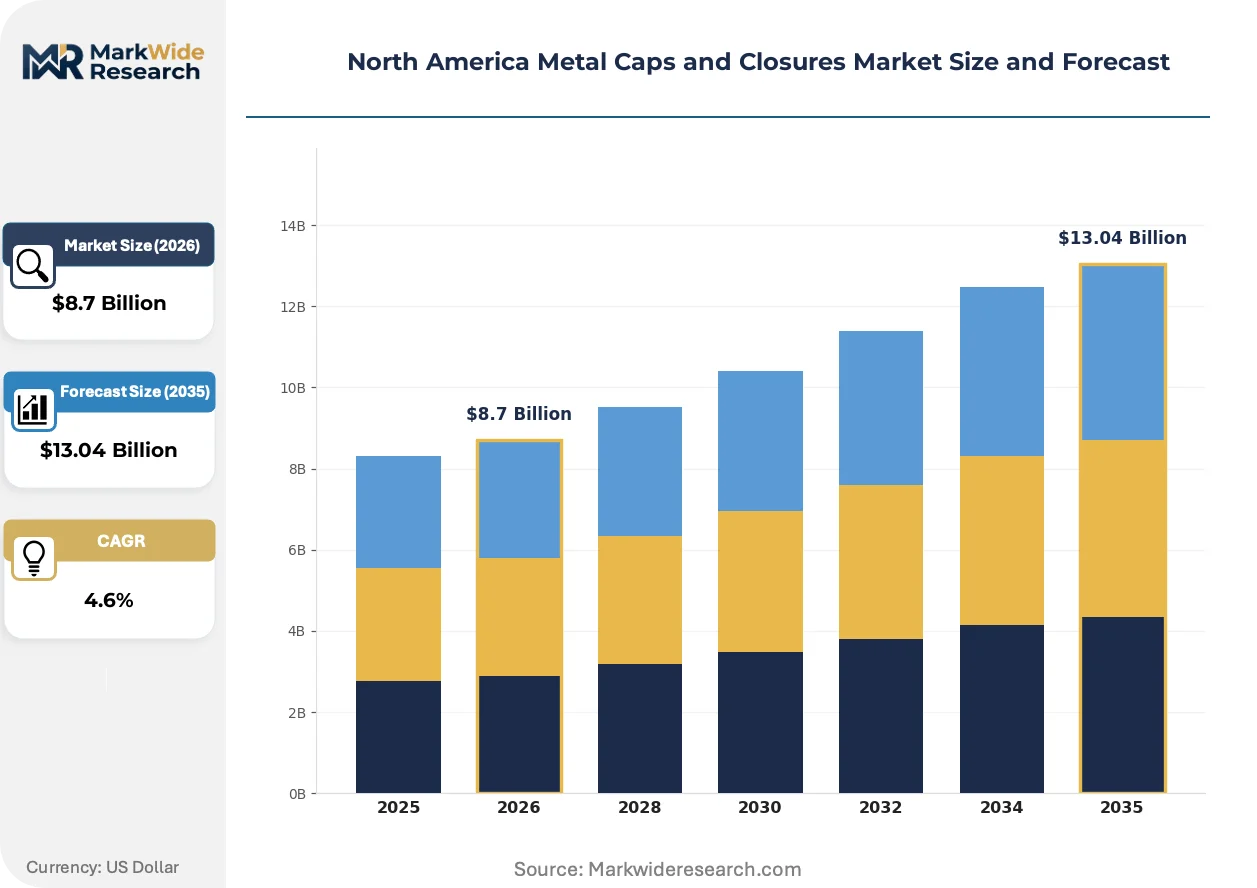
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crown Caps, Screw Caps, Corks, Twist Off Caps End User: Beverage Industry, Food Packaging, Pharmaceuticals, Personal Care Material: Aluminum, Tinplate, Steel, Composite Closure Design: Standard, Child-Resistant, Tamper-Evident, Custom |
| Companies Covered | Crown Holdings, Inc., O.Berk Company, Closure Systems International Inc, Silgan Closures, Alameda Packaging LLC, Guala Closures SpA, Pelliconi & C. SpA, SKS Bottle & Packaging Inc., Amcor PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Metal Caps and Closures Market Trends and Innovations
Threaded aluminum closure designs are converging with digital authentication and lightweighting technologies, compressing traditional specification cycles and elevating material science capabilities among converters.
Digital printing is integrating variable-data decoration directly onto aluminum closure shells, eliminating separate label application steps. Premium spirits and craft beverage brands across California and Texas are adopting this capability for limited-release versioning and anti-counterfeiting serialization. The technology is integrating brand protection with supply chain traceability, collapsing the distinction between closure manufacturer and packaging solutions provider.
FDA food-contact substance notification requirements for novel aluminum alloys are tightening compositional disclosure standards for elements migrating into acidic beverages. Manufacturers must now submit comprehensive toxicological data packages before commercializing modified alloy grades. Carbonated soft drink and ready-to-drink cocktail segments in the US Southeast are experiencing the longest approval delays, forcing reliance on legacy alloy specifications.
Buyer concentration among mega-brewers and multinational beverage corporations is compressing contract renewal cycles from five-year to two-year terms. Direct procurement teams at bottling facilities in Mexico and the US Southwest are negotiating aluminum index-linked pricing clauses that transfer commodity volatility risk upstream to closure converters. This pattern is most visible in aluminum screw cap categories serving sparkling water and hard seltzer portfolios.
North America Metal Caps and Closures Market Segmentation
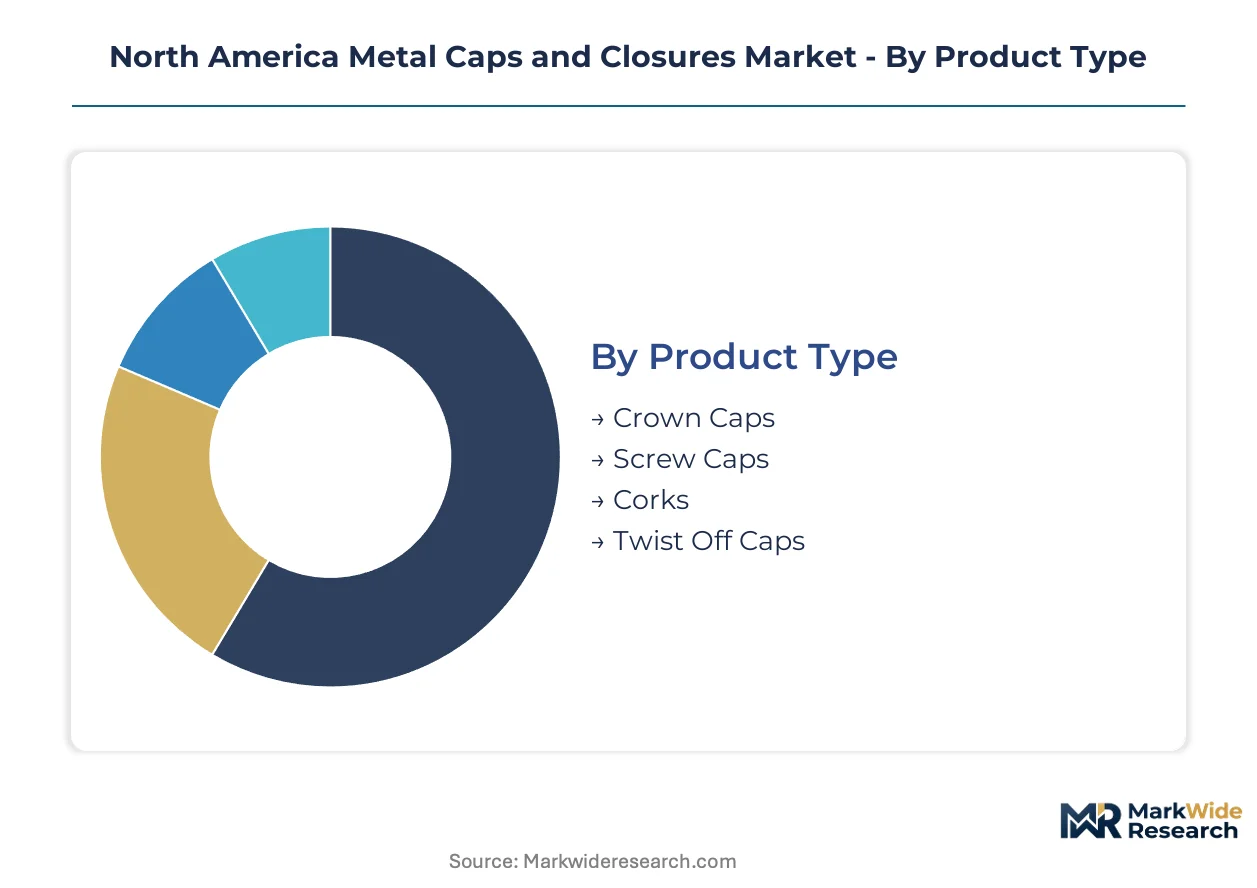
Metal caps and closures demand fragments across incompatible specification regimes. Beverage lightweighting, pharmaceutical safety mandates, and food-contact compliance each impose distinct material and design requirements that resist standardization.
Product Type:
Upgrade cycles accelerate where aluminum substitution displaces legacy steel formats, shortening replacement timelines from equipment depreciation schedules to brand-led format refreshes.
- Screw Caps:Threaded aluminum designs specify 28mm to 43mm diameters with rolled-on pilfer-proof bands. Demand clusters in Mexican sparkling water and US hard seltzer bottling lines where lightweighting targets exceed 15% material reduction versus steel predecessors.
- Twist Off Caps:Lug-style aluminum closures enable single-twist removal without tools. Carbonated soft drink bottlers across the US Southeast specify these for PET bottle compatibility, though steel-tinplate variants retain share in returnable glass systems.
- Crown Caps:Crimped steel shells with polyethylene liners dominate craft beer and legacy carbonated beverage segments. Ohio and Michigan canmaking corridors sustain regional supply concentration.
- Corks:Aluminum-capped natural and synthetic cork hybrids serve premium spirits and wine segments. California and Texas distilleries drive specification for tamper-evident metallized finishes.
Volume placements concentrate in Screw Caps; the faster expansion belongs to Twist Off Caps.
End User:
Customer procurement sophistication varies sharply—beverage giants negotiate index-linked aluminum pricing while pharmaceutical buyers prioritize FDA registration breadth over unit cost.
- Beverage Industry:Mega-brewers and multinational bottlers compress contract cycles to 24 months. Mexican aluminum screw cap adoption accelerates under cross-border tariff exposure.
- Pharmaceuticals:Multi-site FDA-registered manufacturing requirements elevate supplier qualification barriers. Oncology and biologic drug packaging commands premium positioning.
- Food Packaging:Acidic sauce and condiment applications demand epoxy phenolic interior coatings compatible with FDA food-contact substance notifications.
- Personal Care:Cosmetic and fragrance brands specify metallized decorative finishes with crimped or threaded aluminum shells.
Revenue concentrates in Beverage Industry; margins expand most rapidly in Pharmaceuticals.
Material:
Raw material sourcing strategies decouple from long-term contracts as tariff resilience reshapes procurement priorities.
- Aluminum:3000-series and 5000-series alloys dominate beverage applications. Deposit-return system expansions in US states and Canadian provinces drive post-consumer recycled content specifications.
- Tinplate:Captive steel mill relationships constrain converter flexibility. Carbonated soft drink twist-off segments retain steel-tinplate for magnetic separation in recycling streams.
- Steel:Chromium-coated and tin-free steel variants serve cost-sensitive food packaging. EPA metal finishing standards elevate capital requirements for domestic coating operations.
- Composite:Aluminum-plastic hybrid laminates enable tamper-evident functionality with reduced metal mass. Limited penetration outside pharmaceutical specialty segments.
Supply volumes favor Aluminum; specification velocity runs highest for recycled-content alloys.
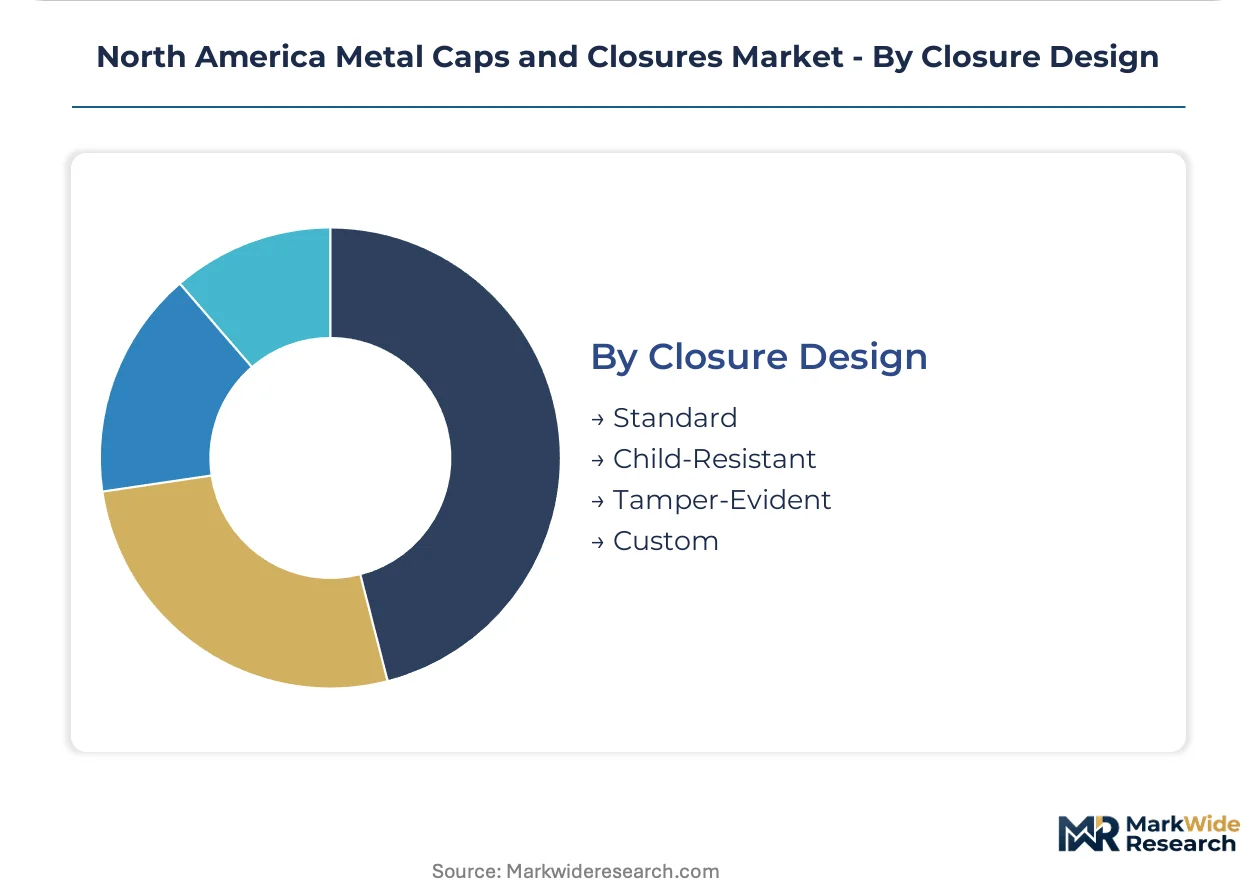
Closure Design:
Regulatory mandates and liability exposure force design standardization in safety-critical categories while premium segments pursue differentiation.
- Tamper-Evident:Breakaway bands and induction-sealed liners satisfy FDA pharmaceutical packaging requirements. Spirits and cannabis applications adopt NFC-enabled authentication integration.
- Child-Resistant:Push-and-turn mechanisms adapted from pharmaceutical standards serve US state and Canadian provincial cannabis legalization. Fastest-growing design category by volume.
- Standard:Basic threaded or crimped formats without secondary safety features. Commodity positioning in mass-market beverage and food segments.
- Custom:Variable-data digital printing and proprietary embossing serve limited-release craft beverage and premium cosmetic positioning.
Unit economics favor Standard designs; regulatory tailwinds accelerate Child-Resistant adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting capacity along the Ohio River Valley anchors North American metal closure supply, with integrated rolling mills feeding forming operations across the Great Lakes manufacturing corridor.
United States
Hard seltzer and sparkling water bottlers in Texas and California drive aluminum screw cap specifications exceeding 15% material reduction targets. FDA food-contact substance notifications govern alloy compositions for acidic beverage compatibility. The Ohio-Michigan canmaking corridor sustains regional production concentration through legacy tool-and-die expertise and captive metal rolling assets.
Canada
British Columbia and Ontario deposit-return system expansions mandate post-consumer recycled aluminum content in beverage closures. Health Canada packaging regulations align with FDA standards while provincial EPR legislation accelerates closed-loop recovery infrastructure. Toronto-area converters serve US cross-border bottlers seeking tariff-advantaged supply alternatives.
Mexico
Mexican beverage bottlers accelerate aluminum screw cap adoption under lightweighting pressures and cross-border logistics optimization. USMCA trade provisions shape raw material sourcing strategies for Monterrey and Mexico City metro production facilities. Baja California and Nuevo León host forming operations supplying US Southwest bottling lines.
North America Metal Caps and Closures Market Competitive Landscape
Capacity expansion dominates the current landscape as converters reconfigure metal sourcing strategies around tariff resilience and lightweighting mandates. The vendor base separates into integrated metal rolling specialists, multi-site FDA-registered pharmaceutical fabricators, and regional beverage-focused formers. Three archetypes define competitive positioning: captive aluminum supply chain operators, pharmaceutical compliance specialists, and carbonated soft drink twist-off segment suppliers. M&A activity and strategic aluminum supply agreements represent the dominant competitive moves reshaping procurement relationships.
Among integrated metal packaging operators, Crown Holdings, Inc. and Amcor PLC occupy positions defined by captive aluminum rolling and forming assets. Silgan Closures exemplifies the pharmaceutical and personal care specialization archetype through multi-site FDA-registered manufacturing infrastructure. Closure Systems International Inc represents carbonated soft drink segment concentration through steel-tinplate sourcing relationships with major bottlers.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| O.Berk Company |
| Closure Systems International Inc |
| Silgan Closures |
| Alameda Packaging LLC |
| Guala Closures SpA |
| Pelliconi & C. SpA |
| SKS Bottle & Packaging Inc. |
| Amcor PLC |
| Others |
Pricing and Supply Chain Analysis
Aluminum-screw-cap versus steel-tinplate divergence splits the market into lightweighting-premium and commodity-legacy tiers, with the former commanding aluminum-index-linked contracts and the latter locked into captive steel-mill arrangements that constrain converter flexibility across the Great Lakes corridor.
Pricing Analysis
Warranty and technical-service bundling separates pharmaceutical-grade closure suppliers from commodity beverage converters. Three-tier pricing structure across premium, standard, and economy levels reflects FDA registration breadth, volume scale, and customization depth. Pricing pressure stems from mega-brewer procurement teams negotiating 24-month contract cycles with aluminum-index-linked clauses that transfer commodity volatility upstream. Beverage giants exhibit highest price sensitivity; pharmaceutical buyers prioritize multi-site FDA registration over unit cost.
Supply Chain Analysis
Freight cost optimization centers on the Ohio River Valley aluminum smelting belt feeding Great Lakes forming operations. Raw material sourcing draws from domestic rolling mills, Canadian primary aluminum, and Mexican cross-border logistics hubs. Supply chain risk concentrates in tariff exposure across USMCA trade corridors. Distribution runs through direct procurement teams at bottling facilities and converter-owned warehousing at manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America metal caps and closures market sits in an aluminum-for-steel substitution phase, as beverage lightweighting mandates displace legacy tinplate formats with threaded aluminum designs.
For Market Incumbents: Hedge aluminum price volatility through diversified metal sourcing agreements beyond single-source contracts. Backward integration into captive rolling capacity secures supply continuity against tariff disruption. Child-resistant closure tooling investments defend positioning as cannabis legalization expands across US states and Canadian provinces. For New Entrants and Emerging Players: Enter via pharmaceutical specialty segments where multi-site FDA registration requirements create qualification barriers that favor agile specialists. Oncology and biologic drug packaging offers the most penetrable white-space target. Smart closure convergence with NFC-enabled authentication provides a differentiated go-to-market angle against established beverage-focused incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical compliance specialists given FDA food-contact notification backlogs that delay new alloy commercialization. Long-term viability favors converters with verified closed-loop aluminum recovery systems aligned to deposit-return system expansions. Watch for state-level extended producer responsibility legislation as the inflection signal for recycled-content specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Supply Agreement Diversification | Tariff resilience decouples converters from single-source beverage contracts across USMCA corridors. |
| Child-Resistant Closure Capacity Addition | Cannabis legalization across US states and Canadian provinces drives fastest-growing design category demand. |
| Multi-Site FDA Registration Expansion | Oncology and biologic drug packaging commands premium positioning through qualification barriers. |
| Smart Closure Technology Integration | NFC-enabled authentication opens premium spirits and cannabis positioning against counterfeiting. |
| Closed-Loop Aluminum Recovery Investment | British Columbia and Ontario EPR mandates create first-mover advantage in verified recycling systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with closure manufacturing executives, beverage procurement directors, pharmaceutical packaging engineers, and FDA regulatory consultants combined with secondary validation from EPA enforcement databases, USMCA trade statistics, and state-level EPR legislation trackers. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates.
Granularity-level modeling operated at product-type, end-user industry, material alloy, and closure-design dimensions across the projection horizon. CAGRs derived from aluminum lightweighting adoption curves, beverage format refresh cycles, and pharmaceutical safety mandate timelines. Forecast inputs incorporated deposit-return system expansion schedules and FDA food-contact notification approval lag assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff regime shifts or accelerated plastic substitution in non-carbonated beverages. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
France Plastic Caps and Closures Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Clic Loc Closure Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Tear-Tab Lids Market