
 Side Pour Caps Market | 2026-2036
Side Pour Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Side Pour Caps Market Analytics
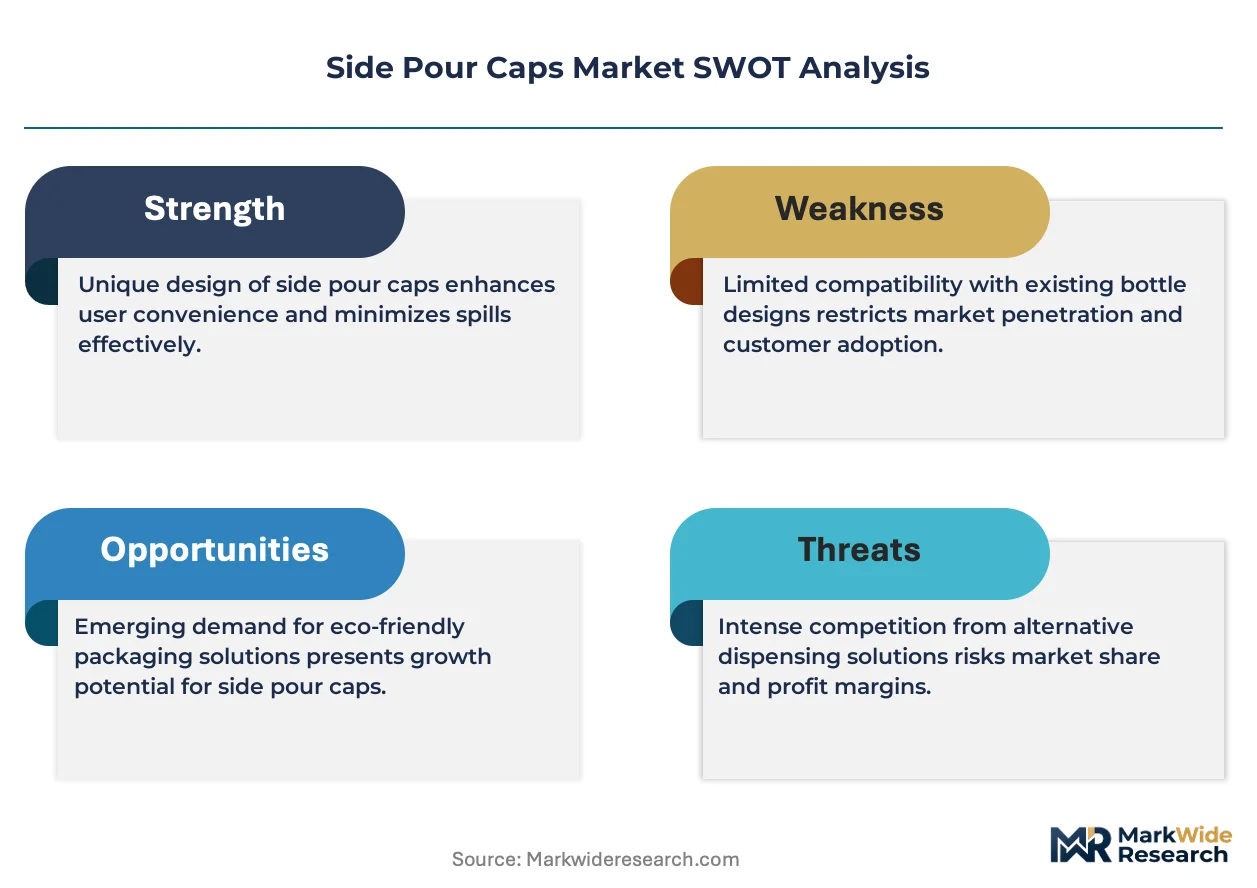
REACH compliance is broadening the cost-of-entry calculus for European suppliers of side pour caps, forcing reformulation of plastic resins and metal platings. Perlick Corporation leverages its century-long specialization in precision dispensing hardware to sustain premium positioning across commercial installations. KegWorks anchors North American distribution through deep channel control in craft beverage supply chains. Lukr Faucets dominates the authentic Czech-style side pour segment with proprietary flow-control engineering.
Side pour caps are precision dispensing closures engineered to regulate laminar flow at angles between 30 and 45 degrees, typically machined from stainless steel or food-grade polymer composites with internal venting channels to prevent turbulent pour. Their primary commercial purpose centers on controlled beverage dispensing in draft systems where foam reduction and visual presentation determine consumer experience. Plastic variants lead volume in mass-market beverage packaging due to cost scalability, while metal closures command margin pools in premium draft installations where thermal conductivity and durability outweigh unit economics. The Food & Beverage Industry end-user segment represents the most concentrated demand channel, with craft brewery adoption outpacing legacy macro-brewery retrofit cycles.
FDA food-contact regulations and EU REACH chemical safety frameworks jointly govern material composition standards for side pour caps in transatlantic trade, with EFSA migration limit testing adding compliance layers for polymer-based closures entering European hospitality channels. The EPA's evolving stance on perfluorinated compounds in food-contact materials is pressuring suppliers to certify fluorine-free seal formulations. Stakeholders must monitor regulatory divergence between US and EU material approval pathways when configuring multi-region product portfolios.
Market Dynamics
REACH compliance is rewriting the cost-of-entry calculus for European suppliers of side pour caps, forcing wholesale reformulation of plastic resins and metal platings while compressing margins for non-compliant producers.
Growth Catalysts
- EU Single-Use Plastics Directive:Germany's traditional beer culture regions and emerging craft clusters are accelerating adoption of reusable closure formats as hospitality venues retrofit draft systems to meet circular economy mandates.
- Precision flow-control engineering:Czech-style side pour technology is displacing conventional tap configurations in North American craft brewery installations seeking foam reduction and visual presentation differentiation.
- Stainless steel machining:Thermal conductivity advantages in premium draft installations are pulling metal closures into high-margin hospitality channels where durability outweighs unit economics.
Market Restraints
- Specialized alloy sourcing:Food-grade stainless steel supply concentrates in German and Austrian mill networks, exposing fabricators to input cost volatility and extended lead times.
- Polymer composite limitations:Current food-grade polymer formulations face migration limit testing barriers under EFSA protocols, restricting European market entry for lower-cost plastic variants.
- Fluorine-free seal alternatives:EPA pressure on perfluorinated compounds is forcing certification of substitute seal formulations that currently underperform on compression set and temperature resistance.
Strategic Opportunities
- Underpenetrated craft clusters:Secondary US metropolitan markets outside established beer hubs present whitespace for side pour system distributors with localized technical support capabilities.
- Regulatory tailwind:EU Green Deal packaging requirements are creating mandated demand for recyclable closure formats in hospitality channels across Belgium, Netherlands, and Denmark.
- Channel innovation:Direct-to-brewery technical consultation models are displacing traditional beverage equipment distributors in craft segment acquisition.
Industry Challenges
- Precision machining talent scarcity:CNC programming expertise for 30-45 degree laminar flow geometries concentrates in legacy Czech and German industrial regions, constraining capacity expansion.
- Legacy system integration:Retrofit compatibility with existing draft infrastructure requires custom adapter fabrication, extending sales cycles and technical validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Side Pour Caps Market |
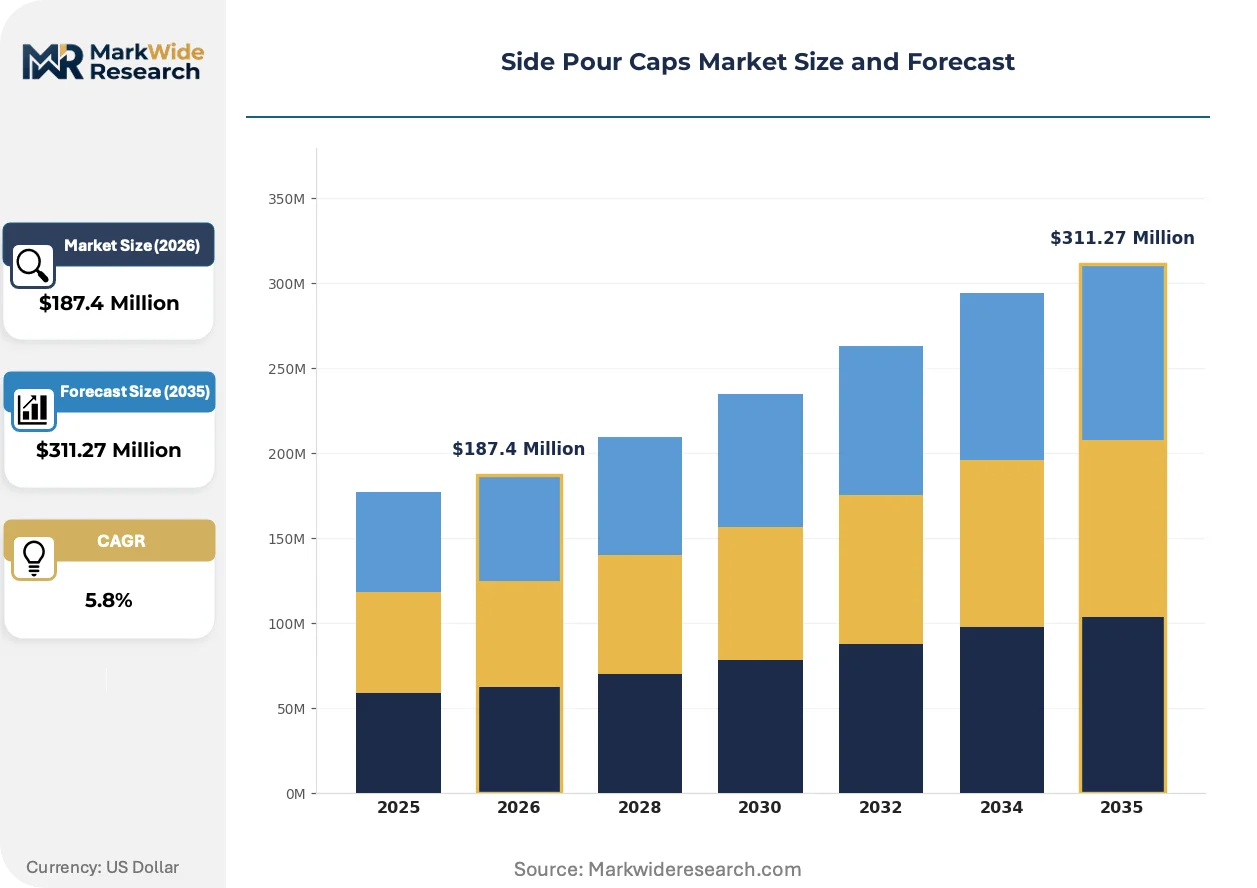
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Glass, Composite Application: Beverage Packaging, Food Containers, Chemical Storage, Personal Care Closure Type: Screw Caps, Snap-On Caps, Flip-Top Caps, Spout Caps End User: Consumer Goods, Food & Beverage Industry, Pharmaceutical Sector, Industrial Applications |
| Companies Covered | Lukr Faucets, KegWorks, Notch Brewing, Bierstadt Lagerhaus, Human Robot, Slow Pour Pils, Stomping Ground, Range Brewing, Perlick Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Side Pour Caps Market Evolving Landscape
Active material science development and regulatory chemistry frameworks are simultaneously pulling side pour cap design toward fluorine-free formulations and precision-machined metal architectures.
Advanced venting channel geometries are rewriting performance benchmarks for foam suppression in high-carbonation beverage dispensing. Craft breweries in Colorado and Oregon are specifying these configurations for hazy IPA and wild ale service. The technology is compressing acceptable tolerance bands from legacy ±2 degrees to ±0.5 degrees on pour angle consistency.
REACH Annex XVII restrictions on nickel release in prolonged food contact are forcing replating strategies for brass and bronze alloy components. German fabricators are migrating toward PVD ceramic coatings that satisfy ECHA migration thresholds. Premium draft installation suppliers in Bavaria and Baden-Württemberg are absorbing certification costs to maintain hospitality channel access.
Specification authority is rotating from procurement departments to draft system technicians and head brewers in craft segment purchasing. Technical consultation and pour training are displacing price-driven distributor relationships in brewery decision frameworks. This pattern concentrates in Pacific Northwest and Mid-Atlantic US craft clusters where technical differentiation drives taproom traffic.
Side Pour Caps Market Segmentation
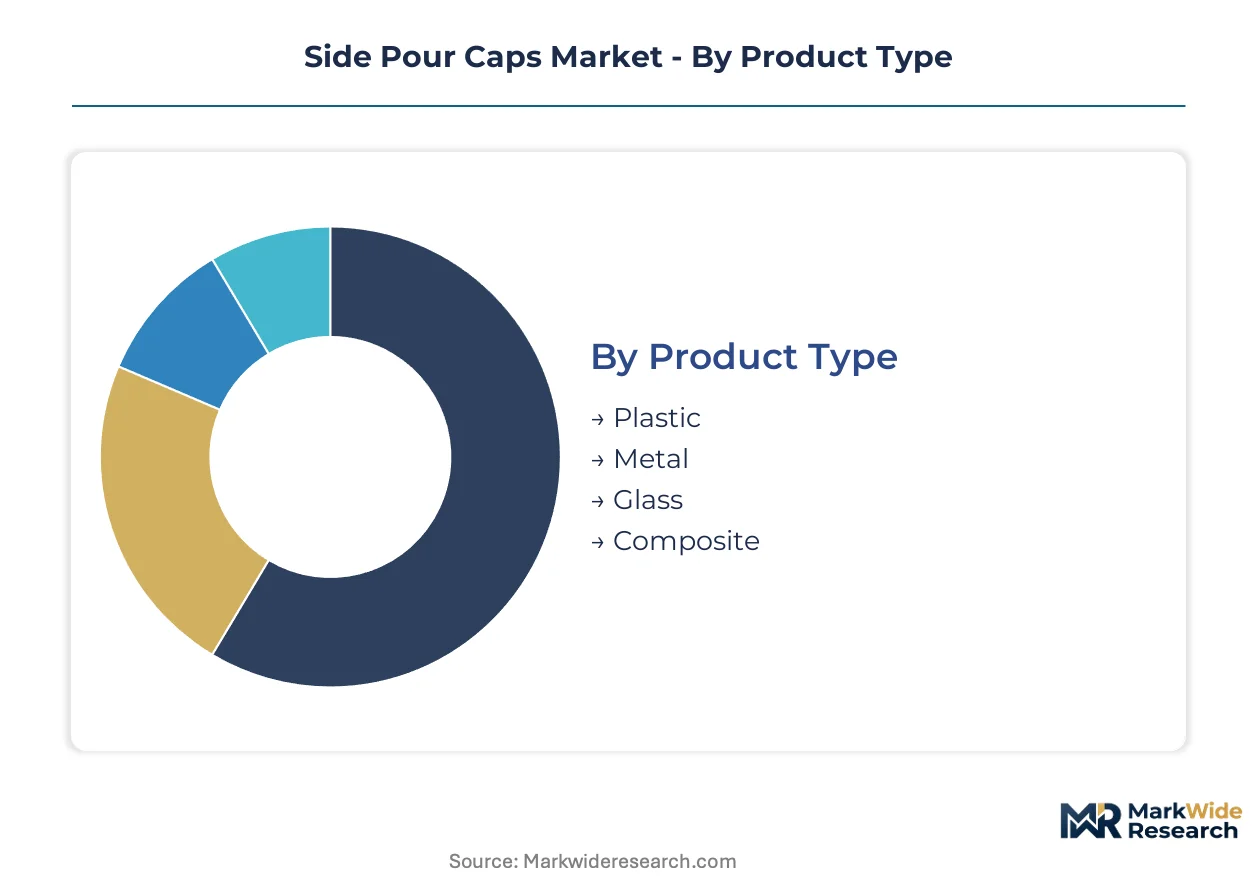
Side pour cap segmentation reveals divergent upgrade cycles across material classes and closure architectures. Brewery procurement teams evaluate retrofit compatibility against total cost of ownership when navigating product specifications.
Product Type:
Replacement cycles vary dramatically by material resilience and regulatory exposure, with hospitality venues weighing durability premiums against compliance certification burdens.
- Plastic:Injection-molded food-grade polymer variants dominate mass-market beverage packaging through cost scalability and color customization flexibility. Craft breweries in Oregon and Colorado specify these for seasonal rotational taps where frequent changeover outweighs longevity requirements. Migration limit testing under EFSA protocols restricts European market entry for lower-cost formulations.
- Metal:CNC-machined stainless steel and brass alloys command premium positioning in draft installations where thermal conductivity ensures temperature-stable pours. Bavarian fabricators source food-grade stainless from German and Austrian mill networks, absorbing lead time volatility to maintain hospitality channel access. REACH Annex XVII nickel release restrictions are forcing PVD ceramic coating adoption.
- Glass:Borosilicate and soda-lime variants serve specialized laboratory and premium spirits applications requiring chemical inertness.
- Composite:Hybrid polymer-metal architectures balance weight reduction with structural integrity in mobile dispensing systems.
Plastic sits at the top of the volume ranking, with Metal climbing the fastest.
Application:
End-use concentration patterns reflect divergent performance specifications and regulatory stringency across consumption environments.
- Beverage Packaging:Draft beer dispensing systems represent the primary commercial channel, with laminar flow control at 30-45 degree pour angles determining foam suppression performance. Czech-style side pour technology is displacing conventional tap configurations in North American craft brewery installations. Specification authority has rotated from procurement departments to head brewers and draft technicians.
- Food Containers:Precision dispensing closures for sauces, oils, and condiments require viscosity-calibrated flow channels distinct from carbonated beverage geometries.
- Chemical Storage:Laboratory and industrial chemical dispensing demands corrosion-resistant seal materials and venting architectures preventing pressure buildup.
- Personal Care:Cosmetic and pharmaceutical liquid dispensing emphasizes drip-free closure designs with ergonomic actuation forces.
Beverage Packaging captures the dominant revenue share, with Food Containers expanding most quickly.
Closure Type:
Mechanism selection hinges on operating environment demands, user ergonomics, and integration complexity with existing draft infrastructure.
- Screw Caps:Threaded metal or polymer closures provide resealable containment for portable beverage vessels and chemical storage containers. Torque specification standardization enables automated capping line compatibility across North American packaging facilities.
- Snap-On Caps:Interference-fit polymer designs enable rapid assembly in high-speed bottling operations where thread engagement slows throughput.
- Flip-Top Caps:Hinged polymer architectures dominate single-handed dispensing scenarios in food service and personal care applications.
- Spout Caps:Precision-molded laminar flow geometries with internal venting channels represent the core side pour technology, machined to ±0.5 degree pour angle tolerances in premium Czech and German fabrication centers.
Spout Caps lead technical innovation investment, with Screw Caps maintaining broadest installed base penetration.
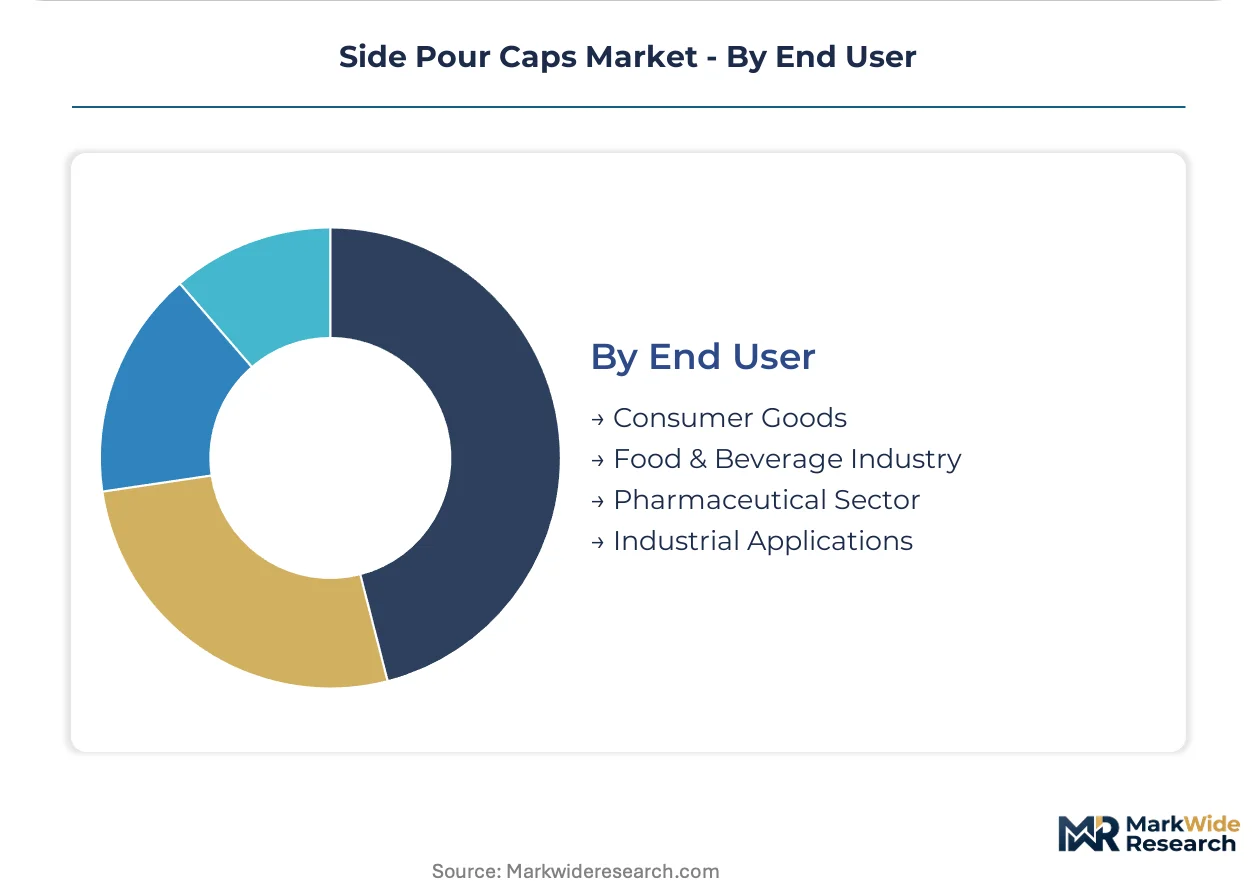
End User:
Purchasing authority structures and technical validation requirements diverge sharply across institutional versus commercial deployment contexts.
- Consumer Goods:Mass-market retail packaging emphasizes unit cost minimization and shelf differentiation through color and form factor variation.
- Food & Beverage Industry:Draft system operators in craft brewery taprooms and hospitality venues prioritize foam reduction performance and visual pour presentation. Technical consultation and pour training are displacing price-driven distributor relationships in brewery decision frameworks across Pacific Northwest and Mid-Atlantic clusters.
- Pharmaceutical Sector:Sterile dispensing and child-resistant closure mandates impose material traceability and validation documentation burdens distinct from commercial beverage applications.
- Industrial Applications:Chemical processing and manufacturing facilities specify corrosion-resistant alloys and pressure-rated seal designs for hazardous material containment.
Food & Beverage Industry commands the steepest expansion trajectory, with Pharmaceutical Sector demanding highest certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CNC programming expertise for 30-45 degree laminar flow geometries concentrates in legacy Czech and German industrial regions, constraining capacity expansion outside these talent pools.
United States
Craft brewery adoption of Czech-style side pour technology is outpacing legacy macro-brewery retrofit cycles in Colorado and Oregon clusters. EPA pressure on perfluorinated compounds in food-contact materials is forcing certification of fluorine-free seal formulations. Pacific Northwest and Mid-Atlantic craft clusters are rotating specification authority from procurement departments to head brewers and draft technicians.
Germany
Bavarian and Baden-Württemberg fabricators absorb certification costs to maintain hospitality channel access under REACH Annex XVII nickel release restrictions. The EU Single-Use Plastics Directive accelerates adoption of reusable closure formats in traditional beer culture regions. German and Austrian mill networks supply food-grade stainless steel, exposing fabricators to input cost volatility and extended lead times.
Czech Republic
Authentic Czech-style side pour segment dominance rests on proprietary flow-control engineering concentrated in legacy industrial regions. REACH compliance is rewriting cost-of-entry calculus for European suppliers, forcing wholesale reformulation of plastic resins and metal platings. Prague and Plzeň fabrication centers maintain ±0.5 degree pour angle tolerance benchmarks through precision machining heritage.
Belgium
EU Green Deal packaging requirements create mandated demand for recyclable closure formats in hospitality channels across Flanders and Wallonia. EFSA migration limit testing restricts European market entry for lower-cost plastic variants from non-compliant suppliers. Brussels and Leuven craft clusters are retrofitting draft systems to meet circular economy mandates ahead of neighboring markets.
Canada
Secondary metropolitan markets outside established beer hubs present whitespace for side pour system distributors with localized technical support capabilities. Health Canada food-contact regulations align with FDA frameworks while maintaining distinct approval pathways for polymer-based closures. Ontario and British Columbia craft brewery clusters are specifying advanced venting channel geometries for hazy IPA service.
Side Pour Caps Market Competitive Landscape
The competitive structure tilts toward precision-machining specialists with century-long dispensing hardware heritage. Player concentration fragments across geographic fabrication clusters rather than consolidating around integrated multinationals. Two strategic archetypes dominate: Czech-origin flow-control engineering houses and North American distribution-anchored technical consultancies. Capacity expansion and direct-to-brewery technical consultation models constitute the dominant competitive moves displacing traditional beverage equipment distributors.
Among Czech-origin specialists, Lukr Faucets occupies a position exemplifying authentic side pour engineering heritage, while Perlick Corporation represents the precision-dispensing hardware archetype with deep commercial installation specialization. KegWorks anchors North American distribution archetype through channel control in craft beverage supply chains. These three players sit within distinct competitive vectors—proprietary flow engineering, precision machining heritage, and distribution depth—rather than competing head-to-head on identical capability sets.
| Leading Market Players |
|---|
| Lukr Faucets |
| KegWorks |
| Notch Brewing |
| Bierstadt Lagerhaus |
| Human Robot |
| Slow Pour Pils |
| Stomping Ground |
| Range Brewing |
| Perlick Corporation |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging requirements gate qualified supply and premium-tier pricing access, as hospitality venues in Belgium and Denmark retrofit draft systems exclusively toward REACH-compliant fabricators while excluding lower-cost polymer suppliers from margin pools.
Pricing Analysis
Bundled technical consultation and pour training services separate premium Czech-origin suppliers from unbundled commodity distributors in North American craft brewery procurement. Three-tier pricing structure across premium certified-metal, mid-grade polymer, and economy injection-molded levels stratifies by REACH certification status and thermal conductivity performance. Cost compression in plastic variants is intensifying because EFSA migration limit testing excludes non-compliant Asian suppliers. Macro-brewery procurement departments exhibit highest price sensitivity; craft brewery head brewers prioritize pour consistency over unit economics.
Supply Chain Analysis
Freight cost volatility from German and Austrian mill networks to North American distribution centers amplifies landed cost premiums for food-grade stainless steel closures. Raw material sourcing draws from Czech precision-machining clusters, Bavarian PVD coating specialists, and Chinese polymer resin suppliers. Single-source vulnerability concentrates in CNC programming talent pools legacy-bound to Prague and Plzeň fabrication centers. Distribution runs through craft beverage equipment distributors and direct-to-brewery technical consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: REACH compliance costs in Germany and the Czech Republic create 15-20 point margin premiums versus North American suppliers facing lighter EPA fluorine-free seal mandates.
For Market Incumbents: Hedge against precision-machining talent scarcity by captive training programs in secondary US metropolitan markets outside Colorado and Oregon saturation. Defend margin position through backward integration into PVD ceramic coating capabilities rather than outsourced German replating. Channel control in Pacific Northwest craft clusters requires localized pour-training infrastructure. For New Entrants and Emerging Players: Draft system technicians represent the most accessible channel partner type for bypassing entrenched beverage equipment distributors. Secondary Canadian metropolitan markets outside Toronto and Vancouver present whitespace for technical support anchored entrants. Specification authority rotation toward head brewers enables direct-to-brewery go-to-market models displacing legacy procurement relationships. For Investors and Strategic Acquirers: Roll-up economics work for Czech-origin precision-machining specialists because fabrication talent concentrates in non-replicable industrial heritage clusters. Five-to-ten year viability hinges on regulatory divergence persistence between EU REACH and EPA frameworks. Acquisition targets should demonstrate EFSA migration limit certification and hospitality channel relationships. The signal to watch is EPA final rule timing on perfluorinated compound bans in food-contact materials.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification Investment | Unlocks hospitality channel access in Germany, Belgium, and Denmark under EU Green Deal mandates. |
| Direct-to-Brewery Technical Consultancy Launch | Captures specification authority rotation from procurement departments to head brewers in US craft clusters. |
| PVD Ceramic Coating Capability Buildout | Satisfies ECHA migration thresholds while replacing nickel-plated brass components in premium draft installations. |
| CNC Talent Development Program | Addresses precision-machining scarcity outside legacy Czech and German industrial regions. |
| Fluorine-Free Seal Formulation Partnership | Preempts EPA regulatory action on perfluorinated compounds in North American food-contact applications. |
Research Methodology
Multiple input streams — primary interviews with draft system technicians, head brewers, and hospitality procurement managers; secondary validation through FDA food-contact filings, ECHA REACH registration databases, and customs trade records — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across volume shipment tracking, certification database analysis, and channel partner revenue attribution anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material class, closure architecture, end-use concentration, and regional regulatory cluster. CAGRs were derived from installed base retrofit cycles and craft brewery formation rates. Industry-specific forecast inputs incorporated EPA perfluorinated compound regulatory trajectory and EU Single-Use Plastics Directive implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH Annex XVII expansion, EPA seal formulation rulemaking, and precision-machining talent migration patterns. Forecasts reflect documented assumptions regarding regulatory divergence persistence and craft brewery capital expenditure continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Cap Seals Market
Caps and Closures
Europe Metal Caps and Closures Market
Caps and Closures
United States Plastic Caps and Closure Market
Caps and Closures
PVC-Free Cap Liners Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Lined Lug Caps Market