
 Spout Closures Market | 2026-2036
Spout Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Spout Closures Market Analytics
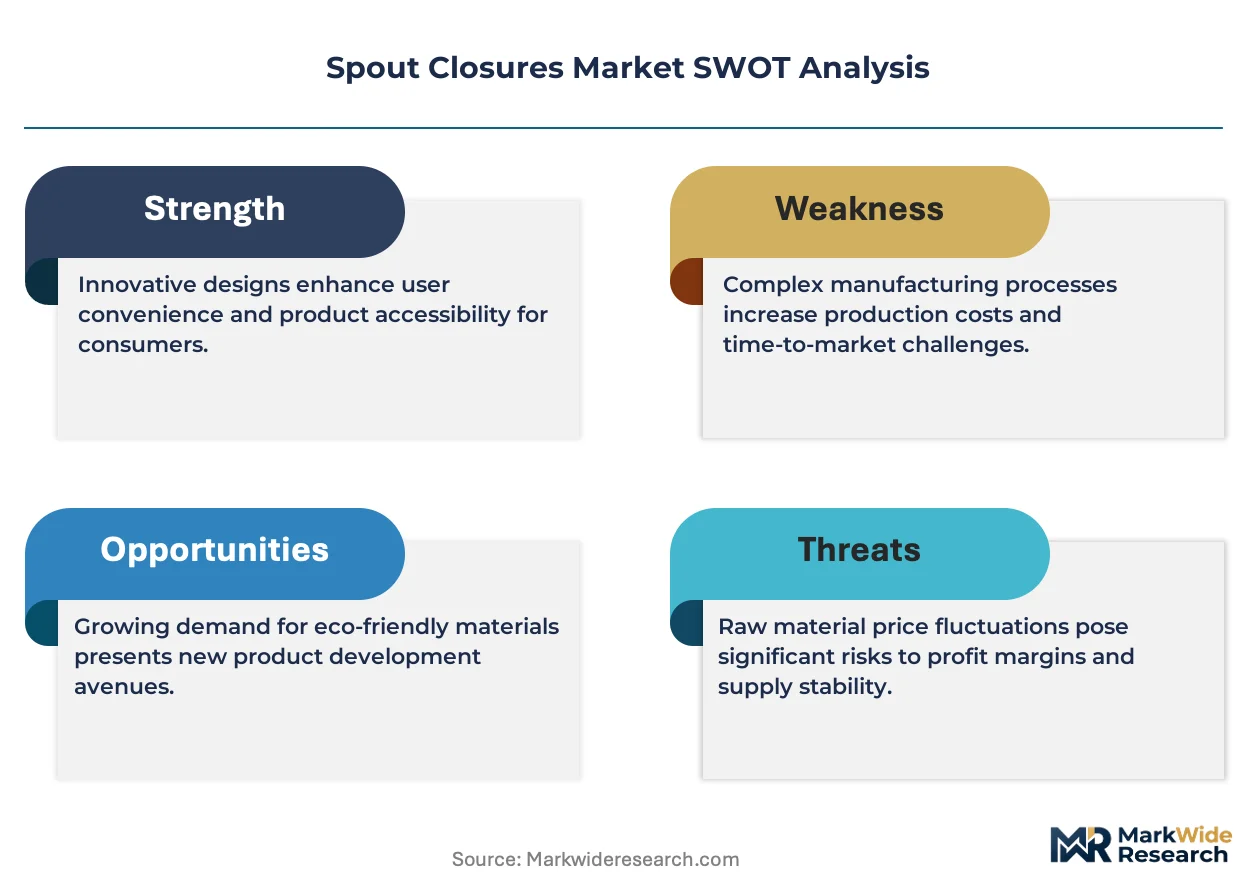
Capital-intensity divergence between blow-molding specialists and injection-molding pure-plays is rotating competitive advantage toward integrated resin-to-closure manufacturers. Berry Global Inc. leverages captive polyethylene supply chains to compress conversion costs on high-volume beverage contracts. Silgan Dispensing anchors North American personal care demand through dedicated dispensing technology centers that competitors struggle to replicate at equivalent scale.
Spout closures are precision-molded dispensing and resealing devices, typically engineered from polypropylene or polyethylene with tamper-evident ring geometries and controlled break-force specifications, designed to regulate product flow while preserving shelf stability across liquid and semi-liquid contents. Plastic spouts occupy the dominant share by closure type due to cost scalability and color customization flexibility, though metal spouts are gaining traction in premium olive oil and spirits applications where oxygen barrier performance commands price premiums. The food packaging application segment leads absolute volume, while personal care represents the fastest-growing margin pool as brands specify dual-chamber and directional-pour geometries.
FDA food-contact substance regulations, EU REACH chemical compliance frameworks, and California's SB 54 extended producer responsibility law collectively constrain material selection and obligate design-for-recyclability investments across the supply base. The EU Packaging and Packaging Waste Regulation tightens recycled content thresholds, forcing converters to validate post-consumer resin performance in living-hinge and threaded-closure geometries. Stakeholders must monitor polymer substitution timelines and regional enforcement variance to avoid stranded inventory in non-compliant formats.
Market Dynamics
Material substitution mandates under the EU Single-Use Plastics Directive are compressing converter margins while accelerating bio-polymer validation cycles across European packaging clusters.
Growth Catalysts
- Extended Producer Responsibility Laws:California SB 54 and New York state mandates force brands to specify recyclable spout formats, pulling volume toward converters with validated post-consumer resin capabilities.
- Food Packaging Converters:North American and European contract manufacturers are expanding resealable spout orders as CPG brands pursue shelf differentiation and portion-controlled dispensing.
- Polymer Innovation:Bio-based polyethylene and polypropylene grades from fermentation-derived feedstocks are clearing FDA food-contact thresholds, unlocking premium pricing in organic food segments.
Market Restraints
- Resin Price Volatility:Naphtha-derived polypropylene contracts swing with crude differentials, compressing spot margins for non-integrated molders lacking captive feedstock supply.
- German Machinery Concentration:Premium closure tooling and validation services cluster in Baden-Württemberg and Bavaria, creating geographic single-source risk for North American converters.
- Metal Substitution Threat:Tinplate and aluminum spouts penetrate premium olive oil and spirits categories where oxygen transmission rates below 0.1 cc/m²/day command price premiums plastic cannot match.
Strategic Opportunities
- Dual-Chamber Dispensing:Personal care brands in France and Germany specify separated-chamber spouts for active-ingredient isolation, opening margin pools above commodity beverage closures.
- EU Packaging and Packaging Waste Regulation:Recycled content thresholds tightening through 2030 force converters to validate post-consumer resin in living-hinge geometries, rewarding early compliance investments.
- E-Commerce Fulfillment Channels:Direct-to-consumer food subscription boxes specify leak-tested spout assemblies with drop-test certification, displacing traditional retail packaging specifications.
Industry Challenges
- Living-Hinge Fatigue Testing:Validating 10,000-cycle performance with post-consumer polypropylene requires specialized rheology expertise scarce among mid-tier molders.
- REACH Compliance Timelines:ECHA substance-of-very-high-concern notifications trigger 18-month reformulation windows that strand inventory in non-compliant colorant masterbatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spout Closures Market |
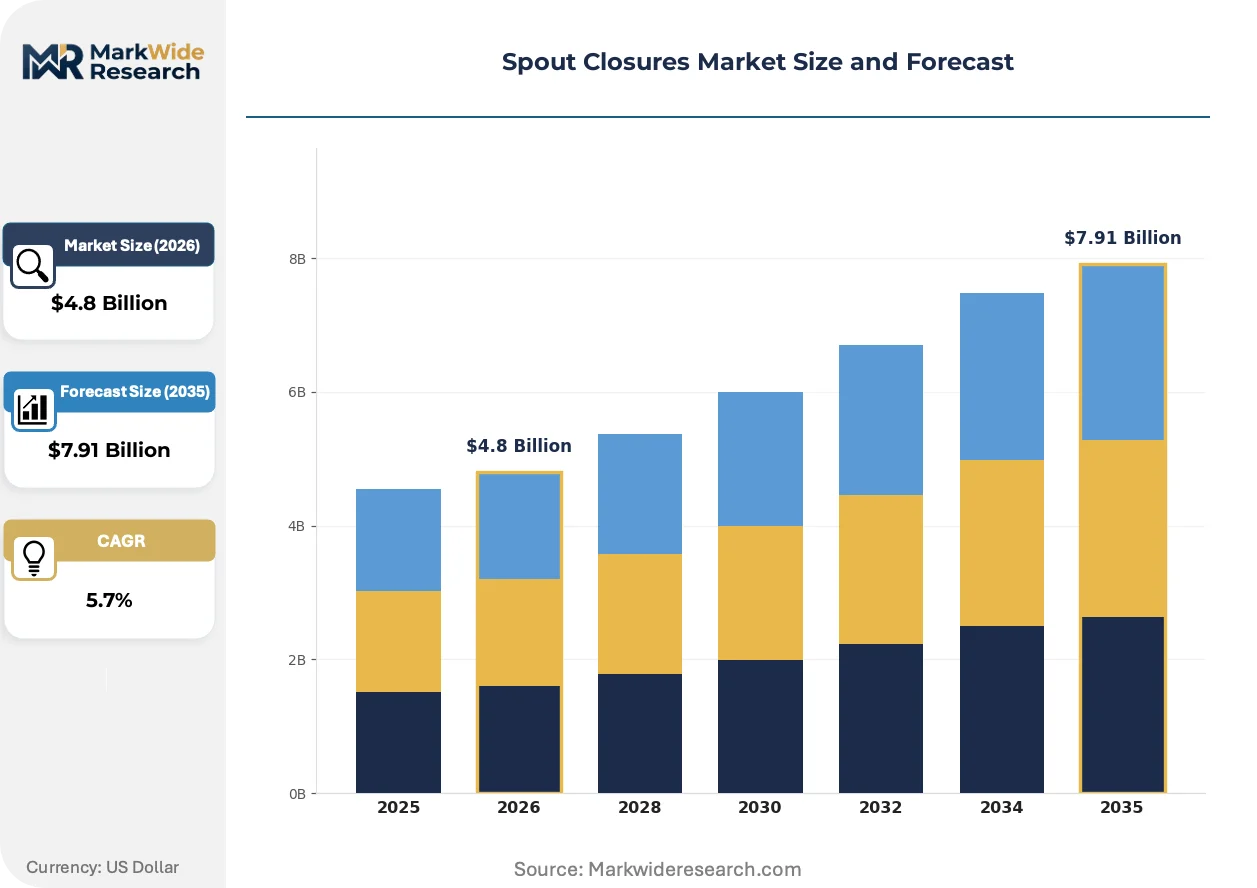
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Closure Type: Plastic Spouts, Metal Spouts, Twist Caps, Pull-Tab Spouts Application: Beverages, Food Packaging, Personal Care, Household Products End User: Retail, Wholesale, Direct-to-Consumer, Food Service Product Size: Small, Medium, Large, Extra Large |
| Companies Covered | Berry Global Inc., Silgan Dispensing, AptarGroup, Inc., Amcor Limited, Weener Plastics Group, Mold-Rite Plastics, BERICAP, O. Berk Company, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spout Closures Market Evolving Landscape
Precision molding technologies and regulatory material mandates are fragmenting the supplier base into resin-integrated specialists versus pure-play converters dependent on spot polymer markets.
Monolayer-to-multilayer co-injection molding is fragmenting competitive positioning among beverage closure manufacturers. High-barrier ethylene vinyl alcohol interlayers now integrate directly into spout bodies during single-shot molding cycles. Premium juice and functional drink brands in Germany and the Netherlands specify these structures for six-month shelf stability without refrigeration.
REACH chemical compliance frameworks are constraining additive packages across European converter operations. ECHA restrictions on intentionally added microplastics force reformulation of slip agents and anti-static compounds used in high-speed capping lines. Food packaging applications face the tightest substitution timelines as brands accelerate clean-label packaging claims ahead of enforcement deadlines.
Brand procurement teams now specify certified-recycled content percentages in annual closure contracts rather than accepting supplier declarations. Third-party verification through ISO 14021 environmental labels is displacing self-reported recycled content claims in French and German retail channels. Personal care brands lead this shift, with dual-chamber spout assemblies requiring chain-of-custody documentation for both resin streams.
Spout Closures Market Segmentation
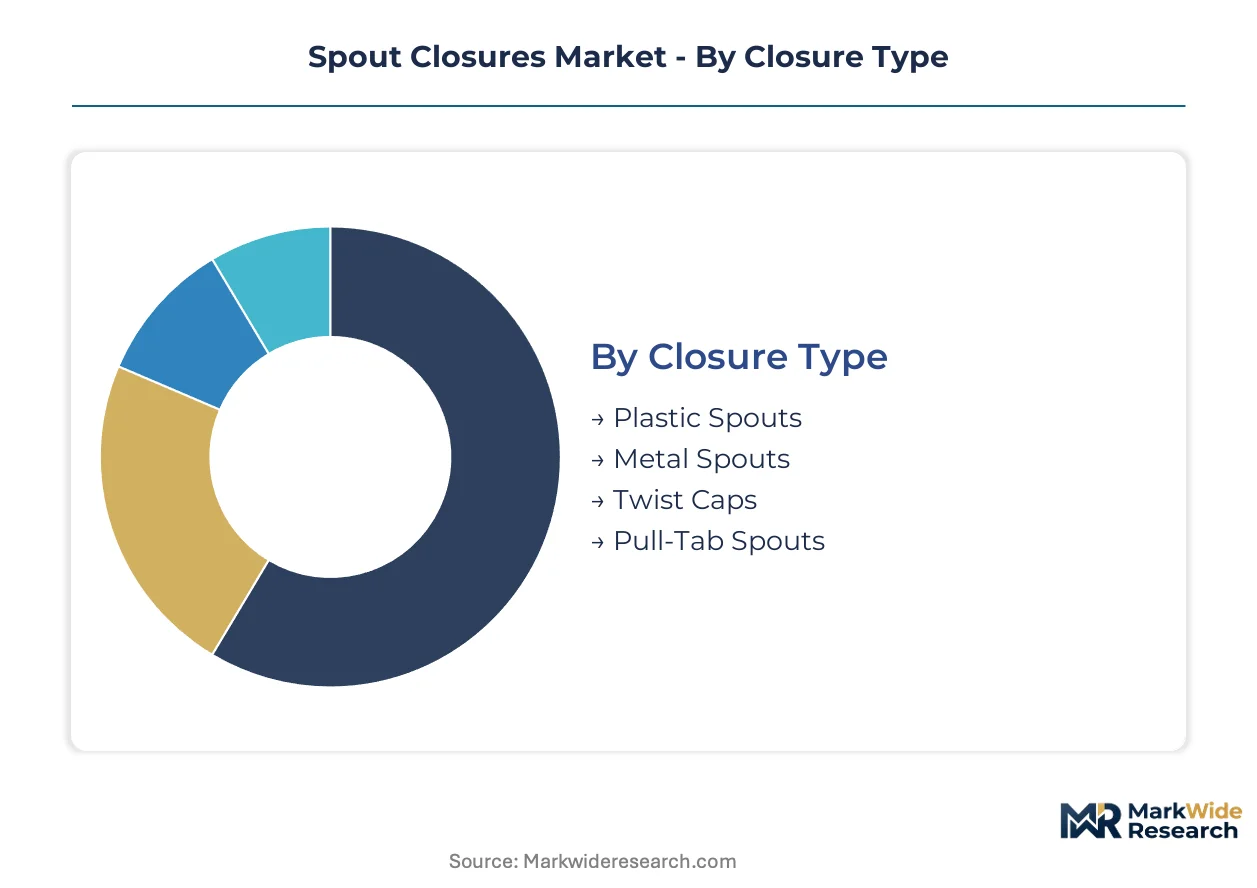
Spout closure procurement channels diverge sharply by segment, with retail-packaged beverages flowing through high-volume converter contracts while personal care direct-to-consumer orders specify custom validation protocols. Understanding these channel dynamics reveals where margin pools concentrate and where compliance investments yield pricing power.
Closure Type:
Channel mix varies by material performance tier, with commodity formats dominating mass retail and engineered solutions capturing premium direct-to-consumer subscriptions.
- Plastic Spouts:Injection-molded polypropylene and polyethylene constructions with living-hinge or threaded geometries dominate beverage and food packaging volume. German and Dutch retail channels pull the majority of European demand as brands specify recyclable monolayer formats under EU Packaging and Packaging Waste Regulation thresholds.
- Metal Spouts:Tinplate and aluminum precision-drawn assemblies with oxygen barrier ratings below 0.1 cc/m²/day serve premium olive oil and spirits categories. Italian and Spanish producers anchor Mediterranean demand where shelf stability without preservatives commands price premiums plastic cannot match.
- Twist Caps:Threaded polypropylene closures with tamper-evident bands flow through wholesale beverage channels requiring high-speed capping line compatibility.
- Pull-Tab Spouts:Single-use aluminum or polymer tear-strip formats concentrate in food service portion-control applications.
By volume, Plastic Spouts leads. By growth pace, Metal Spouts is ahead.
Application:
Cost tier stratification separates commodity beverage contracts from premium personal care specifications requiring dual-chamber validation.
- Beverages:Standard-thread and sports-cap geometries for juice, functional drinks, and water represent the baseline volume tier. California SB 54 compliance requirements are pulling recyclable format specifications ahead of other US states.
- Food Packaging:Resealable spouts for sauces, condiments, and baby food concentrate margin in validated post-consumer resin formats. French and German organic food brands specify bio-based polyethylene grades clearing FDA food-contact thresholds.
- Personal Care:Dual-chamber and directional-pour spout assemblies with separated active-ingredient channels command the steepest expansion trajectory. German and French brands lead specification of these premium geometries.
- Household Products:Industrial-scale closures for cleaning concentrates flow through wholesale and food service channels with lower customization requirements.
Beverages captures the highest absolute volume. Personal Care posts the steepest margin expansion.
End User:
Customer type determines validation depth, with retail and direct-to-consumer channels demanding chain-of-custody documentation absent from wholesale transactions.
- Retail:Mass-market supermarket and hypermarket channels specify ISO 14021-certified recycled content percentages in annual contracts.
- Wholesale:Bulk beverage and food service distributors prioritize capping speed compatibility over material certification.
- Direct-to-Consumer:Subscription box fulfillment requires drop-test certified leak-proof assemblies with validated living-hinge cycle performance.
- Food Service:Single-use portion-control formats with minimal reseal functionality concentrate in institutional procurement.
Retail leads by contract value. Direct-to-Consumer is climbing the fastest.
Product Size:
Volume scale correlates inversely with customization intensity, with smaller formats requiring proportionally higher precision molding investment.
- Small:Precision-molded single-serve portions for airline and hospitality samples demand tight dimensional tolerances.
- Medium:Standard retail SKUs for beverages and personal care represent the production efficiency sweet spot.
- Large:Family-size food packaging formats concentrate resealable functionality investment in German and US retail.
- Extra Large:Industrial and institutional refill formats prioritize cost per unit over feature complexity.
Medium leads by unit volume. Small is gaining share fastest in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in the United States by roughly one-third, reflecting tighter regulatory thresholds and machinery cluster concentration that compress converter margins elsewhere. This asymmetry shapes where premium spout volumes concentrate and where commodity formats dominate procurement.
Germany
Organic food brands in Baden-Württemberg specify bio-based polyethylene grades clearing FDA food-contact thresholds, pulling premium closure volumes ahead of broader European averages. The EU Packaging and Packaging Waste Regulation tightens recycled content mandates through 2030, forcing living-hinge validation investments. Stuttgart-area packaging machinery clusters supply precision tooling that North American converters struggle to replicate at equivalent scale.
United States
California SB 54 extended producer responsibility law forces brands to specify recyclable spout formats, pulling volume toward converters with validated post-consumer resin capabilities. FDA food-contact substance regulations constrain material selection across beverage and personal care applications. Midwest injection-molding corridors in Ohio and Illinois anchor high-volume beverage contract production for national retail chains.
France
Personal care brands in Île-de-France specify dual-chamber spout assemblies with separated active-ingredient channels, commanding margin pools above commodity beverage closures. ECHA restrictions on intentionally added microplastics force reformulation of slip agents in high-speed capping lines. Lyon-area converter operations specialize in clean-label packaging claims ahead of enforcement deadlines.
Italy
Premium olive oil producers in Tuscany and Emilia-Romagna specify tinplate and aluminum spouts with oxygen transmission rates below 0.1 cc/m²/day, where shelf stability without preservatives commands price premiums plastic cannot match. REACH compliance timelines trigger 18-month reformulation windows that strand inventory in non-compliant colorant masterbatches. Bologna-area metal forming clusters anchor Mediterranean demand for barrier-grade closure assemblies.
Netherlands
Functional drink brands in the Randstad specify high-barrier ethylene vinyl alcohol interlayers integrated directly into spout bodies during single-shot molding cycles for six-month shelf stability. ISO 14021 environmental labels displace self-reported recycled content claims in retail channels. Eindhoven-region co-injection specialists validate post-consumer polypropylene performance in living-hinge geometries ahead of EU threshold tightening.
Spout Closures Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with resin-integrated specialists commanding premium pricing while pure-play converters compete on spot polymer efficiency. The market structure consolidates around three tiers: captive feedstock operators, precision-dispensing technology centers, and regional contract molders. Strategic archetypes include backward-integrated resin producers, dual-chamber geometry specialists, and high-volume beverage closure fabricators. Dominant competitive moves center on M&A for resin supply security and capacity expansion in bio-polymer validation facilities.
Among North American fabricators, Berry Global Inc. exemplifies the backward-integrated archetype through captive polyethylene supply chains, while Silgan Dispensing occupies a position within precision-dispensing technology centers. AptarGroup, Inc. represents the dual-chamber specialist tier serving personal care brands with separated active-ingredient isolation requirements. These three anchors illustrate how competitive positioning fragments between cost compression capabilities and premium geometry validation expertise.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Silgan Dispensing |
| AptarGroup, Inc. |
| Amcor Limited |
| Weener Plastics Group |
| Mold-Rite Plastics |
| BERICAP |
| O. Berk Company |
| Constantia Flexibles |
| Others |
Value Network & Pricing Analysis
EU REACH chemical compliance frameworks gate both converter qualification and price differentiation simultaneously, with ECHA substance-of-very-high-concern notifications triggering reformulation investments that separate certified suppliers from spot-market competitors. California SB 54 extended producer responsibility requirements impose parallel certification burdens that concentrate buyer procurement toward validated resin-to-closure manufacturers.
Pricing Analysis
Configured-to-order pricing for dual-chamber personal care spouts commands spreads exceeding standard beverage closure contracts by significant multiples. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with ISO 14021-verified recycled content formats capturing premium positioning. Cost compression in commodity beverage tiers intensifies because naphtha-derived polypropylene contracts swing with crude differentials. Food packaging converters demonstrate highest price sensitivity due to thin spot margins, while personal care brands show least sensitivity when specifying active-ingredient isolation geometries.
Supply Chain Analysis
Inventory lead times for precision tooling from Baden-Württemberg and Bavaria machinery clusters extend beyond North American converter planning horizons. Geographic supply concentration centers on Germany, the United States, and the Netherlands for high-barrier co-injection capabilities. Raw material dependencies rest on fermentation-derived bio-polyethylene, post-consumer polypropylene resin streams, and ethylene vinyl alcohol barrier interlayers. Single-source vulnerability from German tooling concentration creates structural risk for converters lacking validated secondary sources. Distribution runs through converter-to-brand direct contracts rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail procurement teams specifying certified-recycled content percentages in multi-year closure contracts, fragmenting supplier bases between compliant and non-compliant tiers.
For Market Incumbents: Secure captive bio-polymer supply chains through fermentation-derived feedstock partnerships before REACH compliance timelines strand conventional resin inventories. Defend margin position by expanding validation capacity for living-hinge geometries with post-consumer polypropylene, as ECHA restrictions on intentionally added microplastics accelerate clean-label substitution cycles. For New Entrants and Emerging Players: Anchor in direct-to-consumer food subscription channels requiring drop-test certified leak-proof assemblies, where incumbent converters lack specialized fulfillment expertise. Target white-space in French and German dual-chamber personal care specifications, penetrating through chain-of-custody documentation capabilities that commodity molders cannot replicate. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation recycled content threshold tightening reshapes the acquisition landscape toward converters with validated post-consumer resin performance in living-hinge geometries. Long-term viability favors resin-integrated specialists over pure-play molders exposed to spot polymer volatility. Watch ECHA enforcement variance across member states as inflection indicator for stranded inventory risk.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Polymer Validation Facility Expansion | Fermentation-derived polyethylene clearing FDA food-contact thresholds unlocks organic food segment premium pricing. |
| Post-Consumer Resin Integration | Living-hinge geometries with recycled polypropylene satisfy EU Packaging and Packaging Waste Regulation tightening mandates. |
| Dual-Chamber Geometry Patent Portfolio | Separated active-ingredient channels command margin pools above commodity beverage closures in French personal care. |
| German Machinery Cluster Partnership | Baden-Württemberg precision tooling access reduces geographic single-source risk for North American converters. |
| Direct-to-Consumer Fulfillment Certification | Drop-test validated assemblies displace traditional retail specifications in food subscription box channels. |
Research Methodology
The analysis maps plastic spout, metal spout, and dual-chamber dispensing sub-sectors, each validated through packaging machinery engineers, brand procurement managers, and resin technical directors. Primary interviews with converter operations heads, regulatory compliance officers at FDA and ECHA, and personal care brand packaging developers combined with secondary validation from customs trade data, SEC 10-K filings of listed packaging companies, EU regulatory filings, and retail channel audit databases. Bottom-up resin demand modeling and top-down packaging value chain sizing provided cross-check triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled closure type, application segment, end-user channel, and regional regulatory cluster dimensions. CAGRs derived from polymer substitution timelines, machinery capacity expansion announcements, and brand specification shift patterns. Industry-specific forecast inputs included bio-polymer fermentation capacity buildouts and ECHA substance restriction enforcement schedules.
Material uncertainties — resin price volatility, regulatory enforcement variance, and polymer substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about compliance timeline adherence and brand specification inertia. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Elastomeric Closures Market
Caps and Closures
Dispensing Spouts Market
Caps and Closures
Case Closures and Sealers Market
Caps and Closures
Indonesia Plastic Caps and Closures Market
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
Low Profile Compact System Closures Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
Colombia Plastic Caps and Closures Market
Caps and Closures
Screw Closure Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Screw Caps and Closure Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Twist Dispensing Closures Market