
 Brush Caps Market | 2026-2036
Brush Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Brush Caps Market Analytics
Premium-grade polymer specifications are rotating toward higher chemical resistance and precision dispensing tolerances in brush cap procurement. Artis leverages vertical integration across cosmetic applicator design to control quality tiers from resin selection to final assembly. Quantum Labs sustains R&D intensity in specialty polymer formulations that meet EU cosmetic contact standards. Morgan Advanced Materials anchors ceramic-injection capabilities for high-temperature adhesive brush caps serving industrial coatings segments.
Brush caps are precision closure devices integrating filament bundles or applicator tips with threaded, snap-fit, or push-lock bases to enable controlled fluid dispensing; they typically incorporate polypropylene or polyethylene bodies with solvent-resistant thermoplastic elastomer seals, molded through multi-cavity injection processes to achieve leak-proof engagement with container necks. Screw caps dominate volume in paints and adhesives where torque security prevents solvent evaporation, while dispensing caps command margin concentration in cosmetics as brands prioritize controlled flow and ergonomic fingertip control. Plastic material grades lead unit economics across mass-market applications, though metal closures retain structural share in industrial inks requiring corrosion resistance.
REACH substance restrictions and FDA cosmetic contact regulations jointly constrain base polymer and additive selection for brush caps entering European and North American distribution. EMA and EFSA frameworks indirectly shape demand through downstream cosmetic ingredient approvals that propagate into packaging material compliance requirements. BIS certification pressures are rising for brush cap imports into India's expanding domestic cosmetics manufacturing base. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these compounds historically enabled low-surface-energy seals in premium dispensing closures.
Market Dynamics
REACH substance restrictions and FDA cosmetic contact regulations are compressing polymer formulation options while simultaneously fragmenting supplier qualification pools across European and North American distribution channels.
Growth Catalysts
- Precision dispensing demand:Cosmetics manufacturers in Germany are expanding procurement of brush caps engineered for controlled flow of liquid and cream formulations, tightening tolerance specifications for filament bundle alignment.
- REACH compliance differentiation:EU regulatory pressure on per- and polyfluoroalkyl substances is creating competitive separation between suppliers with certified alternative seal chemistries and those dependent on legacy formulations.
- Industrial coatings expansion:High-temperature adhesive applications in automotive refinishing are pulling ceramic-injection molded brush caps into specification sheets previously dominated by standard polymer closures.
Market Restraints
- Specialty polymer supply concentration:Solvent-resistant thermoplastic elastomer feedstocks for cosmetic-grade seals concentrate among a limited set of European compounders, exposing brush cap molders to input volatility.
- Multi-jurisdiction PFAS restrictions:Divergent phase-out timelines across EU REACH, US EPA state-level rules, and emerging frameworks in Canada and Japan complicate global product platform standardization.
- Metal closure substitution in industrial inks:Corrosion-resistant aluminum and steel brush caps retain structural share in packaging for solvent-based printing inks, capping polymer penetration in this segment.
Strategic Opportunities
- India domestic manufacturing incentive:BIS certification pressures on imported brush caps coincide with PLI scheme support for local cosmetics packaging production, opening captive supply arrangements with multinational beauty brands.
- Biopolymer formulation convergence:Advanced bio-based polypropylene grades meeting EU cosmetic contact standards are enabling premium positioning for sustainability-messaging brands seeking petroleum-free closure systems.
- Direct-to-brand distribution channels:E-procurement platforms specializing in beauty packaging components are disintermediating traditional regional distributors for mid-volume cosmetic manufacturers in France and Italy.
Industry Challenges
- Multi-cavity mold qualification timelines:FDA and EMA cosmetic contact certifications for new brush cap designs require 18-24 month validation cycles, compressing product development windows for seasonal cosmetics launches.
- Legacy equipment integration:Precision dispensing brush caps with modified thread geometries face compatibility friction with existing capping machinery installed across contract packaging facilities in North America.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brush Caps Market |
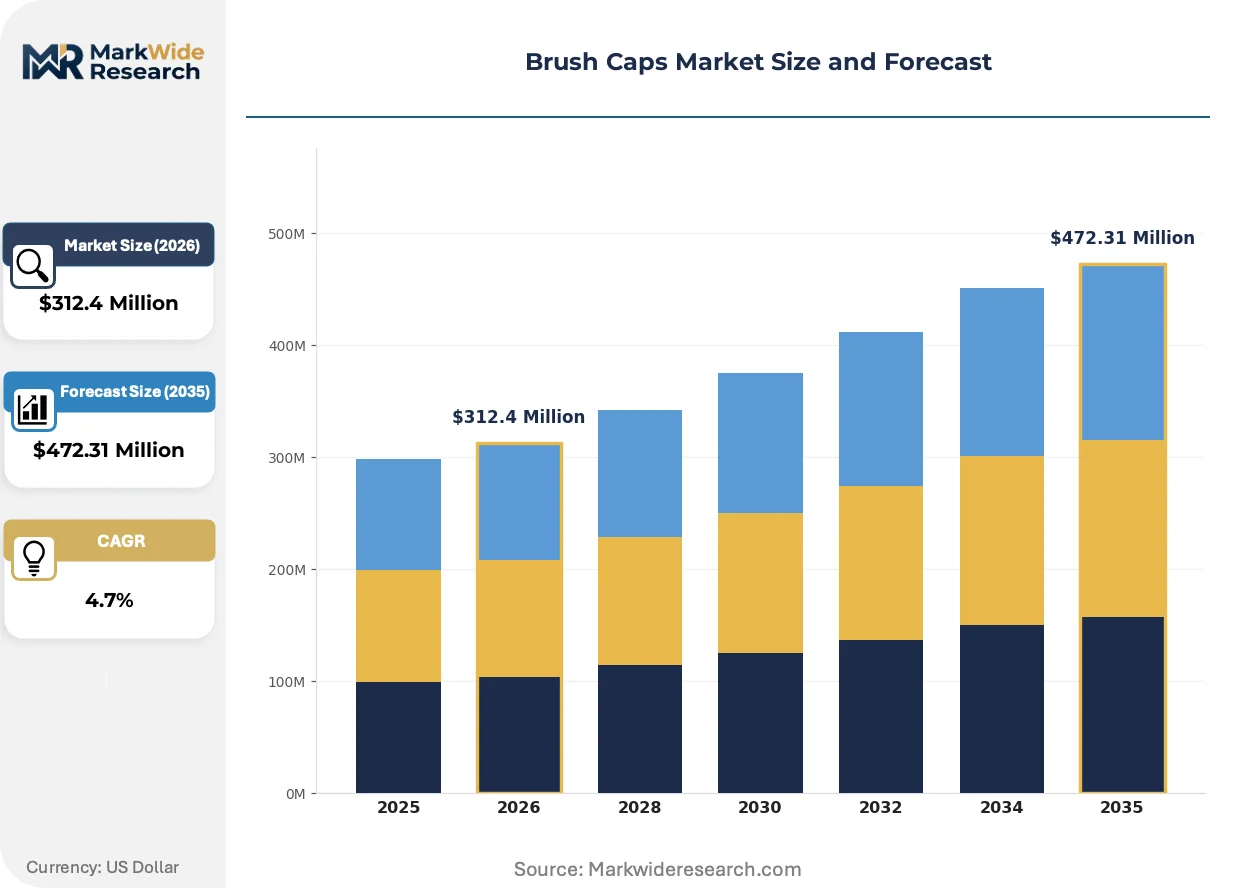
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Flip Caps, Snap Caps, Dispensing Caps Material: Plastic, Metal, Glass, Rubber Application: Cosmetics, Paints, Adhesives, Inks Closure Type: Screw-on, Push-fit, Twist-off, Pop-up |
| Companies Covered | Artis, Tilt Professional Makeup, Paint Brush Cover, Triple Bristle, Likwid Concepts, Quantum Labs, Rockler Companies, RACCOON COMMERCE, Morgan Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brush Caps Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are actively reconfiguring competitive advantage in brush cap manufacturing, with sustainability credentials and precision engineering emerging as the primary axes of differentiation.
Ceramic-injection molding for high-temperature brush cap applications is displacing traditional metal-over-polymer hybrid constructions in industrial coatings segments. Automotive refinishing shops and aerospace maintenance facilities are specifying these units for solvent-heavy adhesive systems. The shift is compressing supplier margins on conventional metal closure production while rewarding compounders with in-house ceramic formulation capabilities.
REACH Annex XVII expansions targeting per- and polyfluoroalkyl substances are forcing reformulation of low-surface-energy seals across European cosmetic packaging supply chains. Brush cap manufacturers dependent on legacy fluoropolymer additives face 12-18 month redesign cycles to qualify silicone and hydrocarbon-based alternatives. German specialty chemical clusters are capturing disproportionate share of requalification contracts due to proximity to ECHA technical guidance and rapid analytical testing infrastructure.
Cosmetics brands are consolidating brush cap suppliers around vertically integrated partners controlling resin selection through final assembly. This procurement pattern is displacing fragmented sourcing models that separated polymer compounders, molders, and filament integrators. The concentration is most visible among North American prestige beauty houses seeking single-point accountability for REACH and FDA compliance documentation.
Brush Caps Market Segmentation
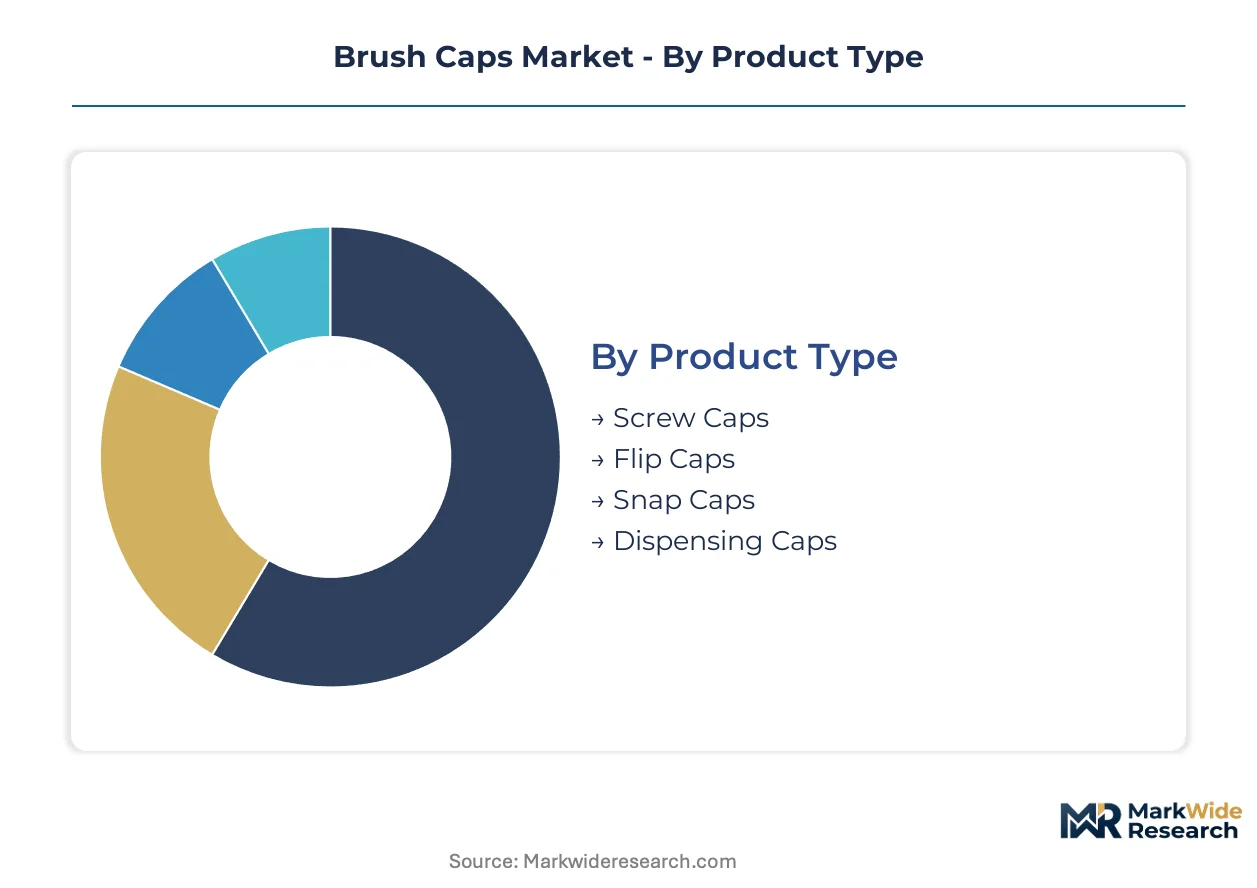
Brush cap procurement patterns diverge sharply across end-use specifications, with cosmetic manufacturers demanding precision tolerances while industrial coatings buyers prioritize chemical resistance. Material selection and closure geometry together determine supplier qualification pools and margin structures.
Product Type:
Screw caps face intensifying substitution pressure from dispensing variants in premium cosmetics, while flip and snap formats erode share in portable personal care applications.
- Screw Caps:Threaded polymer bodies with torque-resistant engagement profiles dominate solvent-heavy industrial formulations. Paints and adhesives manufacturers in Germany specify these units for evaporation control in warehouse storage environments.
- Dispensing Caps:Controlled-flow mechanisms with filament bundle integration command specification sheets for liquid foundation and serum formulations. North American prestige beauty houses consolidate procurement around these variants to enable fingertip dosage precision.
- Flip Caps:Hinged polymer lids suit single-hand operation in travel-size cosmetics and on-the-go personal care.
- Snap Caps:Audible engagement feedback supports child-resistant packaging requirements in household adhesive segments.
Screw caps retain volume leadership; dispensing caps hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity polymer grades from certified cosmetic-contact compounds and corrosion-resistant metal closures.
- Plastic:Polypropylene and polyethylene grades processed through multi-cavity injection molding deliver unit economics for mass-market applications. REACH-compliant thermoplastic elastomer seals from German compounders satisfy EU cosmetic contact standards.
- Metal:Aluminum and steel closures resist solvent corrosion in industrial ink packaging. Japanese printing chemical manufacturers specify these units for extended shelf-life requirements.
- Glass:Borosilicate and soda-lime variants serve premium fragrance and pharmaceutical applications demanding inert contact surfaces.
- Rubber:Natural and synthetic elastomer formulations provide compression seals in high-temperature adhesive brush caps.
Plastic dominates unit shipments; metal closures defend structural share in corrosion-critical segments.
Application:
Customer type fragmentation splits demand between brand-direct cosmetic procurement and distributor-mediated industrial supply chains.
- Cosmetics:Precision filament alignment and ergonomic fingertip control drive specification tightening for liquid and cream formulations. French and Italian beauty brands consolidate supplier bases around vertically integrated partners.
- Paints:Solvent-resistant sealing and torque security dominate technical requirements in architectural and automotive refinishing coatings.
- Adhesives:High-temperature ceramic-injection molded caps displace metal hybrids in aerospace maintenance and automotive assembly applications.
- Inks:Corrosion-resistant closures preserve solvent-based printing formulations in commercial packaging and publishing supply chains.
Cosmetics application commands margin concentration; adhesives segments are climbing fastest on industrial coatings expansion.
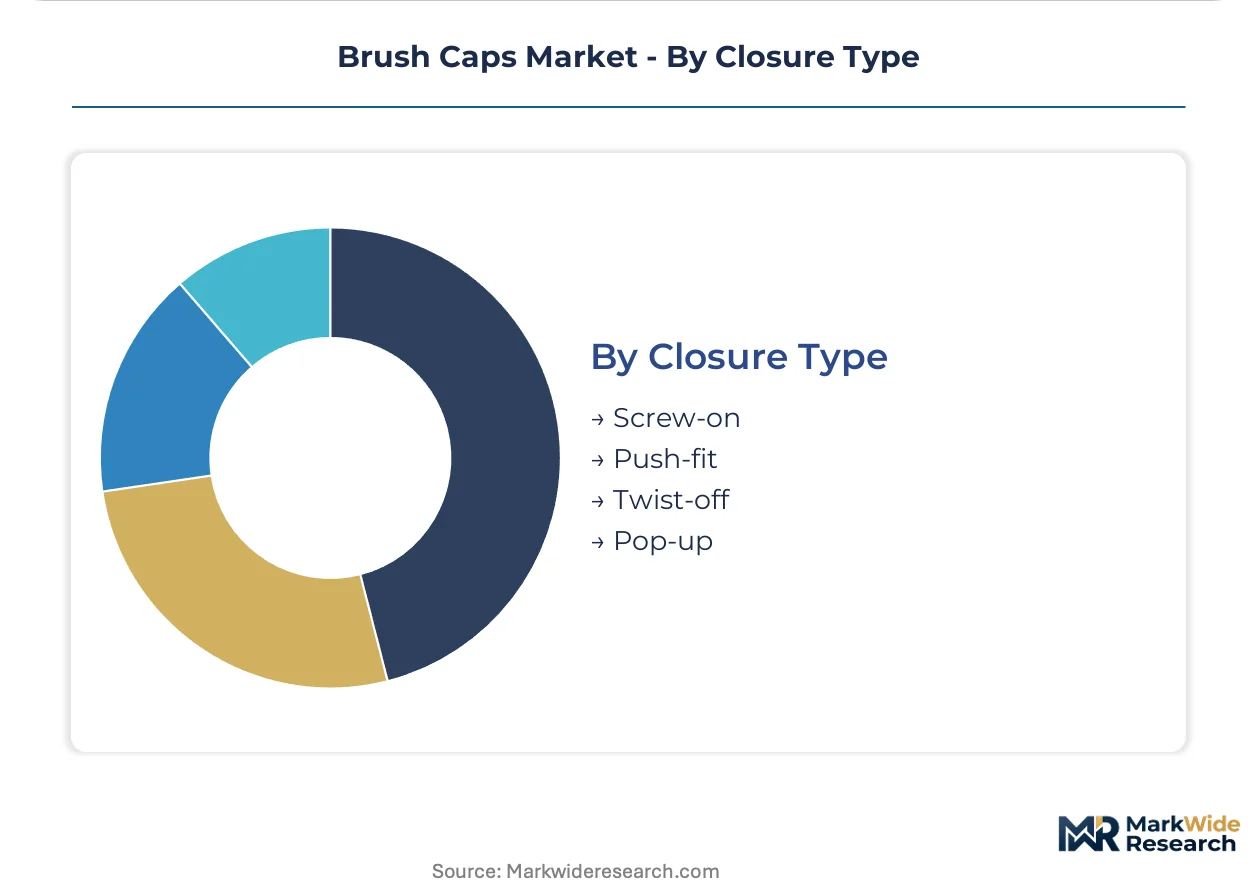
Closure Type:
Supply concentration in precision molding equipment shapes competitive access across thread geometry categories.
- Screw-on:Standardized thread profiles ensure compatibility with existing capping machinery across contract packaging facilities. FDA validation timelines of 18-24 months constrain new design introduction.
- Push-fit:Snap-engagement mechanisms enable rapid assembly in high-volume personal care production lines.
- Twist-off:Break-seal indicators support tamper-evident requirements in pharmaceutical and premium cosmetic packaging.
- Pop-up:Spring-actuated dispensing tips target controlled-flow applications in serum and treatment formulations.
Screw-on closures maintain installed base dominance; pop-up mechanisms are gaining share fastest on precision dispensing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in precision brush cap exports to cosmetics manufacturers across France and Italy, while the United States and China balance import dependence in specialty polymer formulations against domestic molding capacity expansion.
Germany
Cosmetics manufacturers in Hamburg and Frankfurt tighten procurement specifications for filament bundle alignment in liquid foundation applications. ECHA REACH Annex XVII expansions on per- and polyfluoroalkyl substances force compounders in the Cologne-Düsseldorf corridor to accelerate silicone-based seal requalification. Specialty chemical clusters in North Rhine-Westphalia capture disproportionate share of EU cosmetic packaging compliance contracts.
United States
Prestige beauty houses in New York and Los Angeles consolidate supplier bases around single-point accountability for FDA cosmetic contact documentation. EPA state-level PFAS restrictions in California and New York diverge from federal timelines, complicating national product platform standardization. Contract packaging facilities in New Jersey face compatibility friction with precision dispensing caps requiring modified thread geometries.
China
Domestic cosmetics brands in Shanghai and Guangzhou expand procurement of REACH-compliant brush caps for export-oriented production. SAMR cosmetic safety standards tighten material compliance requirements for closure systems entering premium distribution channels. Yangtze River Delta molding clusters invest in multi-cavity injection capacity to serve European brand technical specifications.
India
Multinational beauty brands accelerate captive supply arrangements with domestic manufacturers under PLI scheme support for local cosmetics packaging production. BIS certification pressures on imported brush caps coincide with CDSCO downstream cosmetic ingredient approvals propagating into packaging material requirements. Maharashtra-based compounders develop thermoplastic elastomer formulations for solvent-resistant cosmetic-grade seals.
Japan
Printing chemical manufacturers in Osaka and Tokyo specify corrosion-resistant metal brush caps for solvent-based ink formulations requiring extended shelf-life performance. METI industrial standards shape high-temperature adhesive applications in automotive refinishing segments. Kansai-region ceramic-injection capabilities serve aerospace maintenance specifications previously dominated by standard polymer closures.
Brush Caps Market Competitive Landscape
Concentration sits with vertically integrated compounder-molders controlling resin selection through final assembly. Supplier qualification pools fragment across REACH and FDA certification tiers, compressing margin capture for non-certified fabricators. Three archetypes dominate: specialty polymer formulators, precision injection molders, and filament-integrating closure assemblers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure captive supply arrangements with multinational beauty brands.
Within the specialty materials tier, Morgan Advanced Materials anchors ceramic-injection capabilities for industrial coatings segments, while Quantum Labs exemplifies the polymer formulation archetype serving EU cosmetic contact standards. Artis occupies a position representing vertically integrated design-through-assembly models that consolidate procurement accountability for North American prestige beauty houses. These three entities collectively illustrate the capability spectrum from raw material chemistry to finished closure integration.
| Leading Market Players |
|---|
| Artis |
| Tilt Professional Makeup |
| Paint Brush Cover |
| Triple Bristle |
| Likwid Concepts |
| Quantum Labs |
| Rockler Companies |
| RACCOON COMMERCE |
| Morgan Advanced Materials |
| Others |
Value Network & Pricing Analysis
Multi-cavity injection molding scale economies in Germany's North Rhine-Westphalia cluster compress unit costs for REACH-compliant thermoplastic elastomer seals while establishing price floors that smaller compounders in Eastern Europe struggle to match. This concentration of precision molding capacity simultaneously elevates procurement leverage for multinational cosmetics brands and squeezes margin capture for non-certified fabricators in peripheral supply zones.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across solvent-resistant adhesive applications. Pricing stratifies across premium, standard, and economy tiers based on certification grade and filament bundle precision alignment. Cost compression in standard-grade polypropylene caps is intensifying because Yangtze River Delta molders are expanding capacity for export-oriented production. Industrial coatings buyers exhibit lowest price sensitivity due to specification-locked ceramic-injection requirements, while mass-market personal care brands drive hardest bargain on volume scale.
Supply Chain Analysis
Strait of Malacca transit underwrites polymer resin flows from Middle Eastern petrochemical complexes to injection molding clusters in China and Southeast Asia. Feedstock supply concentrates in Germany, China, and the United States for specialty thermoplastic elastomer formulations. Raw material procurement draws from polypropylene resin, silicone seal compounds, and ceramic powder feedstocks. Single-source vulnerability concentrates among European compounders certified for EU cosmetic contact standards. Distribution runs through brand-direct channels for prestige cosmetics and distributor-mediated networks for industrial coatings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII expansions on per- and polyfluoroalkyl substances are disrupting legacy seal chemistries, creating acquisition opportunities for compounders with certified silicone-based alternatives and compressing timelines for laggard reformulation.
For Market Incumbents: Consolidate supplier qualification pools around vertically integrated partners controlling resin selection through final assembly to defend against REACH compliance documentation fragmentation. Expand multi-cavity molding capacity in Germany's Cologne-Düsseldorf corridor to capture requalification contracts from competitors dependent on legacy fluoropolymer additives. Prioritize backward integration into specialty polymer formulation to secure thermoplastic elastomer supply against input volatility from limited European compounders. For New Entrants and Emerging Players: Differentiate on biopolymer formulation convergence by developing advanced bio-based polypropylene grades meeting EU cosmetic contact standards for sustainability-messaging brands. Target India's domestic manufacturing incentive environment where PLI scheme support and BIS certification pressures on imports create white-space for local compounder-molders. Pursue direct-to-brand distribution channels via e-procurement platforms disintermediating traditional regional distributors in France and Italy. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounder-molders with in-house ceramic-injection capabilities serving high-temperature adhesive segments in automotive refinishing and aerospace maintenance. Long-term viability over the next decade hinges on regulatory chemistry adaptation velocity rather than scale alone. Watch ECHA guidance publication timelines as the inflection signal for requalification contract flow concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polymer Formulation | Secures thermoplastic elastomer supply against European compounder concentration risk. |
| Ceramic-Injection Capacity Expansion | Captures specification shifts in automotive refinishing and aerospace maintenance coatings. |
| Biopolymer Grade Certification Investment | Enables premium positioning for petroleum-free closure systems in EU cosmetic packaging. |
| Direct-to-Brand E-Procurement Platform Launch | Disintermediates traditional distributors for mid-volume French and Italian cosmetics manufacturers. |
| India Captive Supply Arrangement | Aligns with PLI scheme incentives and BIS certification pressures on imported brush caps. |
Research Methodology
Cross-validation between primary interviews with brush cap procurement managers at multinational beauty brands and secondary analysis of ECHA REACH substance restriction filings anchors the qualitative findings. Plant managers at German injection molding clusters, regulatory affairs leads at specialty chemical compounders, and category buyers at French prestige cosmetics houses provided operational perspective. Secondary validation drew from customs trade data, SEC filings of listed packaging companies, and SAMR cosmetic safety standard publications. Bottom-up volume modeling triangulated against top-down value estimates across product type, material grade, and application segments.
Sensitivity analysis tested forecast robustness across alternative PFAS phase-out timeline scenarios and ceramic-injection adoption curve assumptions. The analytical framework spans screw caps, dispensing caps, flip caps, and snap caps by plastic, metal, glass, and rubber materials across cosmetics, paints, adhesives, and inks applications. CAGRs were derived from regression-based trending of procurement volume indicators against macroeconomic drivers. Key inputs included filament bundle precision tolerance specifications and multi-cavity mold qualification timeline data from FDA and EMA cosmetic contact certification records.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity and stable polymer resin feedstock pricing would require recalibration. Forecasts reflect documented assumptions regarding regulatory chemistry transition pace and industrial coatings expansion trajectory. Practitioners should keep alternative scenarios live as ECHA Annex XVII amendment schedules and EPA state-level PFAS rulemakings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Europe Metal Caps and Closures Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Metal Closures Market
Caps and Closures
India Plastic Caps and Closures Market
Caps and Closures
Drum Plugs Market