
 Steel Ring Pull Caps Market | 2026-2036
Steel Ring Pull Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Ring Pull Caps Market Analytics
Asset-light leasing models for high-speed capping equipment are rewriting competitive entry barriers across the steel ring pull caps supply base. Crown Holdings leverages captive steel supply and integrated printing operations to sustain margin control across beverage contracts. Ball Corporation anchors North American volume through long-term supply agreements with major brewing groups. Silgan Holdings differentiates via specialized coatings that extend shelf stability for acidic beverages.
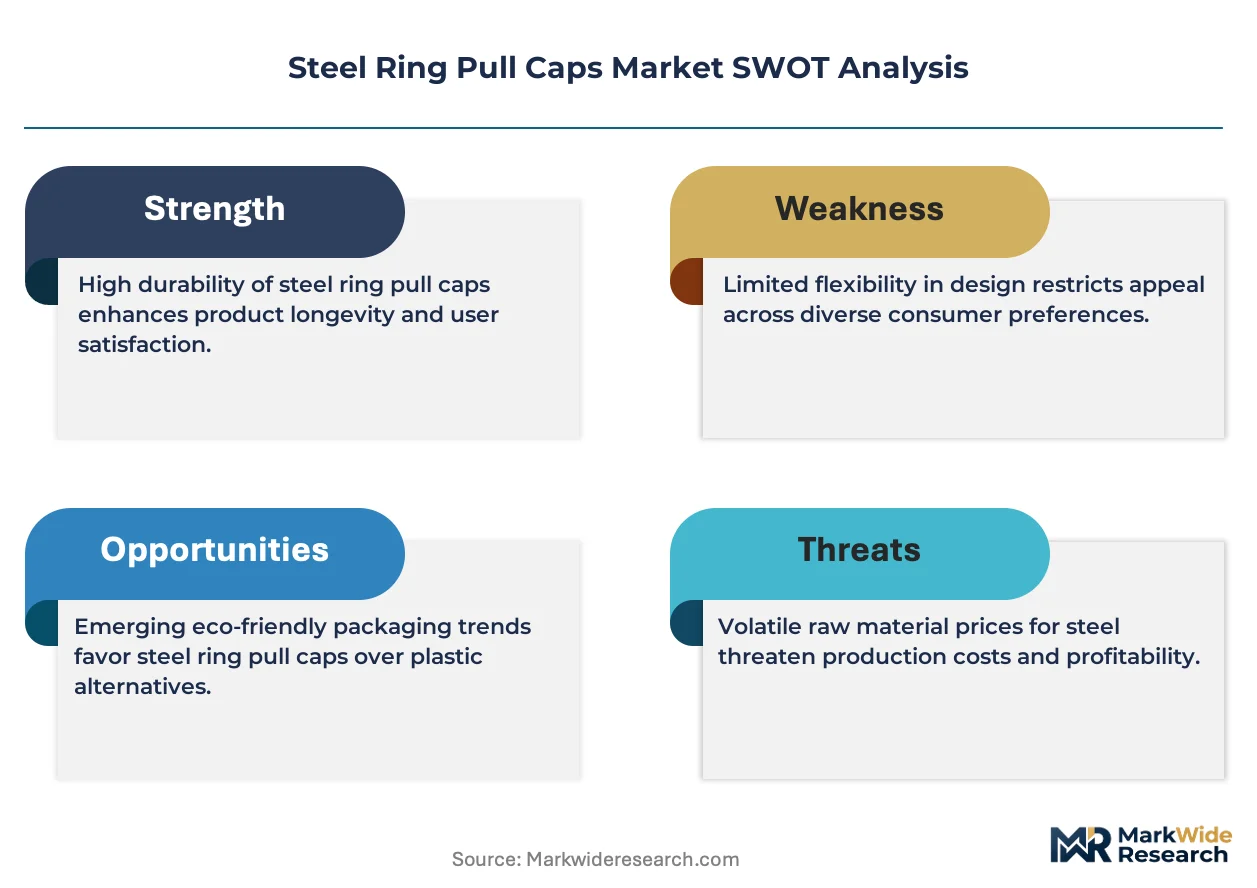
Steel ring pull caps are single-use metal closures formed from tinplate or chrome-coated steel, typically specified with 0.20–0.28 mm wall thickness and scored tear panels that fracture under 15–25 N pull force to enable tool-free container opening. The beverage industry segment dominates volume as carbonated soft drink and beer canning lines standardize on 202- and 206-diameter end specifications. Eco-friendly packaging variants within the steel category are gaining fastest, driven by extended producer responsibility mandates that penalize non-recyclable closure systems. Composite material segments remain niche, constrained by higher unit costs and limited compatibility with existing seaming equipment.
FDA food-contact substance regulations and EPA hazardous air pollutant standards for metal coating operations constrain domestic U.S. manufacturing configurations. China's SAMR enforces GB 4806.9 migration limits that disqualify non-compliant offshore suppliers from branded food contracts. The EU Packaging and Packaging Waste Regulation tightens recyclability thresholds that favor mono-material steel closures over multi-layer alternatives. Stakeholders must monitor how divergent national extended producer responsibility schemes reshape total cost of ownership calculations across their closure sourcing portfolios.
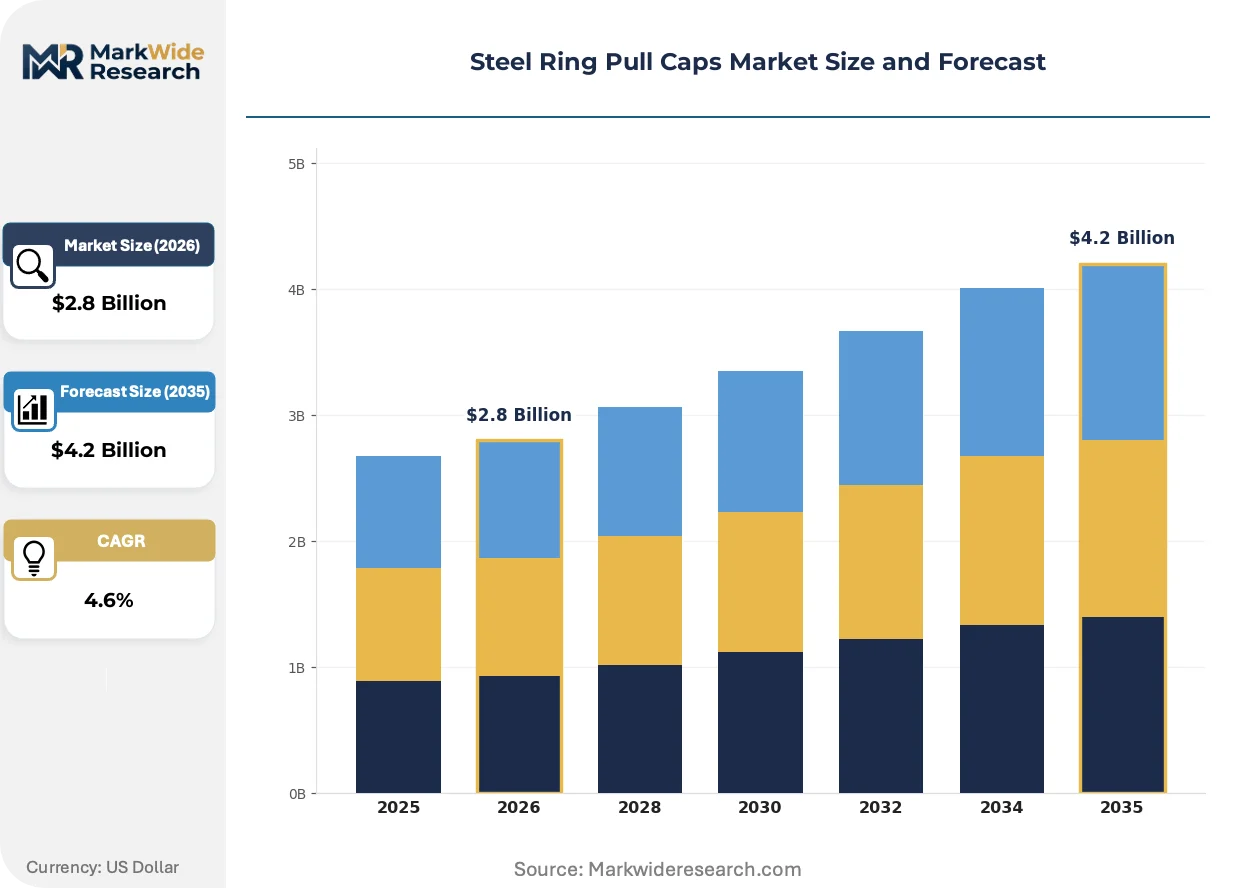
Market Dynamics
Extended producer responsibility mandates across multiple jurisdictions are forcing beverage packagers to abandon composite closures in favor of mono-material steel ring pull systems, compressing supplier qualification timelines and reshaping capital allocation across the closure supply base.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability thresholds favor steel closures over multi-layer alternatives, accelerating conversion of legacy seaming lines across German and Italian canning facilities.
- Aluminum canning line conversions:Southeast Asian contract packagers in Vietnam and Thailand are retrofitting glass bottling infrastructure to handle 202-diameter steel ends for ready-to-drink portfolios.
- Chrome-coated steel specification:Migration toward 0.22 mm chrome-coated substrates reduces tinplate dependency while maintaining scored panel integrity under 20 N pull force.
Market Restraints
- Tinplate price volatility:Raw material swings for electrolytic tinplate constrain margin stability for mid-tier closure manufacturers without captive steel supply.
- GB 4806.9 compliance barriers:China's SAMR migration limits disqualify offshore suppliers lacking certified food-contact metal packaging testing protocols.
- Polymer tab substitutes:Injection-molded plastic stay-on-tab designs threaten steel ring pull share in non-carbonated beverage segments where pull force requirements relax.
Strategic Opportunities
- India beverage canning infrastructure:Underpenetrated aluminum can lines present first-mover advantage for steel end suppliers qualifying under BIS food-contact standards.
- Asset-light equipment leasing:High-speed capping machinery rental models lower entry barriers for regional packagers in Indonesia and Philippines.
- Acidic beverage coating specialization:Epoxy-phenolic and vinyl-organosol formulations that extend shelf stability for energy drinks and sparkling waters command specification premiums.
Industry Challenges
- Seaming technician scarcity:Double-seam integrity validation requires specialized operators, creating bottlenecks as conversion demand outpaces vocational training output.
- Coating line capex intensity:FDA-compliant food-contact coating operations demand EPA hazardous air pollutant abatement systems that strain mid-capitalization supplier balance sheets.
- Cross-border certification timelines:Dual qualification for FDA food-contact substance notifications and EU REACH compliance extends new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Ring Pull Caps Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Plastic, Composite End User: Beverage Industry, Food Industry, Household Products, Industrial Applications Distribution Channel: Retail, Wholesale, Online, Direct Sales Packaging Type: Bulk Packaging, Individual Packaging, Customized Packaging, Eco-friendly Packaging |
| Companies Covered | Crown Holdings Inc., Ball Corporation, Ardagh Group S.A., Silgan Holdings Inc., Amcor plc, Guala Closures S.p.A, Sonoco Products Company, Nippon Closures Co., Ltd., Jiangsu Changjiang Lids Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Ring Pull Caps Market Evolving Landscape
Digital printing integration and scored-panel metallurgy advances are compressing batch size economics while regulatory divergence between major economies forces parallel compliance architectures.
Laser-scored tear panel technology is collapsing the minimum viable production run for customized steel ring pull caps. Regional craft breweries in the United States and specialty beverage startups in Brazil are adopting digitally printed 206-diameter ends at sub-50,000 unit batches. This capability is collapsing the volume threshold that previously locked small brands into generic stock designs.
REACH SVHC disclosure requirements and EU Green Deal packaging targets are tightening material traceability obligations. Steel closure suppliers must now document alloy composition and coating chemistry through the value chain. German beverage canners and French mineral water bottlers face the steepest compliance ramps as they phase multi-material laminates ahead of 2030 recyclability mandates.
Beverage brand technical buyers are consolidating supplier relationships around full-service closure-system partners capable of integrated printing, coating, and seaming support. This pattern displaces fragmented sourcing of ends, tabs, and liners from separate vendors. The shift is most visible among North American brewing groups and Mexican contract packagers serving export markets.
Steel Ring Pull Caps Market Segmentation
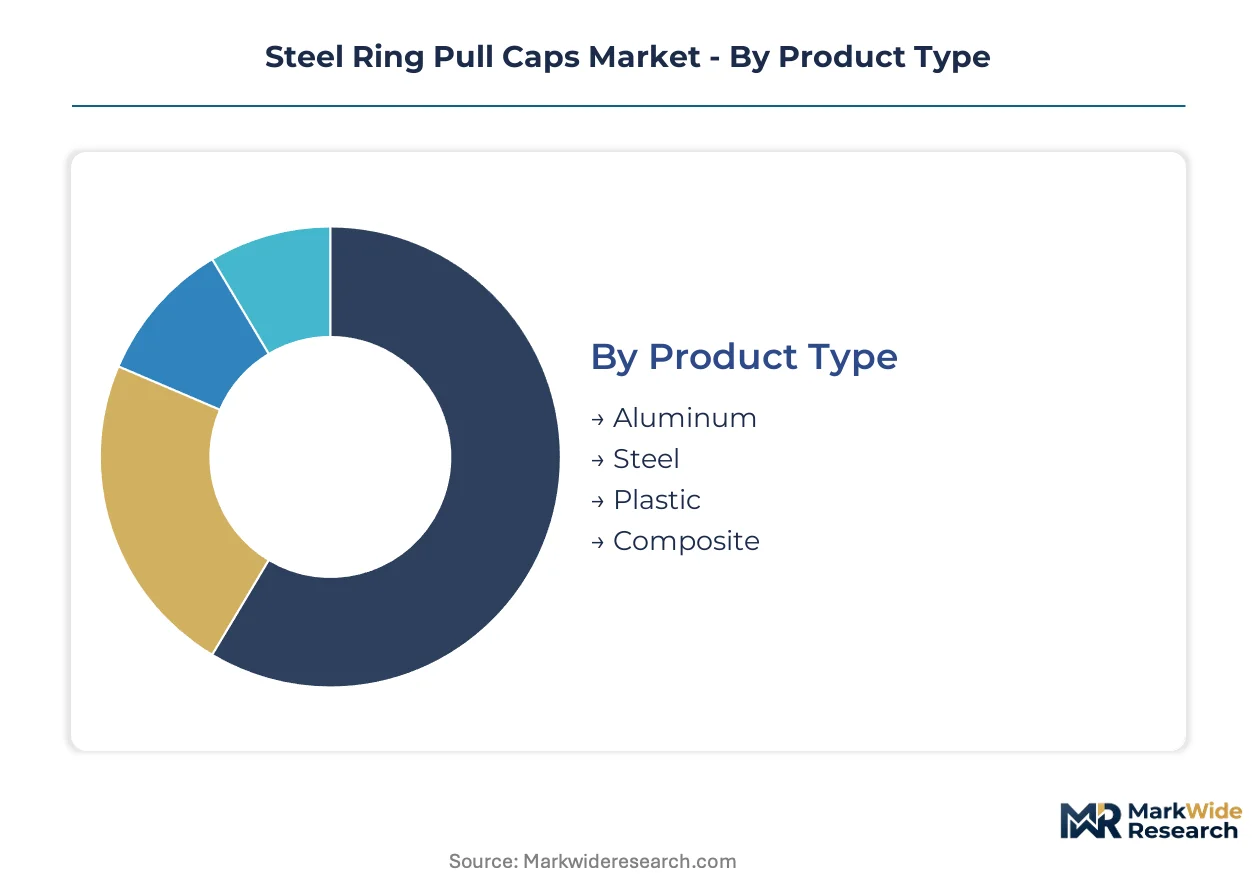
Steel ring pull caps demand fragments across material specifications, end-use requirements, and channel economics. Each dimension carries distinct qualification protocols and margin structures that reshape supplier prioritization.
Product Type:
Chrome-coated steel specifications turn inventory fastest in Southeast Asian canning clusters, while composite alternatives face extended certification cycles in regulated markets.
- Aluminum:Drawn from 3104-H19 alloy with 0.265 mm typical gauge, aluminum ends dominate North American craft brewing where 202-diameter specifications standardize across mobile canning operations. Mexican contract packagers favor aluminum for export-bound sparkling water portfolios subject to FDA food-contact substance notifications.
- Steel: Tinplate and chrome-coated variants specified at 0.20–0.28 mm wall thickness with scored tear panels calibrated to 15–25 N fracture force. German beverage canners and Italian mineral water bottlers are converting legacy lines to steel as EU Packaging and Packaging Waste Regulation recyclability thresholds phase out multi-layer alternatives.
- Plastic: Injection-molded stay-on-tab designs in polypropylene and polyethylene terephthalate blends serve non-carbonated segments where pull force requirements relax below 10 N.
- Composite: Multi-material laminates combining steel substrates with polymer barrier layers face disqualification under extended producer responsibility mandates in France and Germany.
Steel dominates installed base. Aluminum is where expansion concentrates.
End User:
Volume concentration varies sharply by sector, with beverage procurement cycles running 3–4x faster than industrial qualification timelines.
- Beverage Industry:Carbonated soft drink and beer canning lines specify 202- and 206-diameter ends as standard, with double-seam integrity validation requiring specialized technicians. China's SAMR enforces GB 4806.9 migration limits that disqualify non-compliant offshore suppliers from branded contracts.
- Food Industry: Acidic and retort-stable applications demand epoxy-phenolic and vinyl-organosol coating formulations that extend shelf stability. Thailand and Vietnam contract packagers retrofitting glass bottling infrastructure prioritize food-grade steel ends for ready-to-drink and shelf-stable food portfolios.
- Household Products: Aerosol and chemical container specifications emphasize corrosion resistance over food-contact compliance, with shorter supplier qualification protocols.
- Industrial Applications: Lubricant and solvent packaging operates on annual contract cycles with limited coating specialization requirements.
Beverage commands procurement volume. Food is climbing the fastest.
Distribution Channel:
Channel selection determines minimum order thresholds and technical support intensity, with direct relationships commanding specification influence.
- Retail:Big-box beverage merchandisers consolidate closure sourcing through full-service partners capable of integrated printing, coating, and seaming support.
- Wholesale: Regional distributors in Indonesia and Philippines access high-speed capping equipment through asset-light leasing models that lower entry barriers.
- Online: Digital procurement platforms serve specialty beverage startups in Brazil and craft breweries in the United States with sub-50,000 unit batch capabilities via laser-scored tear panel technology.
- Direct Sales: Long-term supply agreements anchor North American brewing group procurement, with technical buyers consolidating around single-source closure-system partners.
Direct sales lock strategic accounts. Online is gaining share fastest.
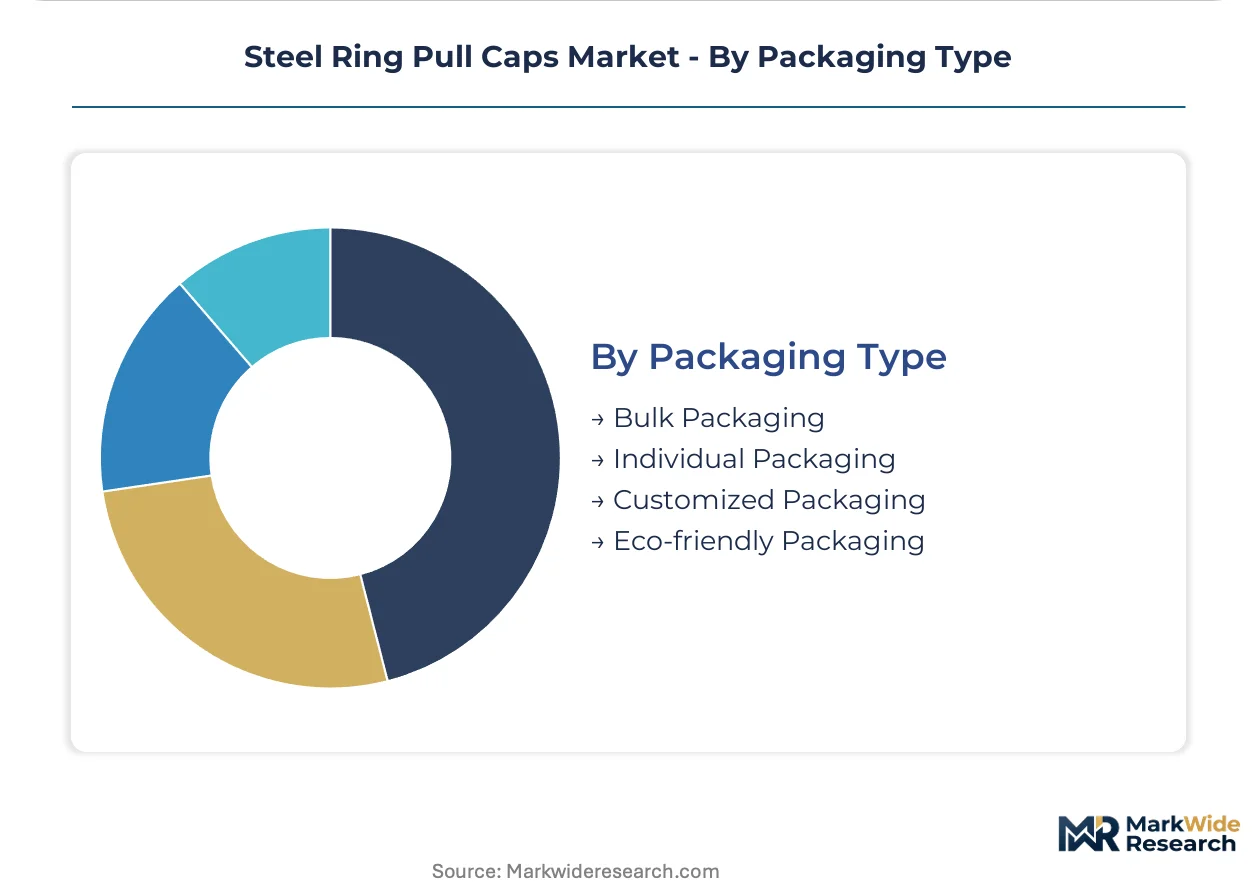
Packaging Type:
Eco-friendly variants carry premium positioning while bulk formats optimize logistics cost for high-volume canners.
- Bulk Packaging:Palletized loose ends and tab-less shells ship to integrated can manufacturing facilities where seaming occurs in-line with filling operations.
- Individual Packaging: Pre-seamed caps for specialty and promotional runs support craft brewery customization demands with shorter lead times.
- Customized Packaging: Digitally printed 206-diameter ends enable regional brand differentiation at batch sizes previously locked out of custom design economics.
- Eco-friendly Packaging: Mono-material steel closures with documented alloy composition and coating chemistry satisfy EU Green Deal packaging targets and REACH SVHC disclosure requirements for German and French bottlers phasing multi-material laminates.
Bulk packaging dominates shipment volume. Eco-friendly is where specification premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility mandates are accelerating steel ring pull adoption across diverse manufacturing clusters. Regulatory divergence between economies is forcing parallel compliance architectures as beverage brands consolidate supplier relationships.
China
Carbonated soft drink canning lines in Guangdong and Zhejiang provinces are converting to 202-diameter steel ends for ready-to-drink portfolios. SAMR enforces GB 4806.9 migration limits that disqualify non-compliant offshore suppliers from branded food contracts. The Yangtze River Delta manufacturing corridor hosts contract packagers retrofitting glass bottling infrastructure to aluminum canning systems.
Germany
Beverage canners in Bavaria and North Rhine-Westphalia face steep compliance ramps under EU Green Deal packaging targets phasing multi-material laminates ahead of 2030. ECHA REACH SVHC disclosure requirements tighten material traceability obligations through the steel closure value chain. The Baden-Württemberg industrial cluster concentrates coating specialization operations for acidic beverage applications.
United States
Craft breweries across the Pacific Northwest and Mountain West regions are adopting laser-scored tear panel technology for sub-50,000 unit customized batches. FDA food-contact substance notifications and EPA hazardous air pollutant standards constrain domestic coating operation configurations. Mobile canning operations in Colorado and Oregon standardize on 202-diameter specifications across regional brewing groups.
Vietnam
Contract packagers in the Red River Delta and Mekong Delta regions are retrofitting glass bottling lines to handle 202-diameter steel ends for export-bound beverage portfolios. Asset-light leasing models for high-speed capping equipment lower entry barriers for regional manufacturers. Ho Chi Minh City industrial zones concentrate seaming technician training programs as conversion demand accelerates.
Brazil
Specialty beverage startups in São Paulo and Minas Gerais are leveraging digital printing integration for customized 206-diameter ends at reduced batch thresholds. ANVISA food-contact regulations govern import qualification protocols for steel closure systems. The Campinas manufacturing cluster anchors coating formulation capabilities for extended shelf stability in tropical climate distribution.
Steel Ring Pull Caps Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base clusters around three strategic archetypes: integrated metal packaging conglomerates with captive steel supply, specialized coating formulators serving acidic beverage niches, and regional fabricators leveraging asset-light equipment leasing. Dominant competitive moves include backward integration into substrate production and geographic expansion through long-term supply agreements with brewing groups.
Within the integrated packaging tier, Crown Holdings Inc. and Ball Corporation exemplify scale-driven archetypes with North American volume concentration. Silgan Holdings Inc. occupies a position among coating-specialist players differentiated through shelf stability formulations. Among Asia-Pacific fabricators, Jiangsu Changjiang Lids Co., Ltd. represents regional manufacturing archetypes serving conversion demand in Southeast Asian canning clusters. These three anchors illustrate how supplier consolidation around full-service closure-system partnerships displaces fragmented sourcing patterns across beverage procurement functions.
| Leading Market Players |
|---|
| Crown Holdings Inc. |
| Ball Corporation |
| Ardagh Group S.A. |
| Silgan Holdings Inc. |
| Amcor plc |
| Guala Closures S.p.A |
| Sonoco Products Company |
| Nippon Closures Co., Ltd. |
| Jiangsu Changjiang Lids Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese tinplate rolling mills is compressing substrate pricing and forcing integrated suppliers to absorb coating line capital intensity through longer contract tenors with beverage canners.
Pricing Analysis
Certification level creates the primary spread across steel ring pull cap quotations, with FDA food-contact substance notification tiers commanding substantial premiums over standard industrial grades. Three-tier pricing structure across premium, standard, and economy levels reflects pull-force calibration precision and coating formulation complexity. Cost compression in mid-tier chrome-coated specifications is intensifying because Southeast Asian contract packagers are consolidating purchase volumes through direct mill relationships. Private-label beverage brands exhibit highest price sensitivity, while multinational brewing groups prioritize seaming reliability over unit cost.
Supply Chain Analysis
Tariff exposure between China and major beverage export destinations dominates supply chain risk assessment for steel substrate sourcing. Production gravity centers on China, Germany, and the United States for integrated closure manufacturing, with Vietnam and Thailand emerging as canning line conversion hubs. Raw material flows draw from electrolytic tinplate producers in East Asia, chrome-coated steel specialists in Europe, and epoxy-phenolic resin formulators serving acidic beverage applications. Distribution runs through direct long-term supply agreements with brewing groups, supplemented by regional distributor networks for specialty beverage startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel ring pull cap incumbents face sustained substitution pressure from injection-molded polymer stay-on-tab designs in non-carbonated segments where pull force requirements relax below 10 N.
For Market Incumbents: Harden coating formulation capabilities against polymer substitute encroachment by investing in shelf stability specialization for energy drinks and sparkling waters. Deepen backward integration into chrome-coated steel substrate production to insulate margin structures from tinplate price volatility. Prioritize GB 4806.9 compliance certification to maintain access to Chinese branded beverage contracts as SAMR tightens migration limits.
For New Entrants and Emerging Players: Build out asset-light equipment leasing capabilities targeting Indonesian and Philippine contract packagers converting glass bottling infrastructure. Concentrate initial qualification efforts on India's underpenetrated aluminum canning lines where BIS food-contact standards create first-mover positioning. Pursue digital printing integration partnerships to serve craft brewery sub-50,000 unit batch demands without legacy seaming line capital burden.
For Investors and Strategic Acquirers: Capital is best deployed toward coating-specialist fabricators with documented EU REACH SVHC traceability systems and established relationships with German beverage canners phasing multi-material laminates. Monitor ECHA regulatory disclosure timelines as inflection indicators for accelerated consolidation around full-service closure-system partners capable of integrated printing, coating, and seaming support.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive chrome-coated steel supply insulates Crown Holdings from raw material volatility. |
| Coating Specialization for Acidic Beverages | Epoxy-phenolic formulations enable Silgan Holdings to command specification premiums. |
| Asset-Light Equipment Leasing Models | Machinery rental lowers entry barriers for Vietnamese contract packagers converting lines. |
| Digital Printing Integration | Laser-scored tear panels collapse minimum viable batch sizes for U.S. craft breweries. |
| Long-Term Supply Agreement Expansion | Ball Corporation anchors North American volume through brewing group procurement consolidation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association disclosures. Primary interviews engaged beverage procurement directors, seaming equipment manufacturers, coating formulation chemists, and contract packaging executives across Southeast Asian conversion clusters. Secondary validation drew from SAMR GB standard publications, EPA hazardous air pollutant enforcement records, ECHA REACH SVHC candidate lists, and beverage canner capital expenditure disclosures. Bottom-up volume modeling triangulated against top-down market sizing across material specifications and end-use segments.
Forecast inputs incorporate installed canning line capacity, conversion timelines from glass to aluminum systems, and regulatory phase-out schedules for multi-material laminates. Segmentation dimensions span material substrate type, coating chemistry, end-use application, and regional manufacturing cluster. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends across certification tiers. Industry-specific inputs include seaming technician training program output and EPA coating line abatement system deployment rates.
Sensitivities concentrate around tinplate price volatility, Chinese regulatory enforcement intensity, and polymer substitute penetration rates in still beverage categories. Forecasts reflect assumptions regarding extended producer responsibility mandate implementation timelines and recyclability threshold harmonization across EU member states. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Metal Closures Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Cap Seals Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Buttress Closures Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Tear Tab Cap Market