
 Injection Well Market | 2026-2036
Injection Well Market Size, Share, and Industry Trends Forecast 2026-2036
Injection Well Market Insights
Petroleum engineering talent is collapsing across the North American oil patch as universities shutter upstream programs and veteran geologists retire. Baker Hughes leverages its integrated well construction portfolio to capture turnkey injection projects from operators lacking in-house expertise. Schlumberger anchors global demand through its digital subsurface platforms that optimize injection profiles in real time. Youngquist Brothers specializes in Florida's unique karst geology, sustaining decades of local regulatory relationships that competitors struggle to replicate.
An injection well is a bored, drilled, or driven shaft designed to deliver fluids deep below potable water aquifers into confined geological formations at pressures exceeding ambient reservoir conditions. These installations typically employ cemented steel casing with corrosion-resistant alloys rated for CO2, brine, or hydrocarbon service to prevent groundwater contamination and ensure zonal isolation. CO2 injection leads the technology segment as federal tax incentives for carbon capture drive Class VI permitting volumes. Waste disposal applications occupy mature margin pools in the Gulf Coast where salt dome formations offer proven long-term containment. Enhanced oil recovery competes fiercely for capital against pure sequestration projects as operators weigh hydrocarbon returns against carbon credit revenues.
The EPA's Underground Injection Control program governs well construction and operation standards across the United States, while Alberta's Energy Regulator imposes parallel requirements for Canadian projects. OSHA mandates govern worker exposure during drilling and completion phases, adding compliance layers that shape contractor selection and project timelines. Stakeholders must monitor how state primacy applications for Class VI authority reshape permitting timelines and capital deployment decisions.
Market Dynamics
The injection well market is compressing around regulatory velocity as EPA Class VI primacy applications outpace permitting capacity, forcing operators to pre-position capital years ahead of anticipated carbon sequestration demand. This structural bottleneck is reshaping contractor relationships and regional investment sequencing.
Growth Catalysts
- Section 45Q Tax Credits:The US Inflation Reduction Act amplifies federal incentives for permanent CO2 storage, accelerating Class VI well permitting volumes in Texas and North Dakota.
- Alberta Carbon Trunk Line:Canadian infrastructure expansion connects industrial emitters to depleted oil reservoirs, stimulating demand for new injection capacity in the Western Canadian Sedimentary Basin.
- Corrosion-Resistant Alloys:Advances in chromium-molybdenum casing materials extend well life under supercritical CO2 conditions, reducing workover frequency and improving project economics.
Market Restraints
- Cement Supply Concentration:Specialized Portland cement for zonal isolation concentrates among Gulf Coast suppliers, exposing project timelines to regional production disruptions.
- EPA Primacy Delays:State-level assumption of Class VI enforcement authority from federal regulators creates multi-year permitting backlogs in jurisdictions lacking technical staffing.
- Geological Screening Limitations:Seismic characterization uncertainty in deep saline formations elevates capital risk for pure sequestration projects relative to enhanced oil recovery alternatives.
Strategic Opportunities
- Offshore Carbon Storage:Norway's Northern Lights project and depleted North Sea oil fields offer unexploited capacity for European industrial emitters facing EU Emissions Trading System compliance costs.
- Direct Air Capture Pairing:Integration with DAC facilities creates new demand clusters in Iceland and the US Southwest where renewable energy abundance supports energy-intensive capture operations.
- Digital Twin Integration:Real-time pressure monitoring combined with machine learning is opening predictive maintenance contracts that bundle hardware and analytics.
Industry Challenges
- Petroleum Engineering Talent Collapse:University program closures and veteran retirements strain project execution capacity, forcing operators toward turnkey contractor relationships.
- Extended Certification Timelines:EPA Underground Injection Control compliance documentation requirements stretch from months to years, compressing returns on committed capital.
- Legacy Well Integrity:Abandoned oil and gas infrastructure in target formations requires expensive plugging and verification before CO2 injection permits issue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injection Well Market |
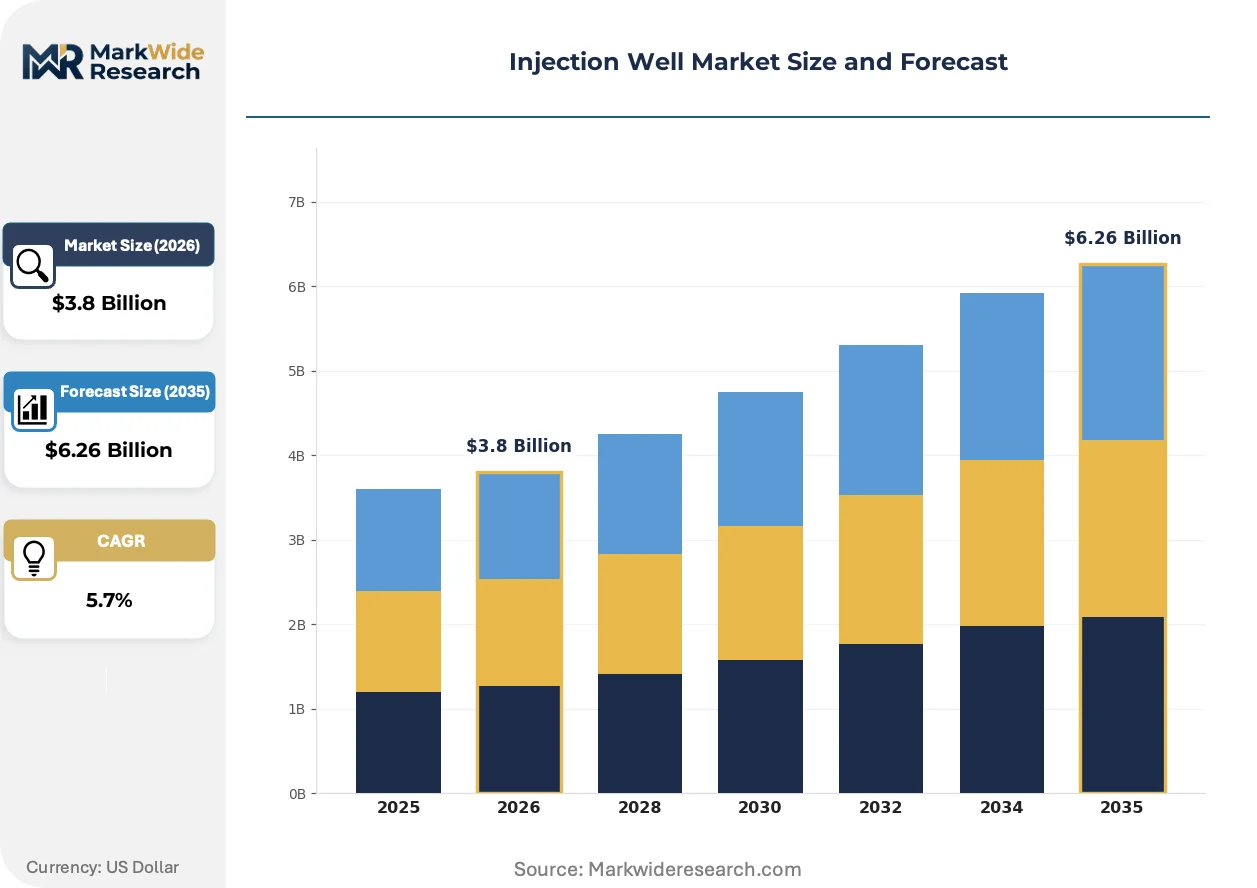
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Injection Type: Water Injection, Gas Injection, Steam Injection, CO2 Injection End User: Oil & Gas Industry, Geothermal Energy, Waste Management, Environmental Services Application: Enhanced Oil Recovery, Waste Disposal, Aquifer Recharge, Pressure Maintenance Technology: Subsurface Injection, Surface Injection, Hydraulic Fracturing, In-situ Treatment |
| Companies Covered | Youngquist Brothers, Jindal Group, SCS Engineers, Baker Hughes, Schlumberger, WSP, Weatherford, Elsing Drilling and Pump Company Inc., Advantek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injection Well Market Trends and Innovations
Digital subsurface platforms are compressing the feedback loop between injection operations and reservoir response, enabling real-time optimization that was previously impossible. This capability convergence is redrawing competitive boundaries between service companies and equipment manufacturers.
Fiber-optic distributed temperature sensing is displacing conventional pressure gauge arrays in deep monitoring wells. Operators in the Permian Basin are deploying this technology at scale to track CO2 plume migration with meter-scale resolution. The structural consequence is compressing insurance premiums and accelerating lender comfort with novel sequestration projects.
The EPA's evolving Class VI construction standards are mandating redundant mechanical barriers and continuous monitoring systems that exceed historical oilfield practice. This regulatory ratchet is elevating capital intensity for new entrants while entrenching incumbents with established compliance track records. Texas and Louisiana operators are responding by front-loading documentation investments to secure early-mover queue positions.
Integrated service contracts are consolidating discrete drilling, completion, and monitoring scopes under single-provider accountability. Majors in Alberta and North Dakota are abandoning fragmented procurement in favor of outcome-based arrangements that transfer reservoir performance risk to contractors. This shift is most visible among operators lacking in-house geology and reservoir engineering depth.
Injection Well Market Segmentation
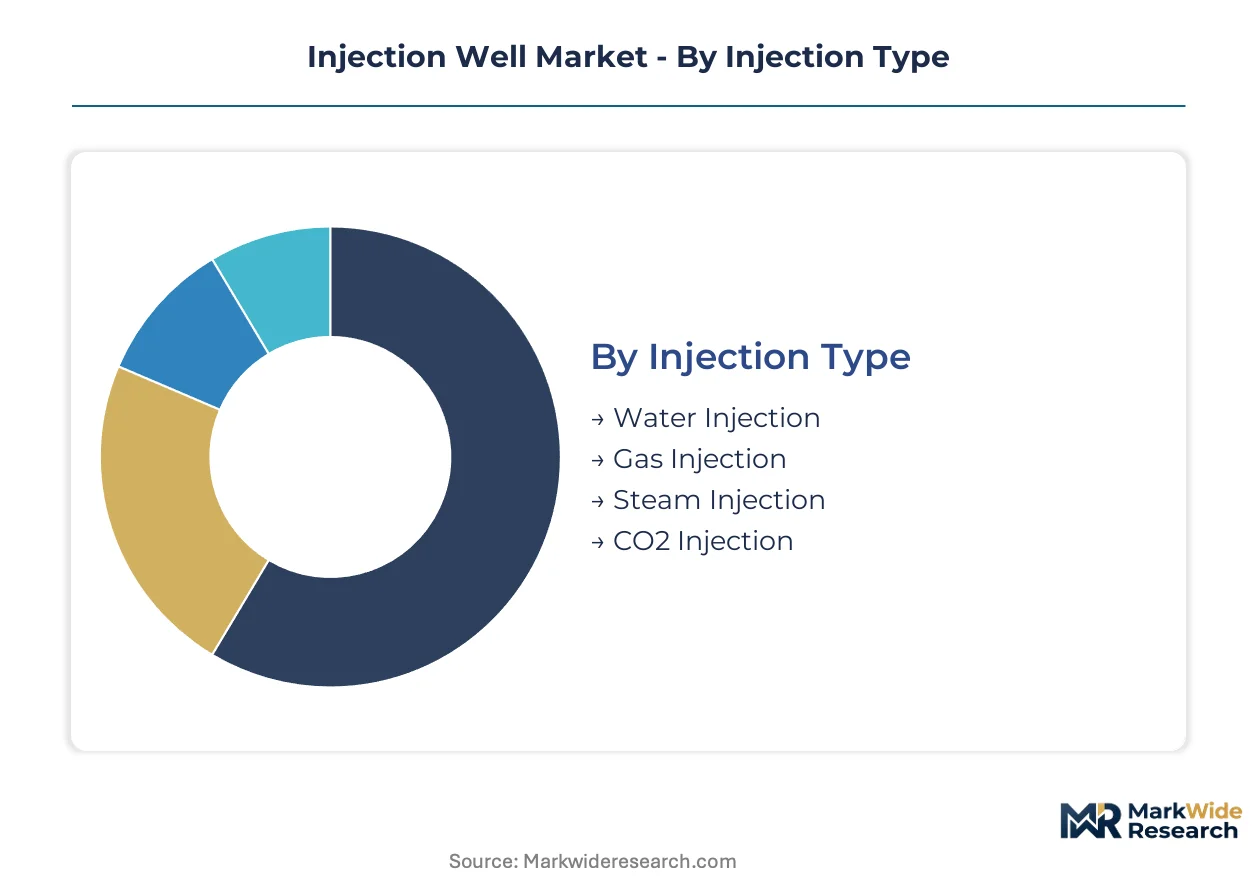
Injection well configurations vary sharply across fluid chemistry, reservoir pressure, and regulatory classification. Segment selection dictates capital intensity, permitting pathway, and contractor specialization requirements.
Injection Type:
CO2 injection faces the strongest substitution pressure as operators weigh carbon capture economics against direct air capture and nature-based offsets.
- CO2 Injection:Supercritical carbon dioxide delivery into depleted reservoirs or deep saline formations for permanent sequestration or enhanced oil recovery. Federal tax incentives under the US Inflation Reduction Act concentrate permitting activity in Texas and North Dakota where depleted formations offer proven containment.
- Gas Injection:Natural gas, nitrogen, or hydrocarbon gas injection maintains reservoir pressure and displaces crude oil toward production wells. Demand clusters in Alberta's Western Canadian Sedimentary Basin where infrastructure connects industrial gas supplies to mature oilfields.
- Water Injection:Brine or produced water reinjection supports pressure maintenance and minimizes surface discharge volumes.
- Steam Injection:Thermal EOR method heating heavy crude to reduce viscosity and improve flow characteristics.
Water injection anchors the volume base while CO2 injection gains share at the steepest rate.
End User:
Cost tier stratification separates capital-rich majors from fragmented independent operators lacking in-house engineering depth.
- Oil & Gas Industry:Upstream operators deploying injection capacity for enhanced recovery, pressure maintenance, and produced water management. Integrated majors in the Permian Basin and North Dakota pre-position capital ahead of Class VI permitting queues.
- Environmental Services:Specialized contractors managing hazardous waste injection into deep confined formations under EPA Underground Injection Control Class I permits. Gulf Coast salt dome formations host the majority of US commercial capacity.
- Waste Management:Industrial waste generators seeking permanent disposal alternatives to surface impoundments and landfills.
- Geothermal Energy:Power developers reinjecting cooled brine to sustain reservoir temperature and pressure for electricity generation.
Oil and gas operators dominate current deployment while environmental services contractors capture margin expansion from tightening surface disposal regulations.
Application:
Maturity gradients separate decades-old pressure maintenance practice from emerging pure sequestration plays.
- Enhanced Oil Recovery:Tertiary recovery method injecting fluids to mobilize residual hydrocarbons after primary and secondary production. Texas operators balance hydrocarbon returns against carbon credit revenues when selecting CO2-EOR over pure sequestration.
- Waste Disposal:Deep well injection of hazardous industrial waste into isolated geological formations. Louisiana and Texas salt domes offer proven long-term containment with minimal permeability risk.
- Pressure Maintenance:Secondary recovery technique sustaining reservoir pressure to sustain production rates and improve ultimate recovery factors.
- Aquifer Recharge:Managed replenishment of depleted groundwater resources for municipal or agricultural water supply security.
Enhanced oil recovery anchors the revenue base while waste disposal applications expand fastest under tightening surface discharge limits.
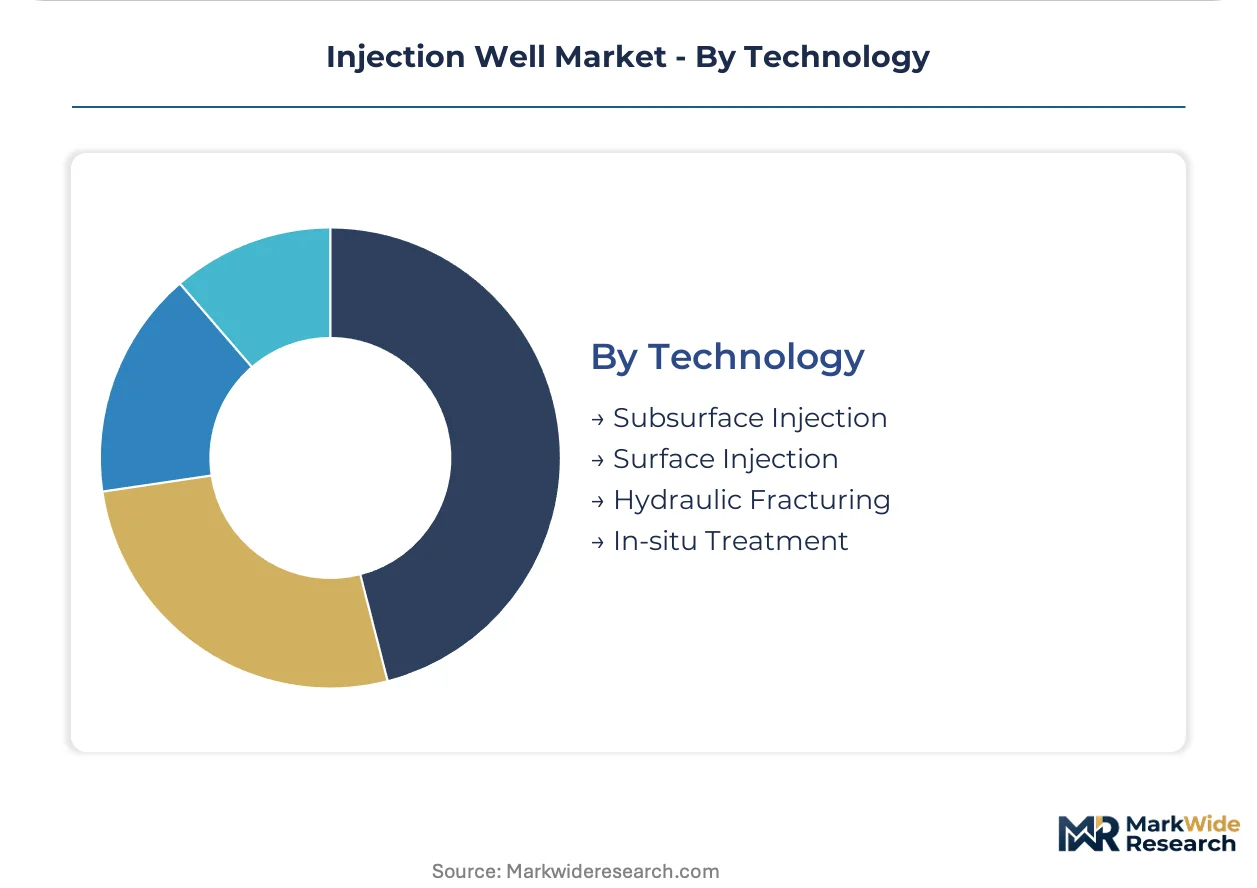
Technology:
Supply concentration in deep drilling and completion services elevates contractor power over project economics.
- Subsurface Injection:Downhole fluid delivery through completed wellbores into target formations at pressures exceeding ambient reservoir conditions. Fiber-optic distributed temperature sensing in the Permian Basin enables real-time plume tracking with meter-scale resolution.
- Hydraulic Fracturing:High-pressure fluid injection creating conductive fracture networks in low-permeability formations to enhance injectivity.
- Surface Injection:Above-ground fluid handling, pumping, and conditioning systems delivering treated fluids to wellhead injection points.
- In-situ Treatment:Downhole chemical or biological modification of target formations to improve containment or reactivity.
Subsurface injection commands the capital allocation while hydraulic fracturing applications climb fastest in unconventional reservoir development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA's Underground Injection Control program governs Class VI permitting velocity in the United States, while parallel regulatory frameworks in Canada and Europe reshape capital deployment sequencing for carbon sequestration infrastructure.
United States
Texas and North Dakota host the majority of active Class VI permitting under EPA oversight, with depleted Permian Basin reservoirs attracting pre-positioned capital from operators seeking 45Q tax credit eligibility. The EPA's primacy application backlog stretches project timelines across multiple years, compressing returns on committed capital. Houston-based service clusters dominate turnkey contractor relationships as petroleum engineering talent scarcity forces integrated outsourcing.
Canada
Alberta's Energy Regulator imposes construction standards parallel to EPA Class VI requirements, stimulating demand in the Western Canadian Sedimentary Basin where the Alberta Carbon Trunk Line connects industrial emitters to depleted oil reservoirs. Calgary operators balance enhanced oil recovery economics against pure sequestration revenues under federal carbon pricing mechanisms. Edmonton-area drilling contractors capture margin expansion from integrated service contracts.
Norway
The Northern Lights project anchors European offshore carbon storage development, with Equinor-led partnerships exploiting depleted North Sea oil fields for EU Emissions Trading System compliance. Norway's Petroleum Safety Authority mandates redundant mechanical barriers exceeding historical North Sea oilfield practice. Stavanger service clusters specialize in subsea injection architecture for saline aquifer formations.
United Kingdom
The North Sea Transition Authority licenses carbon storage sites in depleted UKCS fields, with Teesside and Humber industrial clusters driving demand for offshore injection capacity. The UK's Environmental Permitting Regulations transpose EU CCS Directive requirements into domestic law. Aberdeen contractors leverage decades of subsea expertise to capture early-mover positions in saline formation characterization.
Netherlands
Port of Rotterdam emitters face binding EU ETS reduction timelines, stimulating demand for offshore carbon storage in depleted Dutch North Sea gas fields. The country's State Supervision of Mines enforces well integrity standards matching Norwegian and UK requirements. Eindhoven-region equipment fabricators supply corrosion-resistant alloy systems for supercritical CO2 service.
Injection Well Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the injection well market. Integrated oilfield service majors anchor the premium tier through digital subsurface platforms and turnkey project accountability, while regional specialists capture margin pools in geologically complex or regulatorily opaque jurisdictions. The competitive structure separates into three archetypes: full-service global contractors, geography-bound specialists with regulatory relationships, and niche technology licensors. Consolidation pressure operates through integrated service contract awards that transfer reservoir performance risk to single providers, and through early-mover queue positioning in EPA Class VI permitting backlogs.
Among the named players in this study, Baker Hughes and Schlumberger exemplify the integrated global archetype with accountability for complete drilling-through-monitoring scope, while Youngquist Brothers occupies a position within the geography-bound specialist tier. These three companies represent distinct competitive positioning vectors: scale-driven technology integration versus regulatory relationship depth versus digital platform differentiation.
| Leading Market Players |
|---|
| Youngquist Brothers |
| Jindal Group |
| SCS Engineers |
| Baker Hughes |
| Schlumberger |
| WSP |
| Weatherford |
| Elsing Drilling and Pump Company Inc. |
| Advantek |
| Others |
Pricing and Supply Chain Analysis
Corrosion-resistant alloy substitution for conventional carbon steel casing is simultaneously shifting procurement geography toward Gulf Coast metal service centers and compressing project economics as chromium-molybdenum premiums widen against standard grades. This input transition concentrates pricing power among specialized suppliers while forcing operators to front-load material commitments.
Pricing Analysis
Texas operators face spreads against North Dakota and Alberta counterparts as Gulf Coast proximity to fabrication clusters compresses logistics premiums. Project-based contracting dominates, with price differentiation anchored in EPA Class VI certification status and turnkey scope bundling. Pricing pressure stems from cement supply concentration among regional producers, forcing margin absorption at the contractor tier. Independent operators lacking in-house engineering capacity exhibit highest price sensitivity, while integrated majors prioritize outcome-based accountability over unit cost minimization.
Supply Chain Analysis
Extended lead times for specialized Portland cement and chromium-molybdenum tubulars are stretching project timelines beyond historical norms. Supply concentrates in the United States, Canada, and Norway, with raw material dependencies spanning Gulf Coast cement production, German specialty steel mills, and Norwegian subsea equipment fabricators. Single-source vulnerability in Class VI wellhead systems creates exposure to EPA regulatory change delays. Distribution runs through integrated service contractors consolidating drilling, completion, and monitoring scopes under unified accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The injection well market is recovering through the carbon sequestration capital cycle as Section 45Q tax credit permanence sustains multi-year project backlogs.
For Market Incumbents: Consolidate around early-mover EPA Class VI queue positions in Texas and North Dakota, capturing regulatory relationship depth that new entrants cannot replicate. Deepen backward integration into corrosion-resistant alloy procurement to offset Gulf Coast supply concentration risk. Defensive moves should prioritize turnkey contract awards that transfer reservoir performance risk from operator to contractor. For New Entrants and Emerging Players: Differentiate on digital subsurface platform integration, targeting independent operators lacking in-house petroleum engineering depth. White-space sits with Direct Air Capture pairing projects in Iceland and the US Southwest where renewable energy abundance supports energy-intensive capture operations. Go-to-market positioning should emphasize real-time plume monitoring capabilities that compress insurance premiums and accelerate lender comfort. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed environmental services contractors holding Gulf Coast salt dome waste disposal capacity. Long-term viability frames around carbon pricing mechanism durability across the US, Canada, and EU jurisdictions. Acquisition targets should exhibit established EPA Underground Injection Control compliance track records. The signal to watch is state Class VI primacy approval velocity as inflection indicator for permitting capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Class VI Primacy Queue Positioning | Early EPA approval secures multi-year project backlogs before competitor permitting. |
| Corrosion-Resistant Alloy Backward Integration | In-house chromium-molybdenum sourcing insulates against Gulf Coast supply disruption. |
| Digital Twin Platform Integration | Real-time pressure monitoring bundled with predictive maintenance contracts expands recurring revenue. |
| Direct Air Capture Facility Pairing | Co-location with Iceland or US Southwest renewable energy clusters opens new demand verticals. |
| Turnkey Service Contract Consolidation | Single-provider accountability for drilling-through-monitoring scope transfers reservoir performance risk. |
Research Methodology
Desk research of EPA Underground Injection Control permit databases, state oil and gas regulatory filings, and EIA carbon storage project disclosures preceded structured interviews with drilling contractors, reservoir engineers, Class VI permit consultants, and carbon capture project developers. Primary fieldwork combined with secondary validation across EPA Class VI primacy application records, Alberta Energy Regulator construction standards, and Norwegian Petroleum Safety Authority barrier requirements. Bottom-up project pipeline enumeration triangulated against top-down carbon pricing scenario modeling.
Variance decomposition across injection type, end user, application, and technology segments shaped the analytical framework over the projection horizon. CAGRs derived from segment-level capital deployment trajectories and permitting velocity assumptions. Forecast inputs incorporated Section 45Q tax credit eligibility thresholds, EPA primacy approval timelines, and corrosion-resistant alloy cost curves.
The analysis sits within stated boundaries; outcomes outside sustained federal carbon capture incentives or accelerated state primacy approvals would require recalibration. Forecasts reflect documented assumptions regarding Class VI permitting capacity expansion and supercritical CO2 containment technology maturation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
Oilfield Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market