
 Vietnam Oil and Gas Market | 2026-2036
Vietnam Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Oil and Gas Market Outlook
Vietnam's net-zero commitment by 2050 is rebalancing investment toward gas as a transitional fuel versus coal. PetroVietnam leverages upstream dominance across the Nam Con Son and Cuu Long basins to sustain reserve replacement. PV GAS anchors the domestic gas distribution network through pipeline infrastructure and LNG terminal development. TotalEnergies competes in deepwater exploration blocks, while ExxonMobil positions its Blue Whale gas project for power sector offtake.
Vietnam oil and gas encompasses the exploration, development, production, refining, and distribution of crude oil and natural gas resources, with offshore fields typically operating at water depths of 50-200 meters in the South China Sea and requiring subsea tieback systems for marginal field economics. The sector supplies feedstock to petrochemical complexes, fuel to power generation turbines, and refined products to transportation and industrial heating applications. Exploration activity leads capital deployment as operators target pre-salt and fractured basement reservoirs, while gas processing infrastructure expands fastest to handle associated gas and LNG imports. Refining remains structurally constrained by single-train capacity at Dung Quat and Nghi Son, concentrating margin capture in import-dependent product markets.
The Ministry of Industry and Trade governs upstream licensing through Petroleum Law amendments, while the Vietnam National Oil and Gas Group operates under state-directed production sharing contract negotiations that shape foreign operator participation. Environmental standards from the Ministry of Natural Resources and Environment impose offshore discharge limits and flare gas reduction targets that elevate project compliance costs. Stakeholders must monitor licensing round timing against reserve replacement ratios and LNG import terminal commissioning schedules to align capital allocation with domestic gas demand curves.
Market Dynamics
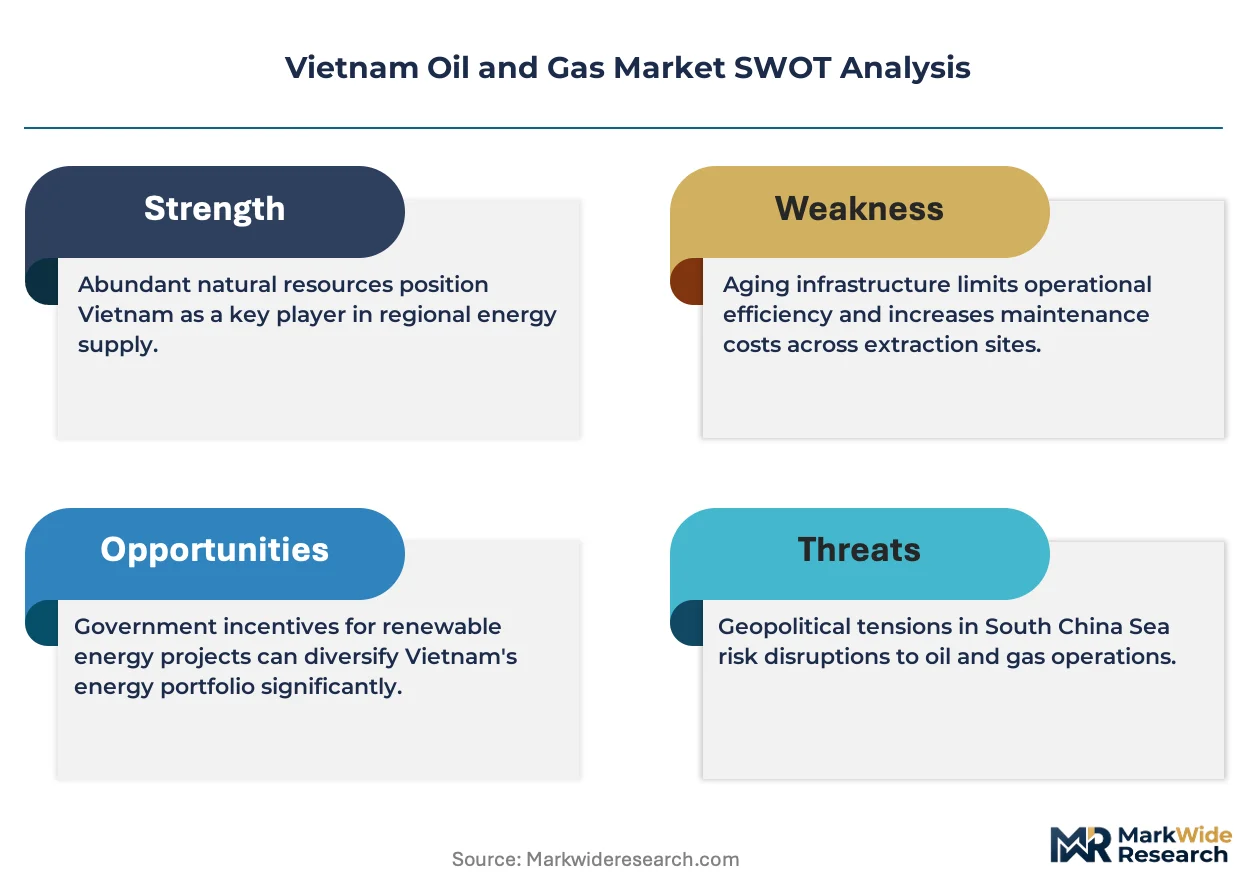
Vietnam's upstream licensing regime under the Ministry of Industry and Trade is compressing exploration timelines while power sector offtake agreements reshape gas field commercialization economics.
Growth Catalysts
- Power sector gas demand:Electricity of Vietnam's baseload expansion plans anchor long-term offtake contracts for Nam Con Son Basin production.
- Petroleum Law amendments:Revised fiscal terms under the 2023 licensing framework improve contractor economics for marginal field developments.
- LNG terminal commissioning:Thi Vai and Son My import infrastructure creates alternative supply pathways for southern industrial zones.
Market Restraints
- Reserve depletion rates:Mature Bach Ho field output decline elevates unit lifting costs across Cuu Long Basin operations.
- Equipment import dependence:Subsea hardware fabrication concentrates in Singapore and South Korean yards, exposing projects to currency volatility.
- Carbon pricing exposure:Vietnam's emerging emissions trading scheme threatens gas-fired power competitiveness against imported renewable electrons.
Strategic Opportunities
- Deepwater pre-salt targets:Unappraised Lower Miocene carbonate buildups in Phu Khanh Basin offer material reserve additions.
- Associated gas monetization:Stranded gas from heavy oil developments in Rang Dong field suits small-scale LNG or CNG distribution.
- Carbon capture retrofit:Net-zero commitments position existing gas processing facilities for blue hydrogen feedstock conversion.
Industry Challenges
- Subsea engineering capacity:Domestic fabrication yards lack saturation diving and hyperbaric welding certification for deepwater tieback installation.
- PSC negotiation timelines:State-directed production sharing contract approvals extend final investment decision cycles beyond operator hurdle rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Oil and Gas Market |
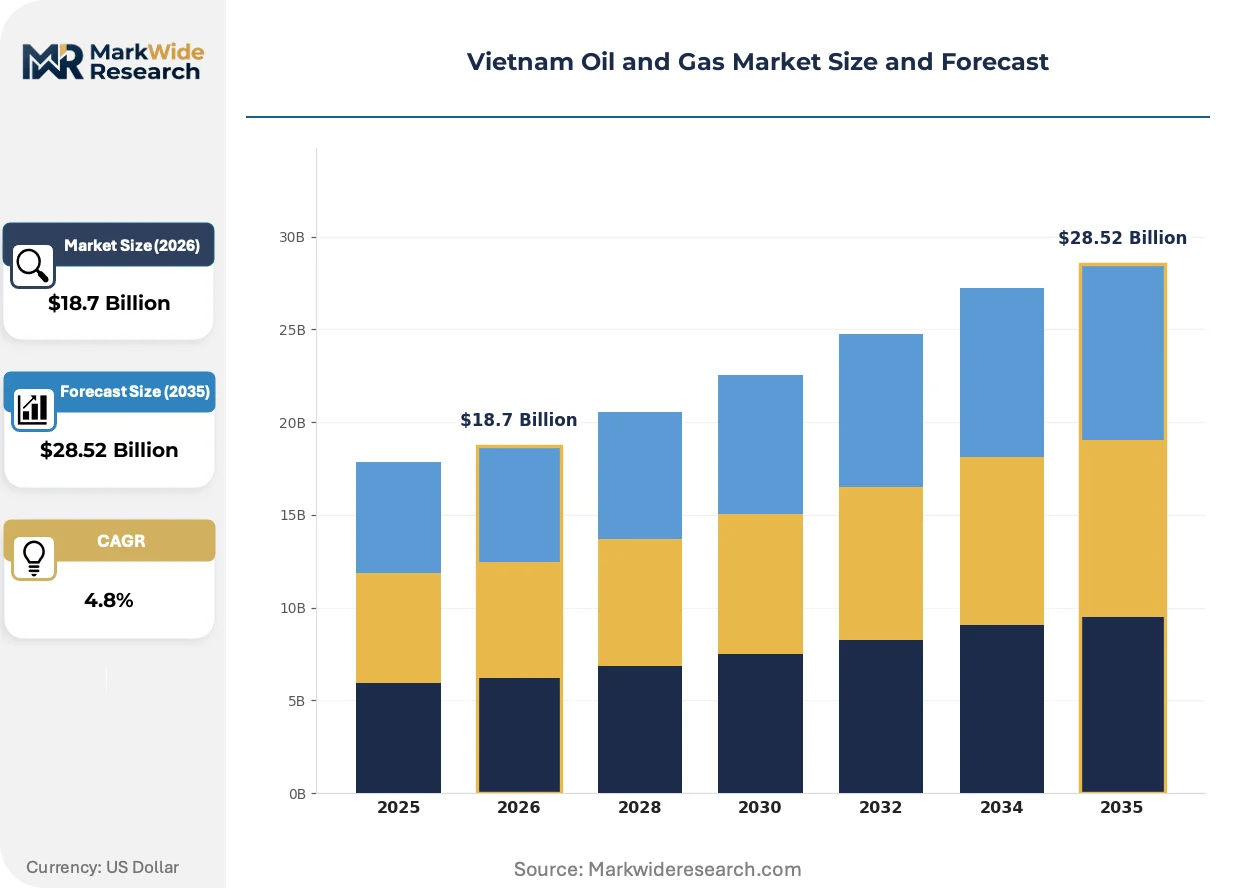
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Exploration, Production, Refining, Distribution Technology: Subsea, Enhanced Oil Recovery, Offshore Drilling, Gas Processing Application: Petrochemical, Power Generation, Transportation, Industrial Heating End User: Utilities, Manufacturing, Automotive, Offshore Operators |
| Companies Covered | Vietnam Oil and Gas Group (PetroVietnam), Vietnam National Petroleum Group (Petrolimex), PetroVietnam Gas JSC (PV GAS), PetroVietnam Oil (PVOIL), Binh Son Refining & Petrochemical (BSR), ExxonMobil Corporation, Eni SpA, Chevron Corporation, TotalEnergies SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Oil and Gas Market Strategic Shifts
Digital reservoir characterization and modular gas processing architectures are compressing development schedules while regulatory carbon accounting reshapes project financing structures.
Subsea multiphase pumping is rewriting marginal field economics by eliminating platform infrastructure requirements. PetroVietnam Technical Services Corporation deploys seabed boosting systems at water depths exceeding 150 meters across Nam Con Son assets. This technology is rewriting the minimum viable reserve threshold for standalone development, unlocking previously stranded basement reservoirs.
Vietnam's Ministry of Natural Resources and Environment enacted flare gas reduction mandates requiring 95% utilization of associated gas by 2025. This regulation forces operators to install gas gathering infrastructure at heavy oil fields previously venting or flaring. Offshore developments in Cuu Long Basin face the steepest compliance cost escalation as legacy facilities require compression and pipeline retrofit.
Power purchase agreement structures are shifting from take-or-pay to tolling arrangements with fuel price pass-through mechanisms. Independent power producers in southern Vietnam favor this model to isolate commodity exposure. This behavioral pivot concentrates credit risk assessment on offtaker balance sheets rather than reserve certification.
Vietnam Oil and Gas Market Segmentation
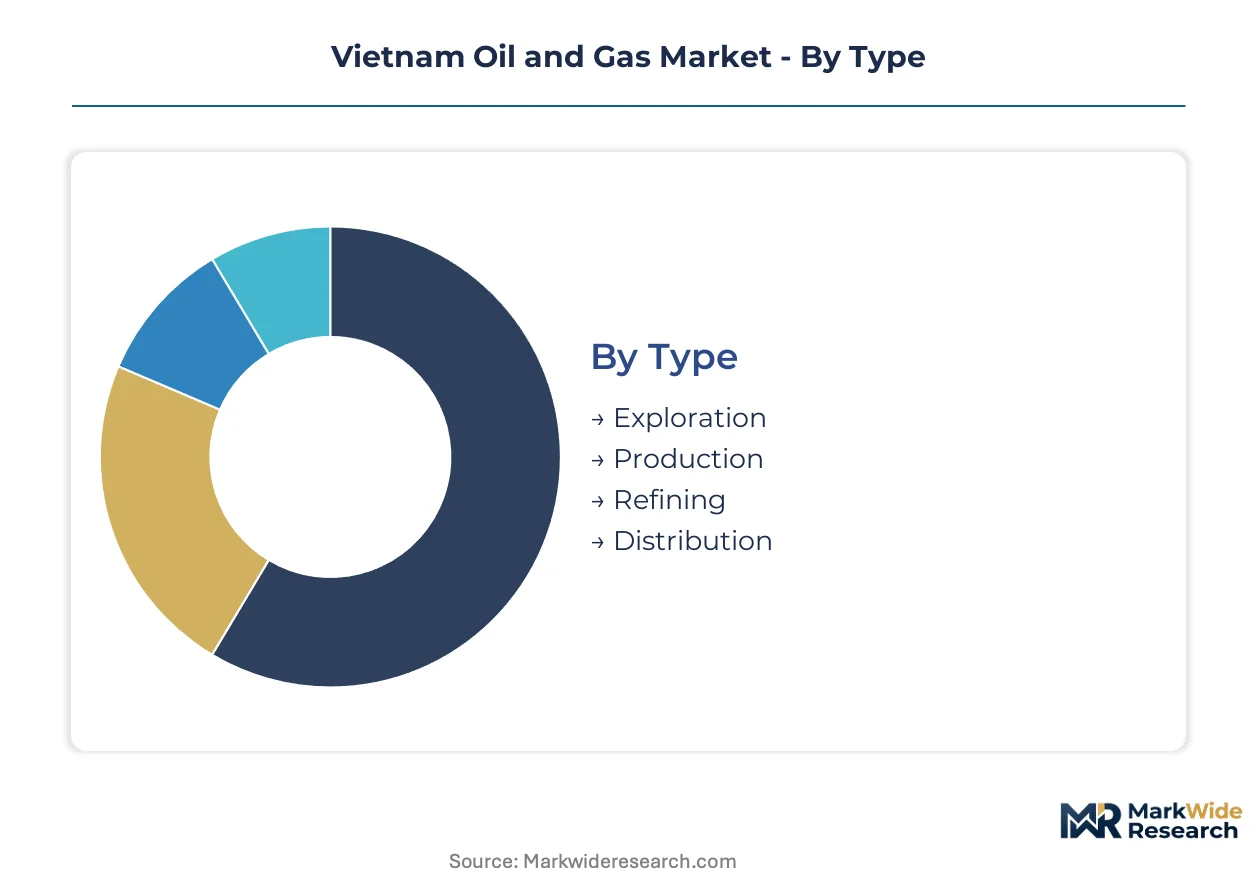
Vietnam's oil and gas segmentation reveals how capital allocation splits between upstream reserve replacement and downstream infrastructure bottlenecks. Each segment carries distinct regulatory burdens from the Ministry of Industry and Trade and the Ministry of Natural Resources and Environment.
Type:
Exploration blocks require Petroleum Law compliance and environmental impact assessments from the Ministry of Natural Resources and Environment before drilling permits issue.
- Exploration:Seismic acquisition and wildcat drilling target pre-salt carbonate buildups in Phu Khanh Basin and fractured basement reservoirs in Cuu Long Basin. Licensing round timing from the Ministry of Industry and Trade dictates capital deployment cycles for foreign operators.
- Production:Subsea tieback systems and platform infrastructure extract crude oil and associated gas from Nam Con Son and Cuu Long basin fields. Declining Bach Ho output elevates unit lifting costs and compresses reserve replacement ratios.
- Refining:Single-train capacity at Dung Quat and Nghi Son refineries constrains domestic product supply and concentrates margin capture in import-dependent markets.
- Distribution:Pipeline networks and coastal terminals move crude to refineries while product distribution serves southern industrial zones.
Leading the category by volume: Production. Expanding most quickly: Exploration.
Technology:
Technology selection determines project economics across Vietnam's 50-200 meter water depth offshore environment and mature field recovery challenges.
- Subsea:Multiphase pumping and seabed boosting systems eliminate platform infrastructure requirements for marginal fields. PetroVietnam Technical Services Corporation deploys these at depths exceeding 150 meters across Nam Con Son assets.
- Enhanced Oil Recovery:Waterflooding and gas injection programs target remaining mobile oil in Rang Dong and Bach Ho mature fields. Recovery factor improvements compete with greenfield development returns.
- Offshore Drilling:Jackup rigs and semisubmersible units drill development wells in South China Sea conditions.
- Gas Processing:Compression and treatment facilities handle associated gas from heavy oil developments and prepare LNG feedstock for Thi Vai terminal.
Dominant by capital deployment: Subsea. Steepest expansion trajectory: Gas Processing.
Application:
Application segments align with Vietnam's energy transition priorities and industrial demand centers.
- Petrochemical:Refinery naphtha and natural gas liquids feed steam crackers and aromatics complexes. Long Son and Ca Mau projects anchor demand for consistent feedstock supply.
- Power Generation:Combined-cycle gas turbines burn Nam Con Son production and Thi Vai LNG imports for Electricity of Vietnam baseload expansion.
- Transportation:Refined gasoline and diesel products move through retail networks and direct industrial sales.
- Industrial Heating:Fuel oil and natural gas supply process heat for steel, cement, and food processing plants.
Highest volume consumption: Power Generation. Gaining share fastest: Petrochemical.
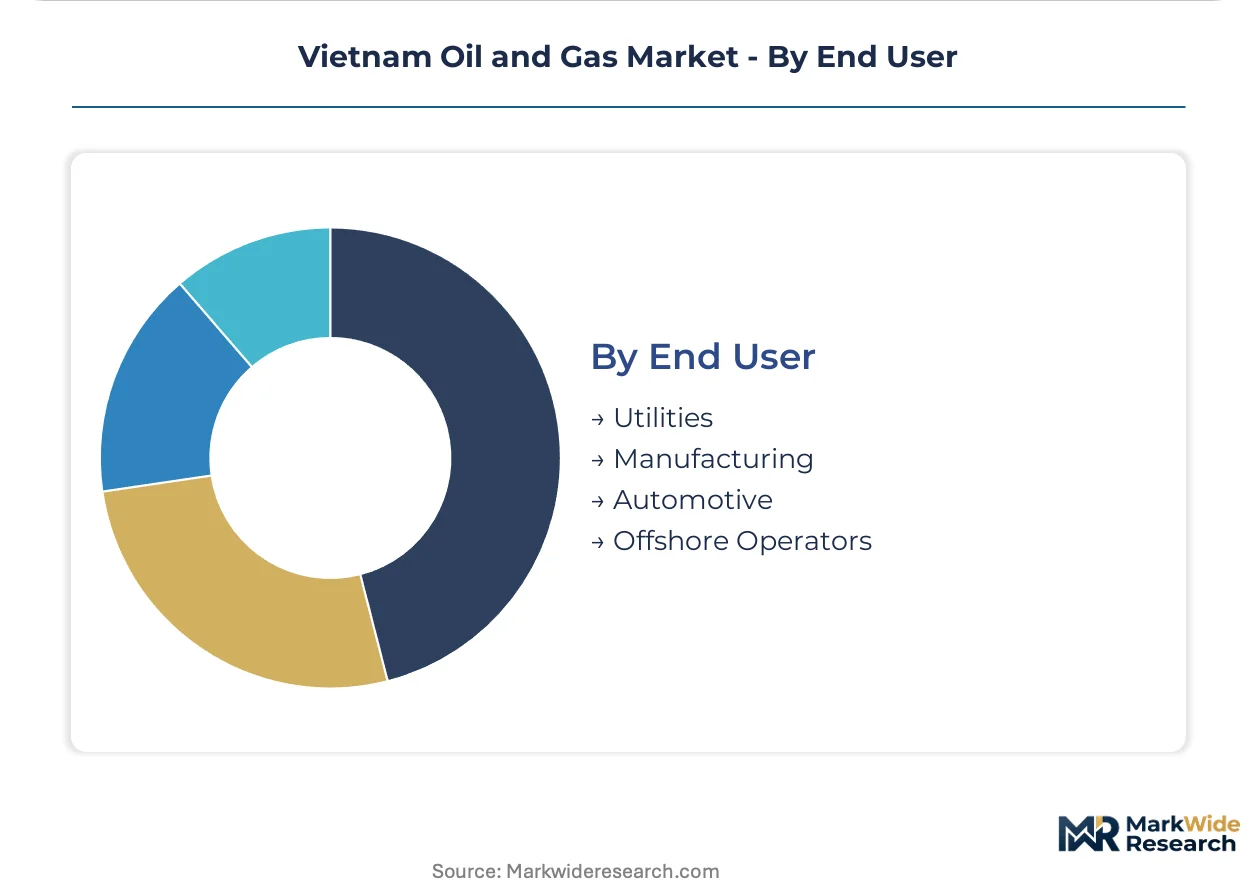
End User:
End user procurement patterns shift from long-term take-or-pay contracts toward tolling arrangements with fuel price pass-through mechanisms.
- Utilities:Electricity of Vietnam and independent power producers sign offtake agreements for gas-fired capacity expansion. Credit risk assessment now concentrates on utility balance sheets rather than reserve certification.
- Manufacturing:Steel, fertilizer, and chemical plants purchase pipeline gas and LNG for process energy.
- Automotive:Vehicle fleets and transport operators consume refined products from Nghi Son and import sources.
- Offshore Operators:International oil companies and PetroVietnam subsidiaries execute production sharing contracts and self-supply fuel for drilling campaigns.
Primary demand anchor: Utilities. Procurement evolution fastest: Offshore Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's domestic production lags consumption by a widening margin, forcing greater reliance on LNG imports and foreign-operated offshore blocks to bridge the energy security gap.
Nam Con Son Basin
Power generation clusters anchor gas demand through Electricity of Vietnam's combined-cycle turbine expansion. The Ministry of Industry and Trade governs production sharing contract renewals for mature field operators. Vung Tau port infrastructure supports offshore logistics and LNG terminal feedstock reception.
Cuu Long Basin
Heavy oil developments from Rang Dong and Bach Ho fields drive associated gas capture investments. The Ministry of Natural Resources and Environment enforces flare gas reduction mandates requiring compression retrofits. Ho Chi Minh City industrial zones absorb processed gas for manufacturing process heat.
Phu Khanh Basin
Pre-salt carbonate exploration targets remain unappraised despite seismic campaigns by international operators. The 2023 Petroleum Law amendments improved fiscal terms for deepwater block awards. Tuy Hoa coastal logistics corridors position the basin for future development staging.
Thi Vai LNG Terminal Zone
Import infrastructure expansion creates alternative supply pathways for southern manufacturing demand. The Ministry of Industry and Trade coordinates terminal commissioning with pipeline network extensions. Ba Ria-Vung Tau province hosts regasification capacity serving the densest industrial load centers.
Vietnam Oil and Gas Market Competitive Environment
The competitive structure tilts toward state-dominated upstream control with selective international participation in deepwater exploration. PetroVietnam subsidiaries anchor domestic production, refining, and distribution through vertically integrated operations. Two archetypes define the field: state-directed national oil companies executing reserve replacement strategies, and international majors leveraging technical expertise for frontier block access. Competitive moves concentrate on production sharing contract negotiation positioning and LNG terminal offtake agreement structuring.
Among state-controlled entities, Vietnam Oil and Gas Group exemplifies upstream dominance across Nam Con Son and Cuu Long basin assets. PetroVietnam Gas JSC occupies a central position in domestic gas distribution network development. Within the international operator tier, ExxonMobil Corporation represents deepwater project execution capabilities through its Blue Whale gas development positioning for power sector offtake.
| Leading Market Players |
|---|
| Vietnam Oil and Gas Group (PetroVietnam) |
| Vietnam National Petroleum Group (Petrolimex) |
| PetroVietnam Gas JSC (PV GAS) |
| PetroVietnam Oil (PVOIL) |
| Binh Son Refining & Petrochemical (BSR) |
| ExxonMobil Corporation |
| Eni SpA |
| Chevron Corporation |
| TotalEnergies SE |
| Others |
Value Chain & Pricing Dynamics
Subsea hardware fabrication costs in Singapore and South Korean yards cascade through production sharing contract economics to power sector offtake pricing, with currency volatility amplifying margin compression across Nam Con Son Basin developments. This input cost structure stratifies project returns between deepwater frontier blocks and mature field tiebacks.
Pricing Analysis
Throughput-based tolling arrangements with fuel price pass-through mechanisms anchor power sector contract structures, replacing legacy take-or-pay commitments. Pricing stratifies across reserve certification tier, offtaker credit quality, and pipeline access proximity to Thi Vai terminal infrastructure. Cost compression in mature Cuu Long Basin operations intensifies due to Bach Ho field decline elevating unit lifting expenses. State-directed utilities exhibit lowest price sensitivity given baseload mandate obligations, while independent power producers negotiate hardest on fuel cost indexation terms.
Supply Chain Analysis
Subsea multiphase pumping systems rest on Singaporean and South Korean fabrication yards for high-pressure component manufacturing. Jackup rig deployment draws from Chinese and Malaysian drilling contractors, while LNG cargo supply feeds from Qatari, Australian, and US export terminals. Single-source vulnerability concentrates in saturation diving certification capacity for deepwater installation work. Distribution runs through Vung Tau port logistics corridors and PV GAS pipeline networks to southern industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's domestic gas production capacity constraints prop long-term contract pricing power, with LNG import terminal commissioning timelines the critical bottleneck determining supply adequacy.
For Market Incumbents: Acquire stranded associated gas assets in Rang Dong and Bach Ho fields to consolidate feedstock supply for small-scale LNG distribution networks. PetroVietnam subsidiaries should deepen backward integration into subsea engineering certification capacity to reduce Singaporean yard dependence. Carbon capture retrofit positioning at existing gas processing facilities addresses emerging emissions trading scheme exposure threatening gas-fired power competitiveness. For New Entrants and Emerging Players: Digital platform routes for carbon accounting and project financing documentation offer entry points into PSC negotiation advisory services. White-space concentrates in Phu Khanh Basin exploration support services and modular gas processing equipment leasing for marginal field developments. Target independent power producer tolling contract structuring as the most penetrable commercialization function, leveraging fuel price risk management expertise. For Investors and Strategic Acquirers: Thi Vai terminal utilization rate inflection is the leading indicator that southern gas market tightness is easing, signaling import dependency saturation. Long-term viability centers on reserve replacement ratio sustainability across Nam Con Son and Cuu Long basins. Acquisition target archetype: subsea engineering specialists with Vietnamese regulatory compliance track record and PetroVietnam Technical Services Corporation partnership history.| Strategic Initiative | Industry Significance |
|---|---|
| Deepwater Block Licensing Positioning | Phu Khanh Basin pre-salt access under 2023 Petroleum Law amendments secures frontier reserve exposure. |
| LNG Terminal Capacity Expansion | Son My infrastructure commissioning diversifies supply pathways beyond Thi Vai congestion constraints. |
| Associated Gas Monetization Infrastructure | Compression retrofit investments at Cuu Long Basin heavy oil fields satisfy Ministry of Natural Resources and Environment flare reduction mandates. |
| Carbon Capture Facility Retrofit | Existing Nam Con Son gas processing plants convert to blue hydrogen feedstock production under net-zero commitments. |
| Subsea Engineering Certification Investment | Domestic saturation diving capacity reduces Singaporean fabrication yard currency volatility exposure. |
Study Parameters
Multi-period observation of reserve replacement ratios, LNG import terminal commissioning schedules, and power sector capacity expansion timelines anchored the trend analysis, supplemented by interviews with upstream project development officers, gas trading executives at PV GAS, Electricity of Vietnam planning directors, subsea engineering contractors, and Ministry of Industry and Trade licensing administrators. Secondary validation drew from Petroleum Law amendment texts, Ministry of Natural Resources and Environment discharge permits, project development databases tracking Nam Con Son and Cuu Long Basin field economics, and customs records for subsea equipment imports. Bottom-up field-level production economics triangulated against top-down sector demand projections.
Segment-weighting across exploration block awards, production asset portfolios, refining capacity utilization, and distribution infrastructure throughput shaped the analytical framework. Segmentation dimensions modeled include upstream activity type, subsea technology deployment, power generation versus petrochemical application, and utility versus manufacturing end-user procurement patterns. CAGRs derived from production decline curve analysis combined with demand elasticity estimates across the projection horizon. Forecast inputs incorporated Electricity of Vietnam baseload expansion commitments and LNG spot price volatility assumptions.
The model holds under stable Petroleum Law fiscal terms and scheduled terminal commissioning timelines; deviation in licensing round delays or carbon pricing scheme acceleration would shift reserve replacement investment incentives. Forecasts reflect stated policy assumptions regarding net-zero commitment implementation pacing and power sector fuel mix targets. A small set of named triggers—PSC negotiation timeline extensions, flare mandate enforcement severity, and regional LNG cargo competition—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Desalter Market
Oil & Gas
Coal Bed Methane Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Oil, Gas and Chemicals Software Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
Swellable Packers Market
Oil & Gas
North America Directional Drilling Services Market