
 Peru Oil and Gas Downstream Market | 2026-2036
Peru Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Peru Oil and Gas Downstream Market Analytics
Multi-source crude procurement is pivoting toward term contracts with regional Latin American suppliers as Peruvian refiners seek supply security. Petróleos del Perú SA anchors downstream operations through its Talara refinery modernization, leveraging upgraded hydrocracking units to process heavier regional crude slates. Repsol SA competes in refined product distribution through its retail network along Peru's Pan-American Highway corridor. TotalEnergies positions in LPG and lubricant segments, extending its Andean logistics footprint beyond conventional fuels.
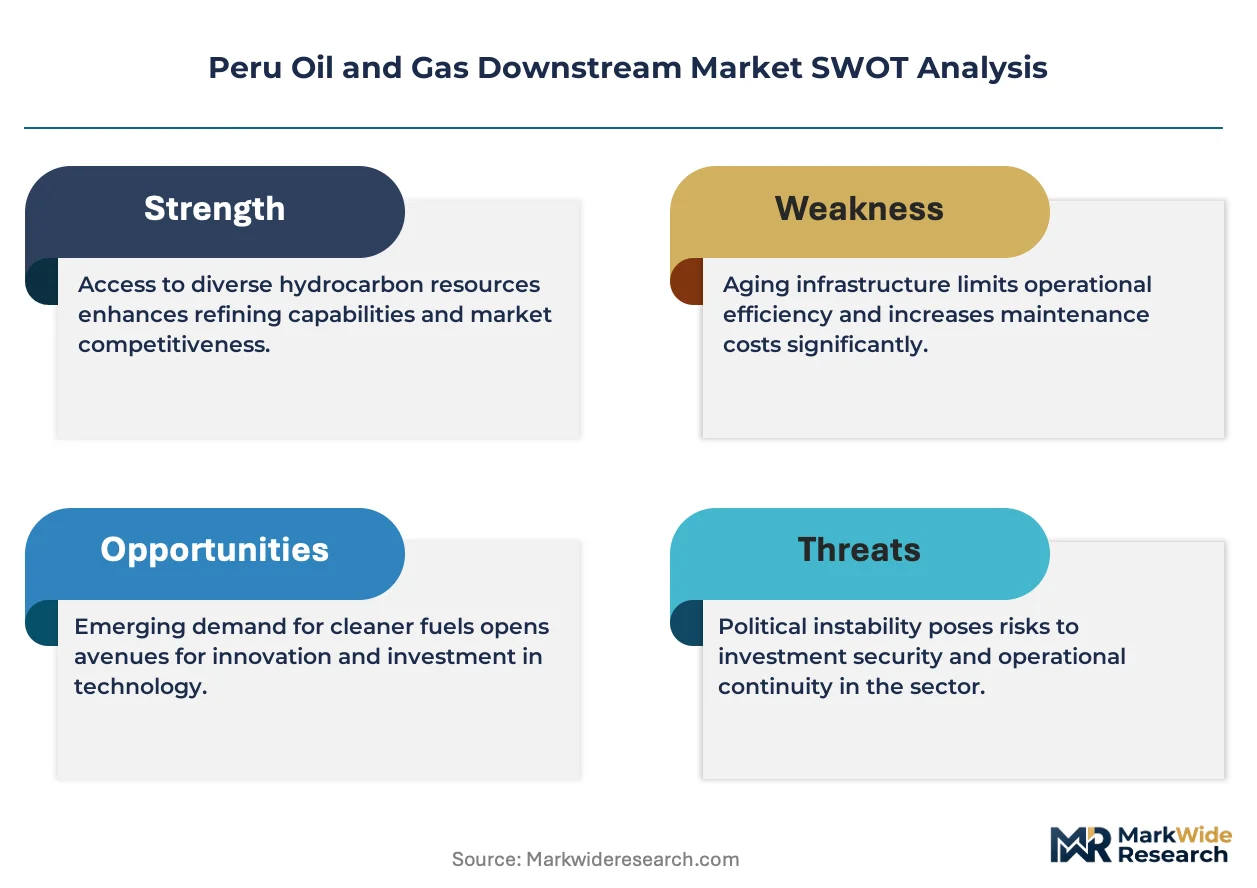
Peru oil and gas downstream encompasses refining, processing, storage, and distribution of crude oil into finished petroleum products, with refineries typically operating conversion units achieving sulfur content below 50 ppm for diesel meeting Euro V-equivalent specifications. The sector's primary purpose is transforming imported and domestic crude into transportation fuels, industrial feedstocks, and residential energy for Peru's import-dependent economy. Gasoline and diesel categories dominate product type revenue pools due to vehicle fleet expansion and mining logistics demand, while jet fuel represents the fastest-growing product segment as Jorge Chávez International Airport cargo volumes expand. Above-ground storage terminals concentrate margin capture along the Pacific coast, where import receipt infrastructure and earthquake-resistant tank farms command premium throughput fees.
Peru's hydrocarbon regulator, Organismo Supervisor de la Inversión Privada en Telecommunications (OSINERGMIN), oversees downstream pricing formulas and refinery margin transparency, while Ministry of Energy and Mines (MINEM) sets strategic reserve mandates and biofuel blending requirements. Environmental standards enforced by Peru's national environmental certification agency shape refinery emissions limits and coastal storage facility permitting timelines. Stakeholders must monitor whether pending Peru LNG integration projects and potential Pacific coast storage hub developments alter competitive access rules for independent marketers.
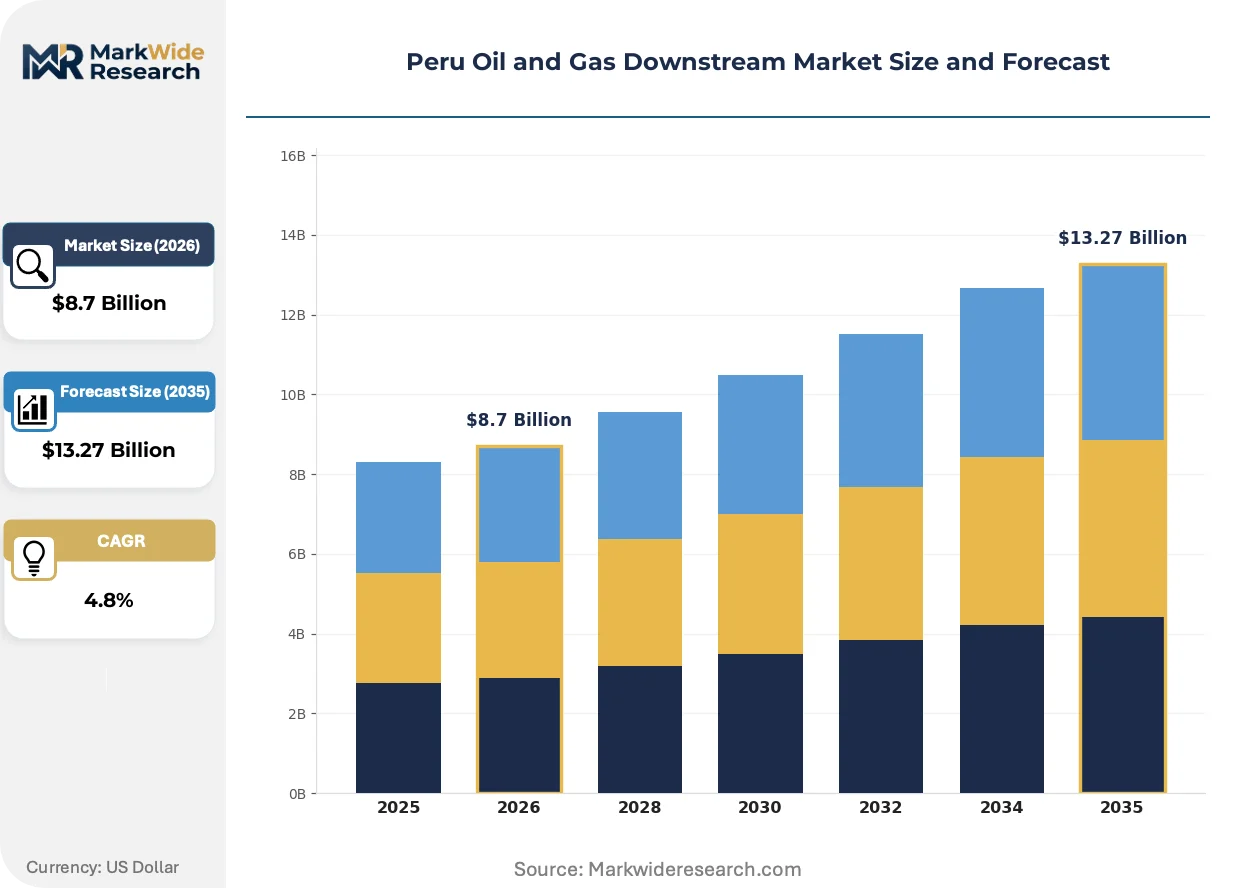
Market Dynamics
Peru's downstream hydrocarbon sector is restructuring around the Talara refinery modernization, which is converting legacy fuel oil production toward higher-yield diesel and gasoline output while absorbing heavier regional crude grades previously unsuited to domestic processing.
Growth Catalysts
- MINEM Strategic Reserve Mandates:Government-mandated inventory floors are expanding storage terminal utilization along the Pacific coast, creating throughput pull for independent logistics operators.
- Mining Logistics Demand:Copper and gold extraction operations in the Andean cordillera are consuming increasing volumes of high-sulfur diesel for haul truck fleets and power generation at remote mine sites.
- Hydrocracking Upgrades:Conversion unit installations at coastal refineries are unlocking processing flexibility for heavier Latin American crude slates previously routed to US Gulf Coast facilities.
Market Restraints
- Andean Import Dependence:Over 80% of crude feedstock arrives via maritime routes through the Panama Canal, exposing margin stability to transit bottlenecks and Pacific shipping rate volatility.
- OSINERGMIN Pricing Formulas:Regulated wholesale fuel price bands compress refinery margin capture during international crude price spikes, limiting reinvestment capacity.
- LPG Substitution Pressure:Residential and commercial heating demand in the sierra region is fragmenting toward piped natural gas where Peru LNG infrastructure reaches, eroding traditional LPG cylinder markets.
Strategic Opportunities
- Biofuel Blending Requirements:MINEM mandates for ethanol and biodiesel incorporation create offtake certainty for domestic agricultural processors and blending terminal operators.
- Jorge Chávez Airport Expansion:Cargo volume growth at the Lima international hub is expanding jet fuel storage and hydrant infrastructure requirements along the Callao coastal strip.
- Amazon Basin Distribution Gaps:Riverine fuel logistics to Iquitos and Puerto Maldonado remain underserved by conventional tanker truck networks, favoring barge-based supply models.
Industry Challenges
- Seismic Engineering Standards:Earthquake-resistant tank farm construction specifications are extending permitting timelines for new coastal storage capacity by 18-24 months.
- Hydrocracker Catalyst Expertise:Specialized technical talent for heavy crude conversion unit operation remains concentrated among a limited pool of international contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peru Oil and Gas Downstream Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Fuel Oil Distribution Channel: Retail Outlets, Wholesale Distributors, Direct Sales, Online Platforms End User: Transportation, Industrial Manufacturing, Household Consumption, Power Generation Storage Type: Above Ground, Underground, Mobile Tanks, Fixed Tanks |
| Companies Covered | Royal Dutch Shell PLC, TotalEnergies, Repsol SA, Anadarko Petroleum Corporation, Chevron, Petróleos del Perú SA, CF Industries Holdings Inc, Occidental Petroleum Corporation, Total SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peru Oil and Gas Downstream Market Evolving Landscape
Digital instrumentation and process control systems are penetrating Peru's refining sector, driven by margin pressure to optimize yield structures and reduce unplanned downtime at conversion units.
Advanced process control software is automating hydrocracker temperature and pressure optimization at the Talara facility, reducing product quality variance. Refinery operators are deploying these systems to manage heavier crude slates without manual intervention. The technology is automating yield curve adjustments that previously required shift-based engineering oversight.
OSINERGMIN transparency requirements on refinery margin reporting are tightening audit standards for cost pass-through calculations in wholesale fuel pricing. Downstream marketers must now submit detailed feedstock cost documentation to justify price adjustments. This regulatory shift is compressing pricing discretion for independent distributors in the Lima-Callao corridor.
Fleet procurement patterns among mining contractors are rotating toward long-term fuel supply agreements with fixed-volume, price-adjusted terms rather than spot market purchases. Large extractive operators in the Ancash and Cajamarca regions are locking in multi-year diesel offtake to hedge against Andean logistics cost volatility. This contractual shift is consolidating buyer power among a handful of mining conglomerates.
Peru Oil and Gas Downstream Market Segmentation
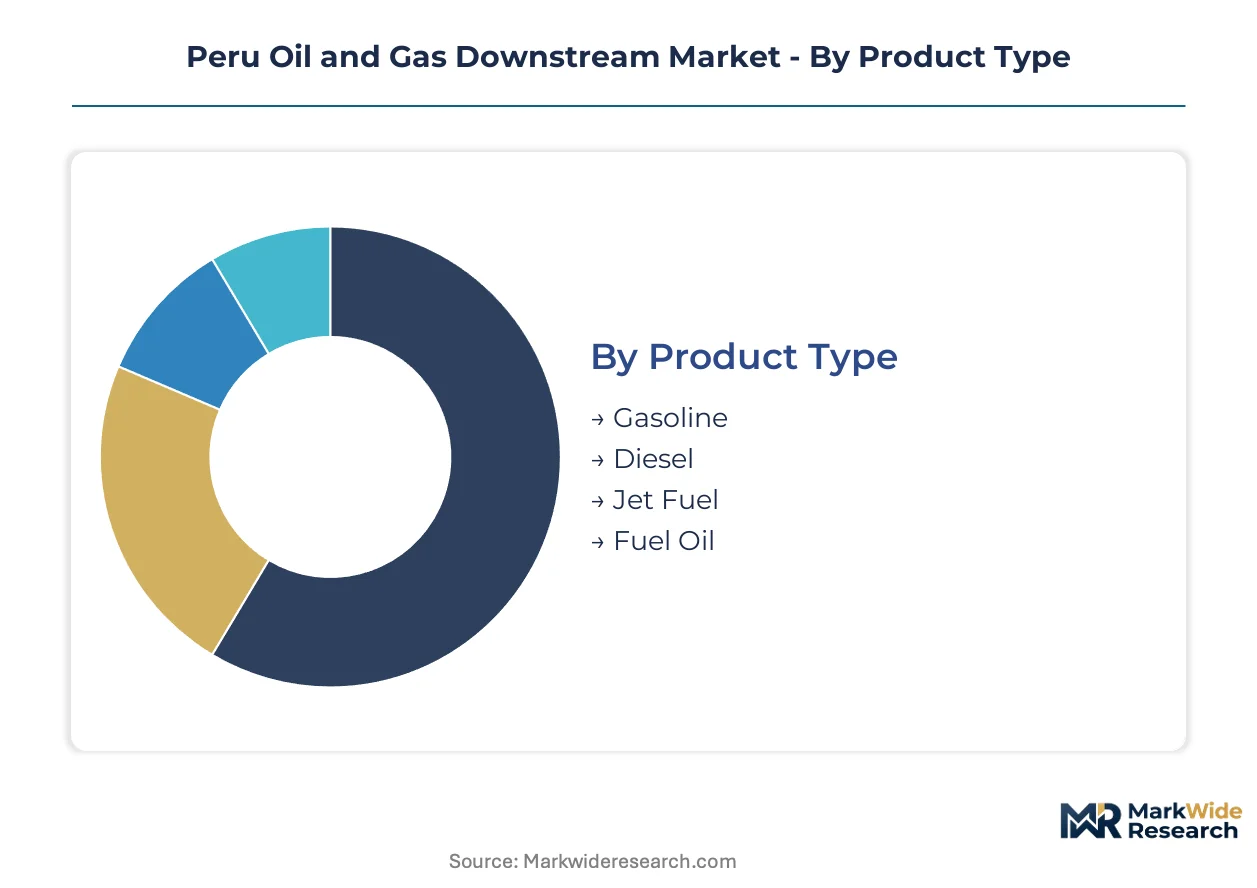
Segmentation in Peru's downstream hydrocarbon sector reveals how product flows, customer procurement patterns, and infrastructure configurations shape margin capture across the Pacific coastal corridor and Andean interior.
Product Type:
Standalone fuel categories dominate revenue pools, while blended and specialized products operate as embedded formulations within broader supply contracts.
- Gasoline:Refined to Euro V-equivalent specifications with maximum sulfur content of 50 ppm. Demand concentrates in Lima-Callao's urban vehicle fleet expansion, driven by rising private vehicle ownership and ride-hailing platform proliferation.
- Diesel:High-sulfur and low-sulfur grades serve distinct end-use profiles, with 500 ppm sulfur content permitted for mining and industrial applications. Procurement from Ancash and Cajamarca mining corridors is shifting toward multi-year offtake agreements with fixed-volume terms.
- Jet Fuel:Kerosene-based aviation turbine fuel meeting international Jet A-1 specifications serves Jorge Chávez International Airport cargo expansion.
- Fuel Oil:Residual fuel oil output from legacy refinery configurations is declining as Talara modernization redirects crude slates toward lighter product yields.
Diesel leads volumes today; jet fuel is gaining share fastest.
Distribution Channel:
Channel selection reflects customer scale, with high-volume consumers bypassing intermediaries while fragmented demand routes through layered distribution networks.
- Retail Outlets:Branded and unbranded service stations along Peru's Pan-American Highway corridor serve vehicle fleet refueling, with Repsol SA maintaining network density advantages.
- Wholesale Distributors:Independent logistics operators capture margin through bulk storage terminal access and secondary distribution to regional markets.
- Direct Sales:Mining conglomerates and industrial manufacturers procure diesel and fuel oil through bilateral contracts with refinery operators, eliminating distributor markups.
- Online Platforms:Digital fuel ordering interfaces are emerging for commercial fleet management, though penetration remains concentrated in Lima-Callao logistics corridors.
Wholesale distributors capture the highest transaction volumes; direct sales channels are climbing the fastest.
End User:
End-use segmentation separates mobile fuel consumption from stationary energy applications, with diverging specification requirements and procurement cadences.
- Transportation:Road, rail, and aviation fuel demand dominates product offtake, with fleet operators prioritizing supply security over price optimization.
- Industrial Manufacturing:Process heat and captive power generation consume residual fuel oil and diesel, with procurement tied to production cycle volatility.
- Household Consumption:LPG cylinder distribution serves residential cooking and heating in sierra regions where piped natural gas infrastructure remains absent.
- Power Generation:Diesel-fired backup generators and fuel oil baseload plants operate in grid-isolated Amazon basin localities.
Transportation leads volumes today; industrial manufacturing is expanding most quickly.
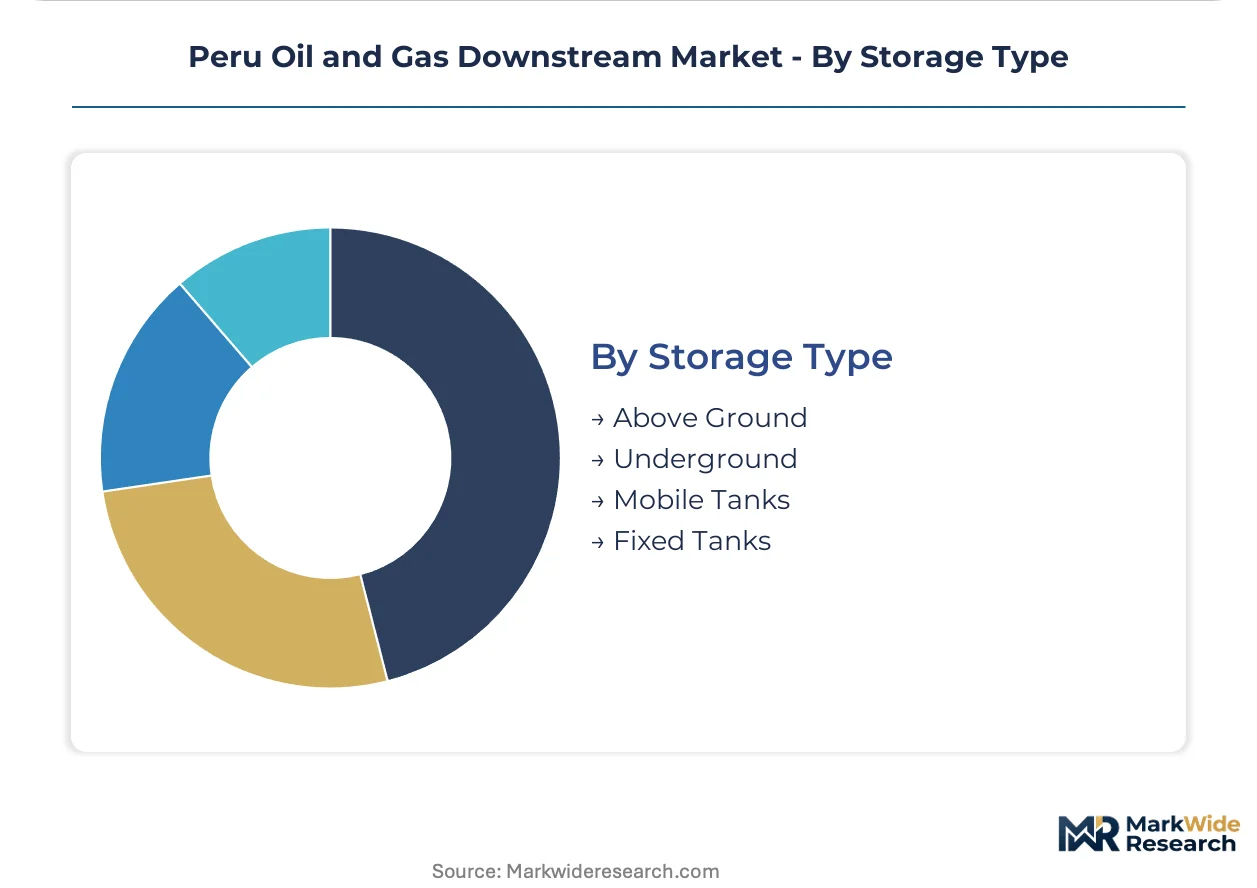
Storage Type:
Storage configuration determines capital intensity and regulatory exposure, with coastal facilities commanding premium throughput fees against higher construction standards.
- Above Ground:Coastal tank farms concentrate import receipt infrastructure, with earthquake-resistant engineering specifications extending permitting timelines.
- Underground:Rock cavern and buried tank storage provides seismic resilience and reduced land use, though deployment is limited by geological suitability.
- Mobile Tanks:Tanker trucks and riverine barges serve Amazon basin distribution gaps to Iquitos and Puerto Maldonado.
- Fixed Tanks:Permanent refinery and terminal storage underpins strategic reserve mandates issued by MINEM.
Above-ground storage leads volumes today; underground configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery modernization investments along Peru's Pacific coast are attracting capital away from jurisdictions with stricter carbon border adjustments, as operators exploit the cost-of-compliance gap between Andean regulatory frameworks and OECD-equivalent standards.
Lima-Callao Corridor
Urban vehicle fleet expansion and ride-hailing platform proliferation are concentrating gasoline demand in Peru's capital metropolitan area. OSINERGMIN pricing formulas govern wholesale fuel margins across coastal distribution terminals. The Callao port complex anchors import receipt infrastructure for regional crude deliveries.
Ancash Mining District
Copper extraction operations at Antamina and other Andean sites are consuming increasing volumes of high-sulfur diesel for haul truck fleets. MINEM strategic reserve mandates require inventory floors at coastal storage facilities serving this corridor. The Huarmey logistics hub channels refined products inland through mountain highway networks.
Talara Refinery Zone
Hydrocracking upgrades are unlocking processing flexibility for heavier Latin American crude slates previously routed elsewhere. Environmental standards enforced by Peru's national environmental certification agency shape refinery emissions limits and coastal storage facility permitting timelines. The Piura regional cluster houses earthquake-resistant tank farms commanding premium throughput fees.
Iquitos Amazon Basin
Riverine fuel logistics to this isolated city remain underserved by conventional tanker truck networks, favoring barge-based supply models. LPG cylinder distribution serves residential cooking demand where piped natural gas infrastructure remains absent. The Loreto provincial market fragments procurement across seasonal river transport windows.
Cajamarca Highlands
Gold extraction operations are locking in multi-year diesel offtake agreements to hedge against Andean logistics cost volatility. Biofuel blending requirements create offtake certainty for domestic agricultural processors supplying ethanol to regional blending terminals. The Jaén transport corridor channels fuel southward toward interconnecting highway systems.
Peru Oil and Gas Downstream Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty lubricant and LPG distribution niches. The market structures around three player tiers: integrated refinery operators with conversion unit assets, international majors leveraging Andean logistics footprints, and independent marketers dependent on terminal access agreements. Dominant competitive moves include hydrocracking capacity upgrades at coastal facilities and long-term supply contracting with mining conglomerates.
Among state-affiliated operators, Petróleos del Perú SA anchors downstream operations through refinery modernization. Spanish-origin Repsol SA and French-origin TotalEnergies exemplify international major positioning across retail networks and specialty product segments. These three entities represent the core competitive archetypes: domestic integrated operator, European multinational with Pan-American Highway corridor presence, and diversified energy major extending beyond conventional fuels.
| Leading Market Players |
|---|
| Royal Dutch Shell PLC |
| TotalEnergies |
| Repsol SA |
| Anadarko Petroleum Corporation |
| Chevron |
| Petróleos del Perú SA |
| CF Industries Holdings Inc |
| Occidental Petroleum Corporation |
| Total SA |
| Others |
Value Network & Pricing Analysis
Peru's national environmental certification agency emissions standards gate qualified supply access and premium-tier pricing for coastal storage operators meeting earthquake-resistant tank farm specifications. OSINERGMIN margin transparency requirements compress pricing discretion for independent distributors unable to document feedstock cost pass-throughs, bifurcating market access between compliant and non-compliant logistics providers.
Pricing Analysis
Input-cost pass-through mechanisms dominate wholesale fuel pricing under OSINERGMIN regulated bands, with refinery operators submitting detailed crude procurement documentation to justify adjustments. Price differentiation separates Euro V-equivalent diesel meeting 50 ppm sulfur limits from high-sulfur 500 ppm mining grades, with certification tier and volume scale as primary drivers. Pricing pressure stems from regulated margin compression during international crude spikes, limiting reinvestment capacity. Mining conglomerates demonstrate lowest price sensitivity through multi-year fixed-volume offtake agreements, while independent retailers face highest sensitivity to wholesale band movements.
Supply Chain Analysis
Single-source vulnerability sits with the Panama Canal as the maritime chokepoint for over 80% of crude feedstock arriving from Ecuador, Colombia, and Brazil. Hydrocracker catalyst supplies draw from specialized international contractors concentrated in the US and Europe, while seismic-resistant steel and engineering services rest on limited qualified vendor pools. Supply chain risk centers on transit bottlenecks and Pacific shipping rate volatility disrupting margin stability. Distribution runs through coastal import terminals at Callao, with secondary tanker truck networks penetrating Andean mining corridors and riverine barges serving Amazon basin gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with MINEM biofuel blending mandates creating structural offtake certainty for agricultural processors and blending terminal operators regardless of crude price cycles.
For Market Incumbents: Hedge against LPG substitution pressure by securing piped natural gas corridor access before Peru LNG infrastructure expands into sierra residential markets. Prioritize hydrocracker catalyst inventory buffers and technical service agreements with international contractors to mitigate operational disruption risks from specialized talent scarcity. Deepen backward integration into regional Latin American crude term contracts to reduce Panama Canal transit exposure.
For New Entrants and Emerging Players: Launch via barge-based supply models targeting Iquitos and Puerto Maldonado distribution gaps underserved by conventional tanker truck networks. White-space opportunities concentrate in Amazon basin riverine logistics and mobile tank deployment for grid-isolated power generation localities. Penetrate through digital fuel ordering interfaces for commercial fleet management in Lima-Callao logistics corridors.
For Investors and Strategic Acquirers: Roll-up economics work for independent coastal storage terminal operators because MINEM strategic reserve mandates guarantee baseline throughput utilization regardless of demand cycles. Long-term viability favors assets with earthquake-resistant specifications and premium fee capture potential. Watch for Peru LNG integration project announcements as inflection indicators for LPG cylinder market displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocracking Capacity Upgrade | Talara refinery modernization unlocks heavier Latin American crude processing flexibility previously routed to US Gulf Coast. |
| Long-term Supply Agreement | Mining conglomerates in Ancash and Cajamarca lock in multi-year diesel offtake to hedge Andean logistics volatility. |
| Coastal Storage Expansion | Earthquake-resistant tank farms at Callao and Piura command premium throughput fees under extended permitting timelines. |
| Biofuel Blending Investment | MINEM ethanol and biodiesel mandates create structural offtake certainty for domestic agricultural processors. |
| Digital Platform Integration | Commercial fleet management interfaces concentrate in Lima-Callao corridors with emerging penetration elsewhere. |
Research Methodology
Bottom-up mining and transportation demand modeling reconciled against top-down refinery output and import tracking forms the analytical core of this study. Primary interviews with refinery operations managers, OSINERGMIN regulatory officials, mining procurement directors, coastal terminal operators, and hydrocracker technical contractors combined with secondary validation from MINEM strategic reserve disclosures, OSINERGMIN pricing formula documentation, customs crude import records, and Jorge Chávez International Airport cargo statistics. Triangulation across these sources calibrated segment-level volume and value estimates.
Historical trendline analysis of refinery yield structures, storage terminal utilization rates, and mining diesel consumption patterns informed projection assumptions across the analysis window. Segmentation modeling incorporated product type, distribution channel, end-use sector, and storage configuration dimensions. CAGRs derived from regression analysis against crude slate evolution, fleet expansion trajectories, and regulatory mandate implementation schedules. Forecast inputs included hydrocracker capacity commissioning timelines and Peru LNG infrastructure rollout phases.
Several conditions sit outside the modeled scope, including potential Pacific coast storage hub developments altering competitive access rules and pending hydrocarbon framework reforms beyond current MINEM strategic reserve mandates. Forecasts reflect documented assumptions regarding international crude price bands and Panama Canal transit reliability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Nigeria Upstream Oil Sector Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Sensors in Oil and Gas Market