
 Air Oxygen Blender Market | 2026-2036
Air Oxygen Blender Market Size, Share, and Industry Trends Forecast 2026-2036
Air Oxygen Blender Market Outlook
North American precision instrument manufacturers is broadening output capacity for medical gas mixing equipment. Ohio Medical leverages vertical integration across valve assembly and flow control to sustain cost discipline in hospital procurement channels. Armstrong Medical specializes in neonatal-specific blender configurations, while Precision Medical anchors distribution through durable medical equipment networks across the United States.
An air oxygen blender is a pneumatic or electronic device that mixes medical-grade oxygen with ambient air to deliver a precise fraction of inspired oxygen (FiO2), typically ranging from 21% to 100%, through regulated flow rates measured in liters per minute. The instrument serves critical respiratory support functions across anesthesia delivery, mechanical ventilation, and bubble CPAP systems in perinatal and acute care settings. Portable blender configurations lead volume shipments due to home care expansion and emergency transport requirements, while high-fidelity units command margin concentration in NICU and surgical suites where accuracy tolerances tighten to within ±3% FiO2 deviation. Pressure swing adsorption technology dominates installed base economics for built-in hospital oxygen generation, though membrane separation advances in compact field units.
FDA 510(k) premarket notification requirements and ISO 80601-2-74 standards for respiratory ventilatory equipment govern product clearance and electrical safety testing for blenders sold in the United States. The EU Medical Device Regulation (MDR) and CE marking obligations under EN ISO 13485 quality management systems shape market access protocols for European commercialization. Stakeholders must monitor evolving EPA and OSHA guidelines on medical gas cylinder handling and workplace exposure limits, as these influence hospital capital budgeting and fleet replacement timing for centralized versus point-of-care oxygen delivery architectures.
Market Dynamics
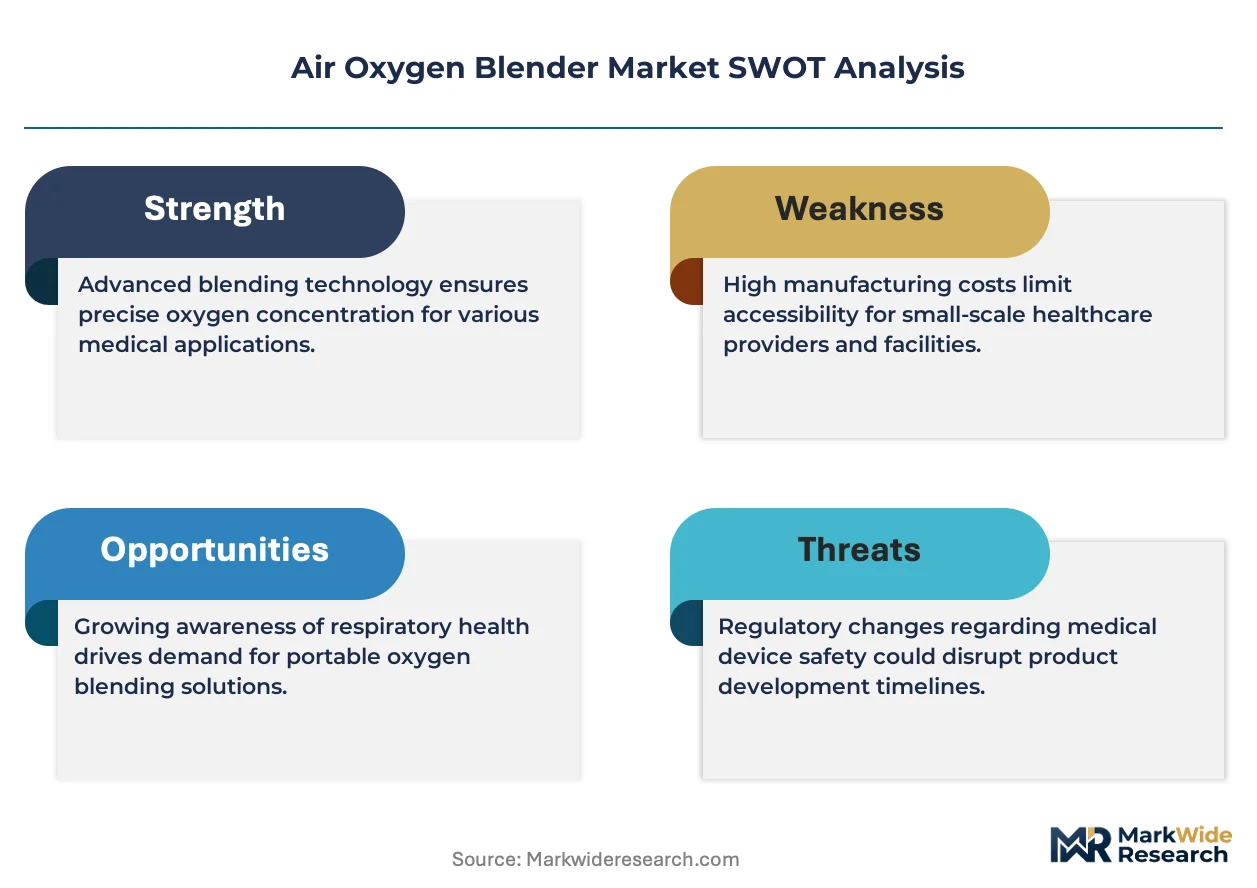
Neonatal precision requirements are compressing tolerance specifications across the installed base, forcing manufacturers to recalibrate flow control architectures around ±3% FiO2 deviation thresholds that now define competitive viability in intensive care procurement.
Growth Catalysts
- ISO 80601-2-74 electrical safety standards:Harmonized testing protocols reduce redundant certification costs for manufacturers targeting multiple regulatory jurisdictions, accelerating product launch velocity.
- Bubble CPAP adoption in perinatal units:Non-invasive respiratory support protocols for premature infants require calibrated blender integration, expanding addressable hardware attach rates.
- Membrane separation miniaturization:Advances in compact oxygen generation enable field-deployable blender systems for emergency medical services and disaster response configurations.
Market Restraints
- Medical-grade aluminum cylinder supply:Concentrated raw material sourcing from primary smelter regions creates input cost volatility that compresses margin structures for portable blender manufacturers.
- FDA 510(k) clearance timelines:Extended premarket notification review periods for pneumatic respiratory devices delay revenue recognition and extend product development cycles.
- Pressure swing adsorption substitution:Built-in hospital oxygen generation systems reduce dependency on external blender hardware in centralized gas distribution architectures.
Strategic Opportunities
- Home care respiratory expansion:Portable blender configurations for chronic obstructive pulmonary disease management address underpenetrated durable medical equipment channels outside acute settings.
- EU Medical Device Regulation harmonization:MDR quality management system convergence creates pathway for single-audit market access across 27 member states, reducing compliance fragmentation.
- Sensor fusion with pulse oximetry:Closed-loop FiO2 adjustment algorithms integrating blender output with SpO2 feedback enable automated titration protocols in surgical suites.
Industry Challenges
- Biomedical engineering specialization:Shortage of technicians qualified in pneumatic calibration and gas mixing validation extends field service response times for precision blender maintenance.
- Legacy anesthesia workstation integration:Retrofitting high-fidelity blenders into installed base equipment with proprietary gas manifold architectures requires custom adapter engineering and extended validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Oxygen Blender Market |
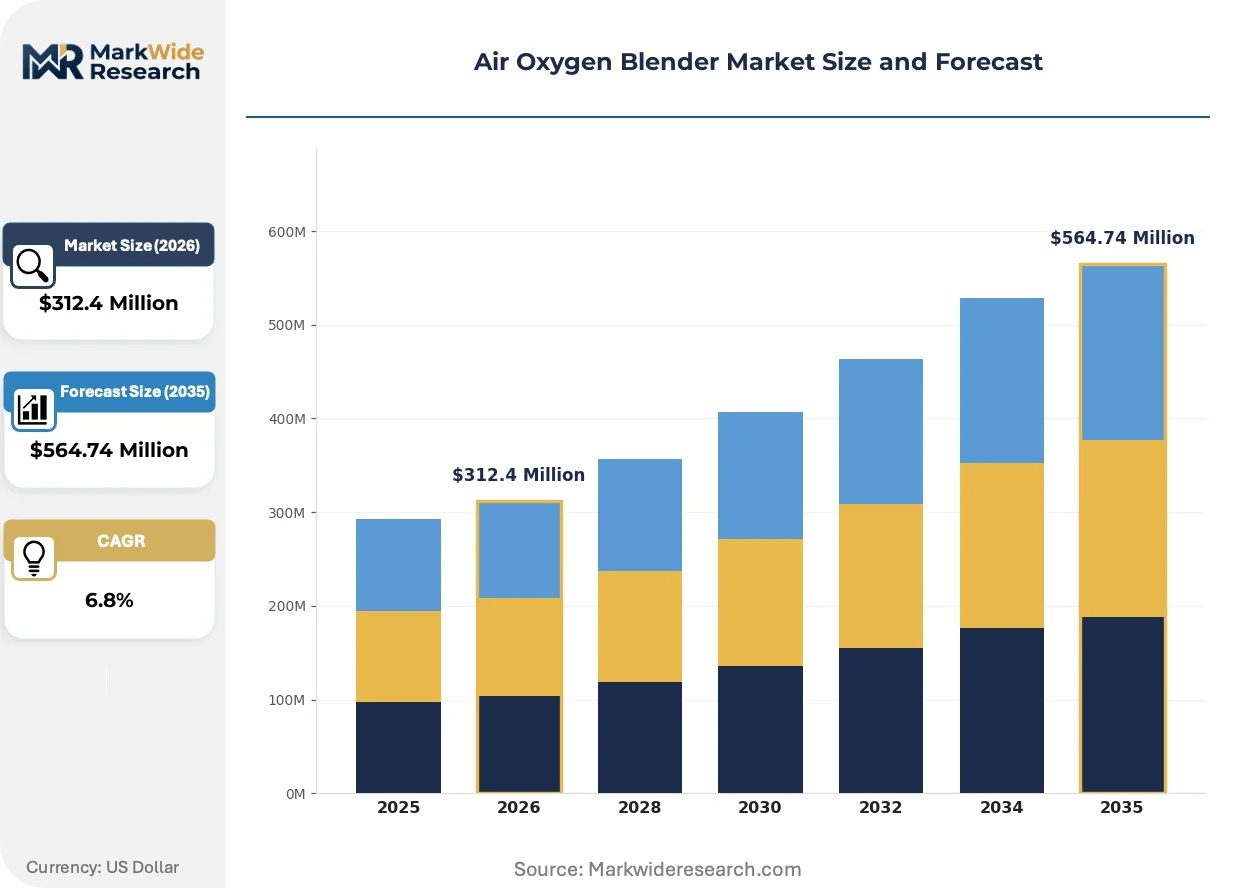
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Blenders, Fixed Blenders, Stationary Blenders, High-Fidelity Blenders Technology: Pressure Swing Adsorption, Membrane Separation, Cryogenic Distillation, Electrochemical Separation End User: Hospitals, Home Care, Medical Clinics, Emergency Services Application: Respiratory Therapy, Anesthesia, Neonatal Care, Sports Medicine |
| Companies Covered | Ohio Medical, Armstrong Medical, Precision Medical, Heyer Medical, EKU Elektronik, Maxtec, Sechrist Industries, Niceneotech, Bio-Med Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Oxygen Blender Market Strategic Shifts
Digital flow sensing and wireless connectivity are redefining how clinicians monitor and adjust oxygen delivery, shifting competitive advantage toward vendors capable of real-time telemetry integration rather than purely mechanical precision.
Microelectromechanical systems (MEMS) thermal mass flow sensors are displacing traditional differential pressure transducers in next-generation blender architectures. Neonatal intensive care units in tertiary hospitals are adopting these configurations fastest, driven by zero-drift stability requirements. The technology is modularizing subsystem replacement protocols, enabling field-upgradeable sensing cartridges that extend equipment lifecycle without full device retirement.
EU Medical Device Regulation (MDR) post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa respiratory devices. Manufacturers must now maintain electronic patient registries tracking blender performance in situ, adding recurring compliance infrastructure costs. High-fidelity surgical blenders face the steepest documentation burdens, with notified bodies demanding extended clinical evaluation reports for novel flow control algorithms.
Hospital procurement committees are unbundling preventive maintenance contracts from capital equipment purchases, treating service agreements as separately negotiable spend categories. Group purchasing organizations are consolidating blender fleet management under multi-year performance-based arrangements that penalize downtime exceeding contracted thresholds. This behavioral shift is most pronounced in United States health systems pursuing operating expense reduction targets under value-based care reimbursement models.
Air Oxygen Blender Market Segmentation
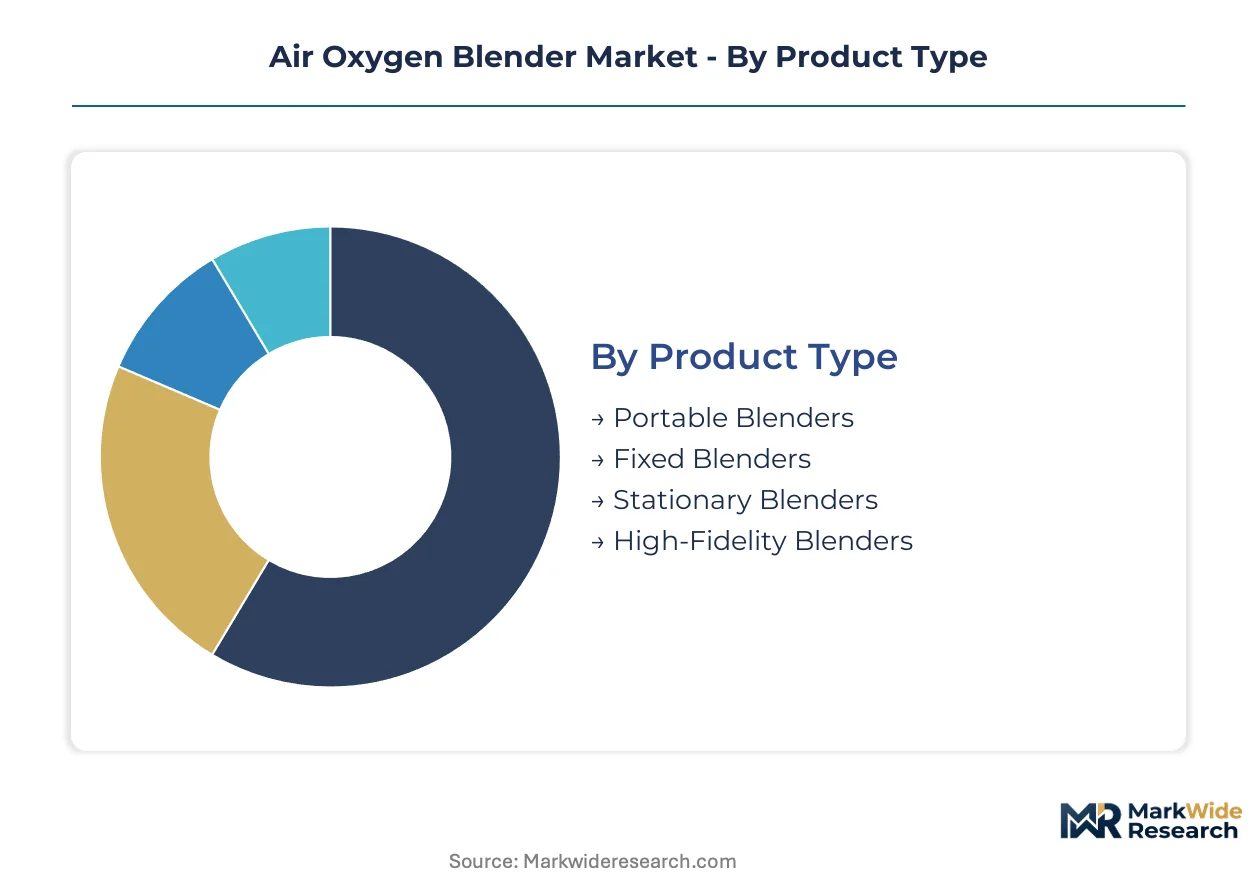
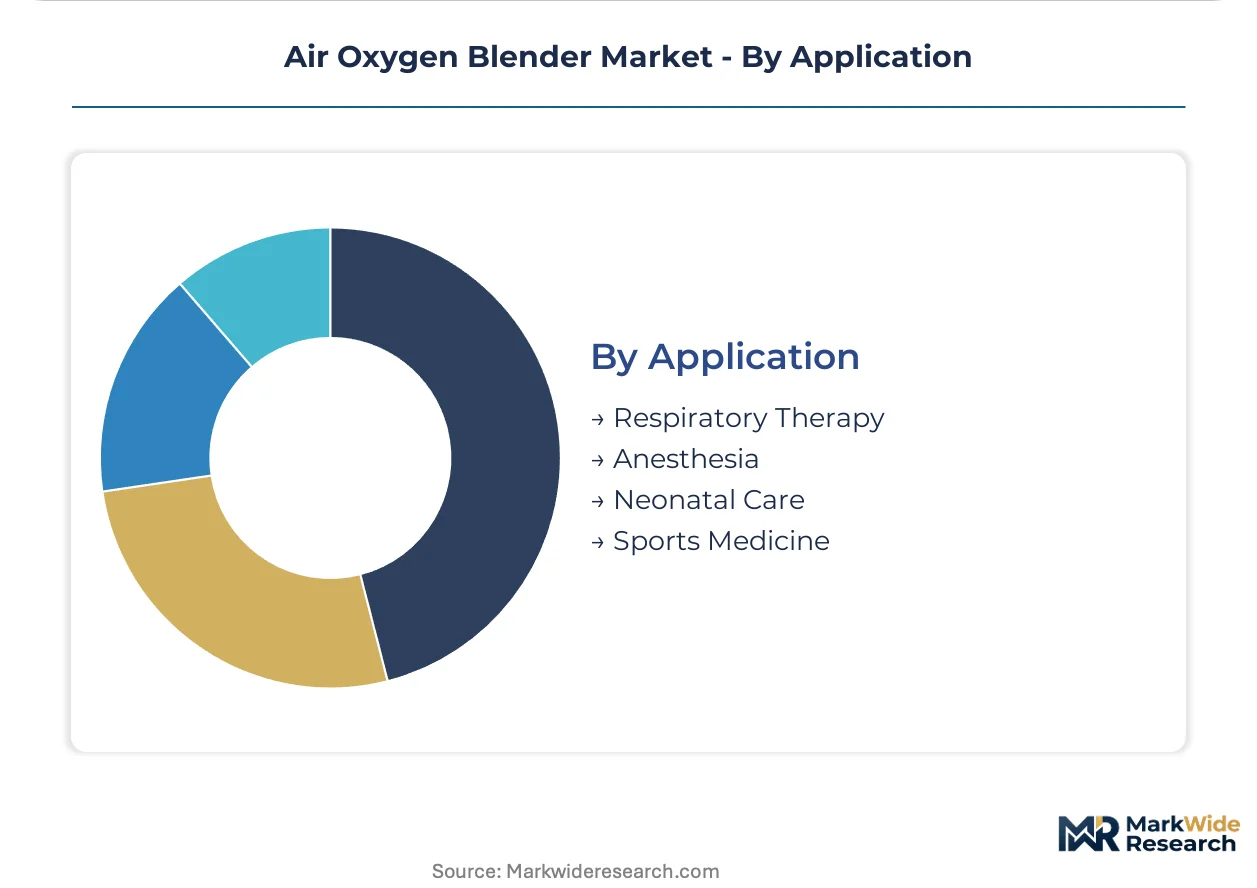
Segmentation in air oxygen blender procurement follows distinct technical and clinical logics that reshape vendor competitive positioning. Product mobility, oxygen generation method, care setting, and therapeutic application each create separate buying centers with incompatible specification requirements and budget authorities.
Product Type:
Portable configurations dominate shipment volumes while fixed installations command margin premiums in capital-intensive care environments.
- Portable Blenders:Battery-capable pneumatic units weighing under 4 kilograms enable emergency transport and home oxygen therapy. Demand concentrates in United States durable medical equipment channels where Medicare reimbursement codes for ambulatory respiratory support sustain replacement cycles.
- Fixed Blenders:Wall-mounted or cart-based systems with centralized gas manifold connections serve permanent installation in operating suites and intensive care pods. Hospitals in tertiary referral networks prioritize these configurations for anesthesia workstation integration where ±3% FiO2 tolerance defines competitive viability.
- Stationary Blenders:High-capacity floor units with dual-flow outputs support multiple patient stations simultaneously in surge capacity wards.
- High-Fidelity Blenders:Closed-loop sensor architectures with automated titration capabilities command premium positioning in surgical suites requiring real-time SpO2 feedback integration.
Today's leader: Portable Blenders. Tomorrow's challenger: High-Fidelity Blenders.
Technology:
Generation method determines capital intensity, operating cost structure, and field service requirements across installed base economics.
- Pressure Swing Adsorption:Zeolite molecular sieve cycling produces medical-grade oxygen from ambient air without cryogenic infrastructure. United States hospital systems deploy these systems for centralized oxygen generation, reducing dependency on cylinder logistics and external blender hardware in new construction projects.
- Membrane Separation:Polymer hollow-fiber modules enable compact, vibration-tolerant oxygen enrichment for pre-hospital and military field applications. Miniaturization advances are expanding addressable hardware into emergency medical services configurations where weight and durability constraints override purity optimization.
- Cryogenic Distillation:Liquid oxygen vaporization systems serve high-volume institutional demand with lowest unit oxygen cost but require substantial infrastructure investment.
- Electrochemical Separation:Solid oxide electrolysis cells generate oxygen through ionic conduction at elevated temperatures, currently limited to specialized aerospace and submarine applications.
Pressure Swing Adsorption anchors current installed base economics. Membrane Separation is climbing the fastest in portable and field-deployable segments.
End User:
Procurement authority and specification complexity fragment across institutional scale and reimbursement environment.
- Hospitals:Integrated delivery networks with centralized biomedical engineering departments negotiate multi-year fleet management agreements. Neonatal intensive care units within these systems impose the tightest calibration tolerances, driving precision instrument specifications across group purchasing organization contracts.
- Home Care:Durable medical equipment suppliers and respiratory therapy service companies purchase portable configurations for chronic obstructive pulmonary disease patient populations. Medicare competitive bidding programs in the United States compress margin structures and favor simplified maintenance protocols.
- Medical Clinics:Outpatient procedure centers require intermittent-use blenders for sedation and minor surgical oxygen delivery.
- Emergency Services:Fire department and ambulance operators prioritize rapid deployment, battery autonomy, and ruggedized housing over precision specifications.
Hospitals retain specification leadership. Home Care is expanding most quickly as post-acute reimbursement shifts toward community-based management.
Application:
Therapeutic use case determines flow rate range, alarm sophistication, and integration requirements with adjacent life support equipment.
- Respiratory Therapy:Mechanical ventilation and non-invasive support protocols require continuous flow delivery with adjustable FiO2 across 21-100% range. United States acute care hospitals standardize these configurations across general medical-surgical floors and step-down units.
- Anesthesia:Operating room blenders integrate with gas anesthesia machines to deliver precise oxygen-nitrous oxide mixtures. FDA 510(k) clearance requirements for respiratory devices elevate documentation burdens and extend development timelines for vendors targeting surgical suite penetration.
- Neonatal Care:Bubble CPAP and mechanical ventilation for premature infants demands ultra-low flow accuracy and minimal pressure fluctuation.
- Sports Medicine:Altitude simulation and hyperoxic training protocols utilize blenders for controlled hypoxic or hyperoxic chamber environments.
Respiratory Therapy commands current volume concentration. Neonatal Care holds the steepest expansion trajectory as perinatal survival rates drive specialized equipment investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as FDA 510(k) clearance timelines and ISO 80601-2-74 compliance costs widen the cost-of-doing-business gap between jurisdictions. Production migration toward regions with streamlined medical device approval pathways is accelerating, while end-market demand concentrates in aging populations with chronic respiratory disease burdens.
United States
Medicare reimbursement codes for durable medical equipment sustain replacement cycles for portable blender fleets in home care channels. FDA premarket notification requirements for pneumatic respiratory devices elevate documentation burdens and extend development timelines. Ohio Medical anchors production clusters in the Midwest with vertical integration across valve assembly operations.
Germany
EU Medical Device Regulation post-market surveillance mandates for Class IIa respiratory devices impose systematic clinical follow-up data collection obligations. CE marking under EN ISO 13485 quality management systems shapes market access protocols. Precision instrument manufacturing concentrates in Baden-Württemberg, where medical technology clusters serve export markets across the European Union.
China
NMPA medical device registration requirements for respiratory equipment create domestic certification pathways parallel to international standards. NMPA governs product clearance through classification and technical review processes. Manufacturing gravity centers on the Yangtze River Delta, where component supply chains for pneumatic devices cluster near Shanghai medical technology zones.
Japan
PMDA pharmaceutical and medical device agency standards for electrical safety testing align with IEC 60601 series harmonization. METI industrial policy supports precision medical device manufacturing through regulatory guidance and standardization initiatives. Production concentrates in the Kansai region around Osaka, where specialized pneumatic component suppliers serve domestic blender assembly operations.
India
CDSCO medical device rules under the Drugs and Cosmetics Act govern import registration and manufacturing licensing for respiratory equipment. PLI scheme production-linked incentives for medical devices attract domestic manufacturing investment. Medical technology clusters in Karnataka and Maharashtra are expanding assembly capacity for export-oriented pneumatic device production.
Air Oxygen Blender Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated and portable configurations to bypass incumbent service networks. The vendor base stratifies across three maturity tiers: legacy pneumatic specialists with decades of hospital relationships, mid-scale regional fabricators serving procurement cost targets, and technology-focused entrants leveraging MEMS sensing and wireless connectivity. Consolidation pressure operates selectively, with acquisition activity targeting niche neonatal specialists and field-service capabilities rather than broad portfolio expansion. Two dominant competitive moves define current positioning: backward integration into valve and flow-control component manufacturing to protect margin structures, and geographic expansion through notified-body relationships that unlock multi-jurisdiction market access.
Among United States-based specialists, Ohio Medical exemplifies the vertically integrated archetype with captive supply of pneumatic subsystems. Armstrong Medical occupies a position within the neonatal-focused tier, while Precision Medical anchors distribution-intensive positioning through durable medical equipment channel relationships. These three represent distinct strategic postures: manufacturing control, clinical specialization, and procurement network penetration.
| Leading Market Players |
|---|
| Ohio Medical |
| Armstrong Medical |
| Precision Medical |
| Heyer Medical |
| EKU Elektronik |
| Maxtec |
| Sechrist Industries |
| Niceneotech |
| Bio-Med Devices |
| Others |
Value Chain & Pricing Dynamics
Medical-grade aluminum pricing indices cascade through pneumatic subsystem costs into three-tier pricing structures across premium, standard, and economy levels. Hospital procurement committees exploit this concentration by unbundling maintenance contracts from capital purchases, compressing margin structures for portable blender manufacturers dependent on cylinder logistics.
Pricing Analysis
Distributor margins in durable medical equipment channels absorb 15-25 point markups before Medicare reimbursement ceilings cap final pricing. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 510(k) clearance tier and MEMS sensor integration rather than purely mechanical precision. Pricing pressure stems from group purchasing organization consolidation of fleet management under performance-based arrangements that penalize downtime. Home care channels exhibit highest price sensitivity due to Medicare competitive bidding compression, while surgical suites tolerate premium positioning for ±3% FiO2 tolerance.
Supply Chain Analysis
Refurbishment flows for precision flow sensors and valve assemblies extend equipment lifecycle without full device retirement, creating secondary parts markets that compete with OEM service revenues. Component manufacturing concentrates in the United States, Germany, and China, with pneumatic valve subsystems drawing from Midwestern industrial clusters and Yangtze River Delta electronics corridors. Raw material dependencies tether production to medical-grade aluminum cylinder supply, zeolite molecular sieves for PSA units, and polymer hollow-fiber membranes. Single-source vulnerability in primary smelter regions exposes margin structures to input cost volatility. Distribution runs through hospital procurement committees, durable medical equipment networks, and emergency services operators with incompatible specification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air oxygen blender market functions as a regulatory compounder where FDA 510(k) clearance timelines and EU MDR post-market surveillance mandates continuously elevate compliance infrastructure costs and consolidate procurement authority among vertically integrated incumbents.
For Market Incumbents: To counter MEMS sensor commoditization from Asian electronics suppliers, deepen backward integration into valve and flow-control component manufacturing while expanding captive service networks that lock hospital systems into multi-year performance-based maintenance contracts. Acquire niche neonatal specialists to defend precision instrument positioning against mid-scale regional fabricators. For New Entrants and Emerging Players: Capture home care respiratory expansion by targeting chronic obstructive pulmonary disease patient populations outside acute settings with simplified portable configurations optimized for Medicare reimbursement codes. Penetrate durable medical equipment channels through direct-to-provider sales models that bypass incumbent service networks and compress distributor margin layers. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-focused entrants leveraging wireless connectivity and closed-loop titration algorithms that enable automated FiO2 adjustment protocols. Long-term viability favors acquisition targets with notified-body relationships unlocking multi-jurisdiction market access across FDA, CE marking, and NMPA pathways. Monitor FDA 510(k) clearance timeline extensions as inflection indicator for consolidation pressure among capital-constrained mid-scale fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pneumatic Subsystems | In-house valve production protects margin structures from medical-grade aluminum volatility. |
| MEMS Sensor Platform Development | Thermal mass flow sensing displaces differential pressure transducers in NICU procurement. |
| EU MDR Quality Management Convergence | Single-audit pathway reduces compliance fragmentation across 27 member states. |
| Closed-Loop SpO2 Integration | Automated titration algorithms command premium positioning in surgical suite procurement. |
| Home Care Channel Direct Penetration | Medicare reimbursement optimization bypasses distributor markup compression. |
Study Parameters
Direct dialogue with hospital purchasing committees, biomedical engineering directors, GPO contracts managers, and neonatal intensive care clinicians grounded qualitative assessment of procurement behavior and calibration tolerance requirements. Secondary validation drew from FDA 510(k) premarket notification databases, ISO 80601-2-74 electrical safety testing protocols, CMS Medicare reimbursement code filings, and hospital capital expenditure disclosures. Bottom-up shipment modeling triangulated against top-down addressable market sizing across product mobility, oxygen generation method, care setting, and therapeutic application dimensions.
Segment-level value outputs across the analysis window reflect installed base economics for pressure swing adsorption systems, portable membrane separation growth trajectories, and high-fidelity surgical blender margin concentration. CAGRs derive from replacement cycle analysis of blender fleets in tertiary referral networks, Medicare reimbursement sustainability for durable medical equipment channels, and perinatal survival rate-driven investment in neonatal precision instruments. Modeled inputs include FDA clearance timeline distributions, EU MDR post-market surveillance cost burdens, and raw material price index volatility for medical-grade aluminum.
Regulatory timeline acceleration, raw material supply disruption, and reimbursement code revision are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around ISO 80601-2-74 harmonization sustaining certification cost structures and bubble CPAP adoption expanding hardware attach rates. Practitioners should monitor FDA 510(k) review period extensions, primary smelter region supply constraints, and Medicare competitive bidding program modifications for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Electroceuticals Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Digital Phoropter Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Occlusion Balloon Catheter Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Physiotherapy Laser Wrist Watch Market