
 Lateral Epicondylitis (Tennis Elbow) Treatment Market | 2026-2036
Lateral Epicondylitis (Tennis Elbow) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lateral Epicondylitis (Tennis Elbow) Treatment Market Foresight
Platelet-rich plasma formulations are consolidating position against corticosteroid injections in outpatient elbow protocols. Pfizer leverages its injectable pain portfolio to sustain presence in physician-administered segments. DJO Global (Enovis) anchors the bracing and support equipment category through rehabilitation channel control. Zimmer Biomet differentiates with arthroscopic surgical solutions for refractory cases.
Lateral epicondylitis treatment encompasses therapeutic interventions targeting extensor carpi radialis brevis tendon microtears, typically involving ultrasound-guided injections, eccentric loading protocols, or extracorporeal shockwave delivery at 0.12-0.25 mJ/mm² energy density. The primary commercial purpose is restoring grip strength and wrist extension while avoiding surgical release. Therapeutic devices command expanding margin pools as clinics shift toward in-office modalities. Medications face pricing pressure from generic NSAID saturation. Support equipment sees fastest volume growth through direct-to-consumer channels and post-discharge home care protocols.
FDA 510(k) pathways govern therapeutic device clearance, while OSHA ergonomic guidelines shape employer-funded prevention program demand. The EU MDR and FDA jointly enforce biocompatibility standards for implantable anchors and injectable scaffolds, elevating documentation burdens for smaller manufacturers. Stakeholders must weigh reimbursement durability for emerging biologic injections against established physical therapy codes when allocating R&D and commercial resources.
Market Dynamics
Outpatient migration of lateral epicondylitis protocols is compressing surgical volumes while elevating reimbursement complexity for in-office biologic delivery. Sports medicine clinics now prioritize same-day therapeutic modalities over referral-based surgical pipelines.
Growth Catalysts
- FDA 510(k) pathway acceleration:Wearable therapeutic devices reach clearance in 90-120 days versus historical 180-day cycles, enabling rapid commercial deployment of neuromuscular stimulation units.
- OSHA ergonomic mandate expansion:Employer-funded prevention programs in manufacturing and logistics verticals drive demand for prophylactic bracing and early-intervention protocols.
- Ultrasound-guided injection technique standardization:Sports medicine fellowship curricula now mandate proficiency, expanding addressable patient pools for image-guided biologic delivery.
Market Restraints
- Corticosteroid efficacy ceiling:Clinical literature documents diminishing returns beyond two injections, capping repeat-revenue potential for pharmaceutical formulations.
- Autologous blood product processing cost:Centrifuge equipment and technician time inflate per-procedure expenses 40-60% above synthetic alternatives.
- EU MDR biocompatibility documentation:Implantable anchor manufacturers face 18-24 month recertification timelines, freezing product line extensions.
Strategic Opportunities
- Direct-to-consumer rehabilitation equipment:Post-discharge home care protocols bypass clinic markup structures, capturing margin pools previously allocated to physical therapy billing.
- Telehealth-guided eccentric loading programs:Remote monitoring platforms enable protocol adherence tracking without geographic proximity to specialized centers.
- India PLI scheme for medical devices:Domestic manufacturing incentives reduce landed cost for therapeutic device exporters targeting price-sensitive Asian markets.
Industry Challenges
- Interventional radiology technician scarcity:Ultrasound-guided injection proficiency requires 200+ supervised procedures, creating training bottlenecks at high-volume clinics.
- Biologic storage cold-chain integrity:Platelet-rich plasma formulations demand 2-8°C maintenance through point-of-care preparation, complicating ambulatory surgical center workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lateral Epicondylitis (Tennis Elbow) Treatment Market |
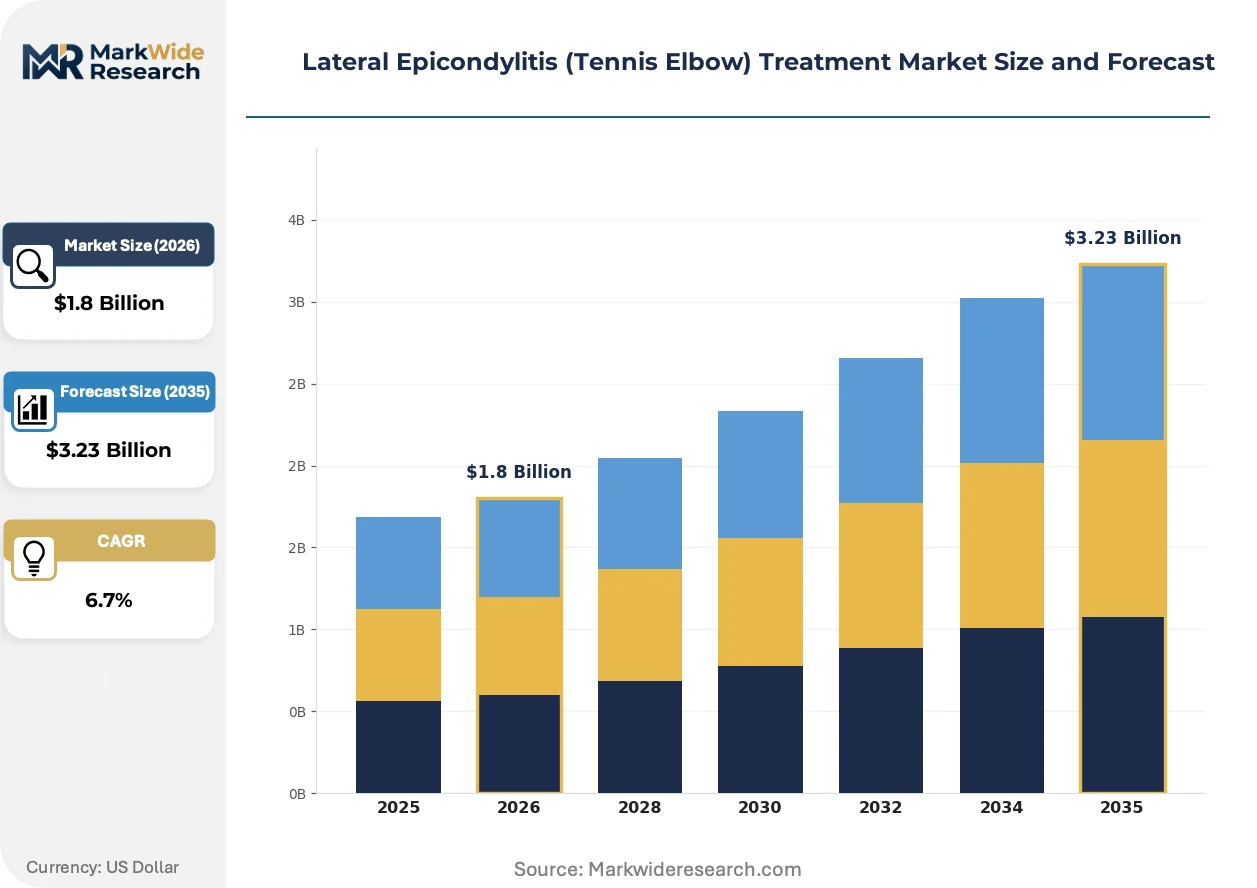
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Physical Therapy, Corticosteroid Injections, Surgery, Brace Product Type: Therapeutic Devices, Medications, Support Equipment, Exercise Tools End User: Clinics, Hospitals, Home Care, Rehabilitation Centers Administration Route: Oral, Topical, Injectable, Transdermal |
| Companies Covered | Pfizer, Teikoku Pharma, 3M Company, BTL, Ossur Corporate, DJO Global (Enovis), Novartis, Arthrex, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lateral Epicondylitis (Tennis Elbow) Treatment Market Shifts & Advancements
Wearable neuromodulation and biologic formulation science are redrawing treatment hierarchies, while regulatory pathways and procurement logic adapt to outpatient-first delivery models.
Extracorporeal shockwave therapy is converging with ultrasound imaging for real-time tendon targeting, enabling energy density calibration at 0.12-0.25 mJ/mm² with anatomical precision. Sports medicine clinics in the United States and Germany are replacing protocol-driven application with image-guided delivery, compressing treatment cycles from twelve to six sessions while elevating per-procedure reimbursement codes.
The EU MDR's 2021 implementation tightened biocompatibility testing requirements for implantable tendon anchors and injectable scaffolds, forcing manufacturers to resubmit technical documentation under stricter clinical evidence standards. European orthopedic device firms have responded by consolidating notified body relationships and freezing non-core product lines, shifting R&D toward 510(k) parallel submissions in the United States where predicate device pathways remain more permissive.
Self-referral patterns among recreational athletes are displacing traditional physician-gatekeeper models, with patients initiating treatment through direct-to-consumer diagnostic platforms and home-use therapeutic devices. This channel compression is most pronounced in United States metropolitan markets where high-deductible health plans incentivize out-of-pocket spending for sub-surgical interventions, forcing clinic networks to unbundle physical therapy packages into à la carte service menus.
Lateral Epicondylitis (Tennis Elbow) Treatment Market Segmentation
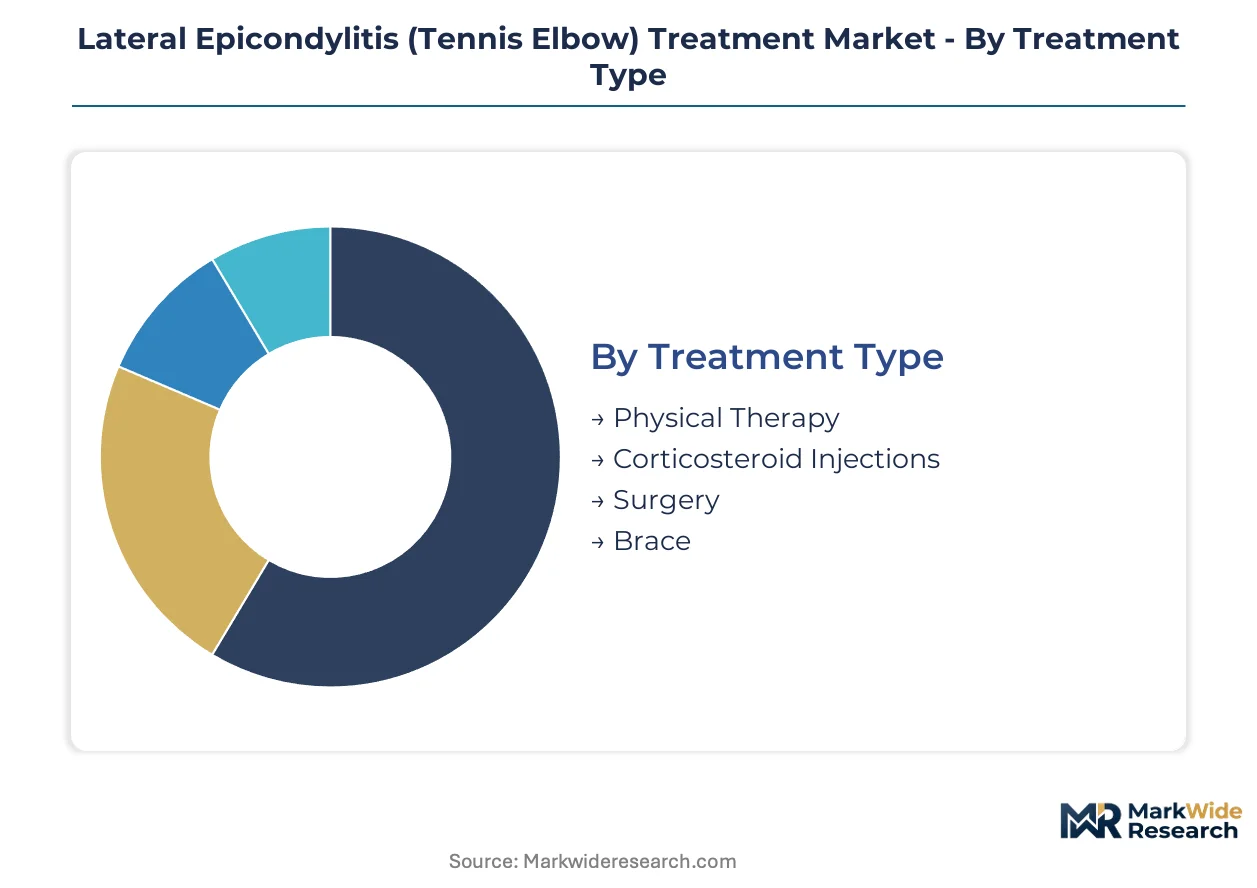
Segmentation in lateral epicondylitis treatment reveals how reimbursement pathways and care delivery sites reshape competitive boundaries. Each dimension—modality, product form, care setting, and administration method—carries distinct margin structures and regulatory requirements that determine manufacturer positioning.
Treatment Type:
Patient severity and prior treatment failure history drive modality selection, with cost tolerance escalating across the progression curve.
- Physical Therapy:Eccentric loading protocols and ultrasound-guided manual techniques target extensor tendon remodeling without invasive intervention. Demand concentrates in United States sports medicine clinics where bundled payment models incentivize conservative first-line approaches.
- Corticosteroid Injections:Triamcinolone and methylprednisolone formulations deliver anti-inflammatory action via landmark-guided or image-guided delivery. Germany and United Kingdom outpatient settings favor these for rapid return-to-work outcomes in occupational cases.
- Surgery:Arthroscopic release and open debridement address refractory cases failing six-plus months of conservative management. Volume is compressing as outpatient protocols capture patients earlier in the disease course.
- Brace:Counterforce straps and wrist splints provide mechanical unloading of the extensor carpi radialis brevis origin. Direct-to-consumer channels in United States metropolitan markets are expanding fastest through employer prevention programs.
Physical therapy leads on scale; brace leads on momentum.
Product Type:
Procurement authority differs sharply across categories—clinicians control therapeutic devices, while patients self-select support equipment.
- Therapeutic Devices:Extracorporeal shockwave systems and neuromuscular stimulation units operate at energy densities of 0.12-0.25 mJ/mm² for tendon regeneration. United States ambulatory surgical centers prioritize FDA 510(k)-cleared platforms with integrated ultrasound guidance.
- Medications:Oral NSAIDs, topical diclofenac, and injectable corticosteroids compete on formulary placement and prior authorization burden. Generic saturation is compressing pricing power across all administration routes.
- Support Equipment:Elbow straps, compression sleeves, and ergonomic braces command expanding margin pools through e-commerce direct sales. Post-discharge home care protocols in Japan and South Korea favor adjustable tension mechanisms.
- Exercise Tools:FlexBar resistance devices and grip strengtheners enable patient-directed eccentric loading programs. Telehealth integration is accelerating adoption in remote geographies lacking specialized hand therapy access.
Therapeutic devices capture the steepest expansion trajectory; medications face the steepest margin compression.
End User:
Site-of-care economics determine product configuration, with reimbursement codes varying 40-60% between institutional and home settings.
- Clinics:Sports medicine and orthopedic urgent care facilities deliver same-day injection and device-based protocols. United States private practice networks are consolidating purchasing to extract volume discounts from device manufacturers.
- Hospitals:Academic medical centers handle complex revision cases and workers' compensation litigation support. Surgical volume is declining as outpatient migration accelerates.
- Home Care:Post-discharge rehabilitation and patient-directed bracing bypass facility fees entirely. European markets with strong community nursing infrastructure show higher adherence to home exercise protocols.
- Rehabilitation Centers:Dedicated hand therapy practices provide specialized eccentric loading and manual therapy. Certification requirements for certified hand therapists create supply constraints in rural United States markets.
Clinics dominate current revenue; home care is climbing the fastest.
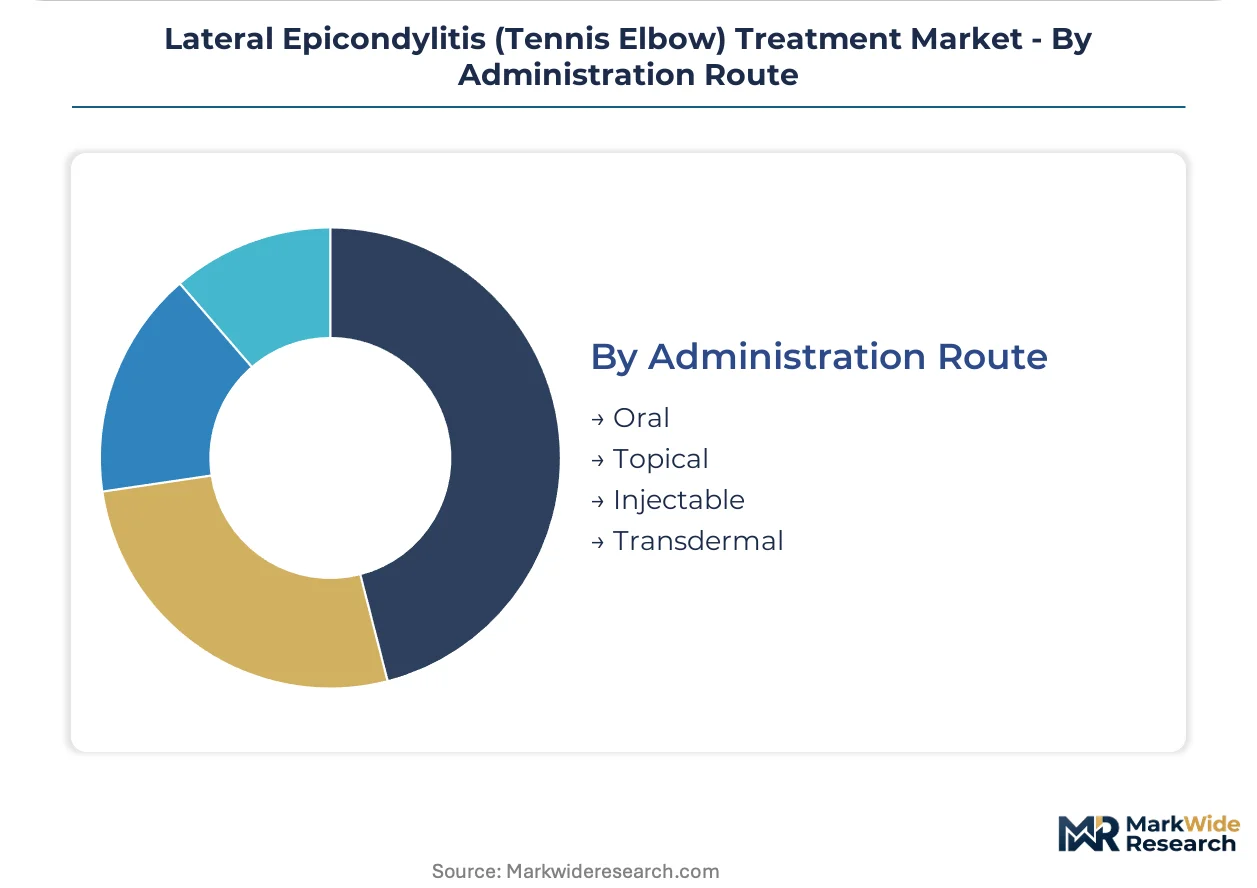
Administration Route:
Route selection balances onset speed against safety profile, with invasiveness correlating to reimbursement complexity.
- Oral:Systemic NSAIDs and analgesics serve as first-line symptom management with broad accessibility. Hepatorenal monitoring requirements limit long-term utilization in polypharmacy populations.
- Topical:Diclofenac gels and lidocaine patches deliver localized action with minimal systemic exposure. European self-medication cultures drive higher per-capita consumption than United States prescription-dependent models.
- Injectable:Corticosteroids, platelet-rich plasma, and hyaluronic acid formulations require sterile technique and anatomical precision. Ultrasound guidance is becoming standard of care in high-volume United States clinics.
- Transdermal:Iontophoresis and phonophoresis systems enhance drug penetration through electrical or ultrasonic energy. Adoption remains limited to specialized physical therapy practices with capital equipment investment capacity.
Injectable routes lead on revenue per procedure; topical formulations are gaining share fastest through over-the-counter channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States sports medicine corridors concentrate the highest procedure volumes and reimbursement intensity for lateral epicondylitis interventions. Geographic demand patterns reflect occupational exposure clusters, regulatory pathway efficiency, and outpatient infrastructure maturity.
United States
FDA 510(k) clearance acceleration for wearable therapeutic devices compresses commercialization timelines to 90-120 days. OSHA ergonomic mandates in manufacturing and logistics verticals expand employer-funded prevention program adoption. Texas Medical Center and Mayo Clinic Rochester anchor high-volume ultrasound-guided injection training networks.
Germany
Extracorporeal shockwave therapy protocols achieve rapid return-to-work outcomes in occupational lateral epicondylitis cases. EU MDR biocompatibility documentation requirements extend recertification timelines for implantable tendon anchors. Berlin and Munich metropolitan clusters concentrate sports medicine fellowship programs standardizing image-guided delivery techniques.
Japan
Post-discharge home care protocols leverage strong community nursing infrastructure for eccentric loading adherence. METI medical device reimbursement pathways prioritize minimally invasive outpatient modalities. Osaka-Kobe industrial corridor generates concentrated employer demand for prophylactic bracing in precision manufacturing workforces.
India
PLI scheme incentives for domestic medical device manufacturing reduce landed costs for therapeutic equipment exporters. CDSCO streamlined approval pathways accelerate market entry for neuromuscular stimulation platforms. Maharashtra and Karnataka urban clusters expand private sports medicine clinic networks targeting recreational athlete self-referral patterns.
United Kingdom
NHS bundled payment models incentivize conservative first-line physical therapy approaches over surgical referral. MHRA post-Brexit regulatory autonomy enables parallel submission strategies with FDA 510(k) pathways. London and Manchester metropolitan areas concentrate private clinic networks unbundling rehabilitation services into à la carte menus.
Lateral Epicondylitis (Tennis Elbow) Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers bridge pharmaceutical, device, and support equipment categories. The vendor base stratifies across three tiers: multinational healthcare conglomerates with injectable and surgical portfolios, specialized orthopedic device firms controlling rehabilitation channels, and emerging wearable technology developers exploiting accelerated FDA pathways. Strategic archetypes include integrated pain management platforms, rehabilitation channel specialists, and outpatient modality innovators. M&A activity and technology licensing agreements represent the dominant competitive moves as firms address reimbursement complexity across care settings.
Among pharmaceutical and device conglomerates, Pfizer and Novartis occupy positions spanning injectable pain formulations, while Zimmer Biomet anchors the surgical solutions tier. DJO Global (Enovis) exemplifies rehabilitation channel control through bracing and support equipment dominance. These three entities represent distinct strategic archetypes: pharmaceutical portfolio leverage, orthopedic surgical systems integration, and outpatient rehabilitation infrastructure capture.
| Leading Market Players |
|---|
| Pfizer |
| Teikoku Pharma |
| 3M Company |
| BTL |
| Ossur Corporate |
| DJO Global (Enovis) |
| Novartis |
| Arthrex |
| Zimmer Biomet |
| Others |
Supply & Pricing Matrix
Captive supply of PRP centrifuge systems and consumables anchors pricing power for outpatient biologic delivery networks, compressing per-procedure margins for clinics lacking in-house processing capacity while elevating returns for integrated device-service platforms.
Pricing Analysis
Input-cost pass-through from biologic formulation raw materials and cold-chain logistics compresses margins on platelet-rich plasma kits, while generic NSAID saturation eliminates pricing power in pharmaceutical tiers. Three-tier pricing structure across premium ultrasound-guided systems, standard landmark-guided injection protocols, and economy oral analgesic tiers separates reimbursement codes by invasiveness level. Pricing pressure stems from employer prevention program procurement consolidating brace and support equipment volumes. Occupational health buyers exhibit highest price sensitivity; academic medical centers show lowest sensitivity for refractory surgical cases.
Supply Chain Analysis
Freight cost volatility for temperature-controlled biologic shipments from Germany, United States, and South Korea distribution hubs elevates landed costs for platelet-rich plasma formulations and hyaluronic acid derivatives. Manufacturing concentration for extracorporeal shockwave systems draws from precision electronics clusters in Germany and Japan, with final assembly tethered to FDA 510(k) submission sites in United States and EU MDR notified body jurisdictions. Single-source vulnerability sits with ultrasound transducer crystal suppliers. Distribution runs through orthopedic device distributors and direct-to-consumer e-commerce platforms for support equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: FDA 510(k) pathway acceleration in the United States enables 90-120 day clearance timelines versus 18-24 month EU MDR recertification cycles, compressing capital recovery periods for therapeutic device manufacturers.
For Market Incumbents: To counter wearable neuromodulation entrants exploiting accelerated FDA pathways, DJO Global and Zimmer Biomet should deepen rehabilitation channel control through exclusive clinic network partnerships and captive supply of consumable injection kits. Backward integration into PRP centrifuge manufacturing reduces per-procedure cost exposure.
For New Entrants and Emerging Players: CDSCO streamlined approval pathways in India open a window for neuromuscular stimulation platforms targeting price-sensitive Asian markets through domestic manufacturing under PLI scheme incentives. Direct-to-consumer rehabilitation equipment and telehealth-guided eccentric loading programs represent the most penetrable white-space targets. Employer-funded prevention program sales bypass clinic procurement gatekeepers entirely.
For Investors and Strategic Acquirers: Roll-up economics work for outpatient modality innovators because reimbursement code unbundling and self-referral pattern growth fragment addressable patient pools across dispersed clinic networks. Platform consolidation of ultrasound-guided injection training networks and biologic formulation capabilities offers 5-10 year viability. Watch FDA 510(k) clearance volume for wearable therapeutic devices as inflection indicator for competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Wearable neuromodulation platforms reach commercial deployment in 90-120 day cycles versus historical timelines. |
| Rehabilitation Channel Partnership | Exclusive clinic network agreements lock out competing brace and support equipment manufacturers from high-volume sites. |
| Biologic Formulation Licensing | Platelet-rich plasma kit manufacturers secure formulary placement through GPO contracts with United States ambulatory surgical centers. |
| Telehealth Platform Integration | Remote eccentric loading adherence tracking expands addressable geography beyond certified hand therapist supply constraints. |
| Domestic Manufacturing Scale-Up | India PLI scheme incentives reduce landed cost for therapeutic device exporters targeting price-sensitive Asian markets. |
Research Methodology
Direct dialogue with sports medicine physicians, orthopedic device procurement managers, GPO contracts specialists, and rehabilitation clinic operators grounded qualitative findings, cross-referenced against FDA 510(k) clearance databases, CMS Medicare reimbursement code filings, hospital procurement transaction records, and EU MDR notified body technical documentation. Secondary validation drew from OSHA ergonomic program filings and employer prevention program RFP data. Bottom-up procedure volume estimates triangulated with top-down manufacturer revenue attribution across the analysis window.
Bottom-up modeling segmented addressable patient pools by treatment type, product form, care setting, and administration route, with CAGRs derived from historical procedure volume trajectories and reimbursement code evolution. Top-down validation cross-checked manufacturer revenue disclosures and industry association estimates. Forecast inputs incorporated FDA 510(k) clearance velocity, EU MDR recertification timeline shifts, and OSHA mandate expansion assumptions.
Revisions become necessary when FDA pathway acceleration stalls, EU MDR enforcement intensity shifts, or employer prevention program funding cycles contract. Forecasts reflect documented assumptions about outpatient migration velocity and biologic formulation adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Personalized Medicine Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market