
 RFID Reader Market | 2026-2036
RFID Reader Market Size, Share, and Industry Trends Forecast 2026-2036
RFID Reader Market Analysis
Modular reader kits bundled with antenna arrays and software licenses is restructuring procurement patterns across enterprise buyers. Zebra Technologies leverages its channel control to dominate North American distribution networks. Impinj sustains technology leadership through specialized RAIN RFID chipsets. NXP Semiconductors anchors European automotive and industrial demand with integrated reader IC portfolios.
An RFID reader is an electronic device that interrogates radio-frequency identification tags through electromagnetic coupling, typically operating at frequencies spanning 125 kHz to 960 MHz depending on the protocol standard; its primary commercial purpose is to automate identification, tracking, and data capture without line-of-sight requirements. Handheld readers occupy the largest volume share in field service and asset tracking applications, while embedded modules represent the fastest-growing configuration as OEMs integrate interrogation capabilities directly into kiosks, vehicles, and industrial equipment. Passive technology leads unit shipments due to lower tag costs, though active RFID commands premium positioning in real-time location systems for healthcare and logistics.
The Federal Communications Commission governs UHF spectrum allocation in the United States, directly shaping reader transmission power and frequency band compliance for manufacturers selling into North America. The European Telecommunications Standards Institute mandates harmonized frequency ranges across member states, creating a unified compliance pathway that reduces fragmentation for vendors targeting the region. ETSI EN 302 208 and FCC Part 15 rules together define the regulatory perimeter that product developers must navigate. Stakeholders should monitor spectrum reallocation proceedings and emerging CE marking requirements under the Radio Equipment Directive as these frameworks will determine market access conditions and product certification burdens.
Market Dynamics
Passive UHF RFID is compressing legacy barcode infrastructure as warehouse operators mandate real-time inventory visibility without line-of-sight constraints. This frequency migration is restructuring procurement priorities across logistics, retail, and automotive verticals.
Growth Catalysts
- FCC Part 15 Rules:The Federal Communications Commission's UHF spectrum allocation enables higher transmission power for North American deployments. Retailers exploit this regulatory clarity to roll out item-level tracking at scale.
- Automotive traceability mandates:Tier-1 suppliers embed RAIN RFID readers into assembly lines for component genealogy. This end-use pull is accelerating reader module shipments into vehicle manufacturing clusters.
- ETSI EN 302 208 harmonization:The European Telecommunications Standards Institute's unified frequency range reduces vendor fragmentation. Manufacturers gain single-SKU compliance across EU member states.
Market Restraints
- Silicon supply concentration:Specialized reader IC fabrication concentrates in East Asian foundries. Geopolitical friction threatens component availability for Western OEMs.
- Active tag battery chemistry volatility:Lithium-ion cell price swings compress margins for real-time location system providers. Healthcare and logistics buyers defer fleet expansions during cost spikes.
- Metallic and liquid interference:UHF signal attenuation in dense packaging environments limits read reliability. Food and beverage processors retain barcode redundancy despite RFID pilots.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives attract reader assembly investments. Domestic supply chains for retail and pharmaceutical tracking are emerging.
- Healthcare asset tracking convergence:RFID-RTLS fusion with BLE beacons creates hybrid location intelligence. Hospital networks in Germany and the United States pilot unified platforms.
- Cloud-native reader management:SaaS-based device orchestration replaces on-premise middleware. Distributors bundle subscription licenses with hardware shipments.
Industry Challenges
- RF engineering talent scarcity:Antenna design and propagation modeling expertise concentrates in semiconductor vendors. System integrators struggle to staff field deployment teams.
- Multi-protocol certification timelines:Readers must validate against ISO 18000-63, EPC Gen2v2, and regional frequency variants. Testing backlog extends product launch windows by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFID Reader Market |
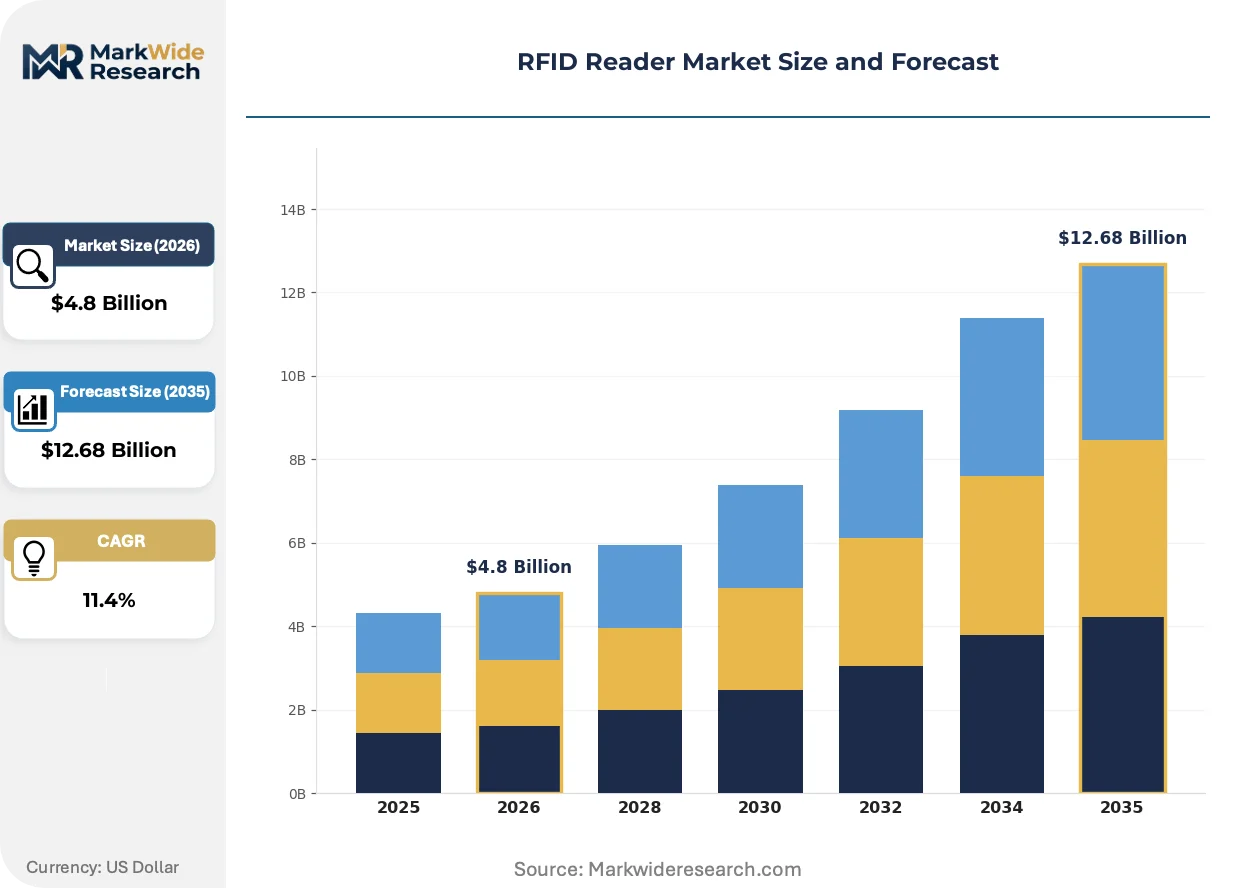
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed Mount, Desktop, Embedded Technology: Active, Passive, Semi-Passive, NFC End User: Retail, Healthcare, Logistics, Manufacturing Deployment Model: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Zebra Technologies, Impinj, NXP Semiconductors, Alien Technology, Honeywell International, Avery Dennison, Invengo Information Technology, GAO RFID, HID Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFID Reader Market Emerging Trajectories
Edge computing architectures are relocating data processing from central servers to reader firmware. This decentralization reduces latency for time-sensitive tracking applications while compressing network infrastructure costs.
AI-powered signal processing is integrating into fixed-mount reader chipsets. Automotive manufacturers deploy these modules at dock doors to filter multipath interference from metal chassis. The technology is integrating predictive maintenance alerts directly into warehouse management systems, eliminating separate sensor networks.
REACH substance restrictions are phasing out specific flame retardants in reader housing plastics. European OEMs reformulate enclosures to maintain CE marking compliance. Industrial automation suppliers in Germany accelerate material qualification to avoid stockout risks during transition periods.
Enterprise buyers now demand hardware-as-a-service contracts with bundled maintenance and firmware updates. System integrators displace traditional distributors in mid-market retail deployments. This preference shift is most visible in United States grocery chains modernizing perishable supply chains.
RFID Reader Market Segmentation
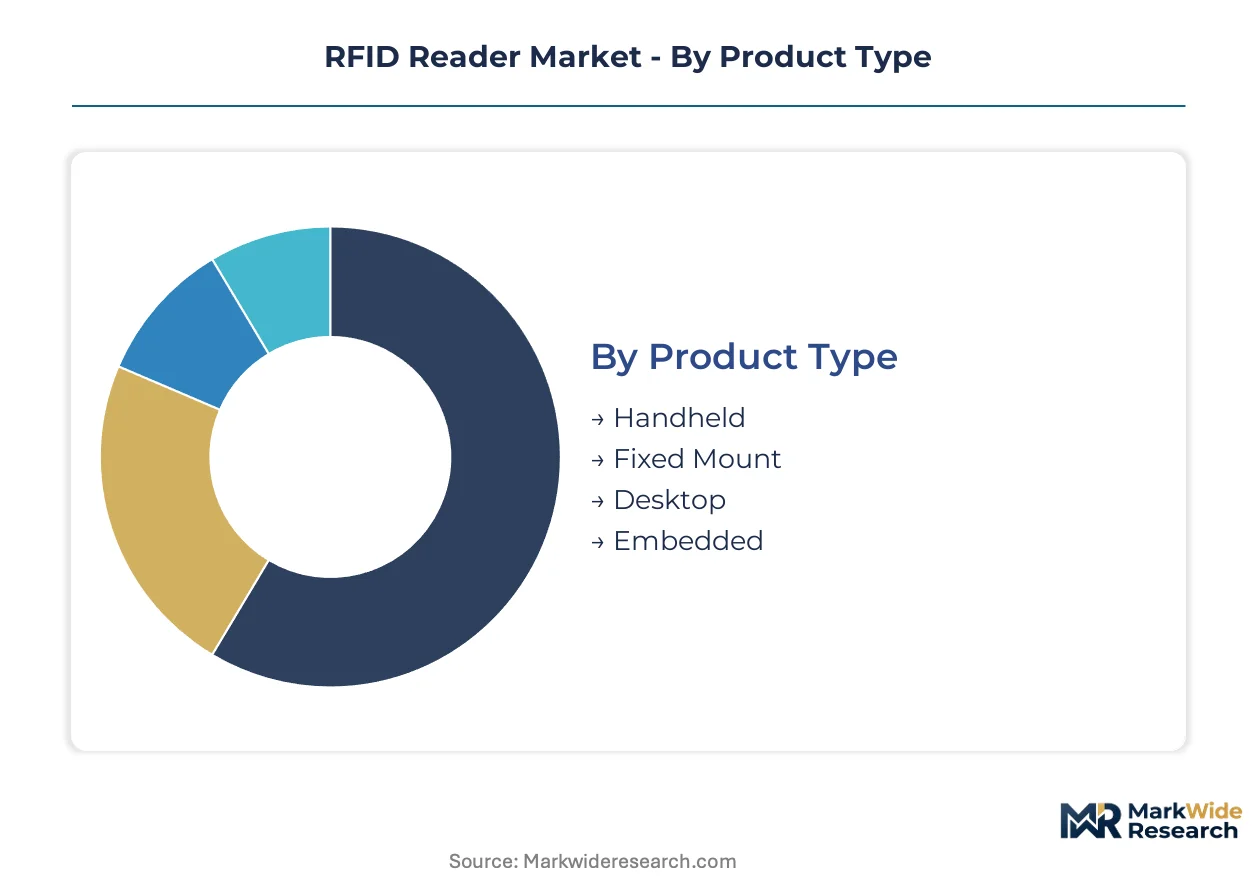
RFID reader procurement patterns diverge sharply between high-volume field deployments and premium integrated installations. Understanding these splits reveals where margin pools concentrate and which technology configurations command pricing power.
Product Type:
Volume leadership sits with portable interrogation devices, while premium value migrates toward embedded integration modules.
- Handheld:Battery-powered units with integrated antennas dominate field service and asset tracking workflows. Logistics operators in the United States deploy these for dock door and yard management, though ergonomic fatigue limits continuous scanning sessions.
- Embedded:OEM-integrated modules embed interrogation chipsets directly into kiosks, vehicles, and industrial equipment. German automotive manufacturers specify these for assembly line traceability, driving the steepest expansion trajectory as hardware disappears into larger systems.
- Fixed Mount:Stationary interrogators with external antenna arrays anchor warehouse chokepoints.
- Desktop:Compact USB-connected units serve laboratory and retail counter applications.
Today's leader: Handheld. Tomorrow's challenger: Embedded.
Technology:
Cost structure separates battery-dependent active systems from inductively coupled passive alternatives.
- Passive:UHF backscatter tags without onboard power dominate unit economics. Retail inventory pilots across China leverage these for item-level tracking, though metallic and liquid environments degrade read reliability.
- Active:Battery-assisted transponders transmit beacons for real-time location systems. Healthcare networks in Germany deploy these for surgical instrument tracking, commanding premium positioning despite lithium cell price volatility.
- Semi-Passive:Hybrid designs use battery for sensor functions while relying on reader power for communication.
- NFC:High-frequency proximity protocols enable smartphone-tap interactions for payment and access control.
Passive technology ships the most units. Active technology captures the highest per-unit value.
End User:
Application maturity varies by vertical compliance requirements and infrastructure investment cycles.
- Logistics:Warehouse operators mandate real-time inventory visibility without line-of-sight constraints. Third-party logistics providers in the United States compress legacy barcode infrastructure through UHF portal deployments at receiving and shipping docks.
- Healthcare:Asset tracking and patient identification drive sterilization-resistant reader specifications. Hospital networks prioritize RTLS convergence with BLE beacons for unified location intelligence.
- Retail:Apparel and grocery chains pilot item-level tagging for loss prevention and self-checkout.
- Manufacturing:Automotive traceability mandates pull readers into Tier-1 supplier assembly lines for component genealogy.
Logistics leads current installations. Healthcare offers the steepest expansion trajectory.
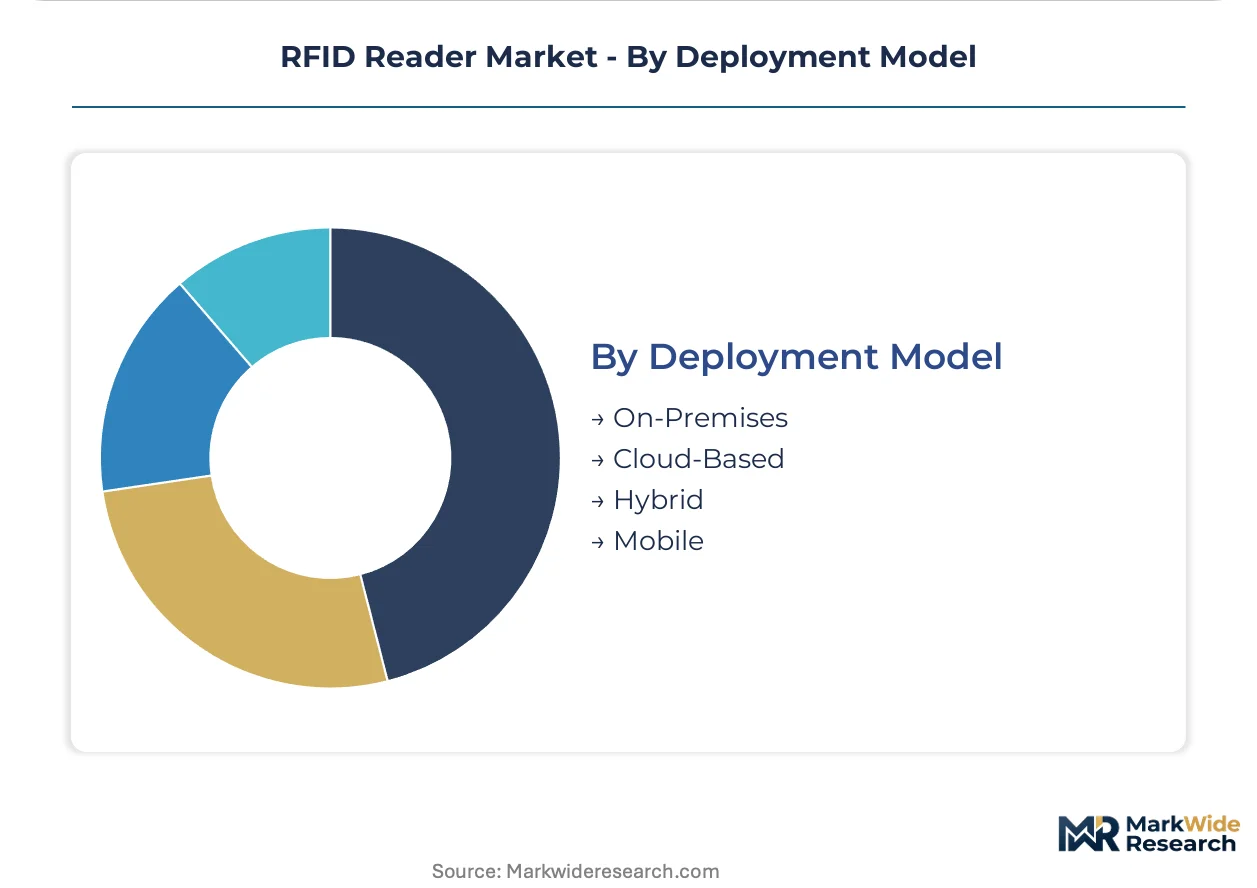
Deployment Model:
Customer IT sophistication determines whether readers operate as standalone edge devices or federated cloud nodes.
- Cloud-Based:SaaS orchestration platforms centralize firmware management and analytics across distributed reader fleets. Mid-market retail chains in the United States favor subscription bundles over capital-intensive on-premise middleware.
- Hybrid:Local edge processing with cloud analytics backup balances latency sensitivity and scalability. Industrial automation suppliers in Germany deploy these architectures to filter sensitive production data while leveraging centralized dashboards.
- On-Premises:Air-gapped installations serve defense and critical infrastructure operators with strict data sovereignty requirements.
- Mobile:Smartphone-tethered readers leverage iOS and Android devices as interrogation hosts for field service.
Hybrid architectures satisfy today's compliance-sensitive buyers. Pure cloud-native deployments are gaining share fastest among digital-native entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RFID reader manufacturing originated in North American and European industrial automation clusters during the 1990s, with early adoption driven by automotive assembly line traceability requirements. Production and deployment patterns now concentrate in five national markets where regulatory clarity and supply chain modernization intersect.
United States
Retail inventory pilots and warehouse automation projects drive reader demand across the Midwest and Southeast distribution corridors. The FCC's Part 15 rules governing UHF spectrum allocation provide transmission power advantages that accelerate item-level tracking rollouts. Chicago and Dallas-Fort Worth logistics hubs deploy portal-mounted interrogators at receiving docks to compress legacy barcode infrastructure.
China
Domestic electronics manufacturing and smart retail initiatives scale passive UHF deployments across coastal provinces. MIIT spectrum harmonization and GB standards compliance create unified certification pathways for reader vendors. Shenzhen and Shanghai industrial zones integrate embedded reader modules into automated guided vehicles and kiosk systems for factory-floor traceability.
Germany
Automotive Tier-1 suppliers mandate RAIN RFID readers for component genealogy tracking across Baden-Württemberg and Bavaria assembly clusters. ETSI EN 302 208 harmonization reduces SKU fragmentation for vendors serving EU member states. Stuttgart and Munich manufacturing belts embed interrogation capabilities directly into production line equipment.
India
Pharmaceutical serialization requirements and retail modernization programs expand reader installations across Maharashtra and Karnataka. The PLI scheme for electronics manufacturing attracts assembly investments and domestic supply chain development. Mumbai and Bangalore distribution networks pilot handheld units for last-mile asset tracking in temperature-controlled logistics.
Japan
Precision manufacturing and healthcare asset tracking sustain demand for high-reliability fixed-mount readers in Aichi and Kanagawa prefectures. METI industrial digitization guidelines encourage RFID-RTLS convergence for operational efficiency. Nagoya automotive suppliers and Yokohama medical device manufacturers specify sterilization-resistant embedded modules for cleanroom environments.
RFID Reader Market Vendor Landscape
The competitive structure tilts toward diversified industrial technology conglomerates with channel control advantages. North American and European vendors dominate premium-tier positioning through software-hardware bundling, while Asian specialists capture volume opportunities in cost-sensitive deployments. Two strategic archetypes prevail: semiconductor-integrated platform providers and modular system integrators with vertical application expertise. Capacity expansion in East Asian foundries and strategic partnerships for cloud-native reader management represent the dominant competitive moves reshaping procurement patterns.
Within the diversified technology tier, Zebra Technologies and Honeywell International occupy positions exemplifying channel-intensive distribution models. Impinj represents the specialized chipset archetype, anchoring technology leadership through RAIN RFID semiconductor portfolios. NXP Semiconductors sits within the integrated IC provider category, leveraging European automotive relationships for reader module specifications.
| Leading Market Players |
|---|
| Zebra Technologies |
| Impinj |
| NXP Semiconductors |
| Alien Technology |
| Honeywell International |
| Avery Dennison |
| Invengo Information Technology |
| GAO RFID |
| HID Global |
| Others |
Supply Flow & Price Mechanics
RF engineering talent scarcity in Taiwan and South Korea widens pricing spreads between premium and economy reader tiers, as specialized antenna design expertise commands compensation premiums that cascade through module cost structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation anchored in FCC/ETSI certification grade and after-sales service bundling. Cost compression in economy handheld units is intensifying because Chinese OEMs are flooding distribution channels with unlicensed chipset alternatives. Mid-market logistics operators exhibit highest price sensitivity, while German automotive Tier-1s prioritize traceability reliability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for reader refurbishment and antenna array remanufacturing are gaining scale as sustainability mandates extend hardware lifecycles. Manufacturing concentrates in China, Taiwan, and Vietnam, with specialized reader IC fabrication drawing from 300mm silicon wafers, copper antenna substrates, and lithium power cells for active systems. Single-source vulnerability in East Asian foundry capacity threatens Western OEM component security. Distribution runs through industrial automation distributors and system integrators rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RFID reader market functions as a stable compounder, with supply chain digitization mandates across retail and automotive providing durable replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Anticipate margin erosion from cloud-native SaaS entrants by hardening channel control through exclusive distribution partnerships with North American industrial integrators. Deepen backward integration into RAIN RFID chipset design to reduce dependence on Impinj and NXP supply allocations. Prioritize certification investment for ETSI EN 302 208 and FCC Part 15 harmonization to maintain single-SKU compliance advantages. For New Entrants and Emerging Players: The price-point gap between premium fixed-mount and economy handheld tiers offers white-space opportunity for mid-performance embedded modules targeting Indian pharmaceutical serialization and Southeast Asian retail modernization. Cloud-native reader management platforms represent the most penetrable segment, as legacy vendors struggle to transition from perpetual license models. Pursue hardware-as-a-service bundling with firmware subscription revenue to displace capital-intensive procurement patterns. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking RFID capabilities to complement existing warehouse robotics and MES software portfolios. Long-term viability rests on software-hardware integration depth rather than commoditized reader manufacturing. Monitor spectrum reallocation proceedings at the FCC and ETSI as inflection indicators for regulatory-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into RAIN RFID Chipsets | Captures margin pool currently extracted by Impinj and NXP Semiconductors. |
| Cloud-Native Reader Management Platform | Displaces on-premise middleware with SaaS orchestration for distributed fleets. |
| ETSI/FCC Dual Certification Investment | Enables single-SKU compliance across EU and North American regulatory zones. |
| Hardware-as-a-Service Contract Rollout | Aligns with mid-market retail preference for subscription over capital expenditure. |
| RFID-RTLS-BLE Hybrid Platform Development | Addresses German and US hospital demand for unified location intelligence. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with RFID hardware procurement managers, system integration specialists, semiconductor supply chain directors, and automotive Tier-1 supplier engineers with secondary validation against FCC spectrum allocation filings, ETSI standardization documents, SEC 10-K disclosures from listed vendors, and customs trade data for reader module imports. Bottom-up shipment estimates and top-down market sizing triangulated to constrain forecast variance.
Historical reference periods spanning the past decade anchored growth trajectory assumptions across the projection horizon, with analytical frameworks modeling segmentation dimensions including product configuration, frequency protocol, deployment architecture, end-use vertical, and geographic regulatory cluster. CAGRs derived from curve-fitting techniques applied to validated shipment and revenue estimates, incorporating inputs from semiconductor foundry capacity expansion schedules and retail inventory modernization capex disclosures.
Caveats apply where silicon supply concentration, spectrum reallocation proceedings, or lithium cell price volatility could materially shift the outlook. Practitioners should monitor FCC Part 15 rulemaking dockets and East Asian foundry utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Disposable Ph Sensors Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Predictive Touch Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
SCR Dosing Control Modules Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Safety Sensors Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Europe MEMS and Sensors Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Inertial Sensing Products Market