
 RF Over Fiber (Rfof) Market | 2026-2036
RF Over Fiber (Rfof) Market Size, Share, and Industry Trends Forecast 2026-2036
RF Over Fiber (Rfof) Market Outlook
Market Dynamics
Defense agency procurement for secure, interference-resistant communication links is hardening as a primary demand pillar. HUBER+SUHNER leverages its Swiss manufacturing base to dominate European defense fiber installations. EMCORE Corporation anchors North American supply through its GaAs and InP laser technology specialization. Coherent Corp. extends its position in wavelength-stabilized optical components for satellite ground stations.
Technical Foundations and Segment Structure
RF Over Fiber refers to the transmission of radio frequency signals over optical fiber cables, typically operating at wavelengths of 1310 nm or 1550 nm with bandwidth capabilities spanning DC to 40 GHz, enabling low-loss signal transport across distances exceeding 100 kilometers. The technology serves critical applications in distributed antenna systems, radar signal processing, and remote radio head connectivity where copper coaxial limitations degrade performance. Transmitters command the largest product type share due to their role in electro-optical conversion at signal origination points, while wavelength division multiplexing technology leads growth as telecom operators multiplex multiple RF channels onto single fiber strands to optimize infrastructure utilization. Military applications represent the fastest-expanding segment as defense agencies modernize electronic warfare and satellite communication architectures with EMI-immune fiber backbones.
Regulatory Environment and Strategic Outlook
The FCC governs spectrum allocation and equipment authorization for commercial RFoF deployments in the United States, while the EU AI Act and CE marking requirements under the Radio Equipment Directive shape product compliance for European market access. Defense applications face additional ITAR controls in the United States and parallel export regimes administered by national security agencies. Stakeholders must monitor evolving spectrum compression policies and defense procurement standardization to align R&D roadmaps with compliance windows and qualification timelines.
Market Dynamics
Defense procurement for EMI-immune communication backbones is compressing qualification timelines and hardening supplier requirements across the RF Over Fiber value chain. This structural pull is reshaping R&D prioritization, capital allocation, and geographic production footprints for component manufacturers.
Growth Catalysts
- FCC Spectrum Reallocation:Broadcasters in the United States are accelerating fiber-based signal distribution investments as terrestrial spectrum compression mandates phase out legacy microwave relay infrastructure.
- Electronic Warfare Modernization:Military agencies are specifying fiber-optic antenna remoting for radar and satellite ground stations to eliminate electromagnetic susceptibility in contested environments.
- Wavelength Division Multiplexing:Telecom operators are multiplexing multiple RF channels onto single fiber strands, optimizing existing infrastructure and deferring new cable deployment capital.
Market Restraints
- Indium Phosphide Supply Concentration:Laser chip fabrication depends on specialized III-V semiconductor foundries concentrated in East Asia, creating single-source vulnerability for high-performance transmitters.
- ITAR Compliance Friction:U.S. defense export controls restrict technology transfer and foreign national workforce participation, elongating procurement cycles for international joint programs.
- Copper Coaxial Incumbency:Legacy installed base in broadcast and cellular infrastructure defers fiber upgrades where distance and interference constraints remain manageable.
Strategic Opportunities
- 5G Distributed Antenna Systems:Dense urban deployments require low-loss fronthaul connectivity to remote radio heads, opening fiber penetration in commercial real estate and stadium infrastructure.
- EU Defense Procurement Harmonization:Permanent Structured Cooperation (PESCO) frameworks are standardizing secure communication specifications, creating cross-border volume aggregation for qualified suppliers.
- Photonic Integration Convergence:Silicon photonics manufacturing techniques are migrating from datacom to RFoF, promising cost reduction and chip-scale transmitter miniaturization.
Industry Challenges
- Specialized RF-Optical Engineering Talent:The intersection of microwave engineering and fiber optics requires hybrid skill sets that outpace university program output and incumbent workforce retraining capacity.
- Qualification Timeline Compression:Defense procurement cycles demand MIL-STD-810 environmental testing and NSA Suite B cryptographic certification that extend development schedules beyond commercial product lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Over Fiber (Rfof) Market |
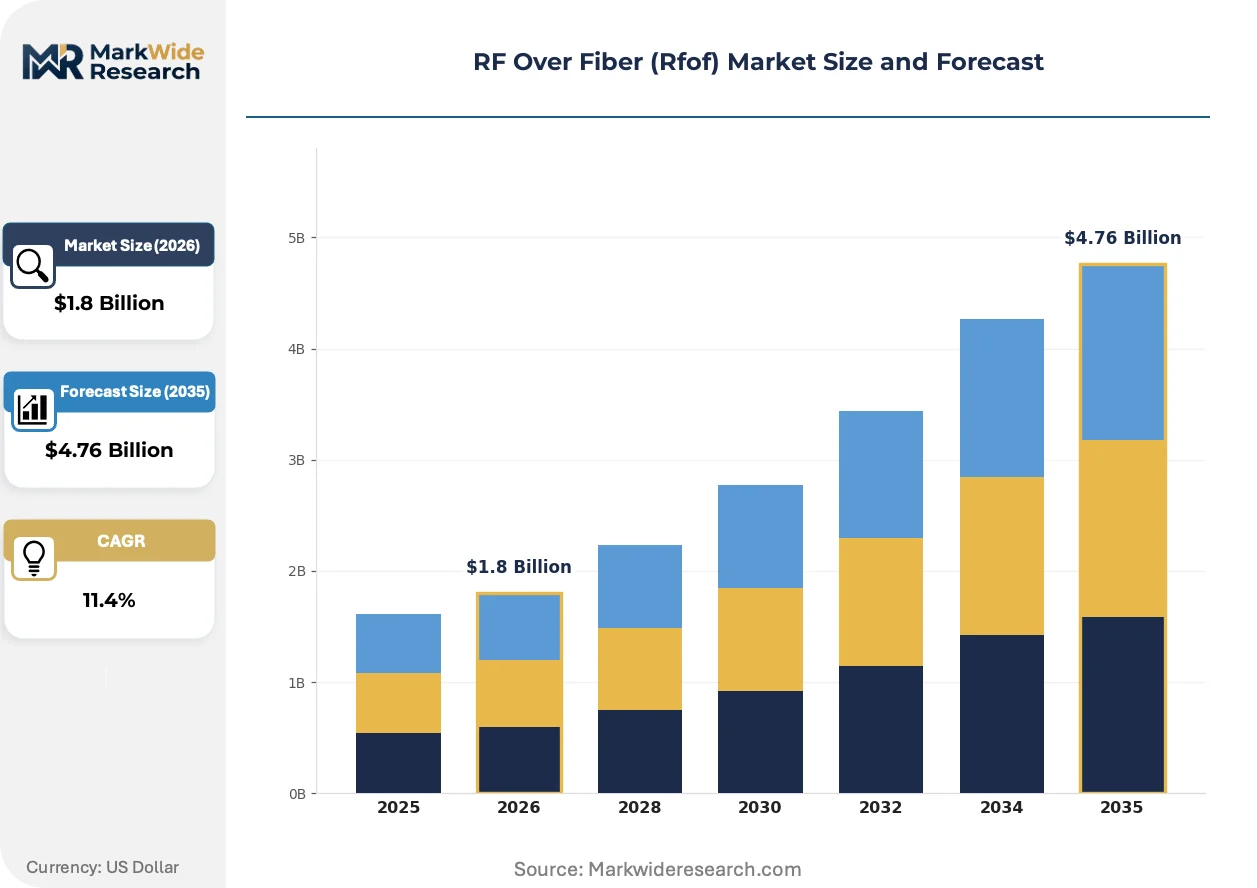
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmitters, Receivers, Repeaters, Optical Components Application: Telecommunications, Broadcast, Military, Healthcare Technology: Wavelength Division Multiplexing, Analog Transmission, Digital Transmission, Modulation Techniques End User: Telecom Operators, Broadcasters, Defense Agencies, Medical Facilities |
| Companies Covered | HUBER+SUHNER, EMCORE Corporation, Coherent Corp., G&H Group, SEIKOH GIKEN CO., LTD, Broadcom, Optical Zonu Corp, Global Foxcom, RF Optic Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Over Fiber (Rfof) Market Strategic Shifts
Photonic integration and defense procurement standardization are converging to reshape competitive positioning. Component miniaturization, regulatory harmonization, and procurement model evolution are compressing traditional supplier hierarchies and enabling new market entry pathways.
Silicon photonics-based RFoF transceivers are overtaking discrete III-V laser assemblies in cost-sensitive commercial applications. Datacom manufacturers are adapting coherent optical DSP architectures for analog RF transport. This convergence is compressing price points for 10-40 GHz links and enabling chip-scale integration previously unattainable with indium phosphide.
EU defense procurement directives under PESCO are mandating interoperable secure communication standards across member states. This harmonization is consolidating previously fragmented national specifications into unified technical baselines. Suppliers qualifying once for pooled procurement gain access to aggregated demand spanning Germany, France, Italy, and Nordic defense corridors.
Performance-based logistics contracts are displacing traditional hardware purchase models in military RFoF programs. Prime contractors now contract for availability and signal integrity uptime rather than equipment delivery. This shift concentrates risk with suppliers while aligning incentives for predictive maintenance and rapid field replacement in United States Pacific Command and European theater deployments.
RF Over Fiber (Rfof) Market Segmentation
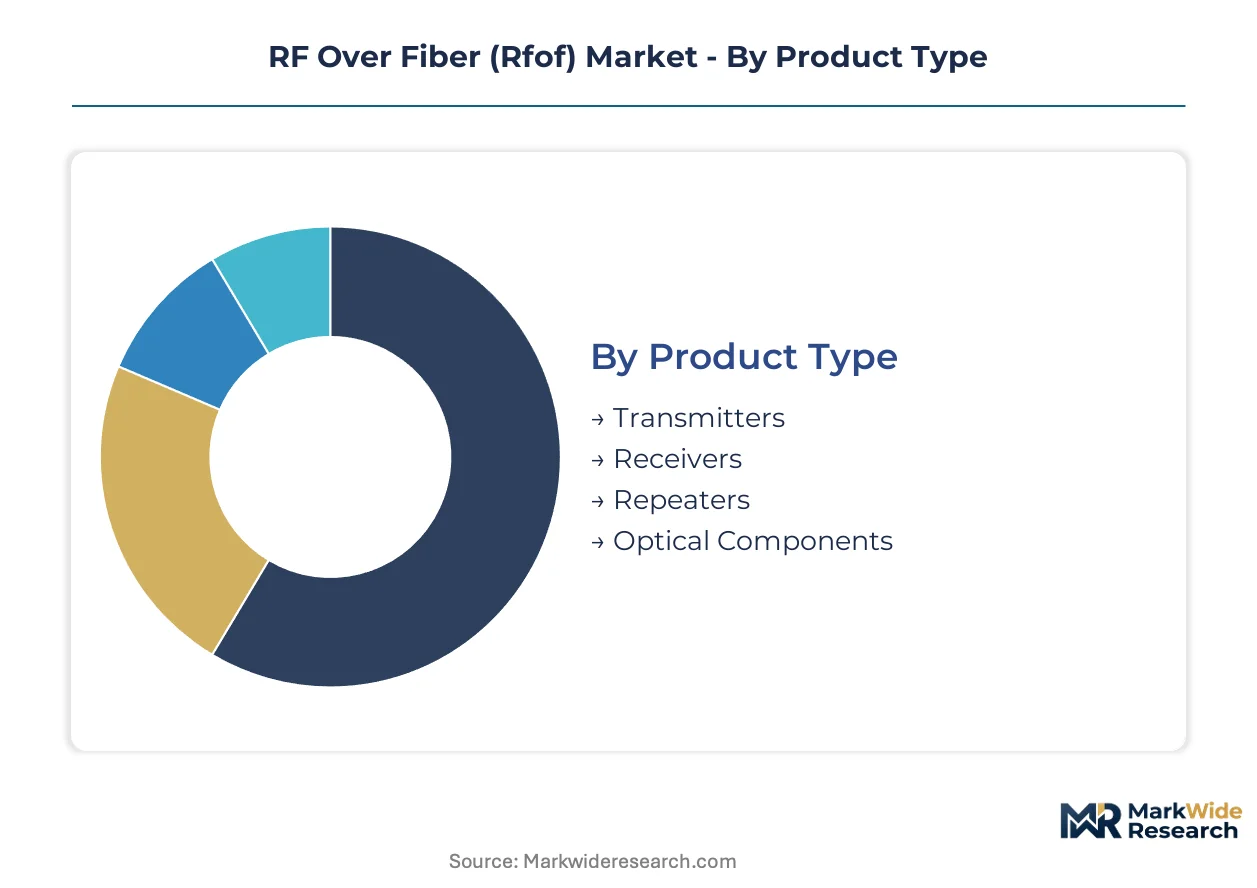
RF Over Fiber procurement patterns diverge sharply across defense, broadcast, and telecom verticals, with each end-use imposing distinct bandwidth, environmental, and security specifications on component suppliers.
Product Type:
Component architecture determines signal fidelity thresholds and thermal management requirements across deployment environments.
- Transmitters:Electro-optical conversion modules utilizing 1310 nm or 1550 nm laser diodes perform the critical signal origination function in antenna remoting systems. Pentagon-adjacent defense corridors in the United States concentrate procurement for EMI-immune transmitter arrays in satellite ground stations and electronic warfare platforms.
- Receivers:Photodetector assemblies with InGaAs or Ge photodiodes convert optical signals back to RF with minimal noise figure degradation. Dense urban 5G fronthaul deployments in United States metropolitan areas drive receiver volume for distributed antenna system backhaul.
- Repeaters:Signal regeneration nodes extend transmission distances beyond passive fiber limitations.
- Optical Components:Circulators, isolators, and wavelength-selective filters condition signal paths.
Mature deployment sits with transmitters. Newer deployment is concentrated in optical components for integrated photonic subassemblies.
Application:
End-use environments impose divergent qualification regimes and lifecycle cost structures on RFoF system suppliers.
- Military:Electronic warfare and satellite communication architectures demand MIL-STD-810 environmental hardening and NSA Suite B cryptographic certification for fiber-optic antenna remoting. United States Pacific Command theater deployments compress qualification timelines while mandating ITAR-controlled supply chains.
- Telecommunications:5G fronthaul and midhaul networks require low-latency, high-bandwidth signal transport to remote radio heads. United States spectrum reallocation policies accelerate fiber-based infrastructure replacement of legacy microwave relay systems.
- Broadcast:FCC-mandated spectrum compression forces terrestrial broadcasters toward fiber distribution.
- Healthcare:MRI and proton therapy facilities utilize RFoF for interference-free signal routing in electromagnetically sensitive clinical environments.
Established infrastructure investment centers on telecommunications. Steepest expansion trajectory belongs to military applications as contested environment communication resilience hardens as a procurement priority.
Technology:
Signal encoding and multiplexing approaches determine spectral efficiency and infrastructure utilization economics.
- Wavelength Division Multiplexing:DWDM and CWDM architectures multiplex multiple RF channels onto single fiber strands, optimizing existing cable plant utilization. Telecom operators in the United States deploy WDM-enabled RFoF to defer new fiber deployment capital while scaling fronthaul capacity.
- Analog Transmission:Direct intensity modulation preserves signal waveform integrity for radar and electronic warfare applications requiring minimal latency and phase distortion. United States defense agencies specify analog links for time-critical threat detection systems.
- Digital Transmission:Digitized RF transport enables signal processing and encryption at the optical layer.
- Modulation Techniques:Advanced modulation formats including QAM and OFDM extend spectral efficiency in bandwidth-constrained deployments.
Volume concentration rests with analog transmission. Technology migration is accelerating toward wavelength division multiplexing as infrastructure optimization pressures intensify.
End User:
Procurement authority and budget cycles shape supplier engagement models and contract structures across customer categories.
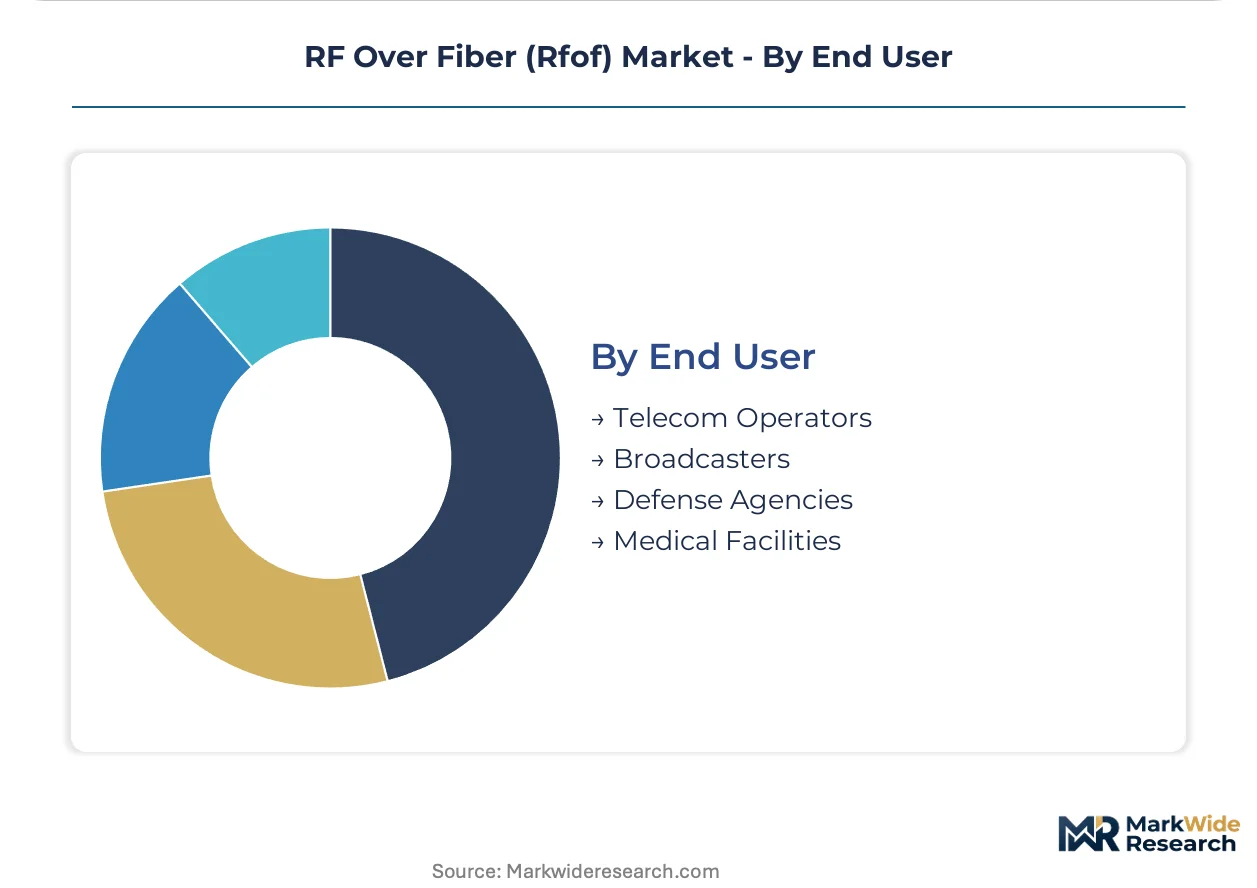
- Defense Agencies:United States Department of Defense and aligned NATO entities specify performance-based logistics contracts emphasizing signal integrity uptime over equipment delivery. ITAR compliance requirements restrict supplier pools to domestic and cleared foreign sources.
- Telecom Operators:AT&T, Verizon, and T-Mobile procurement organizations drive commercial RFoF volume through 5G network densification programs. Capital expenditure cycles align with FCC spectrum auction timelines and infrastructure depreciation schedules.
- Broadcasters:Network affiliates and station groups execute fiber transition investments in response to spectrum repack mandates.
- Medical Facilities:Hospital systems and proton therapy centers procure isolated RFoF links for diagnostic and therapeutic equipment integration.
Contract maturity concentrates with broadcasters. Procurement transformation is most pronounced among defense agencies as availability-based contracting displaces traditional hardware acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement corridors and broadcast infrastructure clusters concentrate RF Over Fiber deployment in tax-advantaged zones near government installations and metropolitan media hubs.
United States
Pentagon-adjacent corridors in Northern Virginia and Maryland drive classified communication backbone installations. FCC spectrum reallocation mandates compress broadcaster transition timelines. Greater Los Angeles and New York City media markets anchor fiber distribution network densification for terrestrial broadcast repack.
Germany
Bundeswehr electronic warfare modernization programs specify EMI-immune antenna remoting for contested environment resilience. EU defense procurement harmonization under PESCO frameworks aggregates cross-border demand. Bavaria's aerospace and defense manufacturing belt concentrates subsystem integration for NATO-aligned satellite ground stations.
China
MIIT spectrum management policies accelerate fiber-based infrastructure replacement in metropolitan 5G deployments. State-directed capital flows concentrate in Yangtze River Delta photonics manufacturing clusters. Shenzhen and Shanghai anchor domestic supply chain verticalization for laser diode and optical component production.
Japan
METI industrial technology roadmaps prioritize photonic integration for next-generation communication hardware. Domestic broadcasters migrate to fiber distribution following Ministry of Internal Affairs spectrum efficiency directives. Tokyo-Osaka corridor concentrates precision optical component manufacturing for defense and commercial dual-use applications.
United Kingdom
Ministry of Defence satellite communication upgrades specify fiber-optic ground station architectures. Ofcom spectrum licensing reforms pressure broadcast infrastructure modernization. South England technology corridors around Cambridge and Oxford concentrate photonics R&D for defense-qualified subsystem suppliers.
RF Over Fiber (Rfof) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with defense procurement favoring qualified incumbents while commercial telecom opens to cost-optimized challengers. The supplier base organizes into three tiers: integrated photonics conglomerates with captive semiconductor fabrication, specialized RF-optical component houses with MIL-STD qualification heritage, and emerging silicon photonics players leveraging datacom manufacturing scale. Consolidation pressure intensifies as defense contracts concentrate volume with fewer qualified sources and commercial price compression favors scale economies.
Within the defense-qualified tier, HUBER+SUHNER, EMCORE Corporation, and Coherent Corp. occupy positions anchored by regulatory certification depth and geographic production footprint control. Swiss and North American manufacturing bases support ITAR and EU defense procurement compliance requirements. These incumbents exemplify the archetype of vertically integrated specialists with captive optical component design and environmental testing capabilities that elongate competitor qualification timelines.
| Leading Market Players |
|---|
| HUBER+SUHNER |
| EMCORE Corporation |
| Coherent Corp. |
| G&H Group |
| SEIKOH GIKEN CO., LTD |
| Broadcom |
| Optical Zonu Corp |
| Global Foxcom |
| RF Optic Ltd. |
| Others |
Value Chain & Pricing Dynamics
MIL-STD-810 certification tiering bifurcates component sourcing between defense-qualified foundries and commercial-grade suppliers, with ITAR-compliant production lines commanding premium positioning while silicon photonics fabrication in Taiwan and China anchors economy-tier transmitter costs. This certification ladder simultaneously shapes procurement timelines and geographic supplier selection, compressing margins at the commercial tier while insulating qualified incumbents from price erosion.
Pricing Analysis
Expedited qualification timelines for Pentagon-adjacent defense corridors command substantial premiums over standard commercial lead times, with ITAR-controlled supply chains pricing at significant elevation above spot-market III-V laser components. Project-based contracting dominates defense procurement, while telecom operators negotiate volume-scale agreements for 5G fronthaul deployments. Price differentiation hinges on NSA Suite B cryptographic certification and MIL-STD environmental testing completion. Cost compression in commercial silicon photonics transmitters intensifies as datacom manufacturers enter RFoF markets. Broadcasters exhibit highest price sensitivity due to FCC-mandated transition timelines with constrained capital budgets.
Supply Chain Analysis
Indium phosphide wafer supply rests on specialized III-V semiconductor foundries concentrated in Taiwan, Japan, and the United States, with epitaxial growth capacity tethered to East Asian equipment manufacturers. Laser diode fabrication draws from InP substrates, GaAs epitaxy, and precision optical coating inputs. Single-source vulnerability concentrates in high-performance transmitter chip supply, with tariff exposure escalating for EU defense procurement dependent on U.S. ITAR-controlled sources. Distribution runs through qualified subsystem integrators for military applications and direct OEM relationships for telecom volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
III-V semiconductor foundry capacity constraints prop pricing power for qualified suppliers, with defense procurement timelines extending beyond commercial product lifecycles and concentrating volume with certified incumbents.
For Market Incumbents: Anchor MIL-STD-810 qualification depth against silicon photonics challengers by accelerating photonic integration roadmaps and securing captive InP wafer supply through backward integration into epitaxial growth. Defend position by expanding environmental testing facilities in Switzerland and North America to compress competitor qualification timelines. For New Entrants and Emerging Players: Direct-to-defense-contractor digital procurement platforms offer lowest-friction entry paths for ITAR-compliant component suppliers seeking bypass of traditional prime contractor gatekeeping. Target commercial 5G distributed antenna system deployments as most penetrable segment, leveraging cloud-native network management tools as differentiated go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with silicon photonics specialists given defense procurement standardization under PESCO frameworks creating cross-border volume aggregation. Long-term viability centers on dual-use technology positioning across commercial telecom and military applications. Watch ITAR compliance timeline compression as inflection indicator for qualified supplier scarcity premium.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integration Roadmap Acceleration | Silicon photonics manufacturing migration from datacom compresses 10-40 GHz transmitter costs for commercial 5G deployments. |
| ITAR-Compliant Foundry Capacity Expansion | Domestic III-V semiconductor fabrication insulates defense suppliers from East Asian single-source vulnerability and tariff exposure. |
| PESCO Qualification Investment | EU defense procurement harmonization aggregates cross-border demand for suppliers meeting unified secure communication specifications. |
| Performance-Based Logistics Contracting | Availability-based military procurement aligns supplier incentives with signal integrity uptime rather than equipment delivery. |
| Silicon Photonics Transceiver Launch | Chip-scale integration enables cost-competitive entry into commercial distributed antenna system markets previously dominated by discrete lasers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with RF-optical component engineering directors, defense procurement officers at Pentagon-adjacent installations, telecom network planning executives, and broadcast infrastructure managers. FCC spectrum reallocation dockets, ITAR compliance documentation, and EU PESCO framework directives provided regulatory validation. Bottom-up transmitter and receiver shipment aggregation triangulated against top-down defense budget allocation analysis.
Segment-level modeling operated at product type, application, technology, and end user dimensions, with geographic granularity at country level for United States, Germany, China, Japan, and United Kingdom. CAGRs derived from regression analysis against defense modernization budget trajectories and 5G capital expenditure cycles. III-V semiconductor foundry capacity utilization and silicon photonics yield improvement curves served as technology-specific forecast inputs across the projection horizon.
The model holds under stable ITAR compliance enforcement and continued FCC spectrum compression; deviation in defense procurement acceleration or photonic integration breakthrough timelines would shift volume concentration between analog and digital transmission architectures. Forecasts reflect documented assumptions regarding qualification timeline compression and foundry capacity expansion. Regulatory harmonization progress and export control policy evolution warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
China Small Signal Transistor Market
RF Components
Global RF Transceiver Market
RF Components
Coaxial Connectors (RF) Market
RF Components
Z-Wave Products Market
RF Components
Global Inductors Market
RF Components
Monolithic Microwave Integrated Circuit (MMIC) Market
RF Components
Gan RF Semiconductor Devices Market
RF Components
RF Interconnect Market
RF Components
Radio Frequency Front End Module Market
RF Components
RF Power Amplifiers Market
RF Components
Multi-Mode Receiver Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
Silicon Tuners Market
RF Components
Small Signal Mosfets Market
RF Components
Space Traveling Wave Tube Amplifiers Market
RF Components
RF Duplexer Market