
 US Wallpaper Market | 2026-2036
US Wallpaper Market Size, Share, and Industry Trends Forecast 2026-2036
US Wallpaper Market Insights
The US wallpaper market is decoupling along a sharp quality divide, with artisan-grade digital prints commanding sustained margin premiums while mass-market vinyl rolls face price compression from imported alternatives. York Wallcoverings leverages its century-old archive and domestic manufacturing footprint to anchor the heritage premium tier. Brewster Home Fashions competes through vertical control over its supply chain and aggressive wholesale distribution across big-box retail channels. Tempaper & Co. differentiates via peel-and-stick technology leadership that captures the DIY renovation segment without contractor dependency.
Wallpaper comprises decorative wall coverings manufactured from paper, vinyl, fabric, or non-woven substrates, typically printed with solvent-based or UV-cured inks and applied with paste or self-adhesive backing to interior vertical surfaces for aesthetic enhancement and surface protection. Non-woven substrates are displacing traditional paper backings in commercial specifications due to dimensional stability during installation and strippability during renovation cycles. The hospitality application segment leads volume contribution as hotel chains prioritize branded interior environments, while online distribution channels are capturing the fastest growth trajectory among contractor and consumer procurement pathways.
The EPA enforces VOC limits under TSCA Title VI that constrain solvent-based ink formulations, while OSHA regulates workplace chemical exposure during manufacturing, and California's Department of Public Health maintains CDPH Standard Method v1.2 for indoor air quality certification that many commercial specifiers now mandate. These overlapping standards are elevating compliance costs for smaller mills while creating market access barriers for uncertified imports. Stakeholders must monitor evolving state-level chemical disclosure requirements and decide whether to absorb certification investments or retreat toward unregulated residential segments.
Market Dynamics
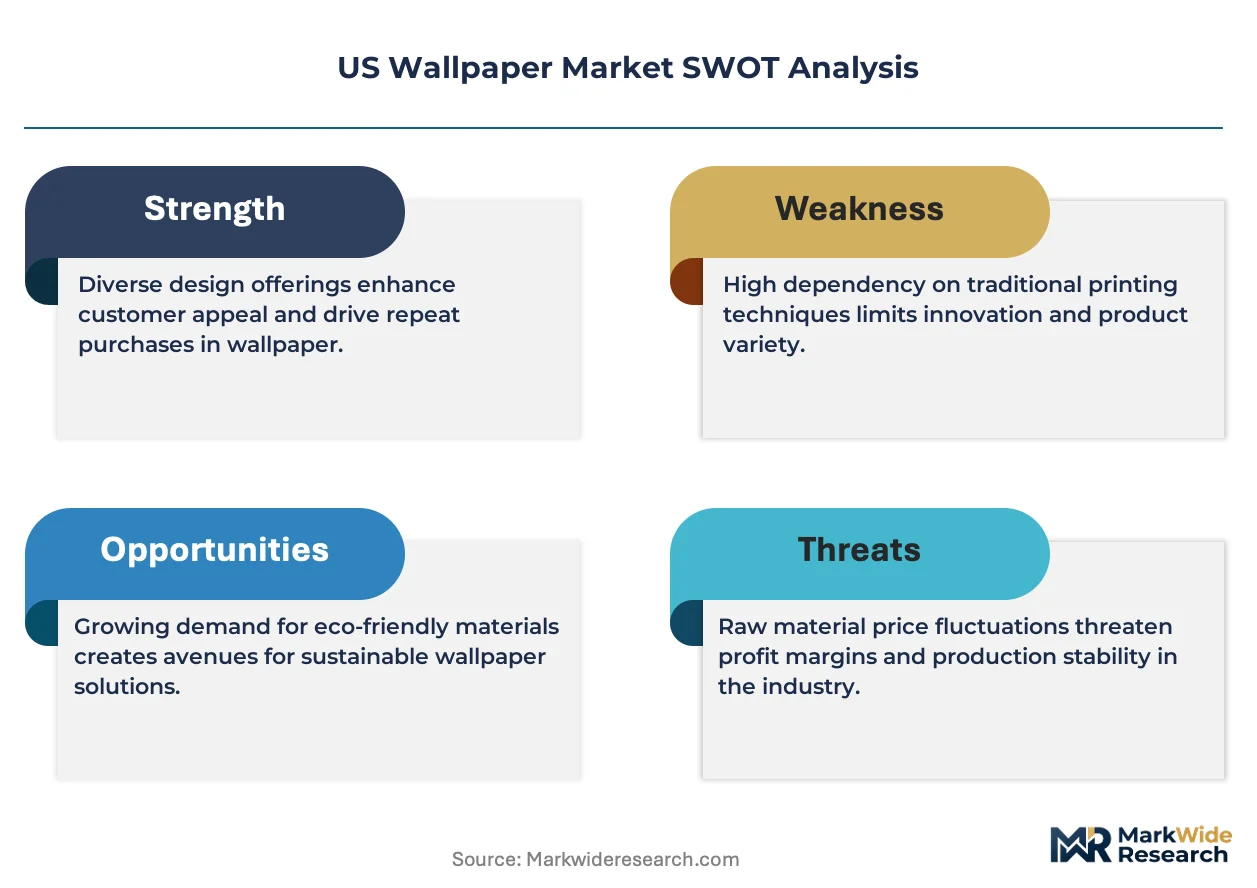
Water-based ink chemistry is redefining US wallpaper manufacturing economics as EPA TSCA Title VI enforcement tightens solvent emission limits, forcing capital retooling across domestic mills while advantaging early adopters with certified supply chains.
Growth Catalysts
- Hospitality Renovation Cycles:Hotel chains are specifying branded wall coverings at scale, driving volume demand for durable vinyl and non-woven substrates that withstand high-traffic turnover.
- CDPH v1.2 Certification:California's indoor air quality standard is becoming a de facto national benchmark for commercial specifiers, creating pull-through demand for compliant products across state lines.
- Peel-and-Stick Formulation Advances:Pressure-sensitive adhesive technology is eliminating contractor dependency for residential installations, opening DIY renovation segments previously served by paint.
Market Restraints
- Petrochemical Input Volatility:Vinyl resin and synthetic adhesive feedstocks track crude oil derivatives, compressing margin predictability for mass-market producers without hedging programs.
- Import Concentration Risk:Uncertified Asian-manufactured rolls dominate economy pricing tiers, creating downward price pressure that domestic mills struggle to match without sacrificing emission compliance.
- Dimensional Stability Tradeoffs:Traditional paper backings remain cheaper but fail commercial strippability requirements, locking smaller mills out of hospitality and healthcare specifications.
Strategic Opportunities
- Texas Construction Corridor:Dallas-Fort Worth and Houston metro areas are outpacing national new-build averages, creating regional demand concentration for builder-grade and designer-specified wall coverings.
- Healthcare Acoustic Applications:Fabric-backed vinyl with sound-absorbing substrates is penetrating hospital and clinic renovations where infection control meets noise reduction mandates.
- Online Contractor Platforms:Digital procurement channels are capturing specification influence previously held by traditional distributors, enabling direct manufacturer-to-installer relationships.
Industry Challenges
- Skilled Installer Shortage:Pattern matching and non-woven application techniques require trained crews, and contractor capacity constraints are lengthening project timelines in high-demand metros.
- Certification Timeline Compression:CDPH and EPA validation cycles for reformulated inks are extending product launch windows, delaying revenue recognition for R&D investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wallpaper Market |
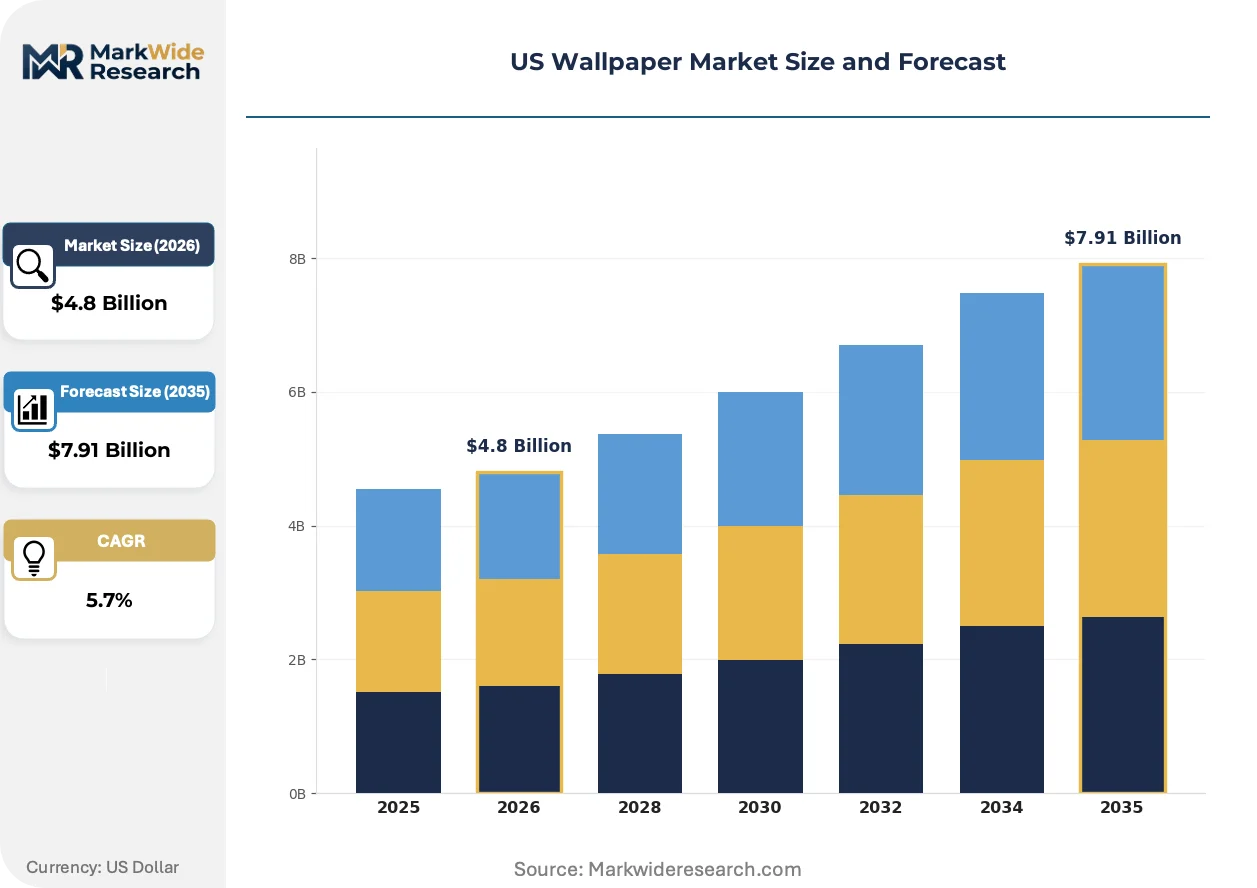
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Fabric, Paper, Non-Woven Application: Residential, Commercial, Hospitality, Healthcare Design Style: Modern, Classic, Vintage, Abstract Distribution Channel: Online, Retail, Wholesale, Contractors |
| Companies Covered | Tempaper & Co., Wallquest, York Wallcoverings, Milton & King, Monadnock Paper Mills, Brewster Home Fashions, Sherwin-Williams, Flavor Paper, F. Schumacher & Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wallpaper Market Trends and Innovations
Digital printing infrastructure is rewiring production economics and design possibilities simultaneously, collapsing minimum order quantities while enabling mass customization that analog rotogravure cannot match.
UV-cured inkjet systems are expanding into short-run artisan production, enabling boutique studios to offer photographic murals and bespoke patterns without plate-making overhead. Hospitality designers are adopting these capabilities for property-specific branded environments. The technology is compressing lead times from weeks to days for custom specifications.
EPA enforcement of TSCA Title VI is tightening volatile organic compound limits for solvent-based formulations, elevating compliance costs for legacy production lines. Manufacturers are responding with water-based chemistry investments and substrate modifications. California's CDPH Standard Method v1.2 is extending beyond state borders as commercial specifiers adopt it as a national procurement filter.
Specification influence is migrating from traditional distributor relationships toward online visualization tools that let architects and interior designers preview installations digitally. Big-box retail and direct-to-consumer channels are capturing residential renovation decisions previously mediated by contractors. This shift is most pronounced in coastal metropolitan markets where DIY renovation rates exceed national averages.
US Wallpaper Market Segmentation
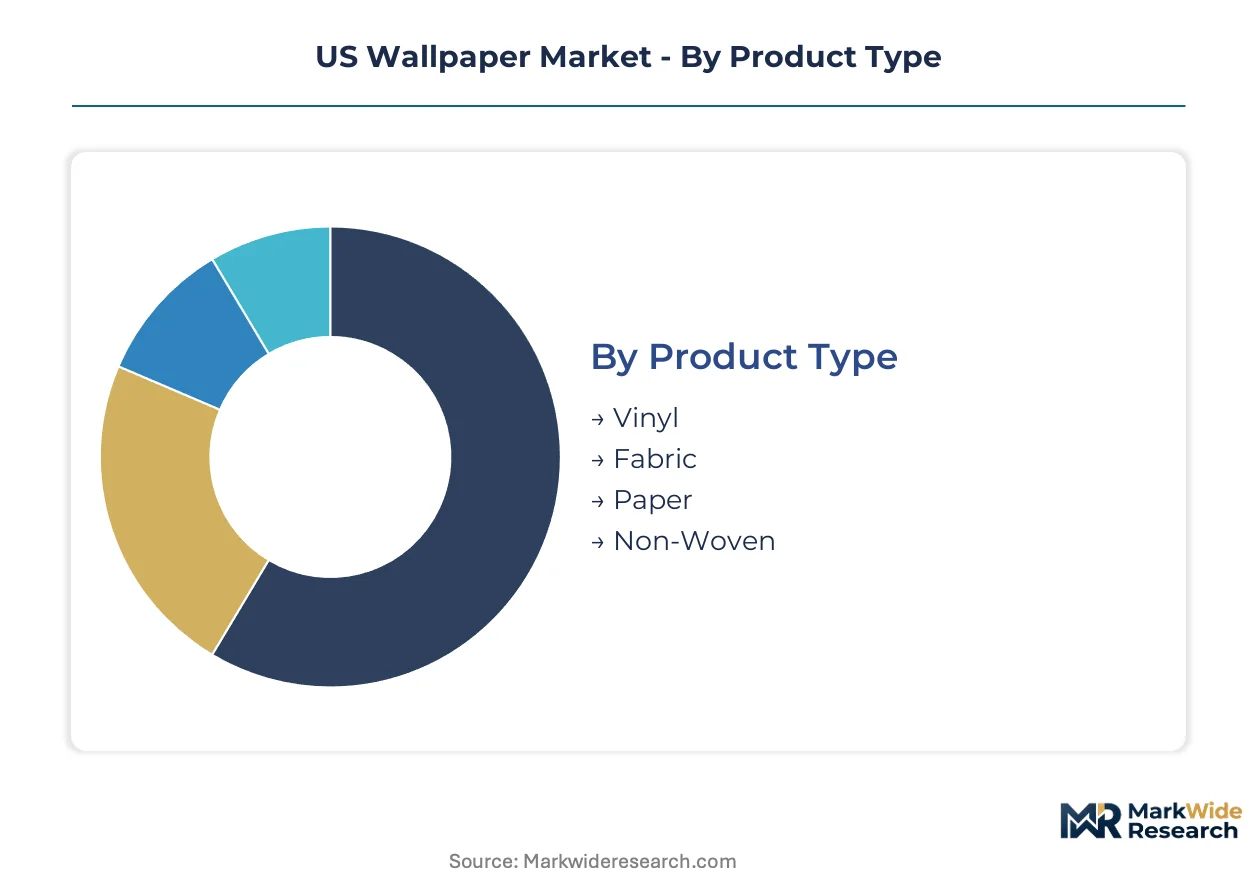
Wallpaper manufacturers must align production capabilities with distinct specification requirements across substrate technologies, end-use environments, and procurement pathways. Each segmentation dimension carries different margin profiles, certification burdens, and installation complexity that shape competitive positioning.
Product Type:
Upgrade cycles from traditional paper to engineered substrates are accelerating as commercial strippability mandates and EPA emission standards reshape material specifications.
- Vinyl:Polyvinyl chloride resin formulations deliver moisture resistance and scrubbability for high-traffic hospitality corridors. Hotel chains in Texas and California specify vinyl for branded property rollouts where durability outweighs first-cost premiums.
- Non-Woven:Synthetic fiber substrates bonded without woven structure provide dimensional stability during paste application and clean removal during renovation. Healthcare facilities prefer non-woven for infection-control zones requiring frequent surface updates.
- Fabric:Textile backings with vinyl or acrylic coatings serve acoustic dampening applications in hospital patient rooms and open-plan offices.
- Paper:Traditional cellulose backings retain cost advantage for residential accent walls where strippability is not specified.
Vinyl sits at the top of the volume ranking, with non-woven climbing the fastest as commercial specifications tighten removal-cycle requirements.
Application:
End-use concentration varies sharply by project scale, with single-property renovations demanding different fulfillment models than national chain rollouts.
- Hospitality:Hotel chains commission branded wall coverings across property portfolios, requiring color consistency and fire-rating compliance at volume. Major operators in Dallas-Fort Worth and Houston drive specification pull-through for durable substrates.
- Residential:Homeowners select peel-and-stick and traditional paste products through retail and direct channels, with coastal metros showing strongest DIY adoption.
- Commercial:Office and retail fit-outs specify non-woven and vinyl for lease-cycle flexibility, with CDPH v1.2 certification increasingly mandatory.
- Healthcare:Hospitals require fabric-backed acoustic products and scrubbable vinyl for patient rooms and corridors, with infection-control protocols driving substrate selection.
Hospitality captures the highest volume concentration, while residential channels are gaining share fastest through online visualization tools and contractor-free installation formats.
Design Style:
Digital printing infrastructure has collapsed minimum order quantities, enabling style proliferation that analog rotogravure could not economically support.
- Modern:Clean geometries and solid fields align with contemporary hospitality and residential interiors, produced efficiently through digital inkjet systems.
- Classic:Damasks and traditional motifs serve heritage property renovations and upscale residential specifications requiring pattern matching expertise.
- Vintage:Archive reproductions and distressed aesthetics target boutique hotel differentiation and residential statement walls.
- Abstract:Non-representational patterns and photographic murals leverage digital printing for bespoke commercial environments and residential customization.
Modern styling leads specification frequency, with abstract designs expanding most quickly as digital production enables photographic and bespoke capabilities.
Distribution Channel:
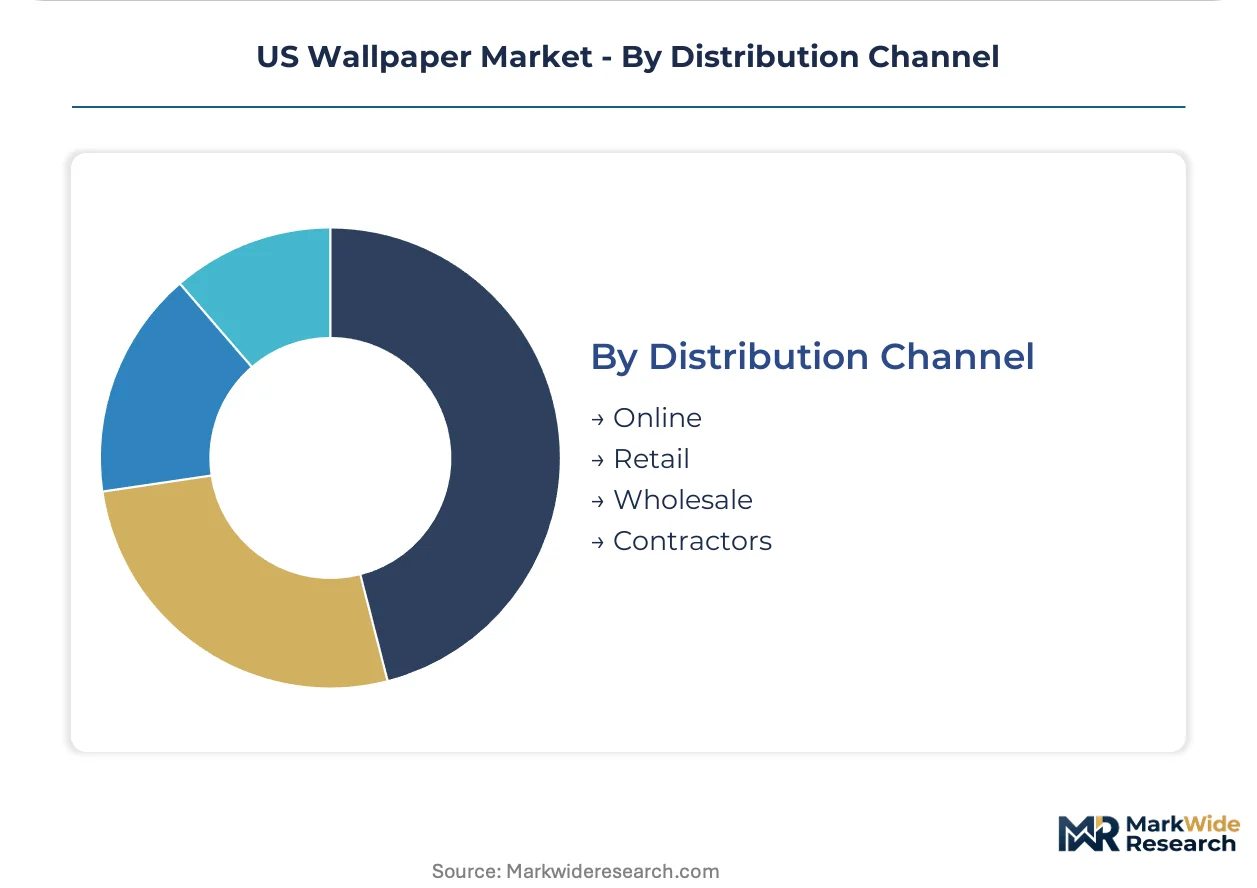
Procurement pathways are fragmenting as specification influence migrates from traditional distributor relationships toward digital platforms and direct manufacturer engagement.
- Online:Direct-to-consumer and contractor-facing platforms capture residential and small commercial orders, with visualization tools reducing sample dependency. Coastal metropolitan markets show highest conversion rates.
- Contractors:Installation professionals specify products for residential and commercial clients, though skilled crew shortages are lengthening project timelines in high-demand metros.
- Retail:Big-box and specialty stores serve DIY renovators with peel-and-stick and traditional paste products, inventory concentrated in California and Texas population centers.
- Wholesale:Distributor networks maintain specification relationships with architects and designers for commercial and hospitality projects, though their influence is compressing.
Contractor channels still handle the largest project volumes, with online platforms showing the steepest expansion trajectory as digital procurement tools capture specification decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's hospitality renovation intensity contrasts with Texas's new construction velocity, creating divergent demand profiles within the same national market. EPA emission enforcement and state-level air quality standards further differentiate procurement requirements across major metros.
California
Los Angeles and San Francisco hotel renovation cycles drive premium substrate specifications, with boutique properties commissioning custom digital prints. The California Department of Public Health enforces CDPH Standard Method v1.2 for indoor air quality certification, which commercial specifiers now treat as a national benchmark. San Diego's healthcare facility expansion is pulling acoustic fabric-backed vinyl into hospital corridors and patient rooms.
Texas
Dallas-Fort Worth and Houston metro construction is outpacing national averages for both residential new-build and commercial retrofit activity. The Texas Commission on Environmental Quality aligns with federal TSCA Title VI standards while allowing faster permitting for low-emission manufacturing facilities. Austin's tech sector office buildouts are specifying strippable non-woven substrates for lease-cycle flexibility.
New York Metro
Manhattan hospitality and luxury residential sectors sustain demand for heritage-patterned wall coverings requiring skilled installation. New York State Department of Environmental Conservation regulations mirror EPA VOC limits while adding disclosure requirements for chemical content. Brooklyn's design studio concentration is incubating boutique digital print operations serving boutique hotel chains.
Southeast
Florida's retirement community construction and Georgia's logistics facility buildouts create divergent demand streams for residential and commercial specifications. State environmental agencies defer to federal EPA standards without additional state-level chemical certification mandates. Atlanta's corporate headquarters relocations are driving office interior specification volume for non-woven commercial grades.
Pacific Northwest
Seattle and Portland residential markets show elevated DIY renovation rates, accelerating peel-and-stick product penetration through direct-to-consumer channels. Oregon and Washington environmental agencies enforce EPA-aligned standards with additional focus on sustainable forestry certification for paper-based substrates. Portland's design-forward residential construction scene favors abstract and vintage aesthetic specifications.
US Wallpaper Market Competitive Landscape
Top-tier vendors anchor the heritage premium tier, while mass-market fabricators compete through supply chain efficiency and wholesale distribution scale. The market structure stratifies across three distinct tiers: century-old domestic mills with archive libraries, vertically integrated wholesalers controlling big-box retail placement, and technology-driven specialists capturing contractor-independent installation segments. Two strategic archetypes dominate competitive positioning: heritage manufacturers leveraging domestic production footprints for emission compliance, and digital-native entrants collapsing fulfillment timelines through direct channels. Consolidation pressure is intensifying as certification costs disadvantage smaller mills, while strategic partnerships between substrate suppliers and ink formulators are locking in compliant supply chains.
Among heritage-tier domestic manufacturers, York Wallcoverings exemplifies the archive-driven positioning that commands specification loyalty in hospitality and upscale residential channels. Tempaper & Co. occupies a distinct technology-leadership position through peel-and-stick formulation advances that eliminate contractor dependency. Brewster Home Fashions represents the wholesale-distribution archetype, leveraging vertical control over supply chain and retail placement to capture volume in builder-grade and mass-market segments.
| Leading Market Players |
|---|
| Tempaper & Co. |
| Wallquest |
| York Wallcoverings |
| Milton & King |
| Monadnock Paper Mills |
| Brewster Home Fashions |
| Sherwin-Williams |
| Flavor Paper |
| F. Schumacher & Co. |
| Others |
Pricing and Supply Chain Analysis
Vinyl resin feedstock costs cascade through three distinct pricing tiers as petrochemical volatility compresses margins at the mass-market end while heritage manufacturers absorb fluctuations through archive-premium positioning. Water-based ink reformulation investments required by EPA TSCA Title VI compliance are widening the cost gap between certified domestic production and uncertified import alternatives.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for economy-grade vinyl rolls, forcing domestic mills toward premium-mid-economy pricing differentiation anchored in emission certification and design archive depth. Price differentiation rests on CDPH v1.2 compliance status and domestic manufacturing footprint, with hospitality specifiers paying premiums for certified supply chains. Pricing pressure stems from import concentration in big-box retail channels, where contractor-grade buyers show highest price sensitivity and boutique hotel designers demonstrate lowest.
Supply Chain Analysis
Container freight rates from Chinese manufacturing hubs to Los Angeles and Long Beach ports directly determine landed cost competitiveness for imported rolls competing against domestic production. Raw material sourcing draws from South Korean and Japanese synthetic fiber suppliers for non-woven substrates, German ink formulators for UV-cured systems, and domestic petrochemical producers for vinyl resin. Single-source vulnerability concentrates in Asian substrate supply, with distribution running through wholesale distributor networks for commercial specifications and direct-to-consumer platforms for residential peel-and-stick segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US wallpaper market offers margin expansion pathways through water-based ink conversion cost absorption and hospitality specification pull-through for certified premium tiers.
For Market Incumbents: Hedge petrochemical input exposure through forward contracts on vinyl resin while accelerating archive-digitization investments that sustain heritage-premium positioning against emerging digital-native competitors. Prioritize CDPH v1.2 pre-certification for new substrate formulations to compress launch timelines before EPA enforcement tightens further. For New Entrants and Emerging Players: Online contractor platforms represent the most penetrable channel for bypassing wholesale distributor gatekeepers, particularly in Texas metro construction corridors where installer capacity constraints create fulfillment gaps. Target healthcare acoustic applications with fabric-backed vinyl prototypes, leveraging strippability mandates as entry wedge against established hospitality suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where certification costs disadvantage sub-scale mills lacking water-based ink conversion capital, creating acquisition opportunities for regional players with compliant supply chains. Focus on domestic manufacturers with CDPH-validated product lines and established hospitality relationships as preferred targets, monitoring EPA enforcement intensity as the key inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Ink Conversion | EPA TSCA Title VI compliance secures hospitality specification access and defends against import competition. |
| Digital Print Infrastructure Investment | UV-cured inkjet systems collapse custom order lead times for boutique hotel branded environments. |
| Peel-and-Stick Formulation R&D | Pressure-sensitive adhesive advances capture DIY renovation segments without contractor dependency. |
| CDPH v1.2 Pre-Certification | California air quality validation extends specification influence across state lines into national commercial procurement. |
| Online Contractor Platform Partnership | Direct manufacturer-installer relationships bypass wholesale distributor margin extraction in residential channels. |
Research Methodology
Multiple input streams — primary interviews with wallpaper manufacturing executives, hospitality procurement directors, and commercial contractor networks, alongside secondary validation through EPA enforcement records, CDPH certification databases, and customs import data — were reconciled through bottom-up production volume modeling and top-down demand segmentation triangulation.
Data-stream reconciliation across substrate technology, end-use application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from trend-line extrapolation of hospitality renovation cycles and residential construction permits, with water-based ink adoption curves and peel-and-stick penetration rates as wallpaper-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA enforcement intensity shifts and petrochemical price volatility. Forecasts reflect assumptions about certification timeline compression and installer labor supply elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
Plantation Shutters Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
MDF Decorative Overlays Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
Decorations and Inclusions Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Home Decor and Accessories Market
Homecare and Decor
United States Decorative Laminates Market
Homecare and Decor
Louvre Windows Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Pillow Cases Market