
 Automatic Toilet Seat Market | 2026-2036
Automatic Toilet Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Toilet Seat Market Insights
Premium heated-seat specifications with integrated bidet functionality is rotating the Automatic Toilet Seat Market toward higher-margin product tiers. Toto leverages its manufacturing scale to dominate Japan's domestic supply chain for ceramic-electronic integration. LIXIL Group anchors European distribution through Geberit's plumbing infrastructure network. Kohler competes in North American residential channels with design-forward heated-seat variants.
An automatic toilet seat is a motorized sanitary fixture incorporating electronic sensors, heating elements, and water-spray mechanisms within a hinged assembly designed for hands-free operation and personal hygiene functions; units typically operate on 110-220V AC power with IPX4-rated water protection and temperature-controlled washlet streams between 35-40°C for user comfort. Smart seats with Bluetooth connectivity and infrared sensors command the highest margin pools as hospitality and healthcare venues prioritize touchless hygiene protocols. Bidet seats sustain volume leadership in East Asian residential markets where warm-water cleansing is standard. Motion sensor seats are gaining fastest in commercial venues across Europe under hygiene-focused building codes.
The US FDA classifies electronic bidet attachments as medical devices when marketed with therapeutic claims, shaping product labeling and import documentation requirements. Japan's METI enforces JIS standards for electrical safety in bathroom fixtures, while South Korea's MFDS oversees KC mark certification for electronic toilet seats sold domestically. China's SAMR implements GB standards for household electronic appliances including waterproofing and electromagnetic compatibility testing. Stakeholders must monitor evolving cross-border certification reciprocity between East Asian regulators and European CE marking bodies as supply chains regionalize.
Market Dynamics
Touchless hygiene protocols established during public health emergencies have permanently altered specification criteria across commercial building categories, with infrared sensor integration now a baseline requirement rather than premium feature.
Growth Catalysts
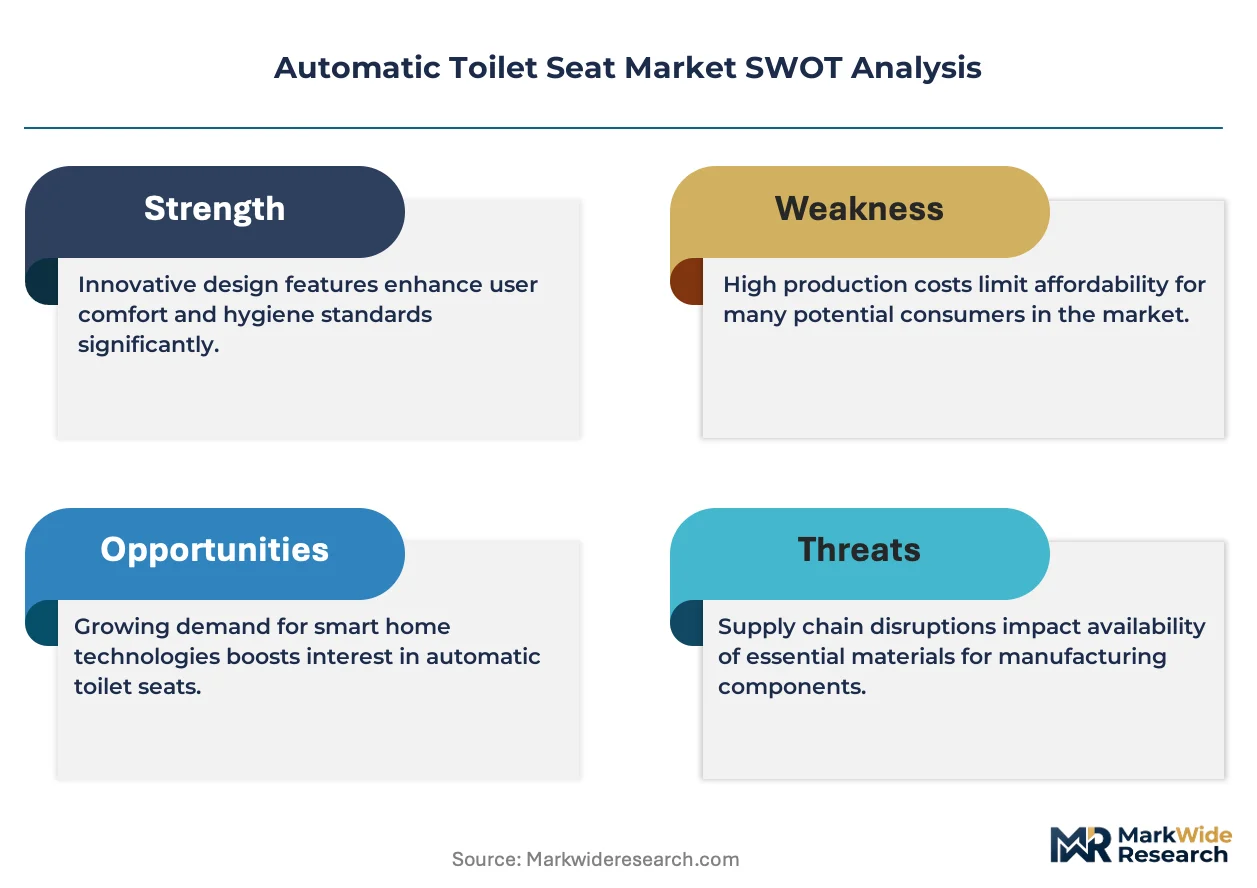
- Japan's METI JIS standards:Mandatory electrical safety certifications for bathroom fixtures create compliance barriers that protect established domestic manufacturers from low-cost imports while elevating overall product quality expectations.
- Healthcare facility renovation cycles:North American hospital systems are specifying antimicrobial ceramic-electronic integration in new construction, with infection control committees mandating hands-free operation for all patient-facing restroom installations.
- Platinum-grade ceramic heating elements:Advances in rapid thermal response technology reduce energy consumption per use cycle, satisfying EU Ecodesign requirements while improving user experience metrics in cold-climate installations.
Market Restraints
- Semiconductor component concentration:Taiwan-based foundries control critical microcontroller supply for sensor-actuator systems, creating single-source vulnerability for motion-detection firmware.
- IPX4 waterproofing certification costs:Third-party testing laboratory backlogs in China extend product launch timelines by 4-6 months for manufacturers seeking GB standard compliance.
- Plumbing contractor skill gaps:Licensed installers capable of integrating 220V electrical feeds with ceramic waste systems remain scarce in secondary US metropolitan markets, limiting residential retrofit penetration.
Strategic Opportunities
- German F-Gas Regulation phase-down:Replacement timelines for climate-controlled commercial buildings create specification windows for thermostatically advanced seats with integrated heating.
- Vietnam hospitality construction pipeline:International hotel chains are pre-specifying smart restroom packages in Ho Chi Minh City and Da Nang developments ahead of domestic supply chain maturation.
- Bluetooth-enabled predictive maintenance:Convergence of IoT connectivity with ceramic pressure sensors enables service-contract revenue models for facility management providers.
Industry Challenges
- Firmware engineering talent scarcity:Embedded systems developers with bathroom-appliance waterproofing experience command premium compensation, constraining R&D expansion at mid-tier manufacturers.
- Cross-border certification reciprocity gaps:Absence of mutual recognition between Japan's PMDA-equivalent sanitary device standards and European CE marking bodies forces redundant testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Toilet Seat Market |
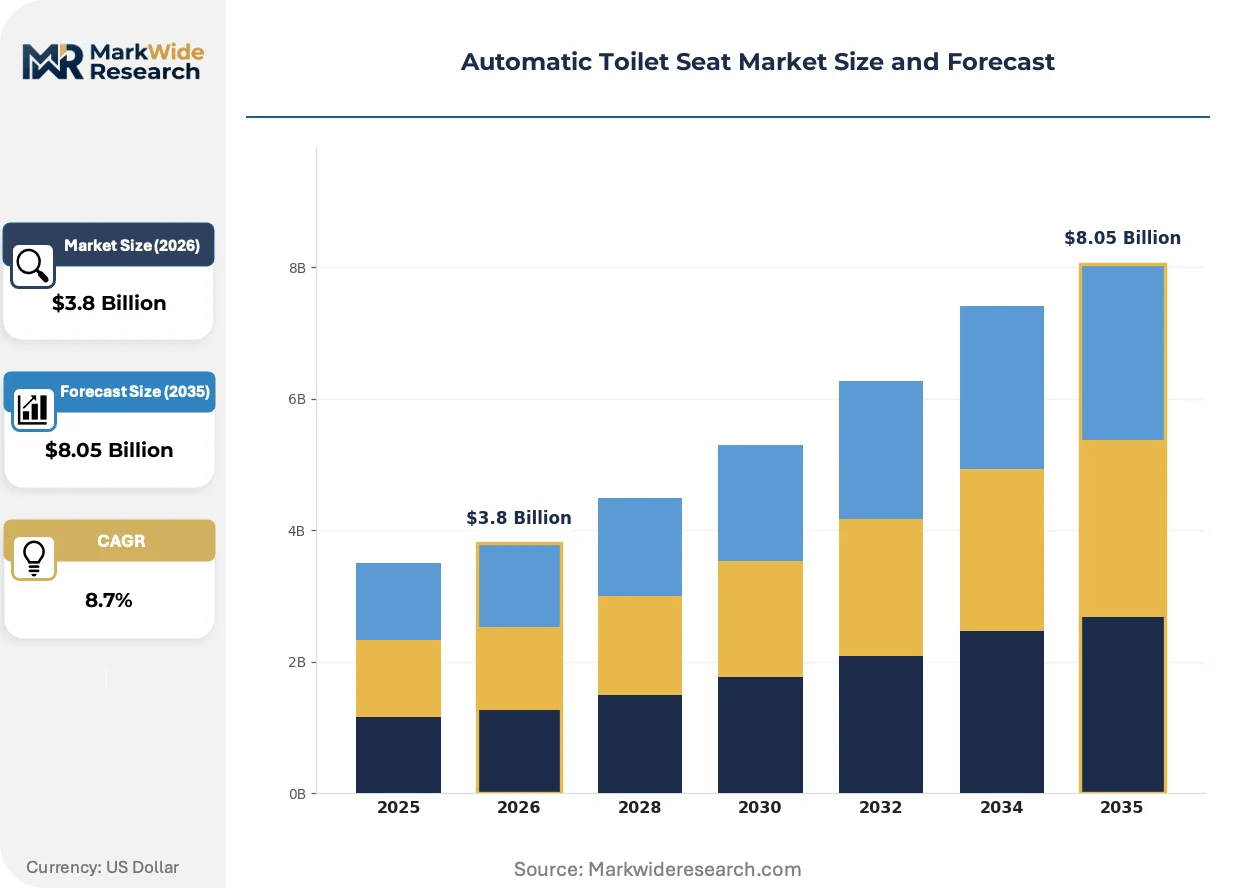
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Seats, Heated Seats, Bidet Seats, Motion Sensor Seats End User: Residential Users, Commercial Venues, Healthcare Facilities, Hospitality Industry Technology: Infrared Sensors, Bluetooth Connectivity, Touchless Operation, Hydraulic Mechanisms Installation: Wall-mounted, Floor-mounted, Portable, Integrated Systems |
| Companies Covered | Toto, LIXIL Group, Kohler, Panasonic, Roca Sanitario, Geberit, Brondell, Duravit, Huida Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Toilet Seat Market Trends and Innovations
Product architecture is bifurcating between all-in-one ceramic-electronic systems and modular retrofit attachments, with specification decisions increasingly driven by building age and plumbing infrastructure vintage rather than brand preference alone.
Capacitive proximity sensors are supplanting traditional mechanical pressure switches in premium installations. Hospitality procurement teams in Seoul and Singapore are specifying non-contact activation for all new properties. This displacement is compressing margins for manufacturers dependent on legacy switchgear supply chains while rewarding semiconductor-integrated design houses.
South Korea's MFDS has tightened electromagnetic compatibility testing protocols for electronic bidets sold under KC certification. Domestic manufacturers must now submit expanded documentation on wireless module shielding. Products with integrated Bluetooth functionality face extended approval timelines, prompting some suppliers to delay connectivity features in initial launches.
Facility managers in China's tier-one cities are unbundling after-sales service from hardware procurement, signing direct maintenance contracts with third-party technicians rather than OEM service networks. This fragmentation is disrupting traditional warranty revenue models and forcing manufacturers to publish open diagnostic protocols. The shift is most visible in Shanghai's commercial office sector, where property management platforms now rate service responsiveness independently of product brand.
Automatic Toilet Seat Market Segmentation
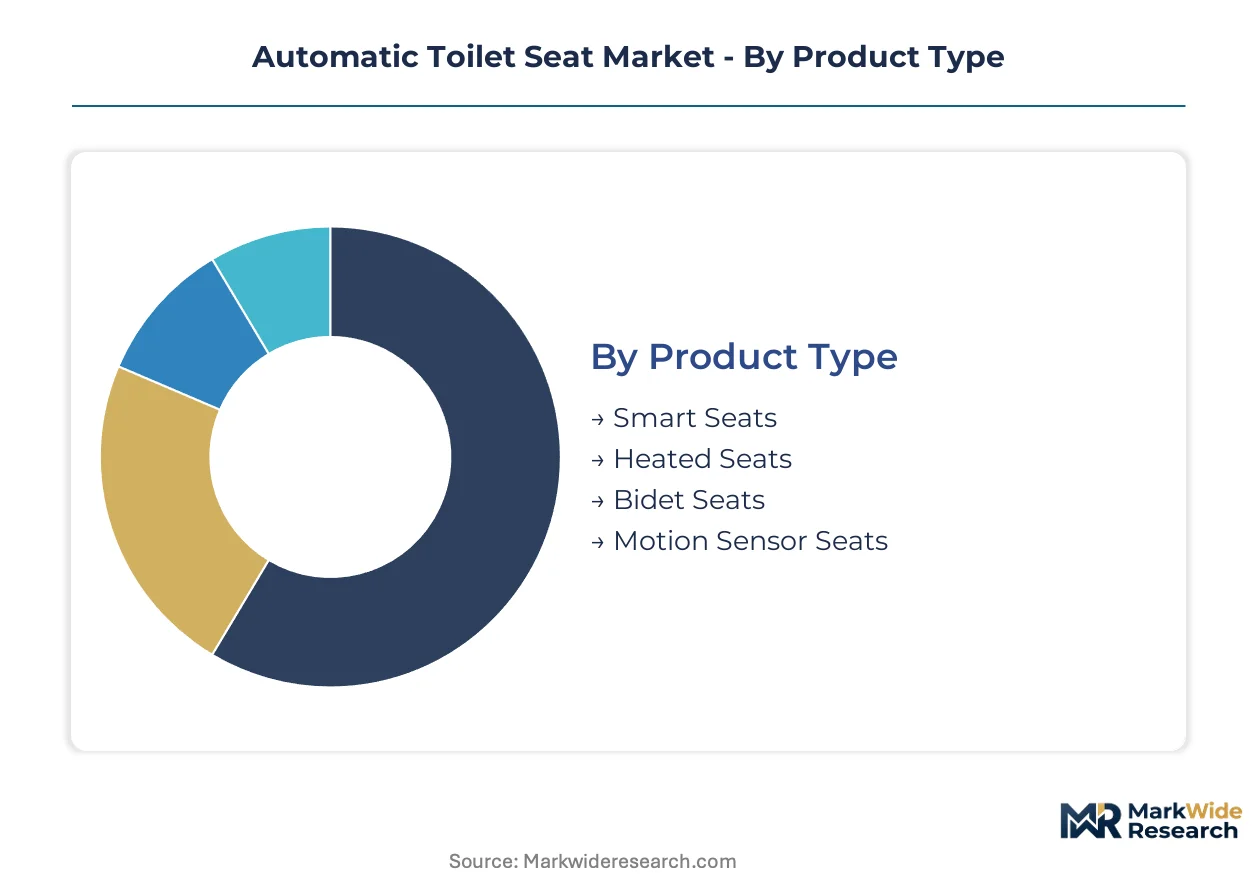
Automatic toilet seat segmentation reveals divergent channel economics. Premium ceramic-electronic integration flows through plumbing contractor networks, while modular retrofit attachments reach consumers via direct e-commerce. Specification authority varies sharply across end-use categories, with healthcare procurement committees demanding antimicrobial certifications unavailable in residential retail channels.
Product Type:
Smart seats and bidet seats concentrate in specialized plumbing distribution, while heated variants and motion-sensor units penetrate broader retail channels including home improvement chains and hospitality procurement platforms.
- Smart Seats:Units integrate Bluetooth modules, capacitive proximity sensors, and predictive maintenance firmware within IPX4-rated housings. Demand clusters in Seoul's commercial office sector and Singapore's luxury hospitality developments where facility managers prioritize IoT-enabled service contracts.
- Heated Seats:Rapid-response ceramic heating elements maintain surface temperatures between 30-40°C with EU Ecodesign-compliant energy profiles. North American residential retrofits drive volume, constrained by licensed electrician scarcity in secondary metropolitan markets.
- Bidet Seats:Temperature-controlled washlet streams with adjustable pressure settings dominate East Asian residential replacement cycles.
- Motion Sensor Seats:Infrared-actuated lid and seat mechanisms satisfy post-pandemic hygiene protocols in European commercial buildings.
By volume, bidet seats lead. By growth pace, motion sensor seats are expanding most quickly.
End User:
Cost tier stratification separates specification-grade healthcare installations from price-sensitive residential retrofits, with hospitality and commercial venues occupying intermediate positions on feature-to-price ratios.
- Residential Users:Replacement-driven demand in Japan and South Korea favors all-in-one ceramic-electronic systems with integrated bidet functionality. China's tier-one cities show rising retrofit interest, though 220V electrical installation requirements limit penetration.
- Commercial Venues:Office buildings and public facilities specify touchless operation under hygiene-focused building codes. Procurement teams in Germany's F-Gas-regulated climate zones prioritize thermostatically advanced heating elements.
- Healthcare Facilities:North American hospital systems mandate antimicrobial surfaces and hands-free operation through infection control committees.
- Hospitality Industry:International hotel chains in Vietnam's Ho Chi Minh City and Da Nang developments pre-specify smart restroom packages ahead of domestic supply chain maturation.
Residential users generate the highest absolute volume. Healthcare facilities command the steepest expansion trajectory.
Technology:
Maturity curves diverge sharply, with hydraulic mechanisms representing legacy infrastructure while Bluetooth connectivity faces extended regulatory approval timelines under South Korea's tightened MFDS electromagnetic compatibility protocols.
- Infrared Sensors:Non-contact activation modules with adjustable detection ranges between 30-80cm. Hospitality procurement in Seoul and Singapore specifies these for all new properties, displacing mechanical pressure switches.
- Bluetooth Connectivity:Wireless firmware updates and usage analytics enable predictive maintenance revenue models. Extended KC certification timelines in South Korea prompt some suppliers to delay connectivity features in initial product launches.
- Touchless Operation:Capacitive proximity detection eliminates physical contact points for hygiene-critical installations.
- Hydraulic Mechanisms:Pneumatic and spring-assisted systems persist in cost-optimized product tiers and legacy building retrofits.
Infrared sensors dominate current installation value. Bluetooth connectivity is gaining share fastest despite regulatory headwinds.
Installation:
Building age and plumbing infrastructure vintage increasingly override brand preference in specification decisions, with integrated systems requiring new construction coordination while portable and retrofit formats address installed base limitations.
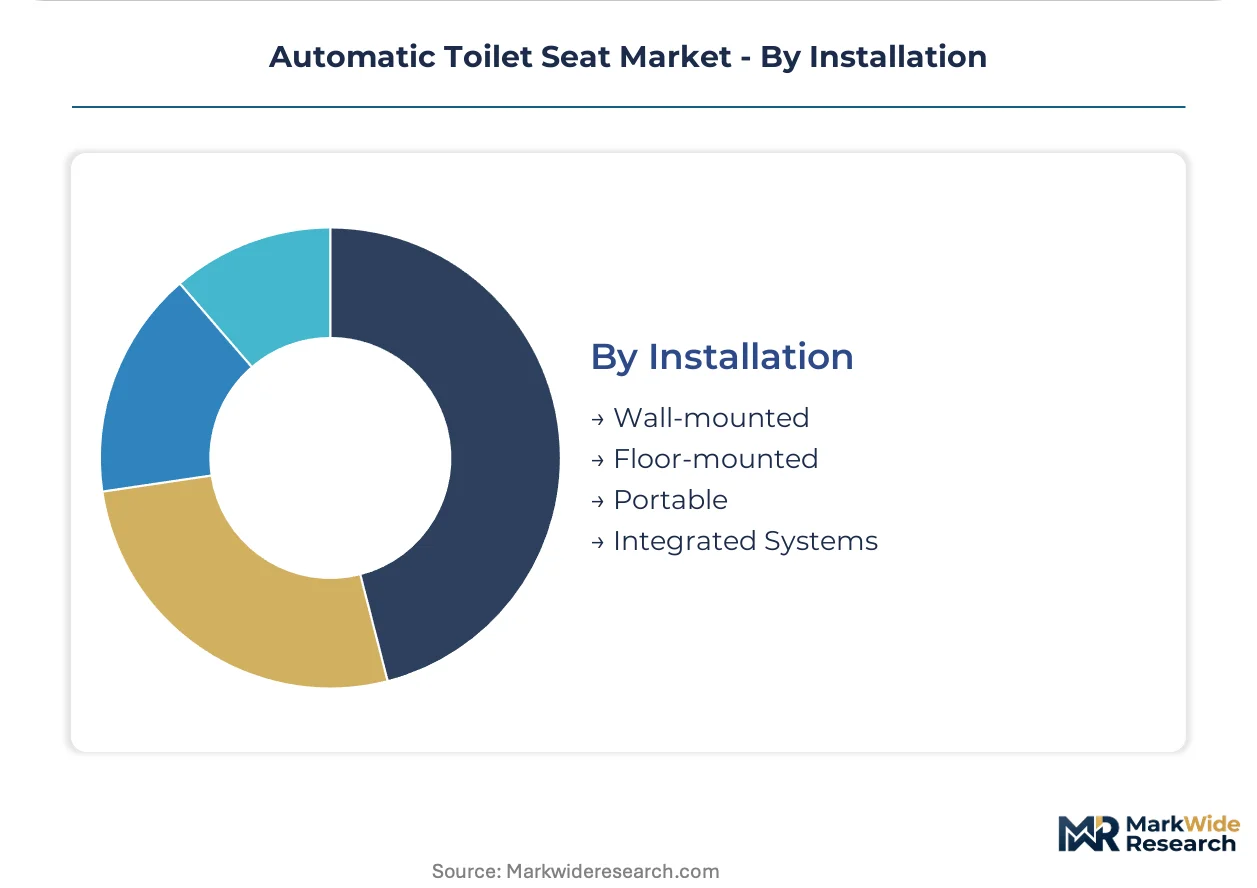
- Wall-mounted:Suspended ceramic bowls with concealed cisterns and integrated electronic modules. European commercial renovations favor these for space optimization and cleaning access.
- Floor-mounted:Traditional waste connection geometry accommodates broader retrofit compatibility. North American residential channels show persistent preference for this configuration.
- Portable:Battery-powered or plug-in units requiring no permanent plumbing modification. Limited to temporary installations and accessibility applications.
- Integrated Systems:Factory-unified ceramic-electronic assemblies with matched warranty coverage. Japan's domestic manufacturers leverage manufacturing scale for these specifications.
Floor-mounted units retain volume leadership. Integrated systems are climbing the fastest as new construction specifications advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese manufacturers export integrated ceramic-electronic systems to hospitality developers across Vietnam and Thailand, while South Korean component suppliers feed sensor modules into Chinese assembly plants serving domestic tier-one cities.
Japan
Replacement-driven residential demand sustains volume leadership for all-in-one washlet systems. METI enforces JIS electrical safety standards that protect domestic manufacturers from low-cost import competition. Manufacturing clusters in Chubu/Nagoya and Kansai/Osaka regions concentrate precision ceramic-electronic integration capacity.
South Korea
Seoul's commercial districts and Busan-Ulsan hospitality corridors specify capacitive proximity sensors for new construction. MFDS tightened KC certification protocols for electromagnetic compatibility, extending Bluetooth-enabled product approval timelines. Domestic manufacturers dominate electronic bidet supply chains serving apartment replacement cycles.
China
Tier-one cities including Shanghai and Beijing show rising smart seat retrofit interest constrained by 220V electrical installation requirements. SAMR implements GB standards for waterproofing and electromagnetic compatibility testing. Yangtze River Delta assembly plants source sensor modules from South Korean suppliers for domestic distribution.
United States
North American hospital systems specify antimicrobial hands-free operation through infection control committee mandates. FDA classifies therapeutic electronic bidets as medical devices, shaping import documentation requirements. Secondary metropolitan markets face licensed electrician scarcity limiting residential retrofit penetration.
Germany
Commercial building renovations under F-Gas Regulation phase-down timelines specify thermostatically advanced heating elements. EU Ecodesign requirements drive rapid thermal response ceramic technology adoption. Bavaria and North Rhine-Westphalia plumbing contractor networks distribute wall-mounted integrated systems for space-optimized installations.
Automatic Toilet Seat Market Competitive Landscape
Listed leaders compete with private specialists across certification barriers and channel access. The vendor base concentrates around three tiers: integrated ceramic-electronic system manufacturers, modular retrofit attachment suppliers, and component specialists supplying sensor and heating subassemblies. Scale-driven players leverage manufacturing footprint for domestic regulatory compliance, while mid-tier competitors pursue geographic expansion through hospitality specification partnerships. Dominant competitive moves include backward integration into ceramic production and technology licensing for connectivity modules.
Among Japan-based integrated system manufacturers, Toto and LIXIL Group exemplify the scale-driven archetype with domestic regulatory compliance advantages. Kohler represents the design-forward North American residential channel specialist. These three anchors occupy positions across distinct geographic and channel vectors rather than competing head-to-head in identical specification environments.
| Leading Market Players |
|---|
| Toto |
| LIXIL Group |
| Kohler |
| Panasonic |
| Roca Sanitario |
| Geberit |
| Brondell |
| Duravit |
| Huida Group |
| Others |
Pricing and Supply Chain Analysis
Japan's METI JIS electrical safety standards gate both supply qualification and price differentiation simultaneously, protecting domestic manufacturers from low-cost import competition while elevating baseline certification costs that stratify product tiers across the Automatic Toilet Seat Market.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Healthcare procurement committees pay certification premiums for antimicrobial surfaces and hands-free operation, while residential retrofits in secondary US metropolitan markets show acute price sensitivity due to licensed electrician scarcity. Cost compression in economy bidet attachments is intensifying because South Korean component suppliers compete on sensor module volume. Price differentiation hinges on IPX4 waterproofing grade and after-sales service bundling.
Supply Chain Analysis
Taiwan-based foundry capacity for motion-detection microcontrollers creates single-source chokepoint vulnerability across sensor-actuator systems. Ceramic heating elements draw from Japanese precision manufacturers in Chubu and Kansai regions, while Yangtze River Delta assembly plants source sensor modules from South Korean suppliers. Semiconductor component concentration exposes firmware-dependent manufacturers to foundry allocation volatility. Distribution runs through plumbing contractor networks for integrated systems and direct e-commerce for modular retrofit attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled predictive maintenance firmware is transforming the Automatic Toilet Seat Market toward platform-economics dynamics, with IoT service contracts creating recurring revenue streams that decouple manufacturer economics from hardware shipment cycles.
For Market Incumbents: Secure backward integration into ceramic heating element production to defend margin position against platinum-grade thermal response commoditization. Lock exclusive distribution through Germany's F-Gas-regulated climate zone plumbing networks before specification windows close. Invest in open diagnostic protocol development to retain service revenue as China's tier-one facility managers fragment aftermarket relationships.
For New Entrants and Emerging Players: Differentiate on Vietnam hospitality pre-specification partnerships ahead of domestic supply chain maturation in Ho Chi Minh City and Da Nang. Target portable battery-powered units for accessibility applications where permanent plumbing modification barriers persist. Pursue direct maintenance contracting with Shanghai commercial property management platforms that rate service responsiveness independently of product brand.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Bluetooth-integrated smart seat sub-segments as South Korea's MFDS extends electromagnetic compatibility approval timelines. Acquire component specialists with captive sensor module shielding capabilities and existing KC certification relationships. Watch for firmware engineering talent scarcity signals in compensation benchmarks as the inflection indicator for R&D expansion constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| KC Certification Investment | Accelerates South Korean market entry before MFDS tightens electromagnetic compatibility protocols further. |
| Ceramic-Electronic Integration Partnership | Secures manufacturing scale advantages for Japan's domestic replacement-driven washlet demand. |
| Predictive Maintenance Platform Launch | Enables facility management service contracts in Seoul's commercial office sector. |
| Antimicrobial Surface Certification | Unlocks North American hospital system procurement committee specifications. |
| Vietnam Hospitality Specification Partnership | Captures international hotel chain pre-commitments ahead of domestic supply chain maturation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and hospital procurement databases. Plumbing contractors, facility managers at commercial office properties, infection control committee members, and electronic bidet manufacturing executives provided operational perspective. METI JIS standards documentation, FDA medical device classification rulings, SAMR GB testing protocols, and EU Ecodesign compliance records supplied regulatory validation. Bottom-up shipment estimates triangulated against top-down construction spending allocations.
Segmentation dimensions modeled include product architecture type, end-use category, sensor technology maturity, and installation configuration across the projection horizon. CAGRs derived from replacement cycle analysis in Japan and South Korea, new construction specification rates in Vietnam hospitality, and retrofit penetration constraints in North American residential channels. Forecast inputs incorporated semiconductor foundry allocation trends and plumbing contractor skill gap indices.
Decision-makers should treat outputs as directional under stable regulatory reciprocity assumptions between East Asian and European certification bodies; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as cross-border electromagnetic compatibility testing protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Smart Toilet Seat Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market