
 Removable Wallpaper Market | 2026-2036
Removable Wallpaper Market Size, Share, and Industry Trends Forecast 2026-2036
Removable Wallpaper Market Outlook
Aftermarket service revenue from installation support and pattern-matching consultation is narrowing as peel-and-stick formulations eliminate professional dependency. York Wallcoverings anchors its position through deep catalog breadth across heritage and contemporary motifs. Tempaper specializes in artist-collaboration drops that sustain premium price positioning. Spoonflower controls a differentiated lane via print-on-demand custom designs that extend buyer co-creation.
Removable wallpaper denotes a self-adhesive wall covering engineered with repositionable acrylic or low-tack adhesive backings, typically manufactured in 18-inch to 27-inch widths with release-liner substrates for residue-free removal. Its primary commercial purpose is to deliver aesthetic surface transformation without substrate damage or lease forfeiture risk. Non-woven and fabric substrates capture expanding margin pools as breathability and matte finishes displace legacy PVC in residential settings. Online retail channels dominate volume throughput while specialty stores occupy the consultative high-end where pattern scale and color calibration demand physical evaluation.
The EPA oversees volatile organic compound thresholds in adhesive formulations, while the EU REACH framework restricts phthalate plasticizers and heavy metal pigments in imported wall coverings. California's Proposition 65 disclosure requirements further shape product labeling and material selection for brands distributing in the United States. Stakeholders must monitor evolving state-level chemical disclosure mandates and adhesive performance standards to anticipate compliance costs and reformulation timelines.
Market Dynamics
Lease-friendly décor mandates from institutional landlords are compressing replacement cycles and elevating pattern-matching precision requirements across the removable wallpaper supply base.
Growth Catalysts
- EU REACH chemical safety frameworks:Phthalate restrictions in imported wall coverings are accelerating PVC displacement toward non-woven and fabric substrates with higher margin profiles.
- Rental property managers:Lease-forfeiture risk mitigation drives bulk procurement of repositionable adhesive backings for tenant turnover environments.
- Low-tack acrylic formulations:Advancements in release-liner substrates enable residue-free removal that sustains repeat purchase behavior among urban apartment dwellers.
Market Restraints
- Petrochemical input volatility:Acrylic adhesive precursors and synthetic fabric substrates expose margins to crude-linked cost swings without pass-through mechanisms.
- California Proposition 65 disclosure mandates:Heavy metal pigment labeling requirements create compliance friction for imported products lacking supply chain traceability.
- Paint and peelable coatings:Lower-cost surface transformation alternatives capture price-sensitive segments in single-family residential renovation.
Strategic Opportunities
- Print-on-demand infrastructure:Digital textile printing convergence with e-commerce fulfillment enables buyer co-creation without inventory carrying costs.
- Seasonal refresh subscription models:Direct-to-consumer channels capture recurring revenue from design-forward urban demographics.
- EPA volatile organic compound thresholds:Adhesive reformulation compliance creates first-mover positioning for domestic manufacturers with in-house laboratory capabilities.
Industry Challenges
- Pattern-matching installation expertise:Peel-and-stick simplification has eroded the professional installer base, creating service gaps for large-scale commercial applications.
- Multi-jurisdiction chemical disclosure alignment:Divergent state-level mandates across the United States fragment labeling requirements and extend product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Removable Wallpaper Market |
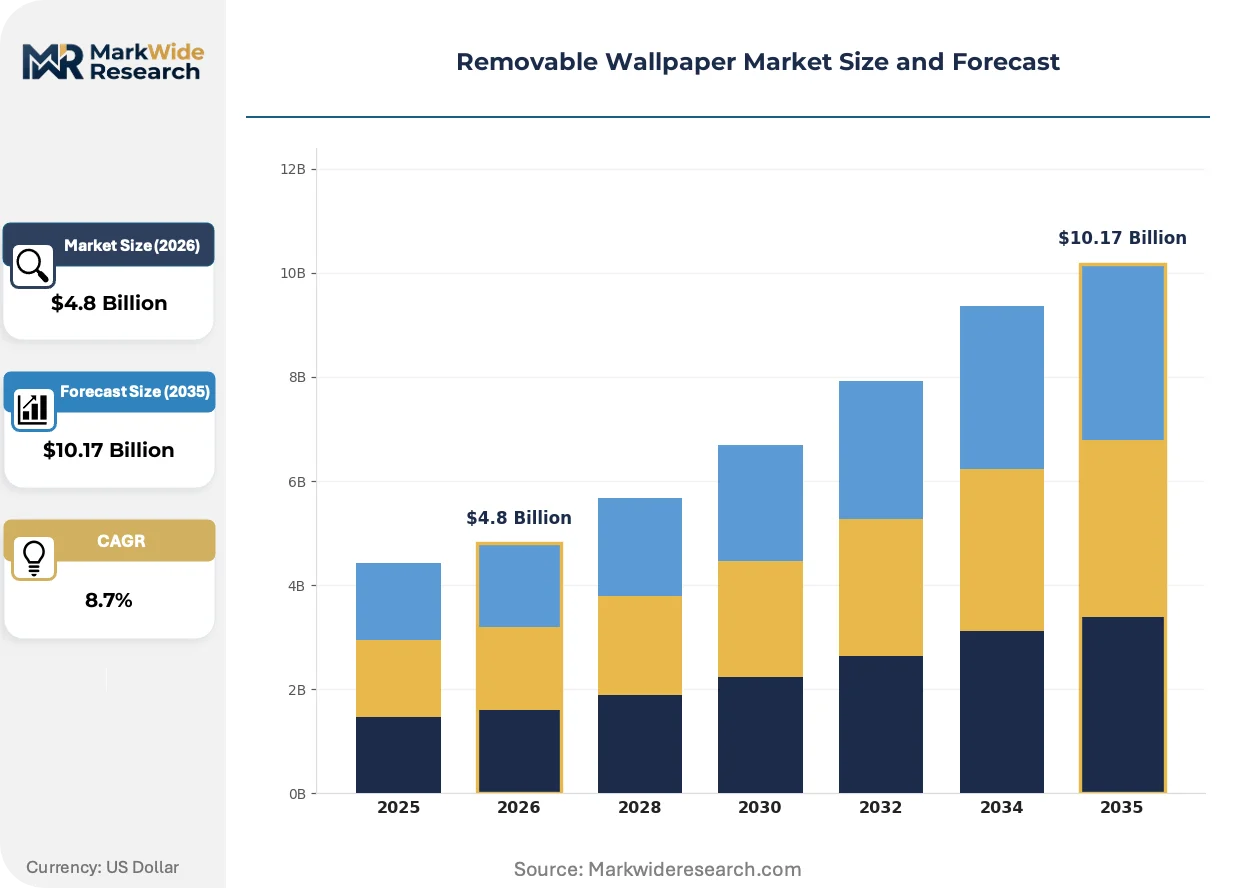
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, Fabric, Non-Woven, Vinyl End User: Homeowners, Commercial Spaces, Schools, Hospitality Design Style: Modern, Vintage, Geometric, Floral Distribution Channel: Online Retail, Specialty Stores, Home Improvement Stores, Wholesale |
| Companies Covered | York Wallcoverings, Brewster Home Fashions, Tempaper, Graham & Brown, WallPops, Chasing Paper, Spoonflower, Wallshoppe, NuWallpaper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Removable Wallpaper Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to reshape substrate preferences and adhesive performance benchmarks across residential and commercial applications.
Water-based acrylic adhesives with enhanced repositionability windows are rendering obsolete solvent-heavy legacy formulations that required precise first-attempt placement. Residential DIY installers and property management maintenance crews adopt these forgiving systems for reduced waste and labor cost containment. The technology is rendering obsolete professional installation dependencies that previously anchored aftermarket service revenue streams.
California's Proposition 65 disclosure requirements are mandating explicit heavy metal pigment warnings on imported wall covering packaging. Manufacturers distributing in the United States must reformulate colorant sourcing or absorb labeling compliance costs that erode price competitiveness. Specialty retailers with consultative sales models face the highest adaptation burden as physical evaluation demands transparent chemical composition communication.
Urban apartment dwellers compress refresh cycles to seasonal patterns aligned with lease renewal dates and social media aesthetic turnover. E-commerce volume throughput displaces specialty store consultation for standardized pattern scales and color calibration decisions. This behavioral shift concentrates demand in the United States coastal metropolitan corridors where rental density and design consciousness intersect most intensely.
Removable Wallpaper Market Segmentation
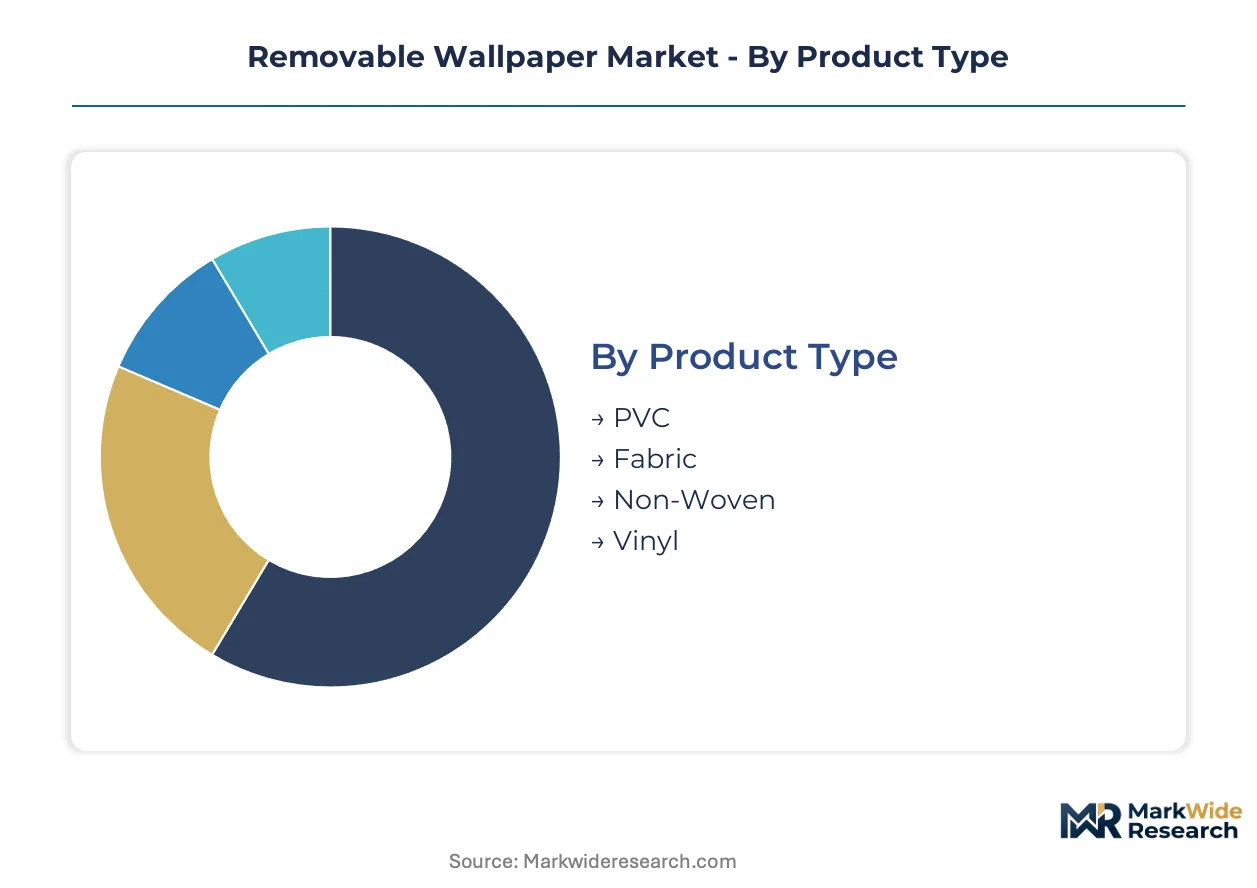
Removable wallpaper segmentation reveals divergent margin structures across material formulations and procurement channels. Each category carries distinct installation support requirements and repeat purchase cadences that reshape manufacturer resource allocation.
Product Type:
After-sales service intensity varies sharply across substrate categories, with repositionability complaints and residue claims driving warranty exposure most acutely in PVC segments.
- Non-Woven:Cellulose-polyester composite substrates enable breathability that prevents mold accumulation in humid residential bathrooms. Demand concentrates among urban apartment dwellers in the United States seeking lease-compliant décor with matte finish aesthetics. EU REACH phthalate restrictions accelerate displacement from PVC toward this higher-margin category.
- Fabric:Woven textile backings with low-tack acrylic adhesives deliver premium tactile surfaces for hospitality accent walls. Procurement from boutique hotels in coastal metropolitan corridors sustains price positioning above synthetic alternatives. California Proposition 65 disclosure mandates complicate pigment sourcing for imported variants.
- PVC:Legacy vinyl formulations with solvent-based adhesives face regulatory compression from volatile organic compound thresholds.
- Vinyl:Standard-grade synthetic substrates dominate volume throughput in home improvement retail channels.
By volume, PVC leads. By growth pace, non-woven is expanding most quickly.
End User:
Cost tier stratification separates premium design consultation from self-service procurement, with commercial segments absorbing pattern-matching labor that residential buyers internalize.
- Commercial Spaces:Corporate office refresh programs and co-working operators drive bulk procurement of standardized geometric patterns. Lease-friendly décor mandates from institutional landlords compress replacement cycles to 18-24 month intervals.
- Hospitality:Boutique hotels and restaurant groups commission custom artist collaborations for Instagrammable interior moments. Tempaper's collaboration model exemplifies this segment's premium positioning.
- Homeowners:DIY installation dominates with seasonal refresh behavior aligned to social media aesthetic turnover.
- Schools:Educational procurement prioritizes durability and chemical safety compliance over design novelty.
Homeowners capture the largest addressable base. Hospitality climbs the fastest in value per square foot.
Design Style:
Application context determines pattern scale and color saturation requirements, with digital printing convergence enabling micro-batch production across all aesthetic categories.
- Modern:Minimalist motifs with neutral palettes dominate urban apartment dweller preferences in United States coastal corridors. Spoonflower's print-on-demand infrastructure enables rapid iteration of contemporary designs without inventory risk.
- Geometric:Bold linear patterns sustain commercial space demand where brand identity alignment matters. Precision pattern-matching requirements elevate technical specifications for large-wall installations.
- Floral:Traditional botanical prints retain strength in residential bedroom applications.
- Vintage:Heritage reproductions anchor York Wallcoverings' catalog breadth for restoration projects.
Modern styling leads in absolute volume. Geometric applications gain share fastest in commercial procurement.
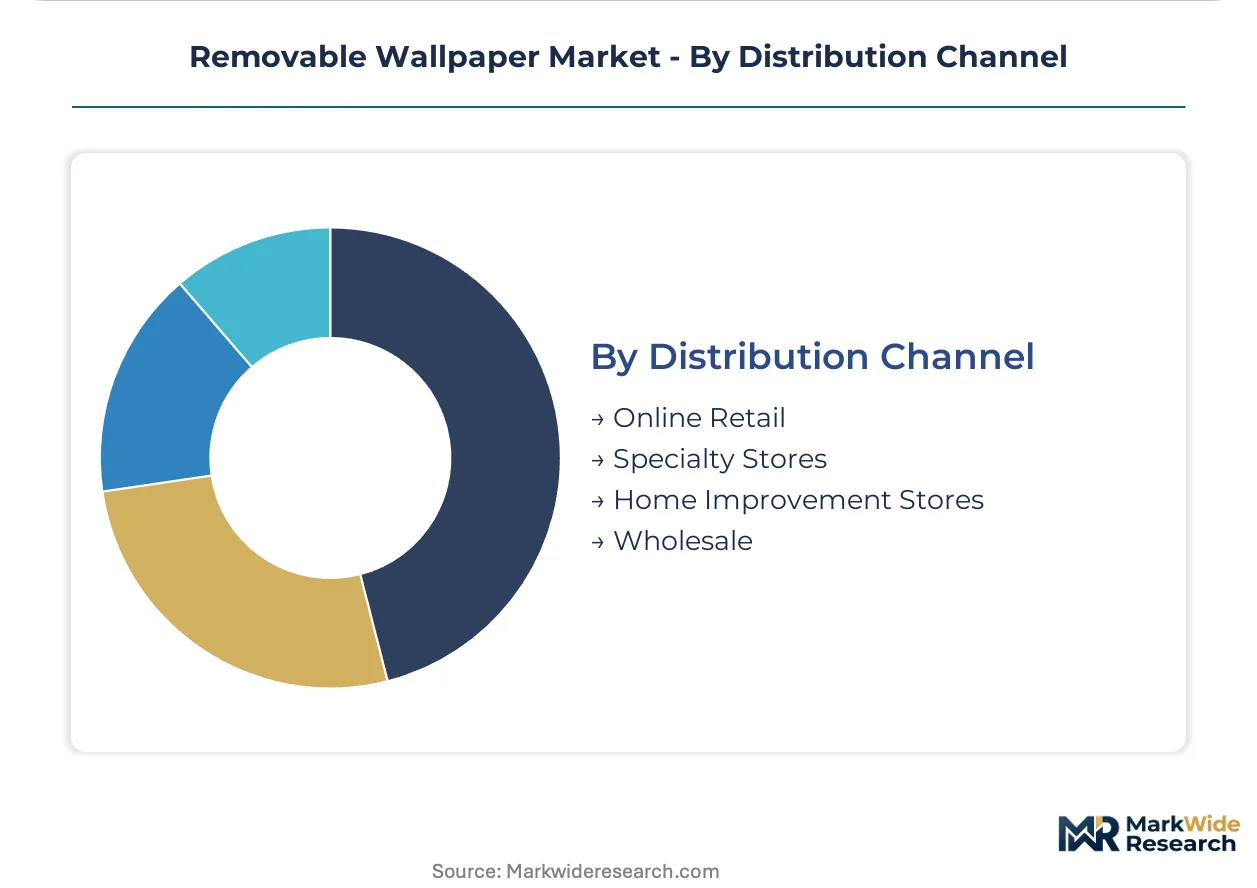
Distribution Channel:
Customer type bifurcation separates consultative evaluation needs from transactional convenience, with channel selection correlating to pattern complexity and project scale.
- Online Retail:E-commerce platforms capture standardized pattern repeat purchases from design-forward urban demographics. Seasonal refresh subscription models concentrate in this channel with direct-to-consumer fulfillment economics.
- Specialty Stores:Physical evaluation environments sustain premium positioning for large-scale pattern decisions where color calibration demands ambient light assessment. Consultative sales staff absorb California Proposition 65 disclosure communication burdens.
- Home Improvement Stores:Mass retail placement drives volume for entry-grade vinyl substrates.
- Wholesale:Property management bulk procurement channels serve rental turnover environments with standardized neutral palettes.
Online retail leads in transaction volume. Specialty stores command the steepest expansion trajectory in average order value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for removable wallpaper concentrates in China, Germany, and the United States, with adhesive formulation expertise and digital printing infrastructure anchoring regional competitive advantages. Raw material sourcing for non-woven substrates and low-tack acrylic adhesives drives cross-border supply dependencies that reshape procurement patterns.
United States
Urban apartment dwellers in New York, Los Angeles, and Chicago compress refresh cycles to seasonal patterns aligned with lease renewals. EPA volatile organic compound thresholds for adhesive formulations mandate reformulation timelines that favor domestic manufacturers with in-house laboratory capabilities. California's Proposition 65 disclosure requirements create compliance friction for imported products lacking supply chain traceability, elevating costs for specialty retailers.
Germany
EU REACH phthalate restrictions accelerate displacement from PVC toward non-woven and fabric substrates with higher margin profiles. ECHA enforcement of chemical safety frameworks in consumer products extends product development timelines for brands distributing across the European Union. Industrial clusters in North Rhine-Westphalia concentrate digital textile printing infrastructure that serves pan-European e-commerce fulfillment.
China
Manufacturing scale for release-liner substrates and synthetic fabric backings supplies global demand through integrated production corridors. MIIT standards for indoor air quality in building materials create dual compliance burdens for exporters targeting both domestic and international markets. Yangtze River Delta industrial zones anchor capacity for water-based acrylic adhesive formulations that satisfy REACH and EPA thresholds simultaneously.
United Kingdom
Boutique hospitality operators in London commission custom artist collaborations for Instagrammable interior moments that sustain premium price positioning. Post-Brexit divergence from EU chemical safety frameworks complicates labeling alignment for brands distributing across both jurisdictions. Midlands manufacturing bases retain heritage reproduction capabilities for restoration projects serving heritage building conservation programs.
Japan
METI guidelines for indoor air quality in residential buildings elevate technical specifications for breathability and low-emission adhesives. Compact urban dwellings in Tokyo and Osaka drive demand for repositionable wall coverings that enable frequent aesthetic refresh without substrate damage. Kansai region textile traditions inform premium fabric substrate development for hospitality and residential accent wall applications.
Removable Wallpaper Market Competitive Environment
Heritage manufacturers and digital-native specialists split the market between catalog breadth and co-creation agility. Consolidation pressure concentrates among mid-scale fabricators lacking proprietary adhesive formulations or direct-to-consumer fulfillment infrastructure. Three archetypes dominate: legacy wallpaper houses with deep pattern archives, print-on-demand platforms enabling buyer customization, and artist-collaboration studios sustaining premium positioning through limited drops. Competitive moves center on portfolio diversification into adjacent surface décor categories and backward integration into adhesive formulation capabilities.
Within the heritage manufacturer tier, York Wallcoverings anchors traditional pattern reproduction for restoration markets. Tempaper and Spoonflower exemplify divergent digital-native strategies—one through artist collaboration drops, the other via print-on-demand infrastructure that eliminates inventory carrying costs. These three companies represent the strategic poles around which smaller competitors cluster.
| Leading Market Players |
|---|
| York Wallcoverings |
| Brewster Home Fashions |
| Tempaper |
| Graham & Brown |
| WallPops |
| Chasing Paper |
| Spoonflower |
| Wallshoppe |
| NuWallpaper |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta manufacturing corridors anchor global capacity for water-based acrylic adhesives and release-liner substrates, concentrating formulation expertise that translates into pricing power for compliant exporters. This geographic clustering enables simultaneous satisfaction of EPA volatile organic compound thresholds and EU REACH phthalate restrictions, creating tiered cost structures that propagate through wholesale and direct-to-consumer channels.
Pricing Analysis
Aftermarket service revenue from pattern-matching consultation and installation support has collapsed as peel-and-stick formulations eliminate professional dependency. Three-tier pricing structure across premium, standard, and economy levels stratifies by substrate breathability and pigment sourcing transparency, with California Proposition 65 disclosure mandates adding compliance premiums to imported variants. Cost compression in entry-grade vinyl segments intensifies because paint and peelable coatings capture price-sensitive single-family renovators. Property management procurement teams exhibit highest price sensitivity due to bulk standardized orders, while boutique hospitality operators absorb premium positioning for custom artist collaborations.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for brands dependent on Yangtze River Delta integrated production corridors. Manufacturing concentrates in China, Germany, and the United States, with raw material dependencies spanning petrochemical-derived acrylic precursors, cellulose-polyester composite substrates, and synthetic fabric backings. Single-source vulnerability concentrates in release-liner substrate production where technical specifications for residue-free removal remain proprietary. Distribution runs through e-commerce platforms for standardized patterns and specialty retail for consultative large-scale decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Removable wallpaper sits in early-cycle expansion as lease-friendly décor mandates from institutional landlords accelerate pattern refresh frequency beyond traditional renovation timelines.
For Market Incumbents: Pre-empt margin erosion in PVC segments by accelerating backward integration into non-woven substrate production in domestic manufacturing bases. Capture EPA reformulation timelines as a first-mover advantage through in-house laboratory capabilities that compress compliance cycles relative to import-dependent competitors. For New Entrants and Emerging Players: Pursue hospitality procurement channels in coastal metropolitan corridors where custom artist collaborations sustain premium positioning above commodity alternatives. White-space concentrates in seasonal refresh subscription models targeting design-forward urban demographics with direct-to-consumer fulfillment economics. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue consumer discretionary play because refresh cycles compress toward seasonal patterns aligned with lease renewals and social media aesthetic turnover. Target print-on-demand infrastructure assets with captive adhesive formulation capabilities. The signal to watch is institutional landlord procurement standardization that would validate lease-friendly décor as a permanent fixture in tenant turnover protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Formulation Backward Integration | In-house EPA compliance capabilities compress reformulation timelines versus import-dependent rivals. |
| Print-on-Demand Infrastructure Investment | Digital textile printing convergence eliminates inventory carrying costs for buyer co-creation models. |
| Seasonal Subscription Model Launch | Direct-to-consumer channels capture recurring revenue from urban apartment dweller refresh behavior. |
| Hospitality Artist Collaboration Program | Boutique hotel procurement sustains premium positioning above synthetic substrate alternatives. |
| EU REACH-Compliant Substrate Transition | Non-woven and fabric categories capture expanding margin pools as PVC faces regulatory compression. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with property management procurement directors, specialty retail category managers, adhesive formulation chemists, digital textile printing engineers, and hospitality interior design consultants. Secondary validation drew from EPA volatile organic compound threshold documentation, EU REACH substance restriction updates, California Proposition 65 regulatory filings, e-commerce platform transaction data, and customs records for wall covering imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across geographic markets.
Calibration anchored volume and value outputs to historical replacement cycle data, lease turnover statistics in major metropolitan rental markets, and substrate-specific margin structures across the projection horizon. Segmentation dimensions modeled include substrate material, end-use application, design style category, and distribution channel with regional regulatory cluster overlays. CAGRs derived from trend extrapolation of refresh frequency compression and material substitution patterns, with specific inputs for institutional landlord procurement standardization timelines and digital printing cost curve trajectories.
Sensitivities concentrate around petrochemical input volatility, divergent state-level chemical disclosure mandates, and pace of PVC displacement toward higher-margin substrates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and rental market density evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Door Handles Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
Saudi Arabia Interior Design Market
Homecare and Decor
Soundproof Door Market
Homecare and Decor
Wall Art Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Wall Clock Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
Asia-Pacific Wall Covering Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
Bifold Door Market