
 Global Decorative Panels Market | 2026-2036
Global Decorative Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Decorative Panels Market Analysis
Modular panel systems bundled with installation hardware and digital specification tools is pivoting procurement patterns for commercial fit-out contractors. Unilin Panels leverages vertical integration from resin chemistry to finished board to sustain margin control across European distribution. Egger Group anchors its competitive position through manufacturing scale at multiple continental hubs. Trespa International B.V. differentiates via technology leadership in high-pressure compact laminates for exterior facade applications.
Decorative panels are engineered surfacing products comprising substrate cores bonded with decorative overlays, typically manufactured through hot-pressing resin-impregnated papers onto particleboard, MDF, or plywood cores at pressures exceeding 7 MPa and temperatures near 150°C, serving primarily to provide aesthetic finish, surface durability, and dimensional stability to interior walls, furniture, and architectural elements. Laminate panels dominate value contribution due to established specification in healthcare and education verticals where impact resistance and hygienic properties command premium positioning. MDF panels represent the fastest-growing substrate category as digital printing and textured embossing technologies enable mass customization at production scale. Wood-based materials retain the largest share of material demand, though metal and glass composites are gaining traction in retail environments seeking differentiated visual merchandising.
FDA guidelines on formaldehyde emissions from composite wood products, ECHA REACH restrictions on hazardous substance content, and CE marking requirements under the EU Construction Products Regulation collectively shape product formulation, testing protocols, and market access conditions for panel manufacturers serving regulated economies. ISO 9001 and ISO 14001 certifications function as baseline qualifiers for specification in institutional and corporate procurement frameworks. Stakeholders must monitor evolving bio-based binder chemistries and circular economy certification schemes as emerging determinants of supplier selection and contract eligibility.
Market Dynamics
Modular specification platforms bundled with digital visualization tools are compressing traditional distributor channels and forcing manufacturers to own direct contractor relationships. This structural shift redistributes margin capture toward panel producers capable of delivering integrated design-to-installation workflows.
Growth Catalysts
- EU Green Deal compliance mandates:ECHA REACH restrictions on hazardous substance content are accelerating specification of low-emission laminate substrates in German healthcare and education construction.
- Digital printing on MDF cores:Mass customization capabilities enable boutique hospitality projects to order batch-one decorative surfaces without premium tooling costs.
- France:Luxury hotel renovation cycles in Paris and Lyon are specifying high-pressure compact laminates as signature interior elements, pulling volume from traditional veneer applications.
Market Restraints
- Urea-formaldehyde resin volatility:Petrochemical feedstock fluctuations compress margins for particleboard substrate producers unable to pass through input cost swings.
- Engineered wood cluster concentration:German and Austrian manufacturing hub dominance creates supply vulnerability for distributors serving Southern European markets.
- CE marking complexity:EU Construction Products Regulation testing protocols extend product launch timelines by 8-14 months for novel bio-based binder formulations.
Strategic Opportunities
- India:BIS certification alignment with ISO 14001 creates pathway for European panel manufacturers to supply premium commercial interiors in Mumbai and Bangalore.
- Metal-glass composite facades:Retail visual merchandising applications in Dubai and Riyadh are specifying hybrid decorative panels for climate-responsive exterior cladding.
- CSRD disclosure requirements:EU corporate sustainability reporting mandates are creating procurement preference for circular economy certified suppliers with verified recycled content chains.
Industry Challenges
- Digital specification tool integration:Commercial fit-out contractors face workflow friction combining manufacturer BIM libraries with legacy project management platforms.
- Bio-based binder scale-up:Laboratory-validated lignin and soy protein adhesives require capital-intensive pilot production lines before achieving CE marking compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Decorative Panels Market |
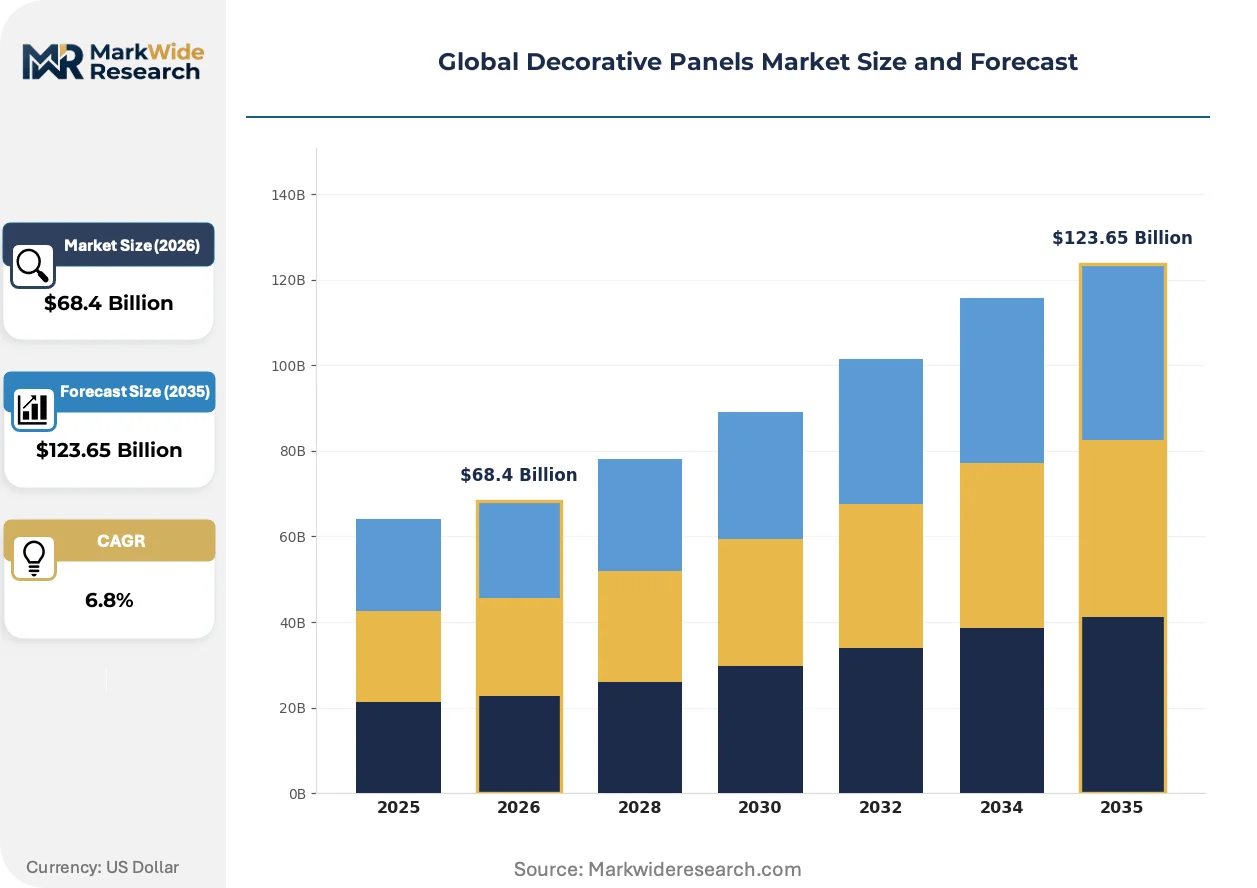
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminate Panels, MDF Panels, Plywood Panels, Veneer Panels Material: Wood, Metal, Glass, Acrylic End User: Residential, Commercial, Hospitality, Retail Design Style: Modern, Traditional, Vintage, Minimalist |
| Companies Covered | Unilin Panels, Egger Group, Trespa International B.V., Georgia-Pacific LLC, Arauco, SWISS KRONO Group, Laminam, Tecnografica, Sonae Arauco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Decorative Panels Market Emerging Trajectories
Surface engineering and specification digitization are converging to collapse traditional procurement cycles. Three developments are actively restructuring how decorative panels move from factory floor to installed interior.
Digital texture embossing synchronized with inkjet decoration is rewriting the economics of premium surface replication. Hospitality designers in Milan and Barcelona are specifying digitally printed oak and marble visuals at one-third the cost of authentic materials. This capability compresses the addressable market for traditional veneer suppliers while expanding specification access to mid-budget commercial projects.
ECHA REACH Annex XVII restrictions on formaldehyde-releasing substances are forcing reformulation of thermosetting resin systems across European manufacturing. Panel producers serving German healthcare construction are accelerating migration to phenol-resorcinol and bio-based adhesive platforms. The regulatory pressure is most acute in particleboard substrates, where incumbent urea-formaldehyde chemistry dominates production volume.
Specification decisions are migrating earlier in project workflows as architects embed manufacturer digital libraries directly into BIM environments. Distributors serving UK and Dutch commercial fit-out markets are losing influence as contractors source directly from panel producers offering integrated technical support. This channel compression is most visible in large-format retail rollouts where repeat specification patterns reward direct manufacturer relationships.
Global Decorative Panels Market Segmentation
Specification workflows in the decorative panels industry fragment across substrate technologies, material compositions, and end-use requirements. Manufacturers must align production capabilities with distinct certification standards and installation protocols that vary by segment.
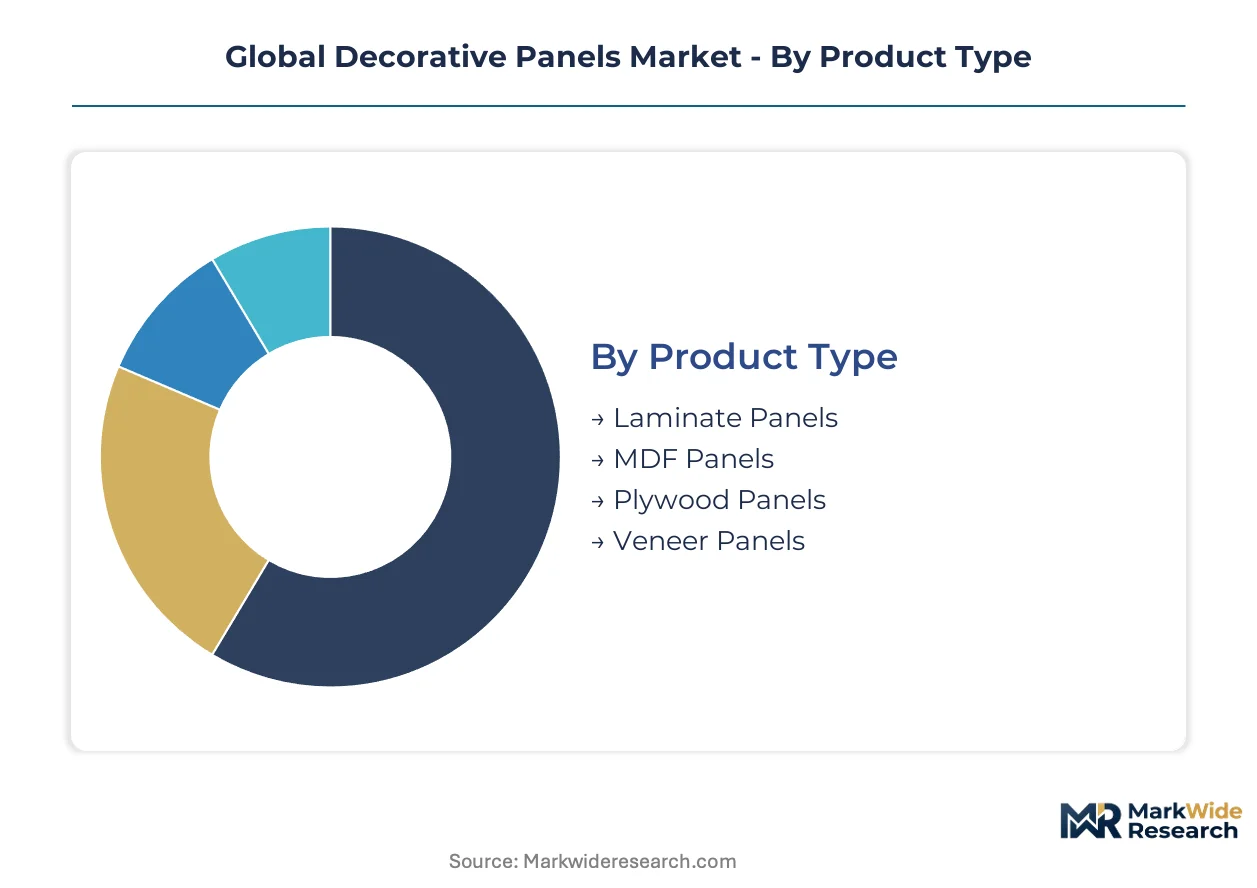
Product Type:
Manufacturing scale concentrates around hot-pressing infrastructure investments and resin chemistry control.
- Laminate Panels:Decorative overlays bonded to particleboard or MDF cores under high pressure and temperature deliver impact resistance and hygienic surfaces. German healthcare construction and French education facilities specify these for high-traffic corridors requiring scratch-resistant finishes.
- MDF Panels:Medium-density fiberboard substrates enable precise digital printing and textured embossing at production scale. Boutique hospitality projects in Milan and Barcelona leverage mass customization capabilities for batch-one decorative surfaces without premium tooling investments.
- Plywood Panels:Cross-laminated veneer construction provides dimensional stability for structural wall applications and furniture manufacturing.
- Veneer Panels:Thin natural wood slices bonded to composite cores offer authentic grain aesthetics at reduced material cost.
Laminate panels absorb the bulk of installed capacity; MDF panels are expanding most quickly.
Material:
Raw material sourcing strategies diverge based on circular economy certification requirements and regional feedstock availability.
- Wood:Engineered wood clusters in Germany and Austria dominate substrate supply chains, with particleboard and MDF production anchored by continental manufacturing hubs. EU Green Deal compliance mandates are accelerating low-emission binder migration across European operations.
- Metal:Aluminum and steel composite panels enable climate-responsive exterior cladding for retail visual merchandising applications in Dubai and Riyadh.
- Glass:Tempered and laminated glass panels serve premium interior partitions and facade systems requiring light transmission.
- Acrylic:Thermoplastic sheets offer lightweight alternatives for illuminated signage and contemporary residential installations.
Wood-based materials command the dominant share of specification volume; metal composites are climbing the fastest in commercial exterior applications.
End User:
Procurement authority structures vary sharply across customer categories, influencing channel strategy and technical support requirements.
- Residential:Individual homeowners and property developers prioritize cost-efficient surfacing for kitchens, wardrobes, and feature walls. Digital specification tools are compressing traditional distributor influence as contractors source directly from manufacturers.
- Commercial:Corporate fit-out contractors demand integrated BIM libraries and installation hardware for office and institutional interiors. UK and Dutch markets exhibit the most pronounced channel compression toward direct manufacturer relationships.
- Hospitality:Luxury hotel renovation cycles in Paris and Lyon specify high-pressure compact laminates as signature interior elements.
- Retail:Rollout programs for branded store networks reward repeat specification patterns and volume pricing agreements.
Commercial end users absorb the bulk of installed capacity; hospitality projects are gaining share fastest in premium laminate specification.
Design Style:
Aesthetic positioning determines overlay printing technology investments and surface texture development priorities.
- Modern:Clean lines and neutral palettes dominate corporate and healthcare interiors. High-gloss and super-matte finishes require specialized pressing parameters and protective overlay formulations.
- Traditional:Classic wood grain patterns and ornamental details persist in residential and heritage restoration projects. Authentic veneer replication demands synchronized embossing with inkjet decoration.
- Vintage:Distressed textures and aged patina effects serve boutique hospitality and retail environments seeking differentiated visual identity.
- Minimalist:Monolithic surfaces with subtle texture variation emphasize material purity over pattern complexity.
Modern styling absorbs the bulk of specification volume; vintage aesthetics are expanding most quickly in boutique hospitality applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Guangdong and Zhejiang provinces concentrate engineered wood substrate manufacturing for export-oriented panel production. These zones offer preferential tax treatment and streamlined customs processing that anchors regional supply chains.
Germany
Healthcare construction in Berlin and Hamburg drives specification of low-emission laminate panels for hospital renovation cycles. ECHA REACH Annex XVII restrictions on formaldehyde-releasing substances accelerate binder chemistry migration across Bavarian and North Rhine-Westphalian manufacturing clusters. The Black Forest region hosts multiple compact laminate production facilities serving premium interior fit-out demand.
China
Digital printing equipment installations in Guangdong province enable mass customization of MDF panels for boutique hospitality exports. GB standards for indoor air quality tighten substrate emission requirements in residential construction. Yangtze River Delta manufacturing hubs supply particleboard cores to furniture exporters serving North American and European markets.
United States
Corporate office renovation in Dallas and Atlanta pulls volume for modular panel systems with integrated installation hardware. EPA formaldehyde emission standards under the Toxic Substances Control Act shape composite wood product formulation. Southeast distribution centers near Atlanta and Charlotte compress lead times for commercial fit-out contractors.
France
Luxury hotel renovation cycles in Paris and Lyon specify high-pressure compact laminates as signature interior elements. EU Green Deal compliance mandates accelerate low-emission substrate specification in public procurement. Auvergne-Rhône-Alpes hosts engineered wood clusters supplying particleboard to furniture manufacturers across Southern Europe.
India
Commercial interior construction in Mumbai and Bangalore creates demand for premium laminate surfacing in IT campus developments. BIS certification alignment with ISO 14001 creates pathway for European panel manufacturers to enter premium segments. Gujarat manufacturing zones concentrate domestic MDF production capacity for residential and commercial applications.
Global Decorative Panels Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate chemistry and surfacing technology vectors. The vendor base stratifies into three tiers: integrated resin-to-board manufacturers, regional substrate specialists, and specification-driven overlay suppliers. Strategic archetypes include backward-integrated chemical producers, scale-driven continental hub operators, and technology-differentiated compact laminate specialists. Competitive moves center on captive resin production investments and direct contractor relationship programs that compress traditional distribution.
Among European integrated manufacturers, Unilin Panels, Egger Group, and Trespa International B.V. exemplify distinct strategic positions within the competitive structure. Unilin Panels represents the backward-integrated archetype with captive control over resin chemistry through finished board production. Egger Group occupies a scale-driven position anchored at multiple continental manufacturing hubs. Trespa International B.V. sits within the technology-differentiated tier focused on high-pressure compact laminate applications. Georgia-Pacific LLC and Arauco represent North and South American market presence respectively. SWISS KRONO Group anchors Central European engineered wood substrate supply.
| Leading Market Players |
|---|
| Unilin Panels |
| Egger Group |
| Trespa International B.V. |
| Georgia-Pacific LLC |
| Arauco |
| SWISS KRONO Group |
| Laminam |
| Tecnografica |
| Sonae Arauco |
| Others |
Supply Flow & Price Mechanics
Formaldehyde resin feedstock indices cascade through engineered wood substrate production into three-tier pricing structure across premium, standard, and economy levels. German healthcare contractors absorb premium positioning for low-emission laminates while Southern European distributors face margin compression from petrochemical volatility and hub concentration.
Pricing Analysis
Margin tightening in particleboard substrates reflects urea-formaldehyde resin cost swings that producers cannot fully pass through. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with CE-marked low-emission panels commanding substantial premiums. Price differentiation hinges on ECHA REACH compliance tier and backward integration depth. Commercial fit-out contractors exhibit highest price sensitivity; luxury hospitality specifiers show lowest.
Supply Chain Analysis
Direct-to-contractor channels displace traditional distributor networks as manufacturers embed BIM libraries and installation hardware into specification workflows. Supply concentrates in Germany, Austria, and China, with engineered wood clusters anchoring substrate availability. Raw material dependencies center on petrochemical resins, decorative overlay papers, and timber feedstocks. Single-source vulnerability from German-Austrian hub dominance exposes Southern European distributors to logistics disruption. Distribution runs through manufacturer-direct relationships for large-format retail rollouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Panel production capacity concentrates in continental European hubs with limited near-term expansion, propping pricing power for compliant producers. German healthcare and French hospitality renovation cycles sustain demand absorption at premium tiers.
For Market Incumbents: Anticipate digital specification platform displacement by accelerating captive resin production investments and direct contractor relationship programs. Defend against bio-based binder entrants by securing ECHA REACH pre-certification for pilot lignin-adhesive production lines. Prioritize CE marking compliance velocity to compress novel substrate launch timelines. For New Entrants and Emerging Players: Digital visualization tools bundled with modular installation systems offer entry pathway into UK and Dutch commercial fit-out markets. Target mid-budget hospitality segments in Milan and Barcelona where mass customization capabilities displace traditional veneer suppliers. Pursue BIS certification alignment for Mumbai and Bangalore premium commercial interior supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor technology-differentiated compact laminate specialists with exterior facade application expertise. Long-term viability over the next decade rests on circular economy certification positioning and verified recycled content chains. Watch CSRD disclosure adoption rates as inflection indicator for procurement preference shifts toward sustainability-verified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Chemistry | Captive urea-formaldehyde and phenol-resorcinol production insulates margin from petrochemical volatility. |
| Digital Specification Platform Launch | BIM library integration compresses distributor channels and locks in direct contractor relationships. |
| Bio-Based Binder Pilot Scale-Up | Lignin and soy protein adhesive validation accelerates EU Green Deal compliance positioning. |
| Circular Economy Certification Program | Verified recycled content chains unlock CSRD-mandated procurement preference in corporate fit-out. |
| Regional Hub Expansion in Southern Europe | Proximity production mitigates German-Austrian cluster concentration risk for Mediterranean distribution. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this decorative panels market assessment. Primary interviews with plant managers at engineered wood facilities, procurement leads at furniture OEMs, distribution channel partners, and specification directors at commercial fit-out contractors supplied operational validation. ECHA REACH substance restriction databases, EU Construction Products Regulation compliance registries, and BIS certification records provided regulatory boundary conditions. Bottom-up substrate production estimates triangulated against top-down construction spending allocations across healthcare, education, hospitality, and retail verticals.
Data-stream reconciliation across production volume, import-export flows, and end-use absorption rates shaped the analytical framework. Segmentation dimensions modeled include substrate technology, material composition, end-use vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical capacity expansion patterns and specification shift trajectories. Industry-specific forecast inputs incorporated digital printing equipment installation rates and bio-based binder laboratory validation timelines.
The model holds under stable ECHA REACH enforcement and continued EU Green Deal compliance trajectory; deviation in petrochemical feedstock availability or CE marking protocol acceleration would shift capacity expansion and pricing assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Asia-Pacific Interior Doors Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
Bulletin Board Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
Door Stopper Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
Stained Glass Market
Homecare and Decor
Soundproof Door Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Christmas Tree Market
Homecare and Decor
United Kingdom Resilient Floor Covering Market
Homecare and Decor
Rift Sawn Lumber Market
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
US Halloween Decorations Market