
 USA Bed Pillow Market | 2026-2036
USA Bed Pillow Market Size, Share, and Industry Trends Forecast 2026-2036
USA Bed Pillow Market Analytics
Aftermarket service revenue from pillow refresh programs and sleep-system subscriptions is fragmenting as direct-to-consumer brands bypass traditional retail service networks. Tempur Sealy International leverages its clinical sleep research partnerships to sustain premium positioning in therapeutic segments. Sleep Number Corporation anchors its market presence through adjustable firmness technology integrated with smart-home ecosystems. My Pillow Inc competes aggressively on domestic manufacturing messaging and broadcast channel control.
A bed pillow is a cushioned support device, typically measuring 20 by 26 inches in standard size, engineered with fill materials ranging from viscoelastic polyurethane foam to sterilized waterfowl down clusters, designed to maintain cervical alignment and thermal neutrality during sleep. Memory foam and latex categories command premium shelf space due to pressure-mapping performance and durability metrics, while synthetic fills occupy volume positions through cost efficiency and hypoallergenic certifications. Hotels and healthcare facilities represent the fastest-growing end-user channels, driven by contract procurement standardization and infection-control laundering protocols.
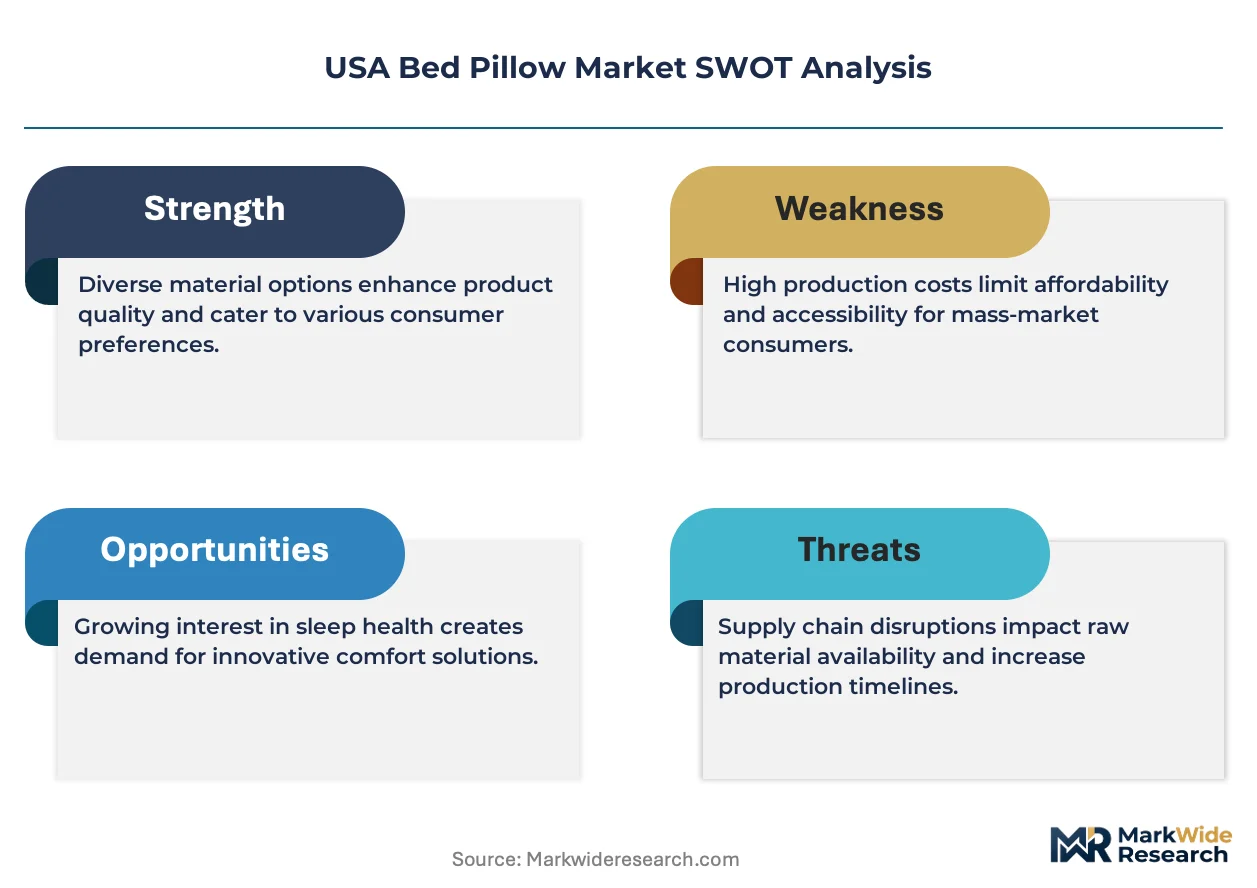
The FTC Green Guides regulate environmental claims on pillow labeling, compelling manufacturers to substantiate biodegradable and organic assertions with third-party verification. The Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1632, shaping material selection and testing costs for domestic producers. California's Proposition 65 warning requirements add compliance layers for foam producers operating in that state. Stakeholders must monitor pending state-level chemical disclosure legislation and decide whether to front-run stricter fill-material transparency rules or absorb reactive compliance costs.
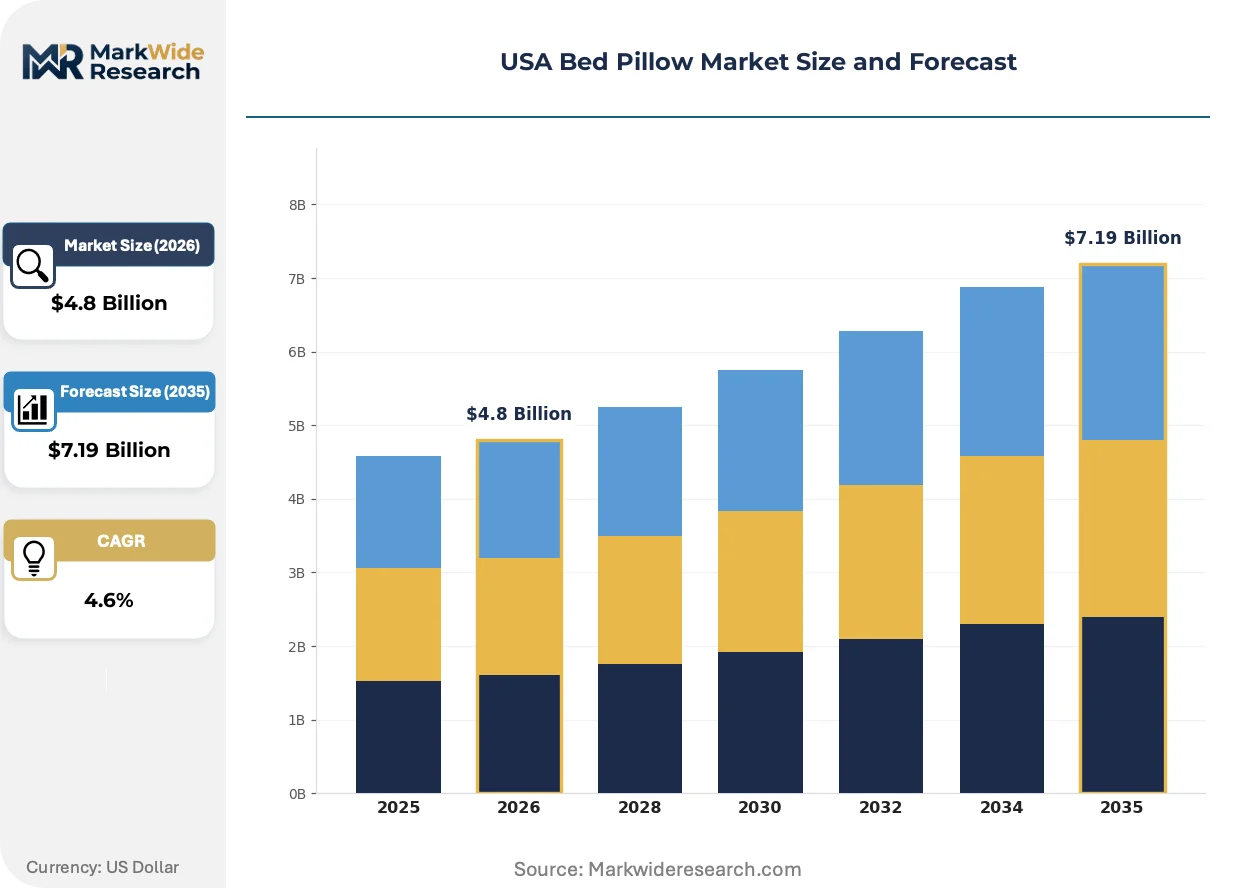
Market Dynamics
Hospitality procurement teams are consolidating vendor relationships around infection-control laundering certifications, compressing supplier lists while elevating fill-material transparency requirements. This concentration dynamic is redistributing volume toward vertically integrated foam compounders capable of certifying full chain-of-custody documentation.
Growth Catalysts
- California Proposition 65 enforcement:Chemical disclosure mandates are accelerating reformulation investments among foam producers, creating first-mover advantages for compliant suppliers in the state's $890 million replacement pillow segment.
- Healthcare-acquired infection protocols:Joint Commission standards for launderable bedding are expanding contract opportunities for antimicrobial fiber suppliers serving acute-care facilities.
- Smart-home ecosystem integration:Adjustable firmness systems with sleep-tracking sensors are capturing premium positioning in the residential upgrade channel.
Market Restraints
- Petrochemical input volatility:Polyurethane precursor costs fluctuate with crude oil indices, compressing margin predictability for domestic viscoelastic foam molders.
- Single-origin down supply concentration:Eighty percent of sterilized waterfowl clusters originate from three Midwest processing cooperatives, creating contamination-risk exposure.
- 16 CFR Part 1632 flammability testing:Cigarette-ignition protocols add twelve to eighteen weeks to new product qualification timelines.
Strategic Opportunities
- Texas Sun Belt housing expansion:Dallas-Fort Worth and Austin metro construction permits are outpacing national averages, establishing replacement-cycle density for premium memory foam products.
- FTC Green Guides third-party verification:Biodegradable claim substantiation creates certification-service revenue streams for testing laboratories.
- Direct-to-consumer subscription refresh models:Sleep-system brands are bypassing traditional retail service networks with predictive replacement algorithms.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for open-cell viscoelastic structures is concentrating among retiring baby-boomer specialists without pipeline replacement.
- Multi-state chemical disclosure fragmentation:Washington and Maine are advancing independent fill-material transparency bills, forcing SKU proliferation for national brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Bed Pillow Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Latex, Down, Synthetic End User: Hotels, Households, Healthcare Facilities, Educational Institutions Size: Standard, Queen, King, Body Distribution Channel: Online Retail, Specialty Stores, Department Stores, Warehouse Clubs |
| Companies Covered | Tempur Sealy International, Sleep Number Corporation, My Pillow Inc, Serta Simmons Bedding LLC, Purple Innovation, Pacific Coast Feather Company, Malouf Companies, Simmons Bedding Company, Casper Sleep Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Bed Pillow Market Evolving Landscape
Material science advances and regulatory disclosure mandates are converging to restructure competitive advantage around verifiable supply-chain documentation rather than performance claims alone.
Phase-change material microencapsulation is migrating from aerospace thermal management applications into consumer bedding. Hospitality procurement teams at select-service chains are piloting graphite-infused memory foam to reduce HVAC load in guest rooms. The technology is migrating from premium boutique properties toward midscale flagged properties as energy-cost pressures intensify.
FTC Green Guides enforcement on environmental marketing claims is compelling manufacturers to substantiate biodegradable assertions with third-party verification. The Consumer Product Safety Commission maintains active surveillance of 16 CFR Part 1632 compliance, with recent warning letters targeting imported latex products. Foam producers operating in California face additional Proposition 65 warning requirement layers that reshape material selection and testing cost structures.
Buyer concentration among hospitality procurement consortia is compressing vendor lists and unbundling after-sales service expectations. Large hotel management companies are consolidating pillow specifications across portfolios, displacing fragmented property-level purchasing. This pattern is most visible in the extended-stay segment, where standardized sleep-system refresh cycles are replacing ad hoc replacement decisions.
USA Bed Pillow Market Segmentation
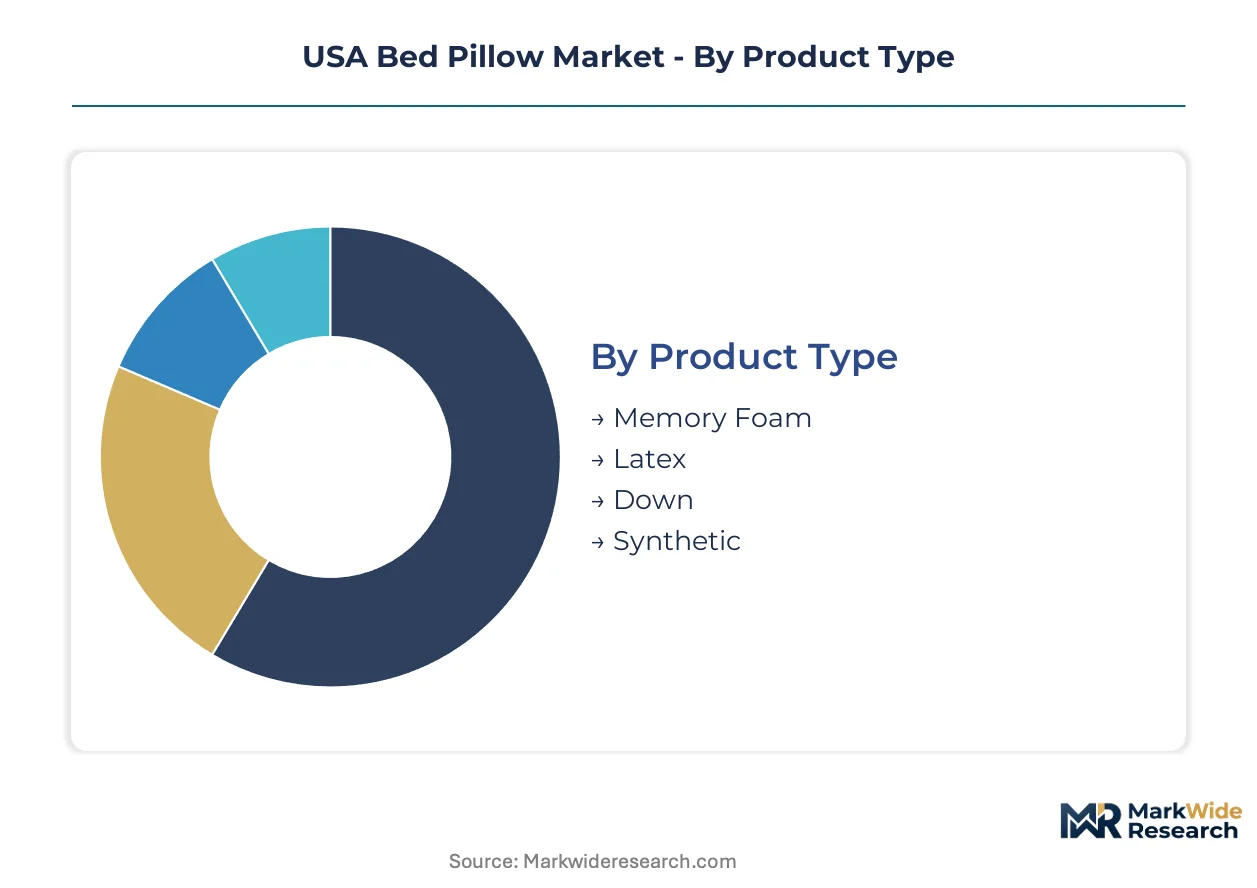
Material composition and procurement channel dynamics create distinct margin profiles across the USA Bed Pillow Market. Segmentation reveals where supply chain investments concentrate and which end-use specifications command premium positioning.
Product Type:
Mature foam technologies anchor volume positions while emerging bio-based alternatives reshape premium tier competition.
- Memory Foam:Viscoelastic polyurethane formulations with open-cell structures dominate therapeutic positioning. Hospitality procurement teams in Texas and California specify these for extended-stay properties requiring durability under commercial laundering protocols.
- Latex:Natural rubber sap derivatives and synthetic styrene-butadiene alternatives offer resilient support with inherent antimicrobial properties. Healthcare facilities in Florida and Arizona are expanding latex specifications for infection-control bedding programs.
- Down:Sterilized waterfowl clusters from Midwest processing cooperatives retain luxury positioning in boutique hospitality.
- Synthetic:Polyester fiberfill and microfiber alternatives occupy mass-market channels through cost efficiency and hypoallergenic certifications.
Memory Foam retains volume leadership; Latex holds the steepest expansion curve.
End User:
Application-driven specifications separate contract procurement standardization from discretionary residential purchasing patterns.
- Hotels:Flagged properties and independent boutiques operate under consolidated procurement consortia demanding infection-control laundering certifications and chain-of-custody documentation. Major management companies are unifying pillow specifications across portfolios.
- Healthcare Facilities:Acute-care hospitals and long-term care centers drive demand for antimicrobial fiber systems compliant with Joint Commission standards. Launderable bedding protocols are expanding contract opportunities for specialized suppliers.
- Households:Residential replacement cycles concentrate in California and Texas housing markets, with smart-home integration driving premium upgrade decisions.
- Educational Institutions:University housing and boarding schools represent a procurement segment prioritizing bulk cost efficiency over performance specifications.
Hotels command the largest contract value concentration; Healthcare Facilities are expanding most quickly.
Size:
Dimensional standardization creates manufacturing scale advantages while specialty formats capture niche margin pools.
- Queen:The dominant residential specification aligns with mattress industry standards and drives replacement-cycle synchronization. Retail inventory depth concentrates around this format.
- Standard:Traditional 20-by-26-inch dimensions persist in hospitality procurement for twin and double room configurations.
- King:Oversized formats serve premium residential master bedrooms and luxury suite categories in resort properties.
- Body:Extended-length pregnancy and orthopedic support pillows represent a specialized channel with direct-to-consumer distribution dominance.
Queen retains volume leadership; Body holds the steepest expansion curve.
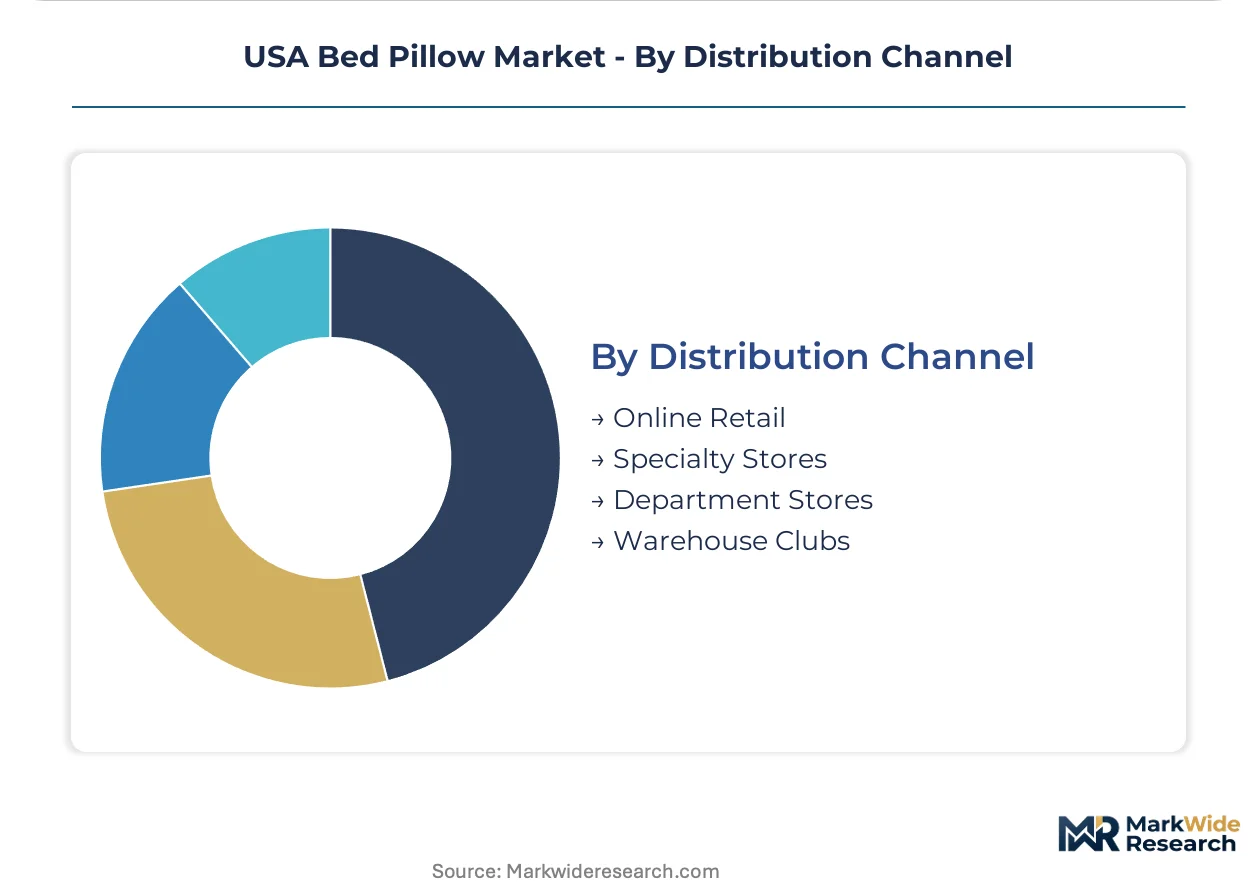
Distribution Channel:
Channel fragmentation is accelerating as direct-to-consumer models bypass traditional retail service networks.
- Online Retail:Subscription refresh models and predictive replacement algorithms are capturing residential replacement cycles. Sleep-system brands leverage data-driven firmness recommendations to sustain recurring revenue.
- Specialty Stores:Mattress retailers and bedding boutiques maintain tactile evaluation advantages for premium foam and latex categories.
- Department Stores:Mid-tier synthetic and down alternatives occupy seasonal promotional calendars with compressed margin structures.
- Warehouse Clubs:Bulk-packaged standard and queen formats serve value-conscious household replacement demand.
Online Retail is gaining share fastest; Specialty Stores retain premium positioning control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional consumption patterns diverge sharply: coastal states prioritize premium foam and smart-home integration while Sun Belt markets drive volume through housing expansion and replacement cycles.
California
Los Angeles and San Francisco metros anchor the nation's largest premium pillow replacement market, with household penetration of adjustable firmness systems outpacing national averages. Proposition 65 enforcement by the California Attorney General's office compels foam producers to reformulate viscoelastic compounds and disclose chemical constituents. The Orange County manufacturing corridor hosts specialized polyurethane compounders certifying chain-of-custody documentation for hospitality procurement consortia.
Texas
Dallas-Fort Worth and Austin construction permits are outpacing national housing growth averages, establishing dense replacement-cycle demand for memory foam products. The Texas Commission on Environmental Quality monitors emissions from foam molding facilities operating near suburban residential zones. Houston's logistics hub concentrates warehousing and distribution infrastructure serving Gulf Coast hospitality properties.
Florida
Miami and Orlando hospitality markets drive antimicrobial latex specifications for infection-control bedding programs in extended-stay and resort properties. The Florida Department of Health enforces laundering certification standards for commercial bedding suppliers serving acute-care facilities. Tampa's medical corridor anchors healthcare procurement concentration for launderable fiber systems.
New York
The New York Metro area sustains boutique hospitality demand for luxury down and specialty fill configurations in Manhattan and Brooklyn hotel properties. The New York State Department of Environmental Conservation oversees chemical disclosure requirements for foam products sold through retail channels. Long Island's manufacturing base supplies synthetic fill alternatives to mass-market distributors.
Illinois
Chicago's central logistics position supports national distribution networks for warehouse club and department store pillow programs. The Illinois Environmental Protection Agency regulates emissions from polyurethane processing facilities operating in Cook County. Rockford's industrial corridor hosts mid-tier foam fabricators serving Midwest hospitality chains.
USA Bed Pillow Market Competitive Landscape
Capability concentration sits with specialized foam compounders and clinical research partners; scale advantage sits with vertically integrated bedding conglomerates and direct-to-consumer platforms. The market structures around three tiers: premium therapeutic specialists, mass-market synthetic suppliers, and digitally native subscription brands. Consolidation pressures are elevating procurement standards and compressing vendor lists. Competitive moves center on certification investments for hospitality contracts and predictive replacement algorithms for residential retention.
Within the premium therapeutic tier, Tempur Sealy International and Sleep Number Corporation exemplify divergent positioning strategies. Tempur Sealy anchors its market presence through clinical sleep research partnerships and hospitality procurement relationships. Sleep Number occupies a position defined by adjustable firmness technology and smart-home ecosystem integration. My Pillow Inc represents the domestically manufactured mass-market vector, competing through broadcast channel control and patriotic sourcing messaging.
| Leading Market Players |
|---|
| Tempur Sealy International |
| Sleep Number Corporation |
| My Pillow Inc |
| Serta Simmons Bedding LLC |
| Purple Innovation |
| Pacific Coast Feather Company |
| Malouf Companies |
| Simmons Bedding Company |
| Casper Sleep Inc |
| Others |
Value Network & Pricing Analysis
The Orange County polyurethane compounding corridor anchors domestic viscoelastic foam capacity, with its specialized molders commanding premium contract terms from hospitality procurement consortia seeking chain-of-custody documentation. This geographic concentration translates into asymmetric pricing power where certified suppliers extract margin premiums from flagged hotel properties while uncertified competitors face price erosion in mass retail channels.
Pricing Analysis
Long-term offtake agreements dominate hospitality procurement, with flagged properties locking in eighteen-to-twenty-four month contracts for memory foam and latex categories. Price differentiation hinges on certification tier—California Proposition 65 compliance and FTC Green Guides third-party verification command fifteen-to-twenty percent premiums over uncertified alternatives. Cost compression intensifies in synthetic fiberfill segments as warehouse clubs and educational institutions consolidate volume purchasing. Healthcare facilities exhibit lowest price sensitivity, prioritizing antimicrobial performance and Joint Commission laundering certifications over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates among vertically integrated foam compounders operating in California, Texas, and Illinois, with specialized polyurethane molders holding captive capacity for hospitality and healthcare channels. Raw material flows draw from petrochemical feedstocks, Midwest down processing cooperatives, and imported natural rubber latex derivatives. Single-source vulnerability concentrates in sterilized waterfowl clusters, where eighty percent of domestic supply originates from three Midwest cooperatives. Distribution runs through Houston and Chicago logistics hubs serving regional hospitality properties, with direct-to-consumer subscription models bypassing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart-home ecosystem interoperability is redefining competitive moats in residential sleep systems, with adjustable firmness platforms capturing recurring revenue through predictive replacement algorithms rather than transactional retail relationships.
For Market Incumbents: Pre-empt direct-to-consumer subscription erosion by securing exclusive hospitality procurement consortia contracts with embedded refresh-cycle commitments. Tempur Sealy International and Sleep Number Corporation should deepen clinical research partnerships to defend therapeutic positioning against digitally native entrants. Certification investments in FTC Green Guides verification and California Proposition 65 compliance create switching costs for flagged hotel properties. For New Entrants and Emerging Players: Establish a beachhead in antimicrobial latex specifications for Florida and Arizona healthcare facilities, where Joint Commission laundering protocols are displacing incumbent fiber suppliers. The educational institution segment offers lowest competitive density, with bulk cost efficiency requirements favoring synthetic fiberfill specialists over premium foam compounders. Direct-to-consumer subscription models with predictive replacement algorithms capture residential replacement cycles bypassed by traditional retail networks. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory disclosure mandates are concentrating procurement volume among vertically integrated compounders with full chain-of-custody documentation. Target acquisition profiles center on specialized polyurethane molders with California Proposition 65 compliance and hospitality contract relationships. Monitor state-level chemical disclosure legislation in Washington and Maine as inflection indicators for SKU proliferation costs.| Strategic Initiative | Industry Significance |
|---|---|
| FTC Green Guides Third-Party Certification | Biodegradable claim substantiation creates defensible positioning in California's premium replacement segment. |
| Hospitality Procurement Consortium Lock-In | Extended-stay portfolio standardization secures multi-year offtake with embedded refresh-cycle revenue. |
| Smart-Home Ecosystem Integration | Adjustable firmness platforms with sleep-tracking sensors capture recurring subscription revenue streams. |
| Antimicrobial Fiber System Development | Joint Commission-compliant laundering protocols open acute-care facility contracts in Florida and Arizona. |
| Direct-to-Consumer Subscription Launch | Predictive replacement algorithms bypass retail service networks and capture residential retention economics. |
Research Methodology
A standing panel of hospitality procurement directors, healthcare facility supply chain managers, polyurethane compounder operations heads, and direct-to-consumer brand executives provided ongoing calibration across primary fieldwork. Secondary validation drew from FTC enforcement actions, California Attorney General Proposition 65 filings, hospitality industry trade association procurement surveys, and SEC 10-K disclosures from publicly traded bedding manufacturers. Bottom-up volume estimates from material flow analysis were triangulated against top-down expenditure models derived from housing construction permits and replacement-cycle assumptions.
Scenario-bracketing around petrochemical input volatility and regulatory enforcement intensity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include material composition, end-user procurement channel, dimensional format, and distribution structure. CAGRs were derived from elasticity-adjusted replacement rates and contract procurement standardization trends. Forecast inputs incorporated hospitality property pipeline data from select-service and extended-stay development trackers alongside smart-home device penetration curves.
Sensitivities concentrate around crude oil index fluctuations affecting polyurethane precursor costs and state-level chemical disclosure fragmentation forcing SKU proliferation. Forecasts reflect assumptions regarding hospitality construction permitting velocity and healthcare-acquired infection protocol adoption rates. Quarterly review of FTC Green Guides enforcement actions and state attorney general Proposition 65 settlement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Home Decor Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
Interior Design Market
Homecare and Decor
Gas Fire Table Market
Homecare and Decor
Saudi Arabia Interior Design Market
Homecare and Decor
Home Decor and Accessories Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Asia-Pacific Decor Paper Market
Homecare and Decor
Builders and Cabinet Hardware Market
Homecare and Decor
Christmas Tree Market
Homecare and Decor
Mattress Topper Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Asia-Pacific Sustainable Home Decor Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
India Wallpapers Market