
 North America Remote Sensing Satellites Market | 2026-2036
North America Remote Sensing Satellites Market Size, Share, and Industry Trends Forecast 2026-2036
North America Remote Sensing Satellites Market Insights
Defense and intelligence demand is decoupling from traditional government procurement cycles as commercial satellite operators win classified contracts. Capella Space Corp. leverages synthetic aperture radar expertise to penetrate defense channels previously reserved for primes. Lockheed Martin Corporation anchors high-altitude persistent infrared programs while competing with agile newcomers. Planet Labs Inc. dominates optical Earth observation with daily global coverage that intelligence agencies now integrate into operational workflows.
Remote sensing satellites are spacecraft equipped with optical, radar, multispectral, or hyperspectral sensors that collect electromagnetic data from Earth's surface at resolutions ranging from sub-meter to hundreds of meters, transmitting processed imagery for geospatial analysis and decision support. Optical imaging sustains the largest revenue share due to maturity and cost efficiency, while radar imaging is accelerating fastest as all-weather, day-night capability becomes mission-critical for defense and disaster response. Low Earth Orbit deployment occupies the dominant position because reduced latency and launch costs enable constellation architectures that geostationary platforms cannot match.
The U.S. Space Force, NRO, and FCC collectively shape market access through spectrum allocation, launch licensing, and classified procurement standards that favor domestic supply chains. NOAA and NASA calibration requirements for climate data create additional compliance layers that filter out non-compliant operators. Stakeholders must monitor how ITAR reform discussions and emerging commercial remote sensing regulations alter competitive barriers for foreign-owned subsidiaries operating within North America.
Market Dynamics
Defense procurement reform is fragmenting the North American remote sensing satellites market, as classified contracts migrate from traditional primes to commercial operators with synthetic aperture radar and hyperspectral capabilities. The U.S. Space Force and NRO modernization programs are rewriting supplier qualification pathways.
Growth Catalysts
- ITAR Reform Momentum:Proposed export control revisions are easing technology transfer restrictions for Canadian and Australian allied programs, expanding addressable demand for U.S. sensor manufacturers.
- Climate Data Mandates:NOAA's Commercial Weather Data Pilot program is creating recurring revenue streams for radio occultation and microwave sounder operators serving federal calibration requirements.
- Wildfire Response Integration:State emergency management agencies across California, Colorado, and Oregon are embedding commercial thermal infrared into dispatch workflows, accelerating procurement cycles outside federal budget windows.
Market Restraints
- Launch Bottleneck Concentration:Domestic heavy-lift capacity dependence on SpaceX Falcon 9 and United Launch Alliance Vulcan Centaur creates single-point-of-failure risk for constellation deployment schedules.
- Spectrum Coordination Friction:FCC Part 25 licensing timelines for Ka-band and V-band downlinks extend 18-24 months, delaying revenue recognition for operators with ready spacecraft.
- Optical Resolution Saturation:Sub-30 centimeter imagery commoditization is compressing pricing power for established electro-optical providers without differentiation in revisit frequency or analytics layering.
Strategic Opportunities
- Arctic Domain Awareness:Canadian Department of National Defence ice surveillance gaps are creating demand for synthetic aperture radar constellations with 24-hour polar coverage, underserved by current operators.
- Carbon Monitoring Verification:California Air Resources Board compliance protocols for cap-and-trade markets are mandating satellite-based methane detection, opening specialized sensor procurement channels.
- AI-Assisted Analytics Bundling:Convergence of onboard edge processing with ground-based machine learning is enabling subscription revenue models that decouple value from raw pixel delivery.
Industry Challenges
- Spacecraft Bus Talent Scarcity:Power subsystem and attitude control engineering expertise concentrates at legacy primes and a handful of venture-backed startups, inflating compensation and extending hiring cycles.
- End-of-Life Debris Compliance:FCC orbital debris mitigation rules requiring post-mission disposal within five years are forcing premature replacement capex and constraining mission extension economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Remote Sensing Satellites Market |
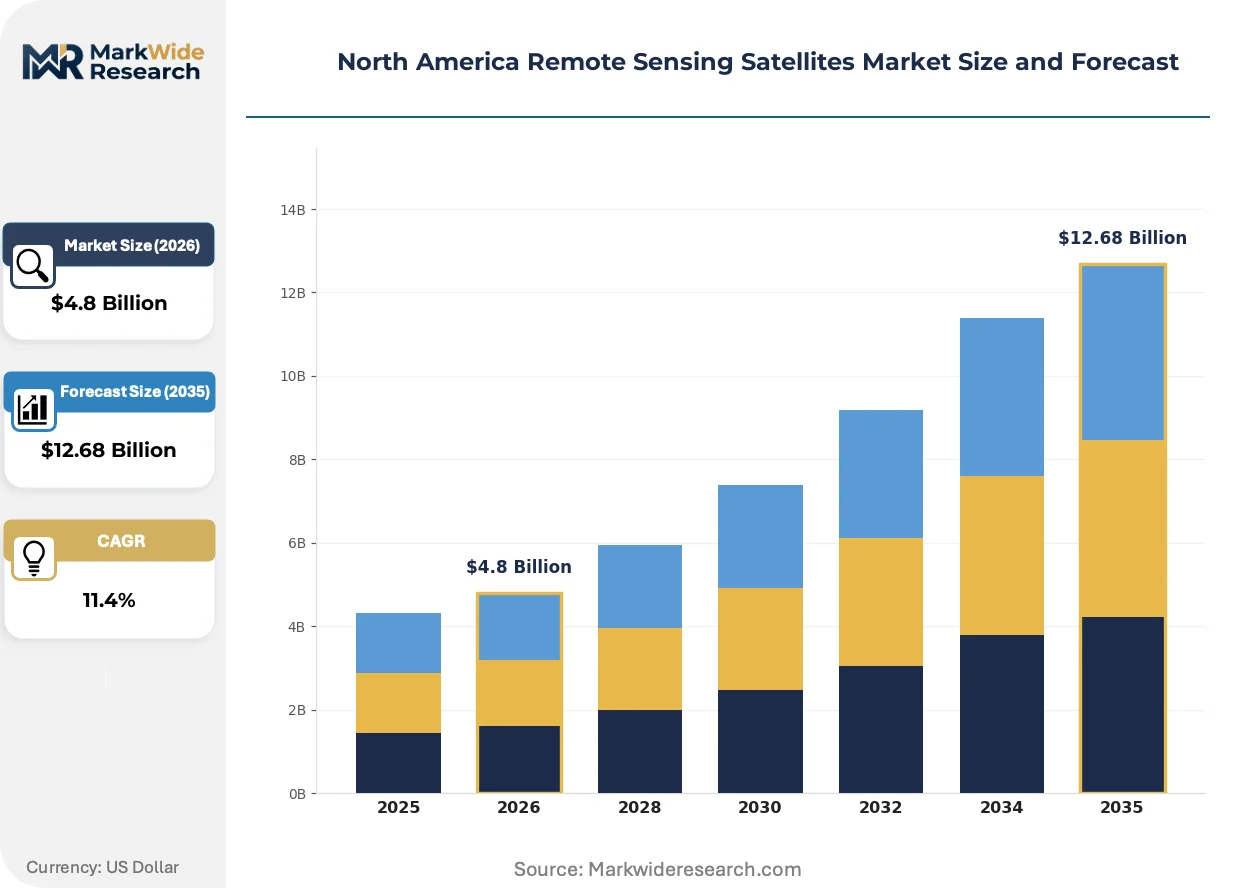
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Urban Planning, Disaster Management, Environmental Monitoring Technology: Optical Imaging, Radar Imaging, Multispectral Imaging, Hyperspectral Imaging End User: Government, Defense, Research Institutions, Commercial Enterprises Deployment: Low Earth Orbit, Geostationary Orbit, Medium Earth Orbit, Sun-Synchronous Orbit |
| Companies Covered | Capella Space Corp., LeoStella, Lockheed Martin Corporation, Northrop Grumman Corporation, Planet Labs Inc., Maxar Technologies Inc., Ball Corporation, BlackSky, Spire Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Remote Sensing Satellites Market Trends and Innovations
Synthetic aperture radar payloads are fragmenting into standardized subsystems, enabling non-aerospace entrants to assemble spacecraft without prime contractor integration. This architectural shift is compressing development timelines and reshaping supplier hierarchies across the continent.
Satellite payload electronics is modularizing around open standards like the SpaceVPX and SOSA technical architectures, allowing sensor providers to swap processors and software-defined radios without bus redesign. Defense primes including Lockheed Martin and Northrop Grumman are adopting these interfaces for rapid technology refresh cycles. The structural consequence is that component vendors are capturing margin previously retained by vertically integrated spacecraft manufacturers.
The U.S. Space Force's Commercial Space Strategy directive is mandating "proliferated architecture" procurement, requiring disaggregated constellations over single large platforms. This policy is redirecting NRO and Space Development Agency budgets toward commercial operators with existing manufacturing lines. Small satellite bus manufacturers in Colorado and California are expanding cleanroom capacity to capture this demand rotation.
Intelligence community buyers are unbundling imagery from analytics, contracting directly with software firms for change detection and feature extraction rather than accepting bundled prime contractor offerings. This disintermediation is visible most acutely in NRO's Electro-Optical Commercial Layer program and CIA's In-Q-Tel portfolio investments. Canadian defence procurement is following this pattern through the Department of National Defence's IDEaS program structure.
North America Remote Sensing Satellites Market Segmentation
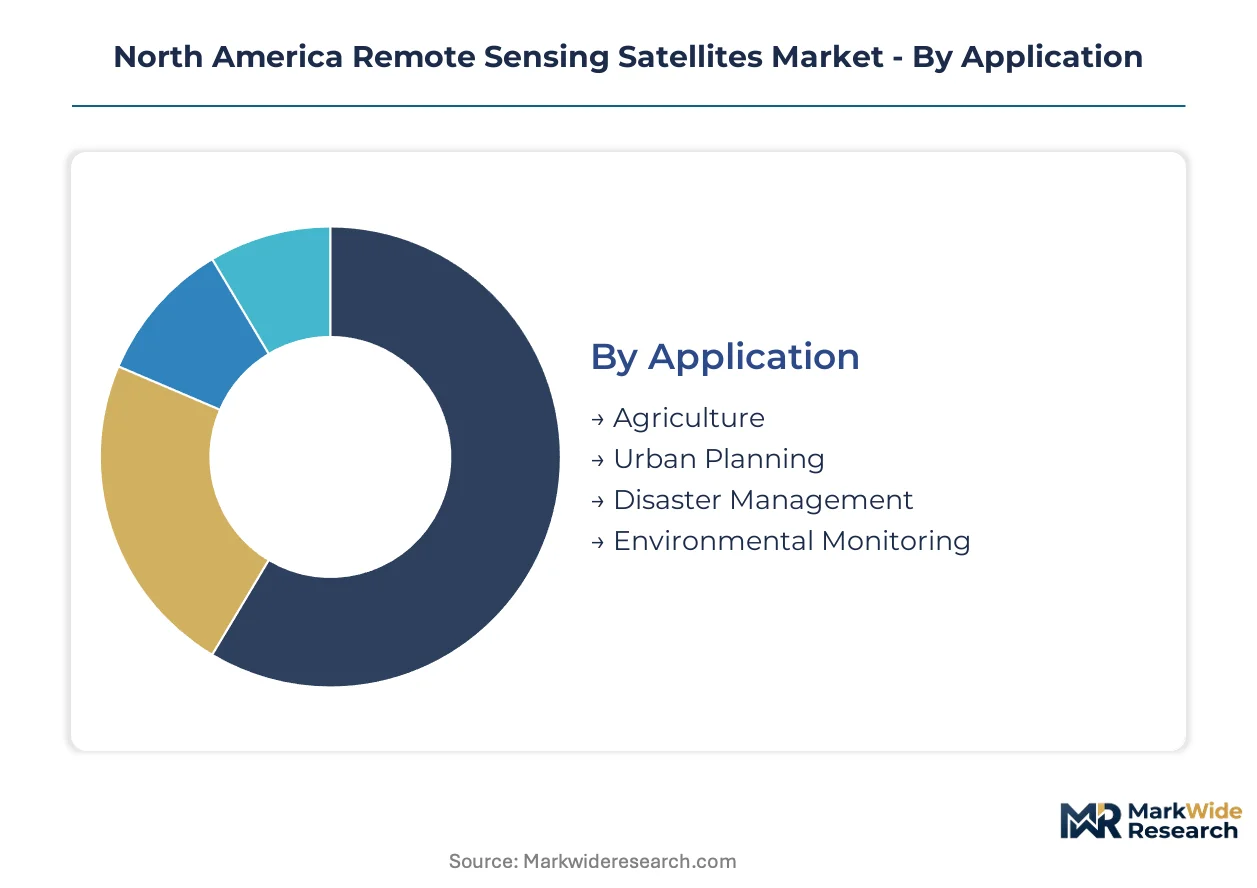
Segmentation reveals how procurement priorities diverge across mission types and customer budgets in the North America remote sensing satellites market. Buyers select technology combinations based on revisit requirements, atmospheric conditions, and data latency tolerances that vary sharply by application.
Application:
Procurement cycles and sensor specifications diverge sharply based on whether buyers need tactical responsiveness or long-term trend analysis.
- Agriculture:Multispectral and hyperspectral sensors track crop health, soil moisture, and yield predictions across the U.S. Corn Belt and Canadian Prairie provinces. State agriculture departments in Iowa and Manitoba contract for seasonal monitoring services that integrate with precision farming platforms.
- Urban Planning:Municipal governments leverage sub-meter optical imagery for zoning enforcement, infrastructure mapping, and informal settlement detection in Sun Belt metropolitan expansion corridors. Demand clusters where population growth strains existing cadastral systems.
- Disaster Management:Federal Emergency Management Agency and state emergency operations centers require rapid-tasking radar and thermal infrared for flood perimeter mapping and wildfire progression tracking.
- Environmental Monitoring:EPA regional offices and tribal environmental programs contract for methane plume detection and watershed quality assessment across the Permian Basin and Great Lakes drainage.
Volume sits with Agriculture; growth tilts toward Disaster Management.
Technology:
Cost per square kilometer captured and all-weather reliability dictate technology selection more than resolution alone.
- Optical Imaging:Electro-optical sensors dominate commercial procurement due to mature supply chains and lower per-unit spacecraft costs. Daily revisit capabilities from Planet Labs and Maxar serve media, agriculture, and urban analytics customers across the United States and Canada.
- Radar Imaging:Synthetic aperture radar penetrates cloud cover and darkness, making it indispensable for defense intelligence and Arctic maritime surveillance. Capella Space and ICEYE have established domestic manufacturing lines to capture classified demand from the NRO and Canadian Department of National Defence.
- Multispectral Imaging:Five-to-ten band sensors balance spectral discrimination with data throughput for agricultural insurance and forestry inventory applications.
- Hyperspectral Imaging:Hundreds of contiguous spectral bands enable mineral identification and chemical composition analysis for mining exploration and environmental enforcement.
Optical Imaging commands installed base; Radar Imaging climbs the fastest on defense reclassification of commercial capabilities.
End User:
Budget authorization mechanisms and data security classifications segment the customer base more than mission requirements alone.
- Government:Civilian agencies including NASA, NOAA, and USGS operate research-focused missions with open data mandates. Procurement flows through multi-year appropriations with congressional oversight of mission specifications.
- Defense:Classified programs under the NRO, U.S. Space Force, and Canadian Department of National Defence drive premium pricing for tasking priority and encrypted downlinks. Commercial operators now compete directly with Boeing and Lockheed Martin for these contracts.
- Research Institutions:Universities and federally funded research centers access archived data through NASA's Commercial Smallsat Data Acquisition Program and similar mechanisms.
- Commercial Enterprises:Insurance underwriters, commodity traders, and infrastructure operators purchase analytics-ready products rather than raw imagery, shifting value capture toward software layers.
Defense concentrates contract value; Commercial Enterprises expand the addressable base fastest.
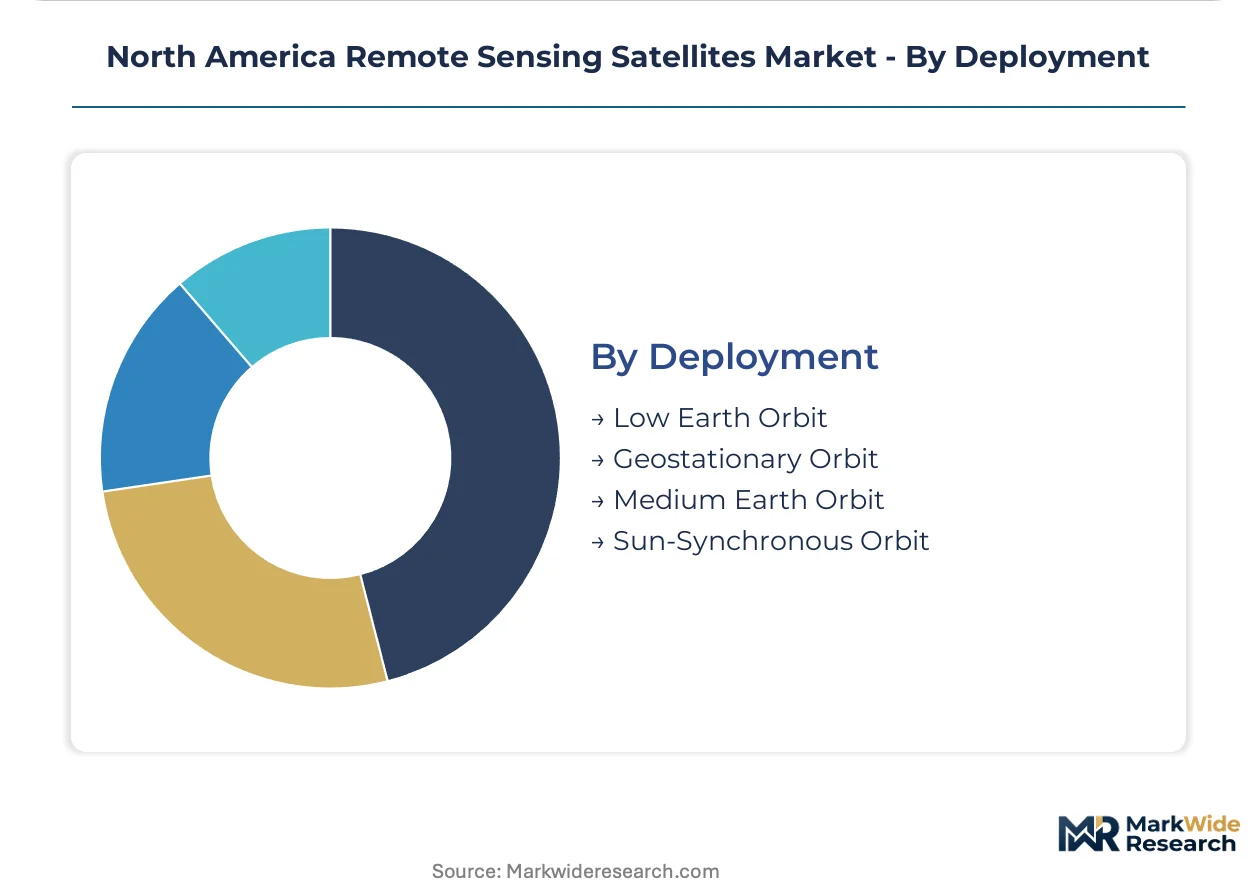
Deployment:
Altitude selection trades coverage persistence against revisit frequency and launch economics.
- Low Earth Orbit:Altitudes below 2,000 kilometers enable small satellite constellations with latency measured in minutes rather than hours. SpaceX rideshare and dedicated small launch vehicles from Rocket Lab and Firefly Aerospace have collapsed deployment costs for LEO architectures.
- Geostationary Orbit:Fixed position relative to Earth's surface supports continuous regional stare capabilities for missile warning and weather monitoring. Lockheed Martin and Northrop Grumman anchor this segment with billion-class platforms.
- Medium Earth Orbit:Intermediate altitudes serve specialized navigation augmentation and communication relay missions with reduced radiation exposure compared to GEO.
- Sun-Synchronous Orbit:Polar orbits with consistent local solar time illumination enable change detection algorithms that require standardized lighting conditions for environmental and agricultural monitoring.
Low Earth Orbit hosts constellation density; Sun-Synchronous Orbit gains share in climate data calibration missions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Opportunity Zones program and Canadian Scientific Research and Experimental Development tax credits concentrate remote sensing satellite investment in designated aerospace corridors across North America. These fiscal instruments accelerate facility placement and R&D capitalization for constellation operators and sensor manufacturers.
United States
Defense procurement reform under the U.S. Space Force Commercial Space Strategy redirects NRO and Space Development Agency budgets toward disaggregated LEO architectures. FCC Part 25 licensing governs Ka-band and V-band downlink authorizations with 18-24 month timelines. California's aerospace corridor from El Segundo to San Jose hosts Capella Space and Planet Labs manufacturing operations, while Colorado's Front Range anchors satellite operations centers for classified mission support.
Canada
Arctic Domain Awareness requirements from the Department of National Defence drive demand for synthetic aperture radar with 24-hour polar coverage capabilities. The IDEaS program structure mirrors U.S. intelligence community procurement patterns, unbundling imagery from analytics for direct software firm contracting. Montreal and Toronto metropolitan areas concentrate AI-assisted analytics startups serving federal ice surveillance and methane monitoring mandates under Environment and Climate Change Canada protocols.
Mexico
Agency for Space Affairs coordination with CONACYT research networks creates emerging demand for agricultural monitoring across the Bajío grain belt and Yucatán Peninsula. The federal Telecommunications and Broadcasting Law framework governs satellite spectrum allocation for commercial Earth observation downlinks. Querétaro's aerospace manufacturing cluster hosts subsystem suppliers for U.S. prime contractor supply chains, while Mexico City anchors regional sales operations for constellation operators.
North America Remote Sensing Satellites Market Competitive Landscape
Top-tier vendors anchor classified defense procurement, while commercial constellation operators capture shifting NRO and Space Force modernization budgets. The market exhibits tiered concentration with legacy primes competing against venture-backed newcomers for disaggregated architecture contracts. Three strategic archetypes dominate: vertically integrated primes with billion-class GEO platforms, agile SAR specialists with rapid revisit capabilities, and optical constellation operators with daily global coverage. Competitive moves center on manufacturing capacity expansion in Colorado and California cleanroom facilities, plus strategic partnerships for AI-assisted analytics bundling.
Within the defense prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation represent established suppliers of high-altitude persistent infrared and geostationary platforms. Among commercial constellation operators, Capella Space Corp. and Planet Labs Inc. exemplify the agile newcomers penetrating classified channels previously reserved for traditional suppliers. These companies occupy positions across the capability spectrum from sub-meter optical imaging to all-weather synthetic aperture radar, reflecting the procurement fragmentation reshaping supplier hierarchies.
| Leading Market Players |
|---|
| Capella Space Corp. |
| LeoStella |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Planet Labs Inc. |
| Maxar Technologies Inc. |
| Ball Corporation |
| BlackSky |
| Spire Global, Inc. |
| Others |
Pricing and Supply Chain Analysis
Attitude control and power subsystem engineering talent concentrates in Colorado's Front Range and California's aerospace corridor, inflating compensation spreads that translate directly into three-tier pricing stratification across premium defense-grade, standard commercial, and economy rideshare tiers.
Pricing Analysis
Short lead-time premiums for rapid-tasking radar capacity command 40-60% markups over standard subscription rates, while spot inventory for optical imagery trades at discounts to annual contracts. The dominant model runs through SaaS-tiered subscriptions with tasking priority tiers. Price differentiation separates encrypted downlink defense contracts from open-data civilian missions, with volume scale and revisit frequency as secondary levers. Pricing pressure stems from sub-30 centimeter optical commoditization compressing margins for established electro-optical providers. Commercial enterprises exhibit highest price sensitivity, while defense intelligence buyers prioritize mission assurance over unit cost.
Supply Chain Analysis
End-of-life satellite refurbishment and component recovery flows remain nascent, with deorbiting mandates forcing premature replacement rather than remanufacturing economics. Manufacturing concentrates in the United States, Canada, and select Mexican subsystem clusters near Querétaro. Supply chains draw from gallium arsenide solar cells, indium phosphide photonics, and radiation-hardened processors as critical inputs. Single-source vulnerability concentrates in domestic heavy-lift launch capacity, with SpaceX Falcon 9 and United Launch Alliance Vulcan Centaur anchoring deployment schedules. Distribution runs through direct federal procurement channels for classified missions and commercial sales teams for enterprise analytics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over sensor manufacturing and launch access determines margin capture, with players pursuing backward integration into spacecraft bus production to reduce prime contractor dependence.
For Market Incumbents: Deploy manufacturing capacity expansion in Colorado and California cleanroom facilities to capture proliferated architecture demand from the U.S. Space Force and NRO. Lockheed Martin and Northrop Grumman must accelerate open-standard payload interfaces to defend against agile SAR specialists penetrating classified channels. Certification investment in NOAA calibration protocols and FCC Part 25 licensing expertise creates switching costs against commercial entrants. For New Entrants and Emerging Players: Launch via Arctic Domain Awareness procurement channels targeting Canadian Department of National Defence ice surveillance gaps underserved by current operators. White-space sits with AI-assisted analytics bundling for carbon monitoring verification under California Air Resources Board protocols, plus methane detection subscription services for Permian Basin operators. The most penetrable segment is state emergency management agencies embedding thermal infrared into wildfire dispatch workflows outside federal budget windows. For Investors and Strategic Acquirers: Re-rating potential sits with small satellite bus manufacturers possessing cleanroom capacity and existing defense contracts given the U.S. Space Force's proliferated architecture procurement mandate. Long-term viability over the next decade hinges on securing recurring revenue streams through federal weather data pilots and classified electro-optical commercial layer programs. Watch for ITAR reform momentum easing technology transfer to Canadian and Australian allied programs as the inflection signal for expanded addressable demand.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Capacity Expansion | Captures U.S. Space Force proliferated architecture demand rotation toward disaggregated LEO constellations. |
| Open-Standard Payload Integration | Enables rapid technology refresh cycles through SpaceVPX and SOSA architectures adopted by defense primes. |
| AI-Assisted Analytics Bundling | Decouples value from raw pixel delivery through subscription models integrating onboard edge processing. |
| Arctic Surveillance Capability Buildout | Addresses Canadian Department of National Defence 24-hour polar coverage gaps with synthetic aperture radar. |
| Carbon Monitoring Certification | Opens specialized procurement channels under California Air Resources Board cap-and-trade compliance protocols. |
Research Methodology
SEC filings, FCC Part 25 licensing databases, and U.S. Space Force budget justification documents formed the secondary backbone, cross-referenced with primary interviews involving satellite bus manufacturing executives, NRO procurement officers, and commercial constellation operators. Bottom-up and top-down triangulation validated segment sizing across optical, radar, multispectral, and hyperspectral technology categories.
Bottom-up modeling built from individual constellation deployment schedules, sensor unit economics, and federal contract award patterns, while top-down analysis anchored total addressable demand through defense modernization appropriations and climate data mandate budgets. Segmentation dimensions spanned application type, sensor technology, end-user budget authorization mechanism, and orbital deployment altitude. CAGRs derived from deployment pipeline visibility and procurement cycle acceleration factors, with launch cost trajectories and ITAR reform probability weighted as scenario inputs.
Launch schedule delays, spectrum licensing timeline extensions, and defense procurement reclassification reversals are the dominant revision risks to modeled outputs. Forecasts embed assumptions regarding continued U.S. Space Force commercial strategy alignment and NOAA Commercial Weather Data Pilot program continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
LEO Satellite System Market
Satellite
Satellite Internet Market
Satellite
UAE Satellite Imagery Services Market
Satellite
Satellite Amplifier Market
Satellite
Satellite Services Market
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
Germany Satellite Imagery Services Market
Satellite
All-Electric Propulsion Satellites Market
Satellite
France Satellite Imagery Services Market
Satellite
Satellite Communication Subsystem Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
North America Satellite IoT Market
Satellite
Nanosatellite Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market