
 Global Ligation Devices Market | 2026-2036
Global Ligation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ligation Devices Market Foresight
China is narrowing its reliance on imported ligation platforms through domestic manufacturing scale-up in Jiangsu and Zhejiang provinces. Medtronic leverages vertically integrated polymer molding capabilities to sustain cost leadership across hemostatic clip portfolios. Ethicon anchors North American hospital contracts through broad GPO access and surgeon training infrastructure. B. Braun Melsungen AG competes on titanium-alloy loop ligator specialization across European teaching hospitals.
Ligation devices are mechanical or energy-based instruments designed to occlude blood vessels, ducts, or tissue structures during surgical intervention, typically constructed from biocompatible polymers, titanium, or stainless steel with jaw aperture specifications ranging from 5 mm to 10 mm for laparoscopic compatibility. Their primary commercial purpose is to achieve secure hemostasis or anatomical isolation while minimizing thermal spread and tissue trauma in minimally invasive and open procedures. Hemostatic clips occupy the largest revenue pool due to universal deployment across general surgery and gynecology applications, whereas ultrasonic ligators represent the fastest-expanding segment as energy-based sealing displaces mechanical clipping in thick-vessel procedures. Single-use deployment dominates hospital procurement protocols, though reusable instrument programs persist in ambulatory surgical centers seeking per-procedure cost compression.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence burdens for manufacturers seeking dual-market access. ISO 13485 quality management systems and biocompatibility testing under ISO 10993 govern material selection and sterilization validation across all commercial jurisdictions. Stakeholders must monitor evolving EU F-Gas Regulation implications for sterilization gas alternatives and track FDA guidance on reusable device reprocessing validation as sustainability pressures intensify procurement criteria.
Market Dynamics
Energy-based sealing platforms are compressing mechanical clip margins as ultrasonic and bipolar technologies displace titanium and polymer staples in thick-vessel procedures across tertiary surgical centers.
Growth Catalysts
- Laparoscopic procedure volume expansion:Tertiary hospitals in China and the United States are scaling minimally invasive suites, creating installed base demand for compatible 5-10 mm ligation platforms.
- EU MDR technical documentation harmonization:Convergence with FDA 510(k) biocompatibility standards is streamlining dual-market access for polymer-based clip manufacturers holding ISO 13485 certification.
- Titanium-alloy specialization:European teaching hospitals are standardizing on reusable loop ligators for cost-per-procedure compression in high-volume general surgery departments.
Market Restraints
- Polymer raw material volatility:Medical-grade bioresorbable polymer feedstock costs fluctuate with specialty chemical supply constraints, pressuring disposable clip margins.
- Validation cost inflation:ISO 10993 biocompatibility testing requirements under FDA and EU MDR convergence are extending product development timelines for new entrants.
- Ultrasonic platform substitution:Energy-based vessel sealing systems are capturing thick-tissue procedures previously dominated by mechanical clipping in cardiac and bariatric applications.
Strategic Opportunities
- Jiangsu-Zhejiang manufacturing clusters:China's domestic production scale-up offers import substitution potential for regional hospital procurement systems seeking supply security.
- Ambulatory surgical center channel expansion:Reusable instrument programs targeting cost-conscious outpatient facilities represent underserved demand outside tertiary hospital networks.
- F-Gas Regulation sterilization alternatives:EU transition away from fluorinated greenhouse gases for device sterilization creates first-mover advantage for ethylene oxide and vaporized hydrogen peroxide validation.
Industry Challenges
- Surgeon training infrastructure gaps:Energy-based ligation platforms require specialized credentialing programs that strain hospital education budgets and extend sales cycles.
- Legacy device reprocessing validation:FDA guidance on reusable instrument sterilization protocols demands capital-intensive documentation that disadvantages mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ligation Devices Market |
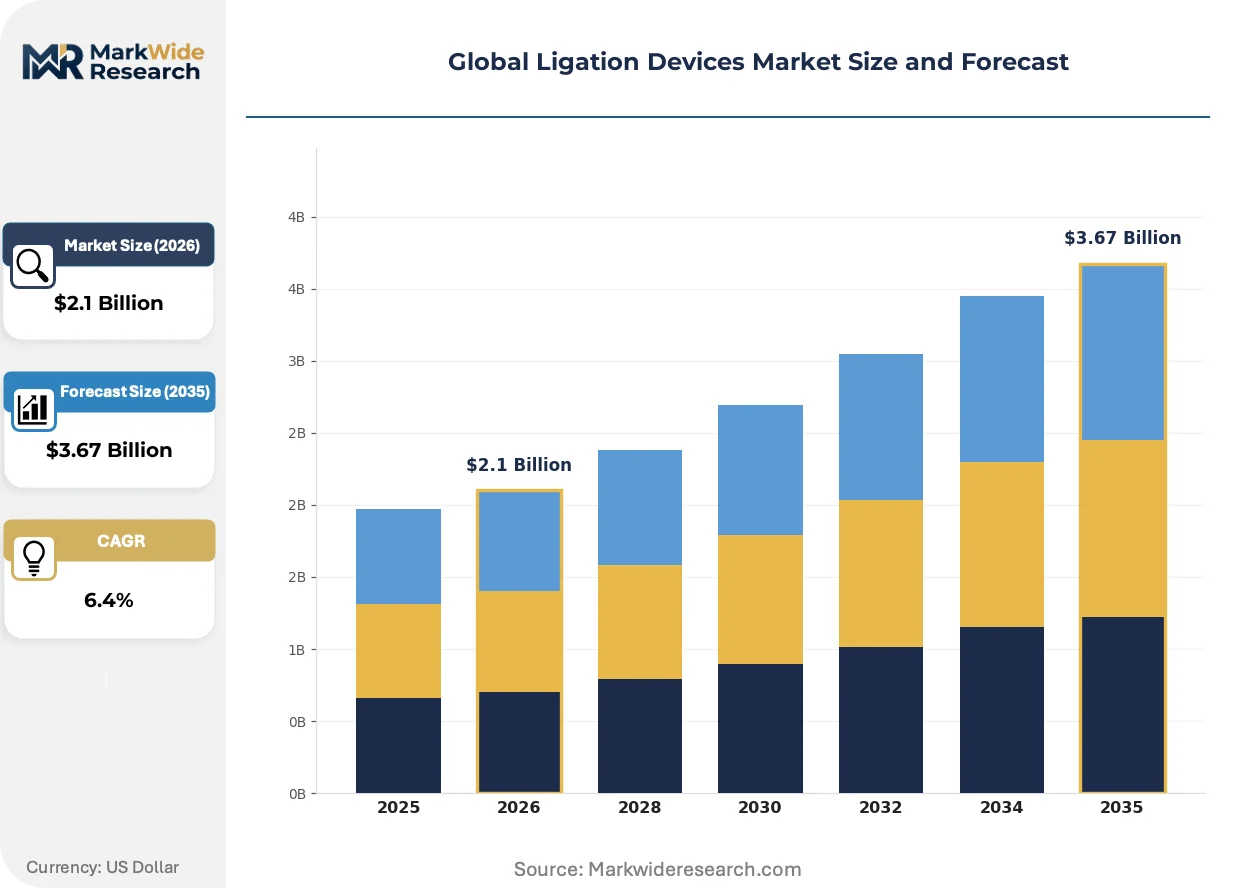
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemostatic Clips, Vessel Ligatures, Loop Ligators, Ultrasonic Ligators, Others Application: General Surgery, Gynecology, Urology, Thoracic Surgery, ENT Procedures End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories Deployment: Single-Use, Reusable, Disposable, Semi-Permanent |
| Companies Covered | Medtronic, Ethicon, Teleflex Incorporated, Olympus Corporation, Applied Medical Resources Corporation, CONMED Corporation, CooperSurgical, B. Braun Melsungen AG, Genicon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ligation Devices Market Shifts & Advancements
Device architectures are converging around dual-energy modalities that blend ultrasonic sealing with bipolar coagulation, compressing the distinction between mechanical and energy-based ligation categories.
Polymer-titanium composite clip designs are hybridizing mechanical security with thermal insulation properties. Tertiary hospital procurement committees in Germany and the United States are specifying these platforms for hybrid open-laparoscopic procedures. The technology is hybridizing previously separate device categories into unified surgical trays that reduce inventory complexity.
EU F-Gas Regulation phase-down mandates are accelerating sterilization gas substitution across European manufacturing facilities. Device producers are revalidating ethylene oxide and nitrogen dioxide cycles ahead of 2030 reduction targets. Jiangsu-based contract manufacturers serving EU markets are investing in alternative sterilization infrastructure to maintain CE marking access.
Hospital group purchasing organizations are consolidating vendor panels around full-procedure bundles rather than discrete device procurement. United States health systems are unbundling after-sales service from capital equipment contracts, forcing manufacturers to price training and maintenance separately. This compression is most visible in multi-hospital networks across Texas and California seeking per-procedure cost transparency.
Global Ligation Devices Market Segmentation
Ligation device procurement patterns diverge sharply across clinical settings, with procedure volume, sterilization infrastructure, and reimbursement density determining which configurations dominate specific hospital tiers. Segment boundaries are blurring as hybrid platforms combine mechanical and energy-based occlusion methods.
Product Type:
Cycle times vary from rapid clip consumption in high-volume general surgery to extended ultrasonic platform depreciation across cardiac service lines.
- Hemostatic Clips:Polymer or titanium constructs with 5-10 mm jaw apertures deliver immediate mechanical hemostasis across laparoscopic and open procedures. Demand concentrates in United States tertiary hospitals where GPO contracts standardize on specific clip applier configurations.
- Ultrasonic Ligators:Energy-based vessel sealing systems coagulate and transect tissue bundles through high-frequency mechanical vibration. German and Chinese teaching hospitals are displacing mechanical clips in thick-vessel bariatric and thoracic applications where thermal spread control is critical.
- Vessel Ligatures:Pre-tied suture configurations enable rapid ligation in confined anatomical spaces.
- Loop Ligators:Titanium-alloy designs target reusable instrument programs in European cost-conscious surgical departments.
- Others:Specialized clip variants for niche anatomical applications.
Hemostatic clips anchor the volume base while ultrasonic ligators gain share at the steepest rate.
Application:
Cost tier stratification separates premium energy-based platforms in cardiac and bariatric surgery from economy mechanical clips in routine outpatient procedures.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair generate the highest absolute clip consumption volumes. United States hospital networks specify 5 mm polymer clips for laparoscopic suites, with procurement committees prioritizing compatibility across multiple applier brands.
- Gynecology:Hysterectomy and ovarian procedures require secure tubal ligation and vascular control. Chinese provincial hospital systems are expanding minimally invasive gynecology suites, creating installed base demand for compatible ligation platforms.
- Urology:Nephrectomy and prostatectomy procedures drive specialized vessel sealing requirements.
- Thoracic Surgery:Lung resection and mediastinal procedures demand precision in fragile tissue environments.
- ENT Procedures:Tonsillectomy and sinus surgery utilize micro-scale ligation configurations.
General surgery commands the procurement volume while gynecology applications are climbing the fastest as minimally invasive suites expand in China and India.
End User:
Customer type determines pricing tolerance, with tertiary hospitals absorbing premium energy platform costs while outpatient facilities prioritize per-procedure economy.
- Hospitals:Tertiary academic medical centers in Germany, the United States, and China maintain diversified ligation inventories spanning mechanical clips, ultrasonic systems, and reusable loop ligators. Capital equipment budgets accommodate multi-platform strategies.
- Ambulatory Surgical Centers:Cost-per-procedure compression drives preference for single-use mechanical clips and limited reusable instrument programs. Texas and California ASC networks are unbundling device procurement from service contracts.
- Specialty Clinics:Focused urology and gynecology practices concentrate on procedure-specific clip configurations.
- Diagnostic Laboratories:Limited ligation device exposure confined to biopsy-related applications.
Hospitals anchor the volume base while ambulatory surgical centers are expanding most quickly as outpatient migration accelerates across United States and European healthcare systems.
Deployment:
Supply concentration in polymer molding and sterilization infrastructure shapes which deployment modes achieve cost competitiveness.
- Single-Use:Pre-sterilized polymer clips dominate hospital procurement protocols where reprocessing validation costs exceed disposable premiums. Jiangsu and Zhejiang manufacturing clusters are scaling domestic production for Chinese hospital supply security.
- Reusable:Titanium-alloy loop ligators and instrument systems target cost-conscious European teaching hospitals and United States ASC networks. FDA guidance on reprocessing validation documentation disadvantages mid-tier manufacturers.
- Disposable:Synonymous with single-use in most procurement contexts.
- Semi-Permanent:Bioresorbable clip designs with programmed degradation timelines.
Single-use deployment anchors the volume base while reusable programs are gaining share fastest among European cost-per-procedure optimization initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the procedural volume leader, while EU MDR harmonization and China's NMPA domestic manufacturing push reshape competitive access across three distinct regulatory zones.
United States
Tertiary hospital networks in Texas and California drive hemostatic clip consumption through high-volume laparoscopic suites. FDA guidance on reusable device reprocessing validation elevates compliance costs for mid-tier manufacturers. The Greater Boston and Midwest surgical corridors concentrate GPO contract negotiations and surgeon training infrastructure.
Germany
Teaching hospitals in Bavaria and North Rhine-Westphalia standardize on titanium-alloy loop ligators for cost-per-procedure optimization. EU MDR technical documentation requirements and F-Gas Regulation sterilization mandates compress product development timelines. The Baden-Württemberg medical technology cluster anchors reusable instrument manufacturing for European distribution.
China
Provincial hospital systems in Jiangsu and Zhejiang provinces scale domestic polymer clip production to reduce import dependency. NMPA regulatory streamlining and dual carbon goals accelerate local manufacturing qualification. The Yangtze River Delta manufacturing corridor concentrates molding capabilities and sterilization infrastructure for regional supply security.
Japan
PMDA-certified energy-based sealing platforms displace mechanical clips in thick-vessel cardiac procedures at Tokyo and Osaka academic centers. METI industrial policy supports precision manufacturing of ultrasonic ligator components. The Nagoya medical device corridor specializes in high-reliability titanium instrument fabrication.
India
CDSCO-registered hemostatic clips penetrate tier-2 city hospitals as minimally invasive surgery expands beyond metro centers. PLI scheme incentives attract contract manufacturing investment for polymer-based devices. The Maharashtra and Gujarat pharmaceutical-industrial corridors host sterilization validation facilities serving domestic and export markets.
Global Ligation Devices Market Competitive Landscape
Vertically integrated conglomerates and specialized instrument fabricators split the market across mechanical and energy-based modalities. The vendor base concentrates around three strategic archetypes: polymer molding specialists with captive raw material supply, energy-platform developers integrating ultrasonic and bipolar technologies, and reusable instrument manufacturers optimizing per-procedure economics. Dominant competitive moves include backward integration into medical-grade polymer feedstock and geographic expansion through Jiangsu-Zhejiang manufacturing partnerships.
Within the integrated-device tier, Medtronic and Ethicon represent scale-driven archetypes with broad GPO access and training infrastructure anchoring. B. Braun Melsungen AG exemplifies the European reusable-instrument specialization model. These three entities occupy positions spanning disposable polymer clips, energy-based sealing platforms, and titanium loop systems without exclusive segment concentration.
| Leading Market Players |
|---|
| Medtronic |
| Ethicon |
| Teleflex Incorporated |
| Olympus Corporation |
| Applied Medical Resources Corporation |
| CONMED Corporation |
| CooperSurgical |
| B. Braun Melsungen AG |
| Genicon |
| Others |
Supply & Pricing Matrix
Yangtze River Delta port congestion and container rate volatility feed directly into landed cost spreads between Jiangsu-manufactured polymer clips and European titanium loop systems, compressing margins for distributors serving mid-tier hospitals while amplifying price differentiation between premium energy platforms and economy mechanical alternatives.
Pricing Analysis
Price spreads between German-made titanium-alloy loop ligators and Jiangsu-produced polymer clips now exceed three-to-one at hospital procurement committees. Three-tier pricing structure across premium energy platforms, standard mechanical clips, and economy single-use alternatives anchors contract negotiations. Cost compression in the economy tier is intensifying because NMPA-qualified domestic manufacturers are undercutting import premiums. Ambulatory surgical centers exhibit the highest price sensitivity, while tertiary academic medical centers absorb premium platform costs for training and compatibility reasons.
Supply Chain Analysis
Medical-grade bioresorbable polymer feedstock draws from specialty chemical producers in Germany, the United States, and Japan, with titanium-alloy bar stock concentrating in Japanese and Austrian metallurgical facilities. Raw material dependencies span medical-grade polycarbonate, titanium Ti-6Al-4V ELI, and sterilization-grade ethylene oxide. Single-source vulnerability in bioresorbable polymer catalyst supply creates disruption risk for next-generation clip programs. Distribution runs through hospital group purchasing organizations in the United States and direct provincial procurement systems in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a regulatory compliance cycle as EU MDR and FDA 510(k) harmonization stabilizes, positioning procurement volume recovery as the dominant cyclical driver through the analysis window.
For Market Incumbents: Build regulatory certification moats by accelerating dual-market FDA-EU MDR submissions ahead of smaller competitors. Deepen backward integration into medical-grade polymer feedstock to buffer raw material volatility. Anchor hospital system contracts through bundled training and maintenance service unbundling to defend against ultrasonic platform substitution threats. For New Entrants and Emerging Players: Pursue ambulatory surgical center channel expansion in Texas and California where GPO panel consolidation has left mid-tier pricing gaps. Target reusable titanium loop ligator programs in European teaching hospitals seeking per-procedure cost compression. Lead with ethylene oxide sterilization validation as EU F-Gas Regulation phase-down creates first-mover positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors polymer molding specialists with captive Jiangsu-Zhejiang manufacturing infrastructure over pure energy-platform developers facing ultrasonic substitution saturation. Long-term viability rests on dual-market regulatory access and sterilization alternative readiness. Watch NMPA domestic qualification timelines as the inflection signal for Chinese market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Harmonization | Streamlines dual-market access for ISO 13485-certified polymer clip manufacturers. |
| Jiangsu-Zhejiang Manufacturing Partnership | Secures domestic supply chains for NMPA-registered devices serving Chinese provincial hospitals. |
| Ethylene Oxide Sterilization Validation | Positions manufacturers ahead of EU F-Gas Regulation phase-down mandates. |
| Ambulatory Surgical Center Channel Expansion | Captures cost-conscious outpatient migration in Texas and California networks. |
| Surgeon Training Infrastructure Investment | Differentiates energy-platform vendors where credentialing programs extend sales cycles. |
Research Methodology
Operator-level perspectives from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and sterile processing department heads anchored the qualitative base. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and ISO 13485 certification records. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation produced converged market estimates.
Scenario-bracketing around regulatory approval timelines and sterilization infrastructure investment cycles framed the analytical approach across the projection horizon. Segmentation dimensions spanned product type, application specialty, end-user facility tier, deployment mode, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and per-procedure consumption coefficients. Forecast inputs incorporated laparoscopic suite construction pipelines and NMPA domestic manufacturing qualification trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by ultrasonic platform developers or Jiangsu-based contract manufacturers would shift outcomes. Cross-checking against hospital capital equipment budget disclosures and GPO contract award announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Transcatheter Pacing System Market
Medical Devices
Intravaginal Device Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Heart Closure Devices Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
Wearable Bioelectronic Skin Patches Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Acne Treatment Devices Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Transradial Access Devices Market