
 Anti-Decubitus Dynamic Mattress Market | 2026-2036
Anti-Decubitus Dynamic Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Decubitus Dynamic Mattress Market Outlook
ISO 13485 certification is reorganizing competitive standing in the anti-decubitus dynamic mattress space, filtering out suppliers lacking quality management systems for medical devices. LINET Group SE leverages its European manufacturing base to sustain dominant positions in alternating pressure systems across acute care settings. Hill-Rom Holdings Inc. anchors North American demand through extensive direct sales infrastructure and clinical training programs. Arjo AB differentiates via integrated wound care portfolios that bundle dynamic mattresses with patient handling equipment.
An anti-decubitus dynamic mattress is a powered or non-powered support surface engineered with cell-on-cell air bladders, viscoelastic foam layers, or thermoregulating gel composites to redistribute pressure and shear forces across the body, primarily preventing Stage I-IV pressure injuries in immobilized patients. Alternating pressure systems dominate hospital procurement budgets due to proven clinical outcomes in intensive care units, while hybrid systems combining low air loss with active pressure redistribution represent the fastest-growing technology segment as facilities seek dual-function capital efficiency. Foam mattresses retain volume leadership in nursing homes where reimbursement constraints favor lower acquisition costs over advanced feature sets.
The FDA's 510(k) clearance pathway and the EU Medical Device Regulation (MDR) impose divergent clinical evidence requirements that fragment product launch timelines between the United States and European markets. The Joint Commission's National Patient Safety Goals and CMS hospital-acquired condition reduction programs directly tie reimbursement penalties to pressure injury incidence, forcing facilities to upgrade surface technologies ahead of standard depreciation cycles. Stakeholders must monitor how evolving post-market surveillance obligations in both jurisdictions reshape warranty terms and service revenue models.
Market Dynamics
CMS hospital-acquired condition penalty programs are compressing mattress replacement cycles across US acute care facilities, forcing capital equipment decisions ahead of standard depreciation schedules.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter post-market surveillance obligations for powered surface technologies are filtering out uncertified suppliers and elevating demand for ISO 13485-compliant manufacturers in European acute care procurement.
- Long-term care facilities:North American nursing homes are expanding alternating pressure system procurement as state-level pressure injury prevention protocols tighten reimbursement eligibility for facility quality ratings.
- Alternating pressure technology:Proven clinical outcomes in intensive care units are driving hospital procurement budgets toward active pressure redistribution systems over static foam alternatives.
Market Restraints
- Medical-grade polymer costs:Volatility in thermoplastic polyurethane and silicone bladder materials is squeezing gross margins for air-cell system manufacturers.
- Supply concentration:European pump motor and solenoid valve production clusters in Germany and Italy create single-source vulnerability for North American assemblers.
- FDA 510(k) pathway friction:Divergent clinical evidence requirements versus EU MDR are fragmenting product launch timelines and duplicating regulatory spend.
Strategic Opportunities
- Home care segment:Aging-in-place policies in Japan and Germany are opening reimbursement pathways for rental-based dynamic mattress services outside institutional settings.
- Hybrid system convergence:Integration of low air loss thermoregulation with active pressure redistribution is capturing dual-function capital efficiency demand in budget-constrained community hospitals.
- ISO 13485 certification gap:Mid-tier foam converters without quality management systems face exclusion from hospital group purchasing organization vendor panels.
Industry Challenges
- Biomedical technician shortage:Complex alternating pressure system maintenance is outpacing available trained service personnel in rural health systems.
- Legacy EMR integration:Smart mattress sensor data streams require costly HL7 FHIR interface development to feed into existing electronic health record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Decubitus Dynamic Mattress Market |
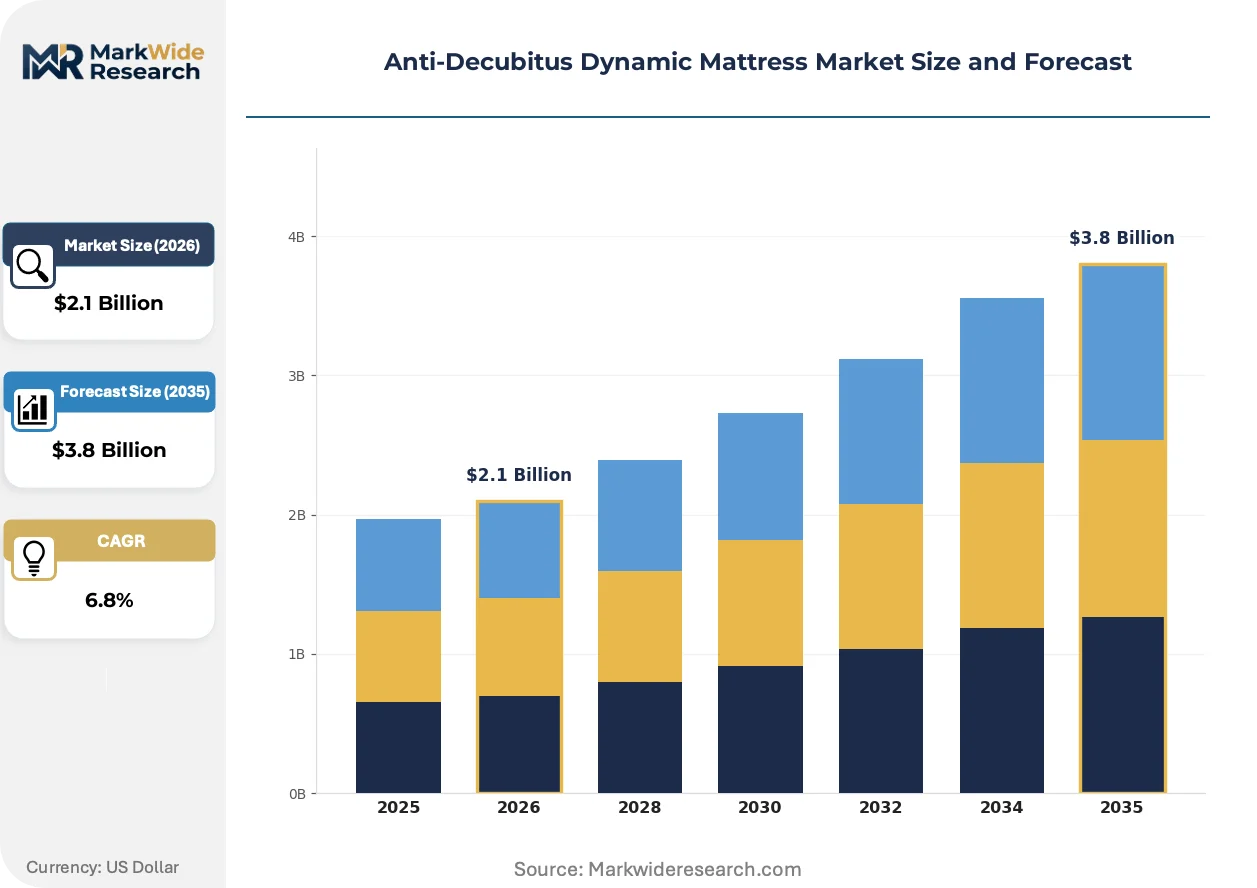
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Mattresses, Foam Mattresses, Gel Mattresses, Water-Inflated Mattresses End User: Hospitals, Nursing Homes, Homecare Providers, Rehabilitation Centers Technology: Static Mattresses, Alternating Pressure Systems, Low Air Loss Systems, Hybrid Systems Distribution Channel: Direct Sales, Online Retail, Medical Supply Stores, Distributors |
| Companies Covered | Invacare Corporation, Drive DeVilbiss Healthcare, LINET Group SE, Apex Medical Corp, Talley Group Ltd, Stryker Corporation, Arjo AB, Malvestio Spa, Hill-Rom Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Decubitus Dynamic Mattress Market Strategic Shifts
Sensor-embedded dynamic surfaces are rewiring competitive advantage around predictive analytics capabilities rather than hardware durability alone.
Microclimate management technology is decomposing the traditional separation between pressure redistribution and moisture control functions. Long-term care operators in Germany and the Netherlands are adopting thermoregulating gel composite layers at twice the pace of standard alternating air systems. This convergence is decomposing the standalone low air loss category into an integrated feature set within hybrid platforms.
The FDA's updated medical device classification for powered surface technologies is tightening predicate device equivalence standards for 510(k) submissions. Manufacturers now face expanded clinical data requirements for software-controlled pressure algorithms. US acute care procurement teams are responding by pre-qualifying suppliers with established FDA quality system inspection histories.
Hospital group purchasing organizations are consolidating vendor panels around full-service contracts bundling equipment, preventive maintenance, and outcome reporting. Independent durable medical equipment distributors are losing access to integrated delivery networks as direct manufacturer relationships capture service revenue streams. This concentration is most visible in the southeastern United States where health system mergers have reduced qualified supplier pools by half.
Anti-Decubitus Dynamic Mattress Market Segmentation
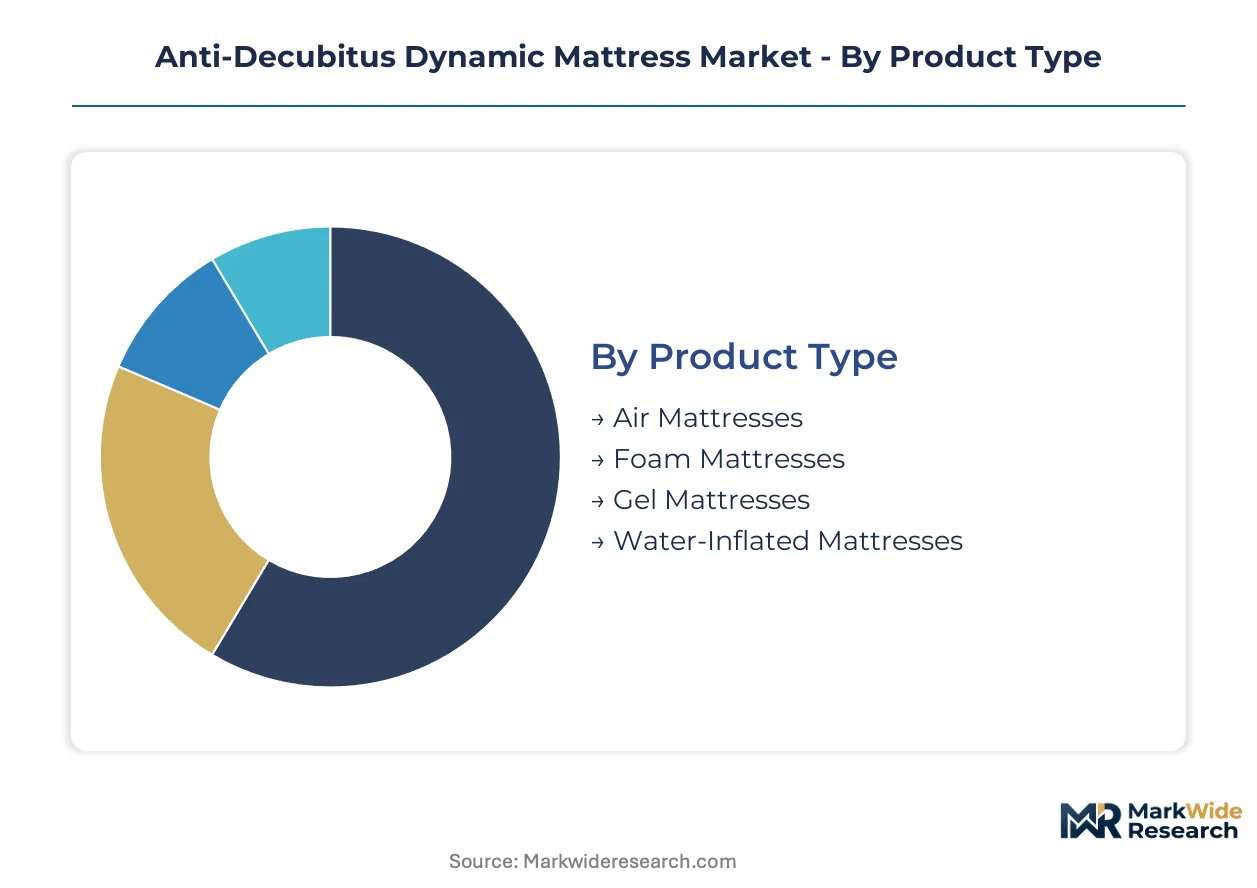
Technology differentiation and end-user procurement authority fragment the anti-decubitus dynamic mattress market into four distinct category axes. Each segmentation layer reveals divergent margin structures, regulatory exposure, and replacement cycle dynamics that reshape supplier competitive positioning.
Product Type:
Margin pools concentrate in air-cell systems where polymer bladder engineering and pump integration create defendable technical moats, while foam platforms compete on manufacturing scale and raw material sourcing efficiency.
- Air Mattresses:Cell-on-cell air bladder architectures with alternating pressure algorithms dominate ICU procurement budgets due to proven Stage III-IV pressure injury prevention outcomes. Demand concentrates in United States acute care facilities where CMS hospital-acquired condition penalties compress replacement cycles ahead of standard depreciation schedules.
- Foam Mattresses:Viscoelastic and high-density polyurethane constructions anchor nursing home volume procurement where reimbursement constraints favor lower acquisition costs over active pressure redistribution features. German long-term care operators are expanding thermoregulating gel-foam hybrid orders at twice the pace of standard air systems.
- Gel Mattresses:Thermoregulating composite layers redistribute shear forces through silicone or thermoplastic elastomer matrices for burn unit and bariatric applications.
- Water-Inflated Mattresses:Hydrostatic pressure distribution systems retain niche adoption in Japan's home care segment where aging-in-place policies subsidize rental-based surface technologies.
Air mattresses hold installed capacity. Foam mattresses is rotating up the share rankings.
End User:
Procurement authority and reimbursement pathways create four distinct customer tiers with diverging contract structures and service intensity requirements.
- Hospitals:Integrated delivery networks and group purchasing organizations consolidate vendor panels around full-service contracts bundling equipment, preventive maintenance, and outcome reporting. United States health system mergers in the southeastern states have reduced qualified supplier pools by half.
- Nursing Homes:State-level quality rating systems tie reimbursement eligibility to pressure injury incidence metrics, forcing alternating pressure system upgrades ahead of capital equipment depreciation timelines.
- Homecare Providers:Rental-based service models are expanding in Germany and Japan where aging-in-place policies open reimbursement pathways outside institutional settings.
- Rehabilitation Centers:Post-acute facilities prioritize hybrid systems combining pressure redistribution with patient handling equipment for bariatric and spinal cord injury protocols.
Hospitals command pricing power through consolidated procurement. Homecare providers is climbing the fastest as a demand channel.
Technology:
Active versus passive pressure management architectures separate premium pricing tiers from commodity replacement markets.
- Alternating Pressure Systems:Software-controlled air cell inflation-deflation cycles redistribute pressure across 5-10 minute intervals, capturing the majority of United States ICU procurement spend due to Joint Commission National Patient Safety Goals compliance requirements.
- Hybrid Systems:Integration of low air loss thermoregulation with active pressure redistribution captures dual-function capital efficiency demand in budget-constrained community hospitals, representing the segment gaining share fastest.
- Static Mattresses:Non-powered foam or gel constructions serve cost-sensitive long-term care environments with minimal biomedical technician support requirements.
- Low Air Loss Systems:Microclimate management through forced air circulation is decomposing into an integrated feature set within hybrid platforms rather than standalone category.
Alternating pressure systems hold installed base dominance. Hybrid systems is rotating up the share rankings.
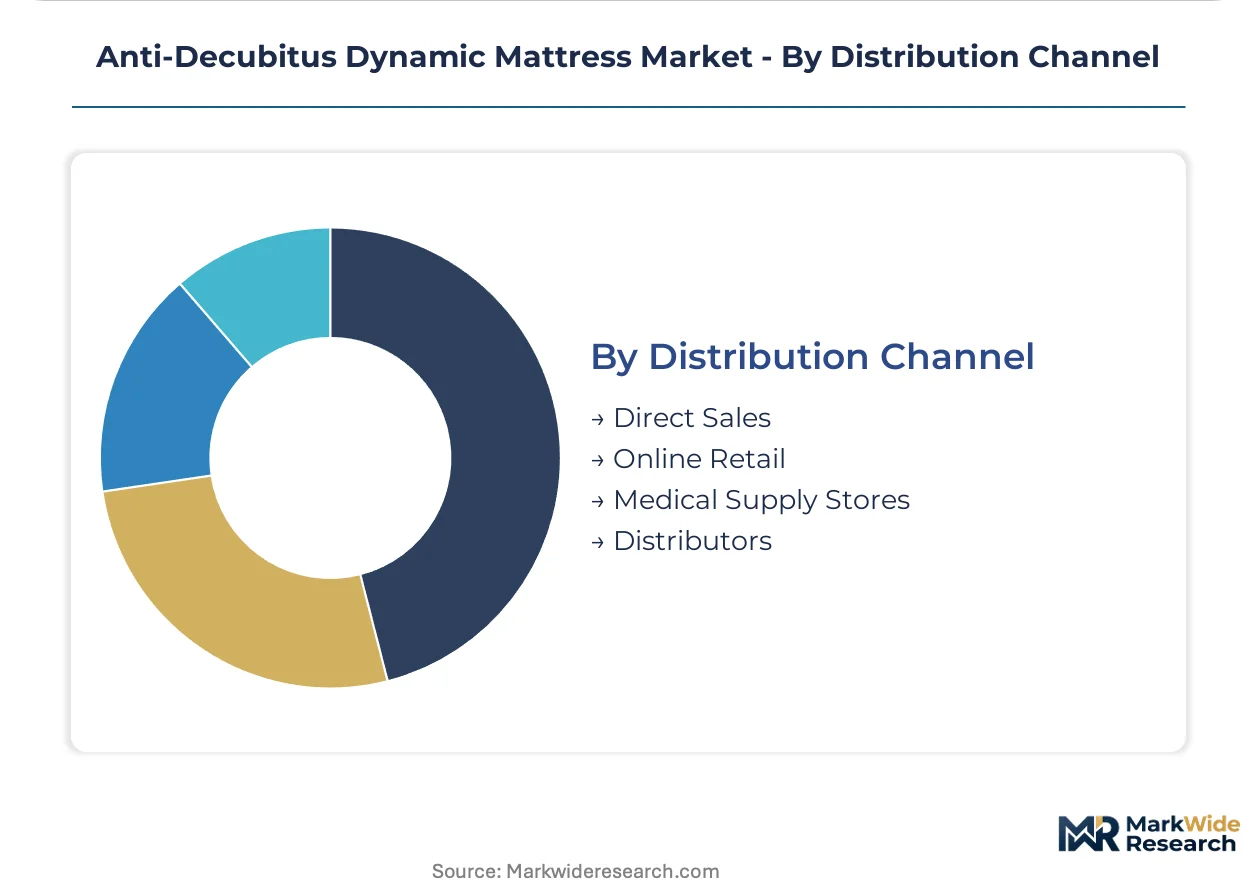
Distribution Channel:
Channel structure determines service revenue capture and warranty liability allocation between manufacturers and intermediaries.
- Direct Sales:Manufacturer field organizations anchor United States acute care procurement through clinical training programs and preventive maintenance contracts, capturing service revenue streams that independent distributors are losing.
- Distributors:Regional medical equipment wholesalers retain relevance in rural health systems where biomedical technician shortages complicate direct manufacturer service coverage.
- Online Retail:E-commerce platforms are expanding in home care segments where patient or family-directed purchases bypass institutional procurement protocols.
- Medical Supply Stores:Brick-and-mortar durable medical equipment retailers serve cash-pay customers and small physician practice orders outside group purchasing organization networks.
Direct sales holds channel margin concentration. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement penalties for hospital-acquired conditions are compressing mattress replacement cycles in acute care facilities worldwide. Germany's aging-in-place policies and Japan's long-term care insurance reforms are opening non-institutional procurement channels. The EU Medical Device Regulation is filtering supplier pools across European acute care networks.
United States
CMS hospital-acquired condition reduction programs tie reimbursement penalties directly to pressure injury incidence metrics. The FDA's updated 510(k) clearance pathway for powered surface technologies is tightening predicate device equivalence standards. Health system mergers across the southeastern states have consolidated vendor panels and reduced qualified supplier pools by half.
Germany
Long-term care insurance reforms subsidize rental-based dynamic mattress services for aging-in-place patients. The EU Medical Device Regulation imposes stricter post-market surveillance obligations on powered surface manufacturers. Manufacturing clusters in North Rhine-Westphalia and Bavaria anchor European pump motor and solenoid valve production for air-cell systems.
Japan
The long-term care insurance system reimburses home-based pressure injury prevention equipment for rapidly aging rural populations. METI standards for medical device software validation affect product registration timelines for algorithm-controlled pressure systems. Industrial concentration in the Kanto region around Tokyo supports domestic assembly of hybrid low air loss platforms.
United Kingdom
NHS England's pressure ulcer reduction framework mandates alternating pressure system procurement in acute trusts meeting quality targets. MHRA conformity assessment procedures under retained EU MDR provisions filter supplier qualification for hospital group purchasing organizations. Manufacturing activity in the Midlands region supplies foam core components to European mattress assemblers.
China
NMPA medical device classification rules for powered support surfaces are harmonizing with international standards to accelerate import substitution. Provincial health procurement platforms in Jiangsu and Zhejiang are consolidating demand for cost-competitive alternating pressure systems. The Yangtze River Delta manufacturing base is expanding domestic production of thermoplastic polyurethane bladder materials.
Anti-Decubitus Dynamic Mattress Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory certification dimensions. The supplier base organizes into three tiers: multinational medical technology conglomerates with full-service contracts, mid-cap European manufacturers with ISO 13485 quality systems, and regional foam converters competing on acquisition cost. Strategic moves concentrate on backward integration into polymer bladder production and direct sales infrastructure buildout to capture service revenue from group purchasing organizations.
Within the premium-tier vector, LINET Group SE and Hill-Rom Holdings Inc. exemplify manufacturers anchoring market position through clinical training programs and preventive maintenance contracts. Arjo AB occupies a position bundling dynamic mattresses with integrated wound care portfolios. Stryker Corporation represents the diversified medical technology archetype leveraging acute care procurement relationships across multiple capital equipment categories.
| Leading Market Players |
|---|
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| LINET Group SE |
| Apex Medical Corp |
| Talley Group Ltd |
| Stryker Corporation |
| Arjo AB |
| Malvestio Spa |
| Hill-Rom Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day pump motor lead times from German and Italian suppliers anchor pricing power for North American assemblers, compressing margin buffers for air-cell system manufacturers while elevating premiums for ISO 13485-certified European producers with captive component inventories.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers, with FDA 510(k) clearance and ISO 13485 quality systems commanding substantial premiums over uncertified foam converters. Three-tier pricing structure across premium, standard, and economy levels reflects this regulatory stratification, with hospital group purchasing organizations consolidating contracts around full-service bundles. Cost compression in the standard tier is intensifying because medical-grade thermoplastic polyurethane bladder materials face commodity volatility. Nursing homes exhibit highest price sensitivity due to reimbursement constraints, while United States acute care facilities prioritize clinical outcome guarantees over acquisition cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate for foam core components sourced from United Kingdom Midlands manufacturers, whereas strategic stockpiling of pump motors and solenoid valves from Germany and Italy mitigates single-source vulnerability for North American assemblers. Raw material dependencies center on thermoplastic polyurethane, silicone elastomers, and high-density polyurethane foam. Distribution runs through direct manufacturer field organizations capturing service revenue from consolidated hospital procurement panels, with independent distributors retreating to rural health systems where biomedical technician shortages persist.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through health system mergers across the southeastern United States, reducing qualified supplier pools by half and forcing vendors toward full-service contract structures.
For Market Incumbents: Fortify positions through backward integration into polymer bladder production and preventive maintenance infrastructure buildout. LINET Group SE and Hill-Rom Holdings Inc. demonstrate how clinical training programs defend against mid-tier foam converters lacking ISO 13485 certification. Captive supply of thermoplastic polyurethane materials insulates margin structures from commodity volatility. For New Entrants and Emerging Players: Anchor in Japan's home care rental segment and Germany's aging-in-place reimbursement pathways, where institutional procurement consolidation has not yet penetrated. These geographies offer the most penetrable demand channels outside group purchasing organization networks. A software-as-a-service pricing model for sensor-embedded predictive analytics bypasses capital equipment procurement friction. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory barriers filter uncertified suppliers while service revenue streams deepen customer captivity. Target mid-cap European manufacturers with established ISO 13485 quality systems and underdeveloped direct sales infrastructure. The signal to watch is FDA quality system inspection history depth as a predictor of 510(k) clearance velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Filters uncertified competitors from hospital group purchasing organization vendor panels. |
| Backward Integration into Polymer Production | Captures margin pools concentrated in thermoplastic polyurethane bladder engineering. |
| Direct Sales Infrastructure Buildout | Captures service revenue streams that independent distributors are losing to manufacturer relationships. |
| Sensor-Embedded Platform Development | Rewires competitive advantage around predictive analytics capabilities beyond hardware durability. |
| Home Care Rental Service Model | Opens reimbursement pathways in Japan and Germany outside institutional procurement consolidation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across hospital procurement committees, biomedical engineering directors, nursing home facility administrators, group purchasing organization contract managers, and durable medical equipment distributors. Secondary validation drew from FDA 510(k) clearance databases, EU Medical Device Regulation technical documentation, CMS hospital-acquired condition penalty program filings, and hospital procurement contract repositories. Bottom-up unit economics triangulated against top-down reimbursement flow analysis.
Across the analysis window, projections integrate technology segment substitution dynamics, regulatory pathway velocity differentials between FDA and EU MDR frameworks, and replacement cycle compression from penalty program expansion. Segmentation dimensions span product architecture, end-user procurement authority, pressure redistribution technology, and distribution channel service intensity. CAGRs derive from fitted growth curves against historical replacement cycle data and reimbursement policy trajectory.
Underlying assumptions cover regulatory pathway stability and polymer commodity price bands, with deviation risk concentrated in FDA 510(k) predicate device equivalence standard tightening and biomedical technician availability constraints. Revision becomes warranted when health system merger velocity crosses thresholds that consolidate vendor panels beyond current trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Microneedling Cartridges Market
Medical Devices
Chile Artificial Organs and Bionic Implants Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Memory Implants Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Wearable Bioelectronic Skin Patches Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Spine Surgery Robots Market
Medical Devices
Intubation Tubes Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market