
 Accelerometers Medical Sensors Market | 2026-2036
Accelerometers Medical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Accelerometers Medical Sensors Market Intelligence
Buyer concentration in the accelerometers medical sensors space is broadening as hospital procurement groups fragment their vendor portfolios while home care agencies aggregate purchasing power. STMicroelectronics leverages its MEMS foundry scale to dominate supply contracts for wearable diagnostics. Bosch Sensortec specializes in ultra-low-power designs that sustain competitive positioning in continuous patient monitoring devices. Texas Instruments anchors its presence through integrated signal-conditioning chipsets that reduce bill-of-materials complexity for original equipment manufacturers.
Accelerometers medical sensors are electromechanical transducers that convert mechanical acceleration into electrical signals, typically fabricated through silicon micromachining processes with capacitive or piezoelectric sensing elements, and serve to quantify motion, vibration, and orientation in clinical and remote health settings. MEMS sensors occupy the largest volume share due to their compatibility with semiconductor batch fabrication, while digital sensors capture expanding margin pools through embedded calibration and direct microcontroller interfacing that eliminates analog front-end components. Patient monitoring applications lead absolute demand as telemetry systems embed accelerometry for fall detection and activity quantification, whereas motion analysis represents the fastest-growing segment driven by orthopedic rehabilitation protocols and sports medicine clinics.
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards govern accelerometer performance claims for diagnostic and monitoring indications, compelling manufacturers to maintain clinical validation dossiers that substantiate measurement accuracy across patient populations. ISO 13485 quality management systems and IEC 60601-1 electrical safety standards further constrain market access for suppliers lacking certified production infrastructure. Stakeholders must monitor evolving cybersecurity guidance from FDA and notified bodies regarding wireless accelerometer data transmission in connected health ecosystems.
Market Dynamics
MEMS fabrication economics and FDA clearance timelines are compressing product development cycles while fragmenting buyer power across hospital procurement groups and home care aggregators.
Growth Catalysts
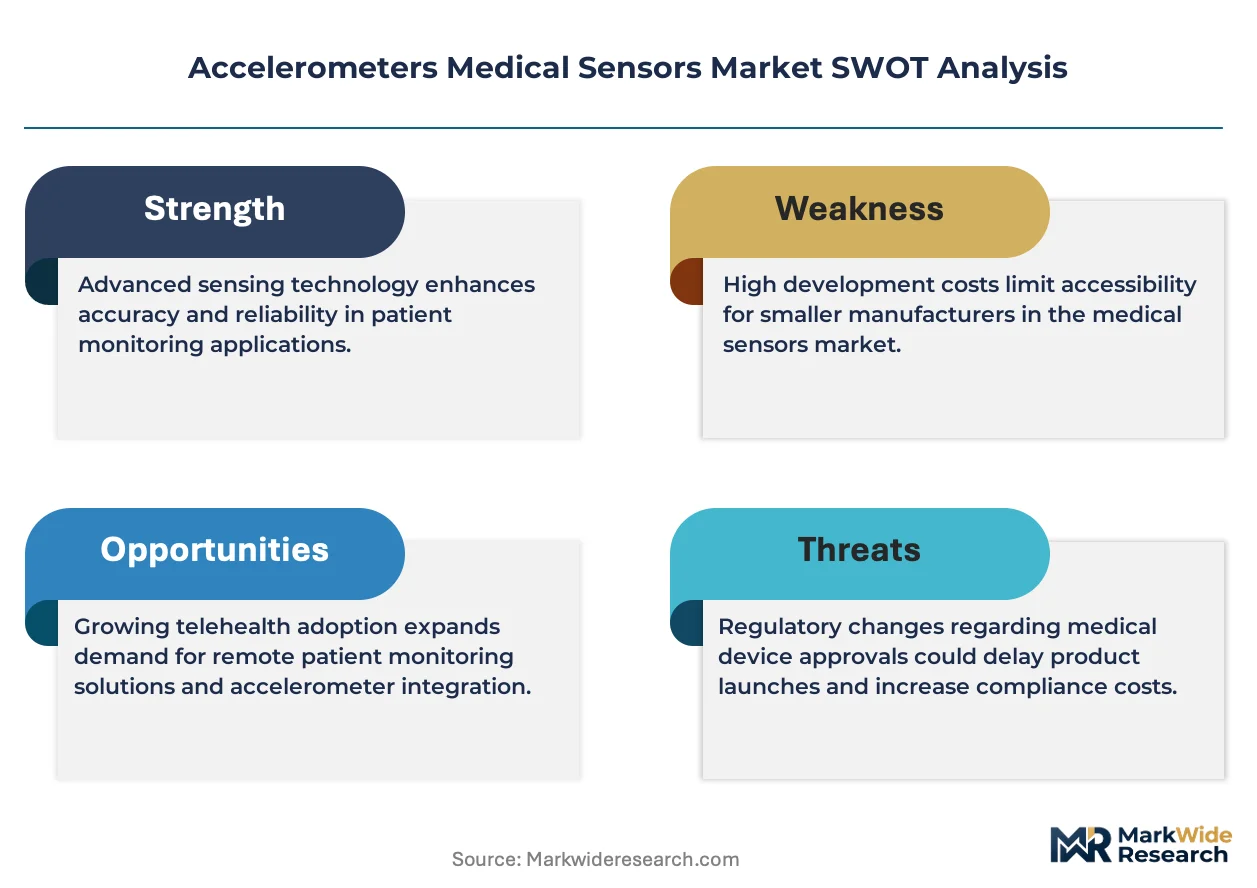
- FDA 510(k) pathway streamlining:Accelerated premarket notification reviews for predicate-device accelerometer claims are shortening time-to-revenue for wearable diagnostic manufacturers targeting fall detection indications.
- Home care telemetry expansion:Post-acute monitoring contracts are embedding accelerometry into remote patient monitoring bundles, pulling sensor demand beyond hospital walls.
- Silicon micromachining scale:Semiconductor foundry capacity dedicated to MEMS inertial sensors is lowering unit economics for capacitive sensing element production.
Market Restraints
- EU MDR technical documentation burden:Clinical validation dossier requirements for active implantable accessories are extending certification timelines and freezing smaller suppliers from European market access.
- Foundry concentration in Taiwan:MEMS wafer fabrication capacity bottlenecks create single-source vulnerability for accelerometer die supply during geopolitical disruption.
- Capacitive drift limitations:Temperature sensitivity in silicon micromachined structures constrains measurement accuracy across patient body temperature variation, limiting diagnostic-grade applications.
Strategic Opportunities
- Japan's aging-in-place infrastructure:METI-funded smart home pilot programs are creating dedicated procurement channels for fall prediction accelerometers in municipal elderly care contracts.
- AI-edge convergence:Embedded neural inference engines on accelerometer companion chips are enabling on-device activity classification without cloud latency, opening sports medicine clinic workflows.
- Direct-to-home distribution:Bypassing durable medical equipment intermediaries through e-commerce platforms is capturing margin from physical therapy patient self-pay segments.
Industry Challenges
- Biocompatibility certification complexity:ISO 10993 testing protocols for skin-contact wearable adhesives containing accelerometer modules are extending product launch schedules.
- Signal processing talent scarcity:Embedded firmware engineers capable of fusing accelerometer data with gyroscope and magnetometer streams command premium compensation, constraining OEM development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Accelerometers Medical Sensors Market |
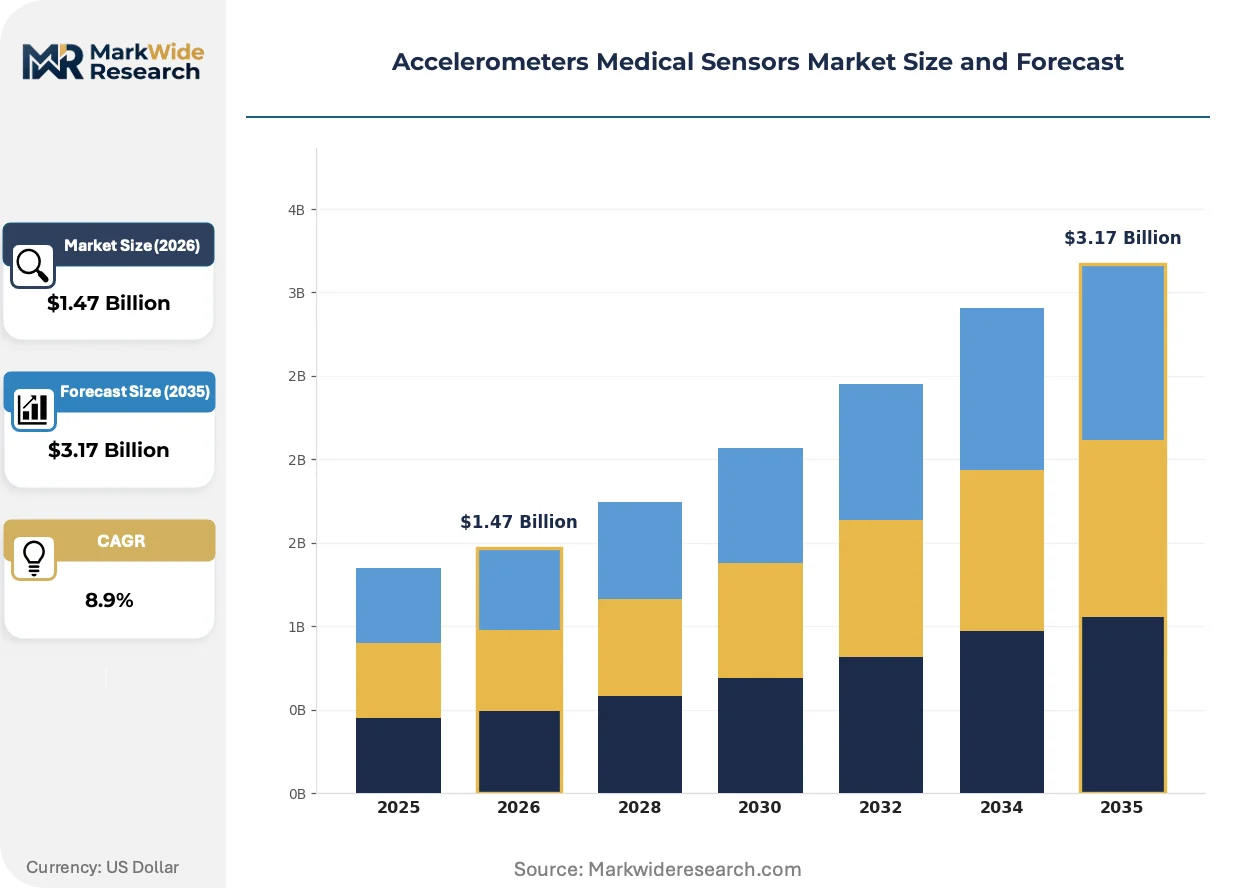
| Market Size in 2026 | $1.47 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Sensors, Digital Sensors, MEMS Sensors, 3D Sensors End User: Hospitals, Clinics, Research Labs, Home Care Application: Patient Monitoring, Rehabilitation, Diagnostics, Motion Analysis Technology: Piezoelectric, Capacitive, Optical, Thermal |
| Companies Covered | Analog Devices, Inc., STMicroelectronics, Fitbit Inc., ResMed, Garmin, Bosch Sensortec, NXP Semiconductors, Texas Instruments, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Accelerometers Medical Sensors Market Strategic Shifts & Innovations
Wireless data transmission architectures and embedded calibration algorithms are displacing analog front-end designs while tightening cybersecurity scrutiny from notified bodies.
Capacitive MEMS accelerometers with integrated temperature compensation is electrifying the transition from external signal conditioning to single-chip solutions. Wearable original equipment manufacturers in Germany and the United States are adopting these designs within eighteen-month product refresh cycles. The elimination of discrete analog components is compressing bill-of-materials counts and shifting value capture toward firmware-integrated suppliers.
EU MDR Annex I general safety and performance requirements are mandating clinical evidence for accelerometer-based diagnostic claims that previously relied on predicate equivalence. Manufacturers must now generate prospective validation data across intended patient populations before CE marking. Orthopedic rehabilitation device segments are responding by embedding accelerometry into broader motion capture systems rather than standalone sensors.
Hospital procurement groups are fragmenting vendor portfolios to reduce concentration risk while home care agencies aggregate purchasing power through group purchasing organizations. The durable medical equipment channel faces disintermediation as direct manufacturer relationships with telehealth platforms capture telemetry contract value. This restructuring is most visible in United States Medicare Advantage plans bundling remote monitoring services.
Accelerometers Medical Sensors Market Segmentation
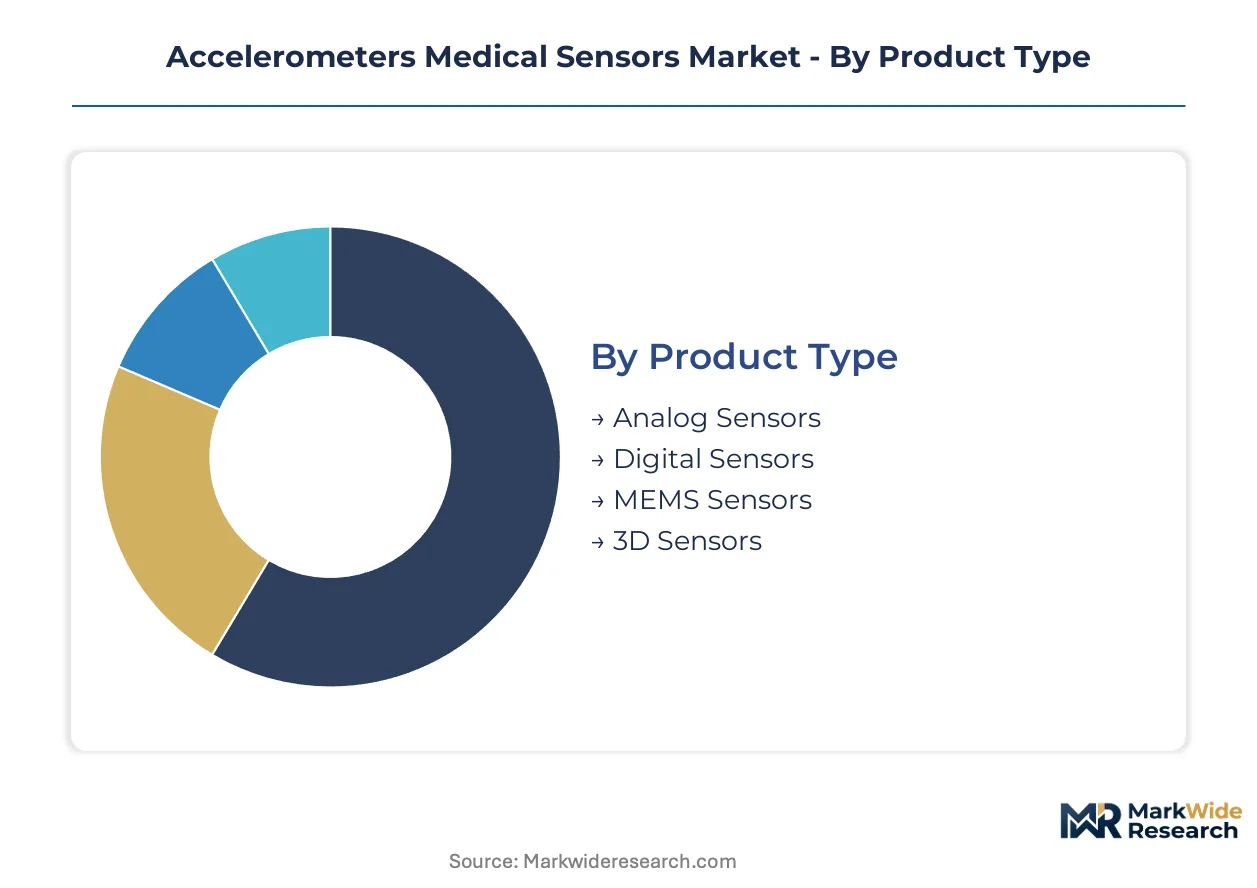
Accelerometer medical sensor procurement splits across technical specifications, care settings, clinical applications, and underlying transduction physics. Buyer priorities diverge sharply between hospital capital equipment committees seeking diagnostic-grade precision and home care aggregators optimizing for connectivity and power efficiency.
Product Type:
Hospital procurement groups weight signal fidelity and integration complexity against unit economics when selecting between analog and digital architectures.
- MEMS Sensors:Silicon micromachined structures fabricated through semiconductor batch processes deliver capacitive or piezoelectric transduction in millimeter-scale packages. Volume concentrates in wearable patient monitoring platforms across Germany and the United States where FDA 510(k) clearance pathways favor established MEMS form factors.
- Digital Sensors:Embedded calibration algorithms and direct microcontroller interfacing eliminate analog front-end components while reducing bill-of-materials complexity. Demand is climbing fastest in continuous monitoring devices where on-chip signal processing enables wireless telemetry without external conditioning circuitry.
- Analog Sensors:Raw voltage output requiring external amplification suits legacy motion analysis systems in orthopedic rehabilitation clinics.
- 3D Sensors:Tri-axial measurement capability supports spatial orientation tracking in fall detection wearables.
Volume sits with MEMS Sensors; growth tilts toward Digital Sensors.
End User:
Care setting determines regulatory pathway, reimbursement code, and device form factor requirements.
- Hospitals:Capital equipment procurement for surgical recovery and ICU step-down units drives demand for diagnostic-grade precision with IEC 60601-1 electrical safety certification. United States hospital networks are consolidating vendor contracts for motion analysis systems while fragmenting accelerometer sourcing to reduce concentration risk.
- Home Care:Remote patient monitoring bundles and aging-in-place infrastructure create procurement channels through Medicare Advantage plans and municipal elderly care contracts. Japan's METI-funded smart home pilot programs are accelerating dedicated procurement for fall prediction accelerometers.
- Clinics:Sports medicine and outpatient rehabilitation facilities prioritize portable motion capture systems.
- Research Labs:Clinical validation studies and algorithm development require configurable sensor platforms with raw data access.
Procurement volume clusters in Hospitals; expansion is steepest in Home Care.
Application:
Clinical indication shapes sensor performance specifications and regulatory evidence requirements.
- Patient Monitoring:Telemetry systems embed accelerometry for fall detection, activity quantification, and bed-exit alerts in acute and post-acute settings. Demand concentrates in United States Medicare Advantage remote monitoring contracts where reimbursement codes now cover continuous accelerometer-based surveillance.
- Motion Analysis:Orthopedic rehabilitation protocols and sports medicine clinics drive requirements for high-sample-rate capture of gait and range-of-motion metrics. EU MDR Annex I clinical evidence mandates are pushing manufacturers toward integrated motion capture systems rather than standalone sensors.
- Rehabilitation:Post-surgical recovery tracking in outpatient and home settings requires durable, patient-worn form factors.
- Diagnostics:Disease-specific movement disorder characterization demands laboratory-grade measurement stability.
Patient Monitoring commands absolute volume; Motion Analysis is expanding most quickly.
Technology:
Transduction physics determines temperature stability, power consumption, and compatibility with semiconductor integration.
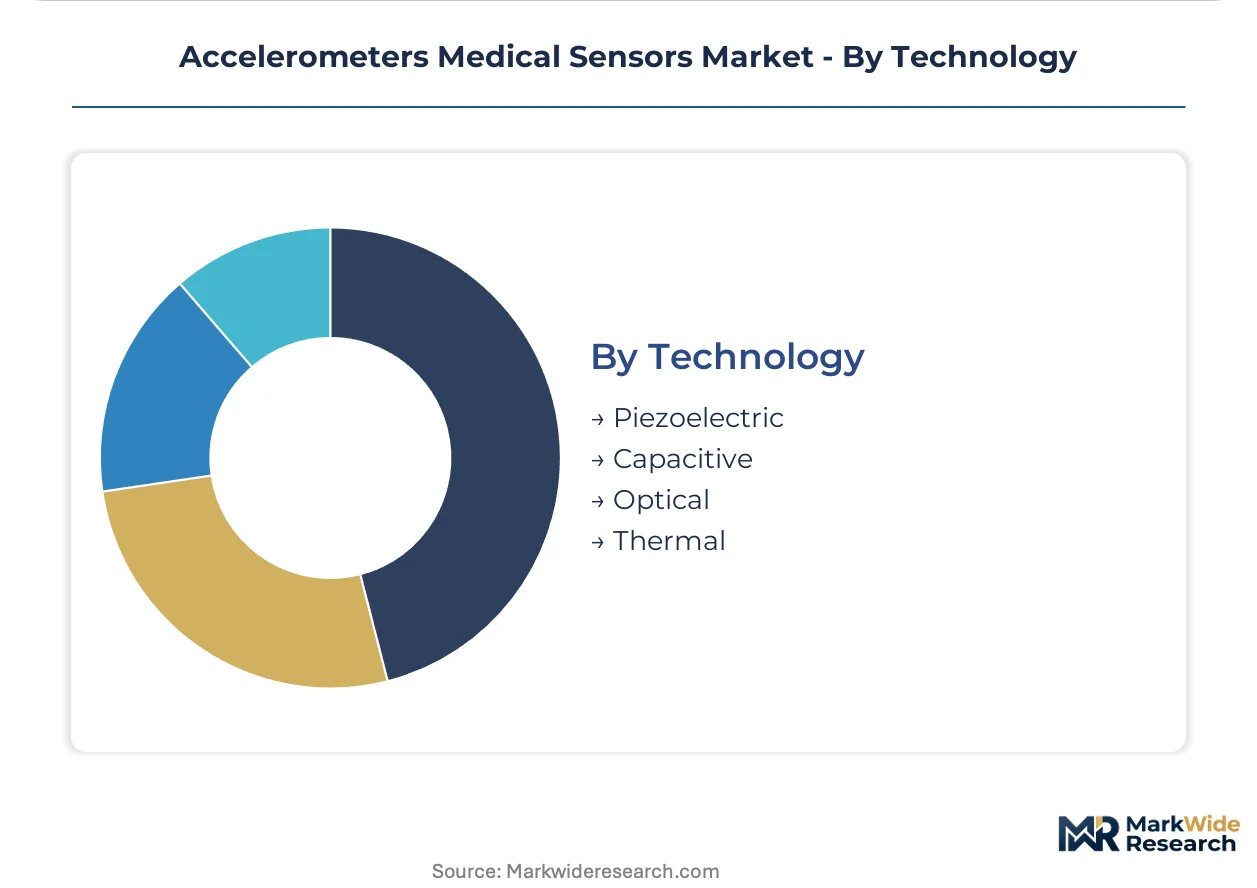
- Capacitive:Silicon micromachined plates with variable-gap electrodes dominate MEMS fabrication due to foundry compatibility and batch economics. Taiwan-based wafer capacity constraints create supply vulnerability for accelerometer die production during geopolitical disruption.
- Piezoelectric:Crystalline materials generating charge under mechanical stress offer wide dynamic range for high-impact motion capture in sports medicine applications.
- Optical:Interferometric or fiber-Bragg-grating approaches serve niche laboratory calibration requirements.
- Thermal:Convection-based sensing provides shock tolerance for implantable or ruggedized wearable designs.
Capacitive technology anchors production volume; Piezoelectric designs are gaining share fastest in high-performance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan anchors accelerometer die supply for medical sensor assembly, yet end-use demand clusters in healthcare systems with established reimbursement pathways for remote monitoring and post-surgical rehabilitation.
United States
Medicare Advantage plans bundle accelerometer-based remote patient monitoring services, creating procurement pull through durable medical equipment channels. FDA 510(k) premarket notification pathways favor predicate-device claims for fall detection wearables. Hospital procurement groups in Texas and California fragment vendor contracts to reduce concentration risk while consolidating motion analysis system purchases.
Germany
Orthopedic rehabilitation clinics drive demand for high-sample-rate motion capture systems integrated with accelerometry. EU MDR technical documentation requirements compel manufacturers to generate prospective clinical validation data before CE marking. Industrial sensor development concentrates in Baden-Württemberg, where MEMS fabrication expertise feeds into medical device supply chains.
Japan
METI-funded smart home pilot programs create municipal procurement channels for fall prediction accelerometers in aging-in-place infrastructure. PMDA consultation procedures guide manufacturers through premarket submission requirements for diagnostic-grade devices. Sensor integration activity clusters in Kanagawa Prefecture, where medical device OEMs partner with semiconductor houses for custom MEMS designs.
China
Domestic production of MEMS inertial sensors scales through state-backed semiconductor initiatives, though medical-grade certification lags consumer and automotive applications. NMPA registration requirements for active implantable and body-worn diagnostic accessories tighten validation protocols for imported accelerometer modules. Shenzhen hardware ecosystems supply reference designs for wearable patient monitoring platforms targeting home care segments.
South Korea
MFDS regulatory guidance accelerates approval timelines for software-as-medical-device applications incorporating accelerometer data. National health insurance reimbursement codes for digital therapeutics create demand pull for motion analysis systems in stroke rehabilitation. Seoul Capital Area medical device clusters integrate MEMS sourcing with domestic foundry capacity for capacitive sensing elements.
Accelerometers Medical Sensors Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue algorithm-integrated service models that bundle hardware with remote monitoring platforms. Market structure tilts toward consolidation among semiconductor foundries supplying MEMS die, while downstream device assembly fragments across wearable OEMs and telemetry system integrators. Three archetypes dominate: MEMS foundry operators with medical-certified production lines, fabless sensor designers licensing calibration IP, and verticalized health platforms capturing end-user relationships. Competitive moves center on strategic partnerships between foundries and wearable OEMs, plus portfolio diversification into multi-sensor fusion modules combining accelerometry with gyroscope and magnetometer elements.
Within the foundry-tier, STMicroelectronics and Bosch Sensortec occupy positions exemplifying scale-driven MEMS production for medical-qualified supply chains. Texas Instruments anchors the signal-conditioning chipset segment, representing the integration archetype that reduces bill-of-materials complexity for device manufacturers. These three entities collectively illustrate competitive positioning across the value chain from die fabrication to system-level component supply.
| Leading Market Players |
|---|
| Analog Devices, Inc. |
| STMicroelectronics |
| Fitbit Inc. |
| ResMed |
| Garmin |
| Bosch Sensortec |
| NXP Semiconductors |
| Texas Instruments |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Silicon wafer costs cascade from Taiwan foundries through MEMS die fabrication into tiered accelerometer module pricing, with FDA-certified production lines commanding premium positioning over consumer-grade alternatives.
Pricing Analysis
Service bundling separates calibration-inclusive contracts from bare-component transactions. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and volume scale. Cost compression in economy tiers intensifies because hospital procurement groups fragment vendor portfolios. Home care aggregators exhibit highest price sensitivity; diagnostic-grade OEMs accept premium positioning for validated supply chains.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based MEMS wafer fabrication capacity for capacitive sensing element production. Raw material dependencies include silicon substrates, photoresist chemicals, and noble metal electrode materials. Distribution runs through semiconductor distributors into device OEM assembly facilities. Tariff exposure on imported die creates margin pressure for European and United States-based sensor packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS foundry capacity constraints prop pricing power for certified medical-grade supply, creating durable margin pools for qualified producers.
For Market Incumbents: Extend calibration IP licensing into firmware-integrated service models that capture recurring revenue beyond hardware sales. Add captive MEMS capacity in South Korea or Japan to reduce Taiwan concentration exposure. Deepen hospital system partnerships before procurement fragmentation accelerates. For New Entrants and Emerging Players: FDA 510(k) pathway streamlining in the United States opens a window for predicate-device accelerometer claims targeting fall detection wearables. Home care telemetry bundles represent the most penetrable segment. Pursue direct-to-telehealth-platform distribution to bypass durable medical equipment intermediaries. For Investors and Strategic Acquirers: PMDA consultation filing volumes in Japan are the leading indicator that aging-in-place infrastructure procurement is scaling. Target fabless sensor designers with embedded calibration algorithms and existing FDA master files. Watch for foundry-tier consolidation signals as capacity scarcity intensifies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated premarket reviews shorten time-to-revenue for wearable diagnostic manufacturers. |
| CE Marking Pathway | EU MDR clinical dossier requirements compel prospective validation investment before market access. |
| Hospital System Partnership | Procurement group consolidation creates vendor consolidation pressure for motion analysis systems. |
| Software Companion Development | Embedded neural inference on accelerometer companion chips enables on-device activity classification. |
| Reimbursement Strategy | Medicare Advantage remote monitoring bundles pull sensor demand beyond hospital walls. |
Research Approach
Multi-period observation of FDA 510(k) clearance timelines, EU MDR certification trajectories, and foundry capacity utilization anchored the trend analysis, supplemented by interviews with MEMS foundry operations managers, hospital biomedical engineers, GPO contracts managers, and remote patient monitoring platform executives. Secondary validation drew from FDA premarket notification databases, EUDAMED registration records, SEMI industry reports, and CMS Medicare reimbursement code updates. Bottom-up sensor shipment estimates triangulated against top-down healthcare telemetry spending figures.
Input-output matrices mapped capacitive MEMS die production through sensor module assembly into end-use applications across patient monitoring, motion analysis, and rehabilitation segments. Modeled dimensions included product architecture, care setting, clinical indication, and transduction physics. CAGRs were derived from segmented volume projections reconciled against macro healthcare expenditure trends. Forecast inputs incorporated semiconductor capital expenditure cycles and regulatory approval velocity.
The model assumes a particular technology adoption path; alternative pathways for piezoelectric or thermal transduction would alter the outlook if temperature stability or shock tolerance requirements shift. Forecasts reflect assumptions about reimbursement code expansion and foundry capacity allocation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Augmented Bone Graft Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Bandage Contact Lenses Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Spine Bone Stimulators Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Morcellators Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Infant Incubator Market
Medical Devices
Spinal Osteosynthesis Units Market