
 Europe Plastic Packaging Films Market | 2026-2036
Europe Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plastic Packaging Films Market Insights
Fresh produce and ready-to-eat meal packaging is recalibrating demand profiles across the continent. Amcor plc leverages its pan-European manufacturing footprint to serve multinational food brands with consistent specifications. Mondi plc anchors its position through integrated paper and film operations that address fiber-based flexible packaging demand. Berry Global Inc. competes aggressively in healthcare and industrial segments with specialized high-barrier and sterilizable film portfolios.
Europe plastic packaging films are thin, flexible polymer substrates typically ranging from 12 to 150 microns in thickness, manufactured through cast or blown extrusion processes and often coextruded or laminated to achieve oxygen transmission rates below 1 cc/m²/day for sensitive contents. These films primarily protect perishables from moisture ingress, gas exchange, and mechanical damage while enabling efficient forming, sealing, and printing on high-speed packaging lines. Stretch film dominates volume flows across the material spectrum, while barrier film commands premium positioning due to ethylene vinyl alcohol and polyamide layer incorporation for oxygen-sensitive applications. Polyethylene sustains its volume leadership across food and industrial end-uses, though polypropylene is gaining share in retort and microwaveable formats where thermal resistance determines specification.
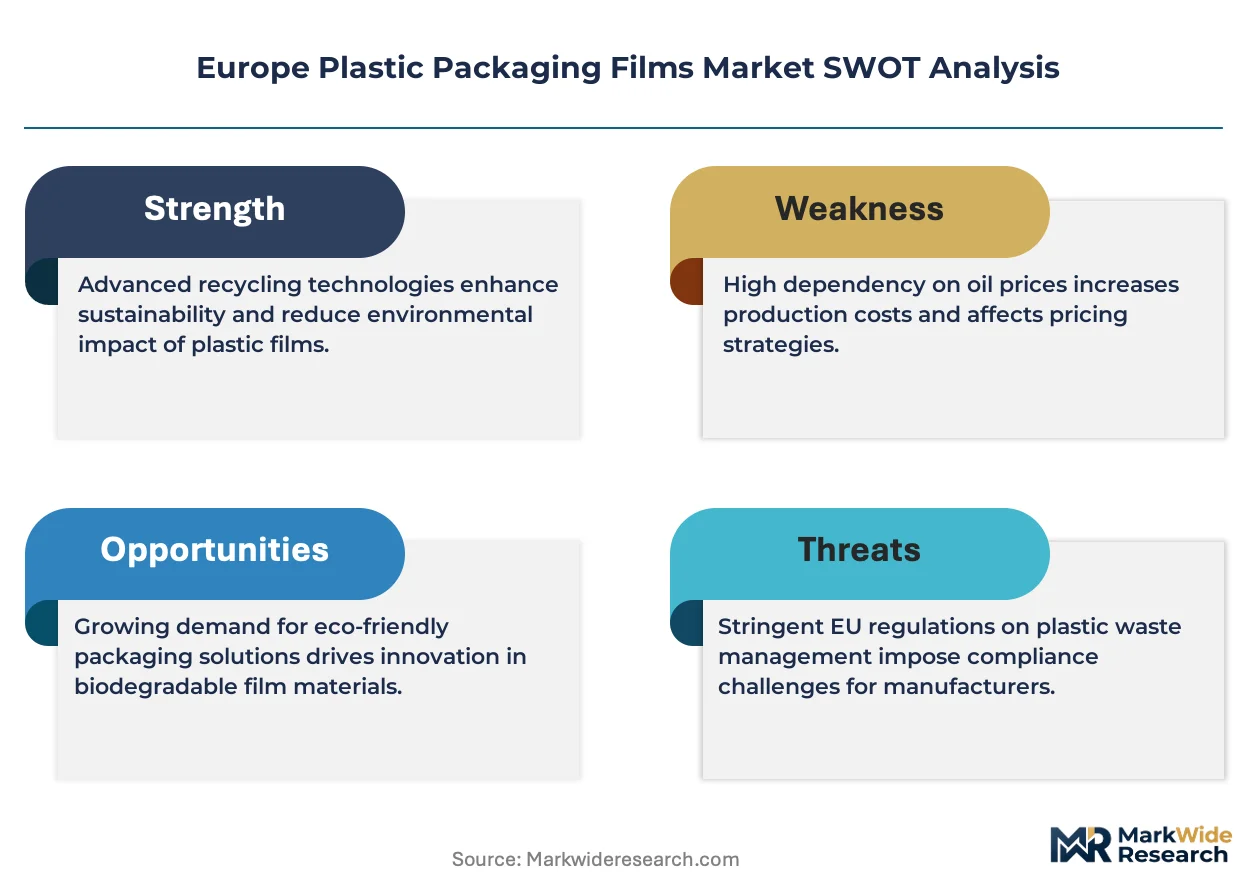
The EU's Packaging and Packaging Waste Regulation and ECHA's REACH framework are reshaping material selection, with extended producer responsibility schemes now mandating minimum recycled content thresholds that force reformulation of multilayer structures. CE marking requirements under the EU's harmonized standards for materials in contact with food establish compliance baselines that filter non-conforming imports from third-country suppliers. Stakeholders must monitor how the EU Green Deal's carbon border adjustment mechanism alters cost structures for virgin resin imports and whether mechanical recycling infrastructure investments keep pace with regulatory timelines for recyclability targets.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is forcing a wholesale reconstitution of film structures, as extended producer responsibility schemes and mandatory recycled content thresholds render multilayer laminates economically unviable and technically non-compliant.
Growth Catalysts
- EPR scheme expansion:Germany's Verpackungsgesetz mandates minimum recycled content thresholds that accelerate investment in mono-material compatible extrusion lines and compatibilizer technologies.
- Fresh produce sector:Modified atmosphere packaging demand from Spanish and Italian vegetable exporters pulls high-barrier film volumes as retailers specify shelf-life extension for cross-border distribution.
- Digital printing integration:Flexographic and inkjet systems enable shorter run lengths and SKU proliferation, allowing food brands to regionalize packaging without plate changeover penalties.
Market Restraints
- Ethylene vinyl alcohol supply concentration:Korean and Japanese resin producers control 70% of EVOH supply to European converters, exposing film manufacturers to freight volatility and currency hedging costs.
- Mechanical recycling incompatibility:Legacy multilayer structures containing polyamide tie layers resist density-separation processes, forcing film producers to absorb scrap losses or invest in solvent-based delamination.
- Compostable film performance gap:Polylactic acid and polyhydroxyalkanoate alternatives exhibit moisture sensitivity and seal-strength deficiencies that disqualify them from retort and deep-freeze applications.
Strategic Opportunities
- Poland and Romania:Underdeveloped secondary packaging infrastructure in these markets creates first-mover positioning for stretch film producers serving automotive and appliance export clusters.
- Chemical recycling feedstock agreements:Partnerships with pyrolysis operators allow film producers to certify circular content without mechanical recycling yield losses, satisfying brand owner sustainability claims.
- Healthcare sterilizable films:Ethylene oxide and gamma-radiation compatible barrier structures for medical device packaging command price premiums as European healthcare supply chains reshore from Asian suppliers.
Industry Challenges
- Polymer compatibilizer formulation:Blending post-consumer polyethylene with virgin resin requires precise viscosity matching and antioxidant stabilization that few extrusion technicians master.
- CE marking documentation:EU harmonized standards for food contact materials demand migration testing protocols that extend new product qualification timelines by four to six months.
- Legacy line retrofitting:Converting blown film assets from multilayer to mono-material production necessitates die and cooling ring replacement that strains mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plastic Packaging Films Market |
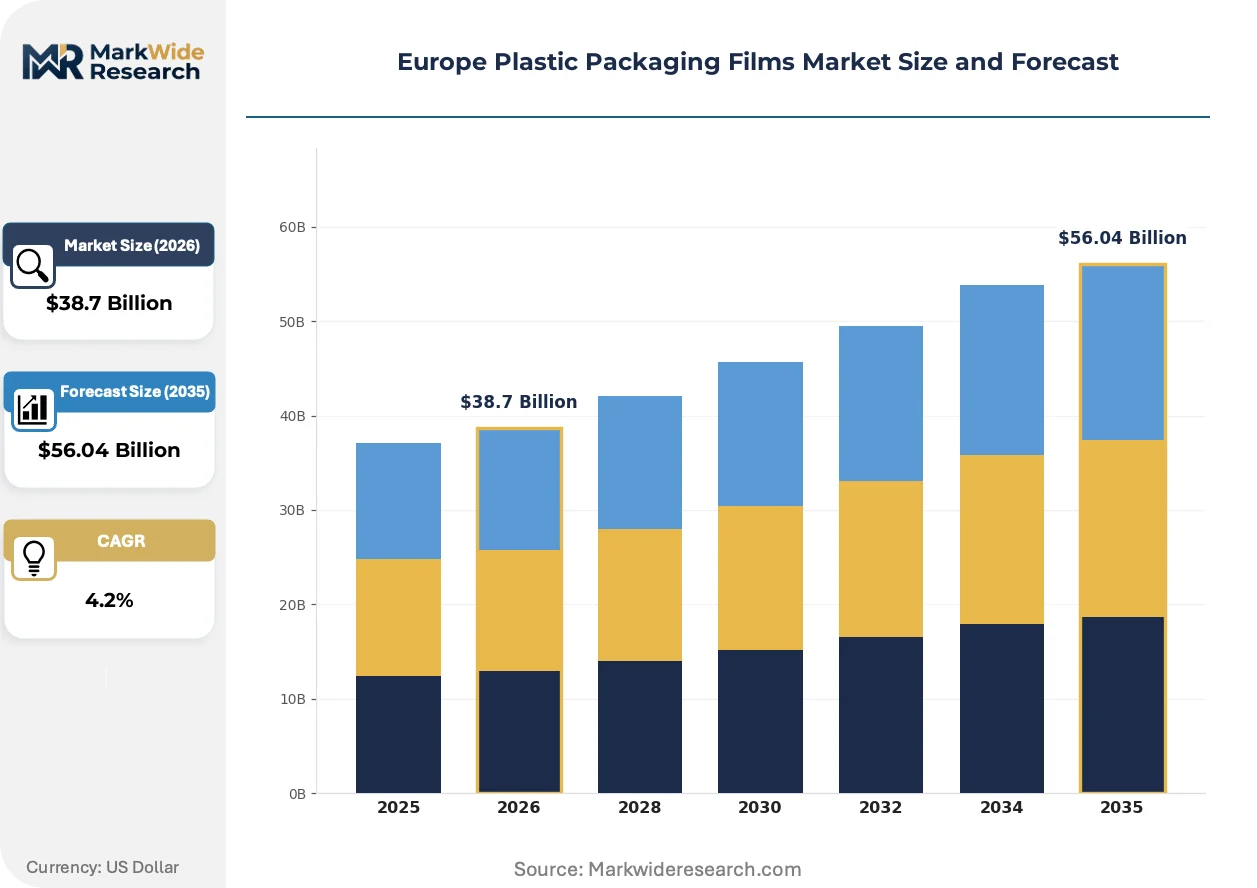
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Barrier Film, Rigid Film Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others Application: Food & Beverage, Healthcare, Consumer Goods, Industrial Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Taghleef Industries LLC, Innovia Films Ltd, Jindal Films Europe Virton S.A., Mondi plc, Amcor plc, Berry Global Inc., SÜDPACK Holding GmbH, Toray Films Europe, Klöckner Pentaplast GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plastic Packaging Films Market Trends and Innovations
Film producers are racing to re-engineer coextrusion architectures as regulatory deadlines compress development cycles, with sustainability performance now determining specification wins in branded food accounts.
Mono-material polyethylene barrier films incorporating advanced nucleating agents and metallized coatings are overtaking conventional EVOH-PA multilayers in ambient shelf-stable applications. German discount retailers and French dairy processors specify these structures for recycling stream compatibility. The shift is compressing demand for high-barrier coextrusion equipment while expanding metallizing and coating capacity bookings.
REACH authorization requirements for phthalate plasticizers and bisphenol-based additives are eliminating legacy formulation options for cling film and stretch wrap producers. ECHA's candidate list expansion forces substitution with bio-based or non-toxic alternatives that alter seal initiation temperatures and cling performance. Food service distributors in Benelux and Scandinavia now reject non-compliant inventory, accelerating formulation turnover.
Centralized procurement consortia among pan-European food manufacturers are consolidating supplier panels and demanding audited carbon footprint data across Scope 3 emissions. Purchasing directors at multinational dairy and meat processors now specify film suppliers with verified mass-balance certification for recycled content. This behavioral shift concentrates volume with integrated resin-to-film producers capable of blockchain-tracked provenance documentation, marginalizing smaller converters lacking LCA capabilities.
Europe Plastic Packaging Films Market Segmentation
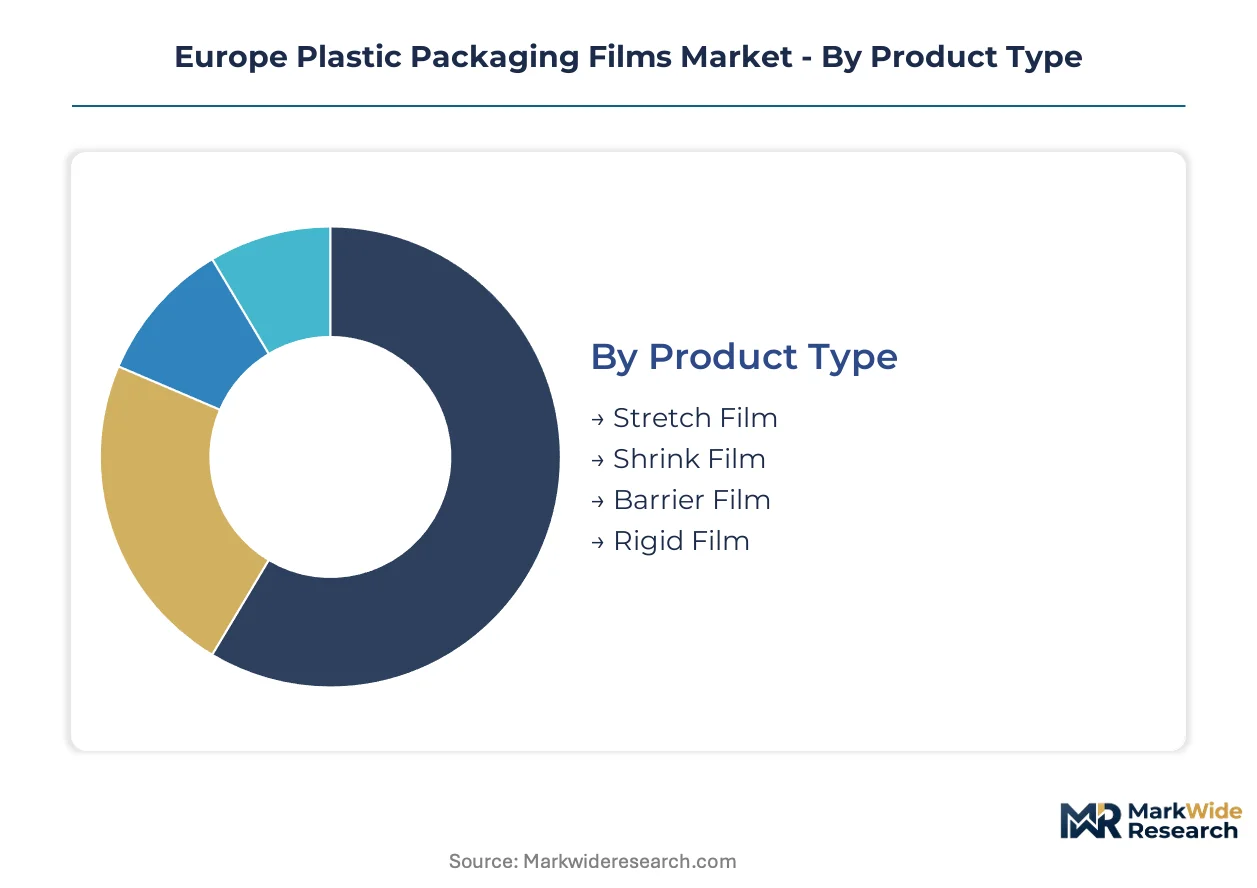
Film converters across Europe are reconfiguring extrusion assets to serve diverging specification requirements across end-use sectors. Segmentation reveals where technical complexity commands premium positioning versus where commodity scale determines margin survival.
Product Type:
Equipment replacement cycles are accelerating as converters retire legacy multilayer lines unable to produce mono-material structures compliant with extended producer responsibility schemes.
- Stretch Film:Linear low-density polyethylene formulations dominate palletization and unitization across automotive and appliance manufacturing clusters in Germany and Poland. Demand concentrates in hand-wrap and machine-wrap grades where downgauging to sub-15 micron specifications reduces resin consumption per pallet.
- Barrier Film:Ethylene vinyl alcohol and polyamide coextrusions or metallized polyethylene alternatives protect oxygen-sensitive contents in modified atmosphere packaging for Spanish vegetable exporters and French dairy processors. ECHA's REACH framework and the EU's Packaging and Packaging Waste Regulation are forcing rapid substitution of non-recyclable multilayers with mono-material barrier structures.
- Shrink Film:Cross-linked and non-cross-linked polyethylene grades bundle multi-pack consumer goods for retail display; Italian beverage bottlers specify high-clarity formulations for shelf visibility.
- Rigid Film:Thermoformable polypropylene and polyethylene terephthalate structures serve tray and blister applications where dimensional stability determines forming depth and seal integrity.
Stretch film sits at the top of the volume ranking, with barrier film climbing the fastest as food brands redesign packaging for recycling stream compatibility.
Material:
Raw material selection now hinges on mechanical recycling infrastructure availability and mass-balance certification capabilities rather than purely functional performance.
- Polyethylene:Low-density, linear low-density, and high-density grades sustain volume leadership across flexible food packaging, stretch wrap, and industrial film applications. German discount retailers specify recycled-content polyethylene for private-label packaging to satisfy Verpackungsgesetz mandates.
- Polypropylene:Cast and oriented films gain share in retort pouches and microwaveable trays where thermal resistance above 120°C determines specification. Biaxially oriented polypropylene dominates snack food packaging for its stiffness and printability.
- Polyvinyl Chloride:Cling film for fresh produce wrapping persists in Southern European markets despite REACH authorization pressures on phthalate plasticizers; converters are substituting with bio-based alternatives that alter seal initiation behavior.
- Others:Polyamide, polyethylene terephthalate, and biodegradable polymers including polylactic acid serve niche applications where barrier performance or compostability claims justify cost premiums.
Polyethylene maintains the dominant volume position, with polypropylene expanding most quickly in high-temperature food packaging formats.
Application:
End-use demand fragmentation is forcing converters to maintain parallel production capabilities for food-grade and industrial specifications with diverging compliance requirements.
- Food & Beverage:Modified atmosphere packaging for meat, cheese, and fresh produce drives specification innovation; CE marking under EU harmonized standards for food contact materials extends qualification timelines.
- Healthcare:Sterilizable barrier films for medical device packaging command price premiums as European supply chains reshore from Asian suppliers; ethylene oxide and gamma-radiation compatibility requirements filter supplier panels.
- Consumer Goods:Printed laminates for personal care and household products face sustainability scrutiny from Benelux and Scandinavian distributors rejecting non-compliant inventory.
- Industrial:Construction membrane and agricultural film applications tolerate higher recycled content inclusion where optical clarity is non-critical.
Food and beverage applications generate the highest volume throughput, with healthcare demonstrating the steepest margin expansion trajectory.
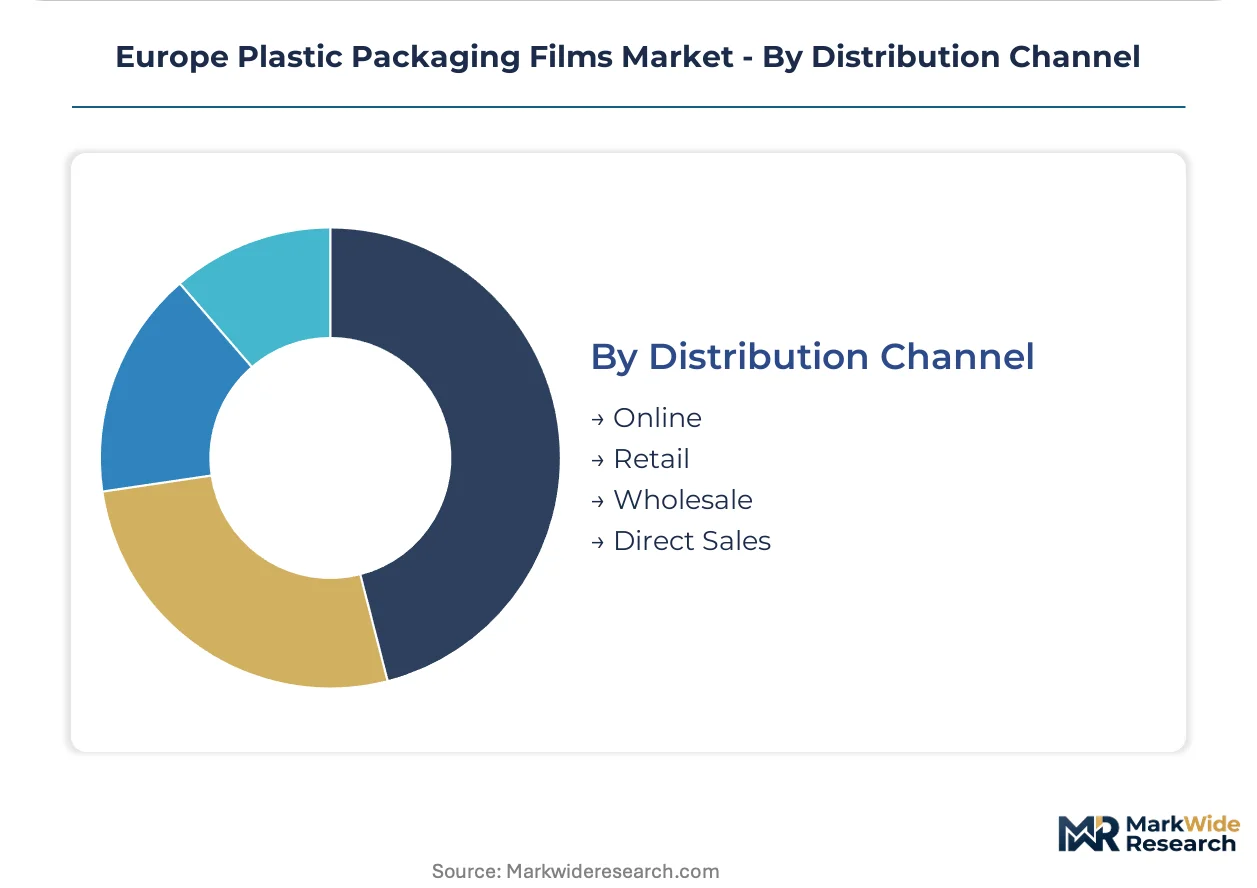
Distribution Channel:
Procurement consolidation among pan-European food manufacturers is reshaping how film specifications reach converter order books.
- Online:Digital platforms serve small and mid-tier converters with standardized stock grades and rapid turnaround on narrow width slitting requirements.
- Retail:Regional distribution networks supply maintenance, repair, and operations film volumes to local packaging operations.
- Wholesale:Merchant distributors aggregate demand from fragmented food processors and coordinate just-in-time delivery to minimize converter inventory carrying costs.
- Direct Sales:Integrated resin-to-film producers with blockchain-tracked provenance documentation capture multinational dairy and meat processor accounts specifying audited carbon footprint data.
Direct sales channels command the largest contract values, with online platforms gaining share fastest among smaller converters lacking procurement consortium access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing film production capacity across the continent as converters seek jurisdictions with lower compliance costs for legacy multilayer assets. The EU's Packaging and Packaging Waste Regulation applies uniformly, yet national implementation timelines and enforcement intensity create operational gaps that shape investment flows.
Germany
Centralized food processing and automotive export manufacturing generate outsized demand for stretch and barrier film specifications. The Verpackungsgesetz mandates recycled content thresholds that accelerate mono-material line investments in the Ruhr industrial corridor. Bavarian dairy processors and Baden-Württemberg automotive clusters specify high-barrier structures for cross-border distribution networks.
France
Dairy and cheese packaging requirements from Normandy and Brittany processors drive modified atmosphere film innovation for shelf-life extension. ECHA's REACH framework restricts phthalate plasticizers in cling film formulations, forcing substitution with bio-based alternatives. The Grand Est region hosts pharmaceutical packaging converters serving sterilizable film demand from Paris-based healthcare distributors.
Italy
Fresh produce exporters in Emilia-Romagna and Sicily specify high-clarity shrink film for retail display visibility in Northern European markets. CE marking requirements under EU harmonized standards extend qualification timelines for food contact materials. The Veneto packaging machinery cluster supplies extrusion and metallizing equipment to domestic film converters.
Spain
Vegetable exporters in Murcia and Almería pull high-barrier volumes for modified atmosphere packaging of peppers and tomatoes bound for German discount retailers. Extended producer responsibility schemes under national packaging waste legislation concentrate investment in recyclable mono-material structures. Catalan converters serve pan-European beverage bottlers with printed shrink sleeve specifications.
Poland
Automotive and appliance export manufacturing in the Silesian and Greater Poland voivodeships generates stretch film demand for palletization and unitization. Underdeveloped secondary packaging infrastructure creates positioning opportunities for producers serving German supply chain requirements. Warsaw-based distributors aggregate demand from fragmented food processors for just-in-time film delivery.
Europe Plastic Packaging Films Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated resin-to-film producers capturing multinational accounts while regional converters serve fragmented local demand. The vendor base concentrates around three strategic archetypes: pan-European integrated producers with mass-balance certification capabilities, mid-tier national specialists with legacy multilayer assets, and niche healthcare-focused sterilizable film suppliers. M&A activity targets compatibilizer technology and chemical recycling feedstock agreements, while capacity expansion concentrates in Poland and Romania to serve automotive export clusters.
Within the integrated producer tier, Amcor plc and Mondi plc exemplify archetypes of scale-driven positioning with pan-European manufacturing footprints. Berry Global Inc. occupies a position among specialized barrier film suppliers addressing healthcare and industrial segments. These entities anchor competitive dynamics as procurement consolidation among pan-European food manufacturers concentrates volume with producers capable of blockchain-tracked provenance documentation.
| Leading Market Players |
|---|
| Taghleef Industries LLC |
| Innovia Films Ltd |
| Jindal Films Europe Virton S.A. |
| Mondi plc |
| Amcor plc |
| Berry Global Inc. |
| SÜDPACK Holding GmbH |
| Toray Films Europe |
| Klöckner Pentaplast GmbH |
| Others |
Pricing and Supply Chain Analysis
Extended producer responsibility schemes under the EU's Packaging and Packaging Waste Regulation are compressing margins for multilayer film converters while rewarding mono-material specialists with pricing power and specification wins.
Pricing Analysis
Distributor margins absorb the compliance cost burden for smaller converters lacking direct resin sourcing relationships. Three-tier pricing structure across premium, standard, and economy levels separates mass-balance certified film from conventional grades and commodity stock rolls. Cost compression in standard-tier polyethylene formulations is intensifying because German discount retailers mandate recycled content thresholds without corresponding price premiums. Food processors with centralized procurement consortium access exhibit lowest price sensitivity, while fragmented meat packers in Poland and Romania face acute margin pressure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from pan-European dairy and meat processors specifying blockchain-tracked provenance documentation. Raw material supply concentrates in Germany, Belgium, and the Netherlands, where integrated resin-to-film producers control ethylene and propylene feedstock access. EVOH barrier resin draws from Korean and Japanese suppliers, creating single-source vulnerability for high-oxygen-barrier specifications. Distribution runs through merchant wholesalers aggregating fragmented food processor demand, with just-in-time delivery coordination minimizing converter inventory carrying costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material film conversion creates margin expansion as technical complexity commands premium positioning while mechanical recycling scale drives resin cost reduction.
For Market Incumbents: Deepen backward integration into post-consumer polyethylene sorting and compatibilizer formulation to secure mass-balance certification capabilities. Expand metallizing capacity in the Ruhr corridor to capture specification shifts away from EVOH-PA multilayers. Defend against Korean resin supplier price volatility through long-term offtake agreements with pyrolysis operators for circular feedstock security. For New Entrants and Emerging Players: Capture underdeveloped secondary packaging infrastructure in Poland's Silesian automotive clusters and Romania's appliance export zones. Target stretch film grades for palletization demand where downgauging specifications reduce resin consumption per pallet. Enter through wholesale distribution partnerships aggregating fragmented processor demand without requiring direct multinational account access. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier converters possessing legacy blown film assets in jurisdictions with delayed enforcement timelines. Long-term viability hinges on chemical recycling feedstock agreements and compatibilizer technology ownership. Watch for ECHA REACH authorization expansions affecting phthalate plasticizer formulations as the inflection signal for formulation substitution investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Recycling | Mass-balance certification secures multinational dairy processor contracts under Verpackungsgesetz mandates. |
| Metallizing Capacity Expansion | Mono-material barrier coatings displace EVOH-PA multilayers in ambient shelf-stable French dairy applications. |
| Chemical Recycling Feedstock Partnership | Pyrolysis operator agreements satisfy brand owner sustainability claims without mechanical yield losses. |
| Compatibilizer Technology Acquisition | Viscosity matching expertise enables post-consumer polyethylene blending at German discount retailer specifications. |
| Healthcare Sterilizable Film Qualification | Ethylene oxide and gamma-radiation compatibility captures reshoring demand from Paris-based medical distributors. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Southern Europe, with primary inputs from each regional cluster combining structured interviews with extrusion plant managers, procurement leads at downstream food processors, distribution channel partners, and technical R&D directors with secondary validation against customs and trade data, Cefic industry reports, SEC filings, and EU regulatory databases. Bottom-up volume modeling triangulates with top-down value estimates.
Granularity extends to product type, material grade, end-use application, and distribution channel across the projection horizon. CAGRs derive from segment-level growth rate synthesis incorporating EPR scheme implementation timelines, mechanical recycling infrastructure buildout curves, and food export volume trajectories. Industry-specific inputs include ethylene and propylene feedstock price indices, EVOH resin import volumes, and packaging machinery installation data.
Regulatory enforcement delays, pyrolysis capacity commissioning slippage, and EVOH supply disruption are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
France Plastic Bottles Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
China Plastic Packaging Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
Plastic Shrink Wrap Market