
 PET Jars Market | 2026-2036
PET Jars Market Size, Share, and Industry Trends Forecast 2026-2036
PET Jars Market Analytics
Asset-light leasing models for blow-molding equipment is reconfiguring competitive entry barriers, allowing mid-sized converters to scale without heavy capital deployment. Berry Global Inc. leverages its North American manufacturing footprint to sustain cost leadership in high-volume food contracts. ALPLA anchors its position through backward integration into preform production, controlling resin flow across multiple plant locations. Resilux NV differentiates by specializing in custom wide-mouth formats for premium nut butter and spread brands.
PET jars are thermoformed or injection-stretch-blow-molded containers constructed from polyethylene terephthalate resin, typically offering barrier properties against moisture and oxygen with wall thickness ranging from 0.3 to 1.2 millimeters depending on application requirements. Their primary purpose centers on shelf-stable storage, consumer visibility of contents, and compatibility with automated filling lines across food, pharmaceutical, and personal care operations. Wide mouth jars dominate volume in the food and beverage end user segment due to spoon-access convenience for viscous products, while tamper evident jars command margin premiums in pharmaceuticals where child-resistant and senior-friendly closure compliance adds certification value. The 500ml to 1L capacity band represents the most contested space, with multiple converters competing for condiment and cooking sauce contracts that balance shipping cube efficiency with household consumption rates.
FDA food contact regulations and EU REACH compliance requirements shape material selection and additive formulations for PET jars entering their respective markets, with rPET sourcing documentation now treated as a market access prerequisite rather than a voluntary attribute. The EU Packaging and Packaging Waste Regulation extends these obligations through mandatory recycled content minimums and extended producer responsibility fee structures that favor lightweight, recyclable designs. ISO 22000 and BRCGS certification standards further filter supplier qualification for food contact applications, particularly for converters supplying private-label retail programs. Stakeholders must monitor evolving rPET availability constraints and corresponding price volatility to secure supply commitments before contract renewal cycles.
Market Dynamics
The EU Single-Use Plastics Directive is compressing virgin resin tolerance and forcing converters to reconfigure blow-molding lines for rPET compatibility before contract renewal cycles complete.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content minimums are pulling forward converter investment in rPET sourcing infrastructure across German and French food processing clusters.
- Wide-mouth jar technology:Spoon-access convenience for nut butter and spread brands is displacing metal canisters in North American private-label retail programs.
- German converter concentration:Central European packaging clusters serving high-volume sauce and condiment contracts are capturing cross-border demand from Polish and Czech food processors.
Market Restraints
- rPET feedstock volatility:Bottle-to-bottle recycling capacity constraints in the EU are creating price spikes that compress converter margins on fixed-price annual contracts.
- Preform supply concentration:Backward-integrated resin controllers in Austria and Belgium limit independent converter access to virgin PET during allocation periods.
- HDPE substitution in pharmaceuticals:Moisture-sensitive drug formulations are migrating to fluorinated HDPE barriers that exceed standard PET oxygen transmission rates.
Strategic Opportunities
- Indian food retail modernization:Organized retail expansion in Maharashtra and Gujarat is creating first-mover advantages for jar converters establishing local blow-molding partnerships.
- Pharmaceutical serialization integration:EU MDR traceability mandates are opening service contracts for tamper-evident jar assembly with embedded QR-code authentication.
- Lightweighting technology convergence:Finite element analysis coupled with injection-stretch-blow-molding simulation is enabling sub-20-gram 500ml jar designs that qualify for reduced EPR fees.
Industry Challenges
- Blow-molding technician scarcity:ISBM process optimization and cavity balancing expertise is concentrating among aging workforces in Northern Italy and Southern Germany.
- Multi-certification burden:Simultaneous BRCGS, ISO 22000, and FDA food contact audits are extending qualification timelines for converters entering private-label retail supply chains.
- Legacy filling line incompatibility:Lightweight jar designs with reduced neck finish tolerances are jamming capping equipment calibrated for legacy wall thickness specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Jars Market |
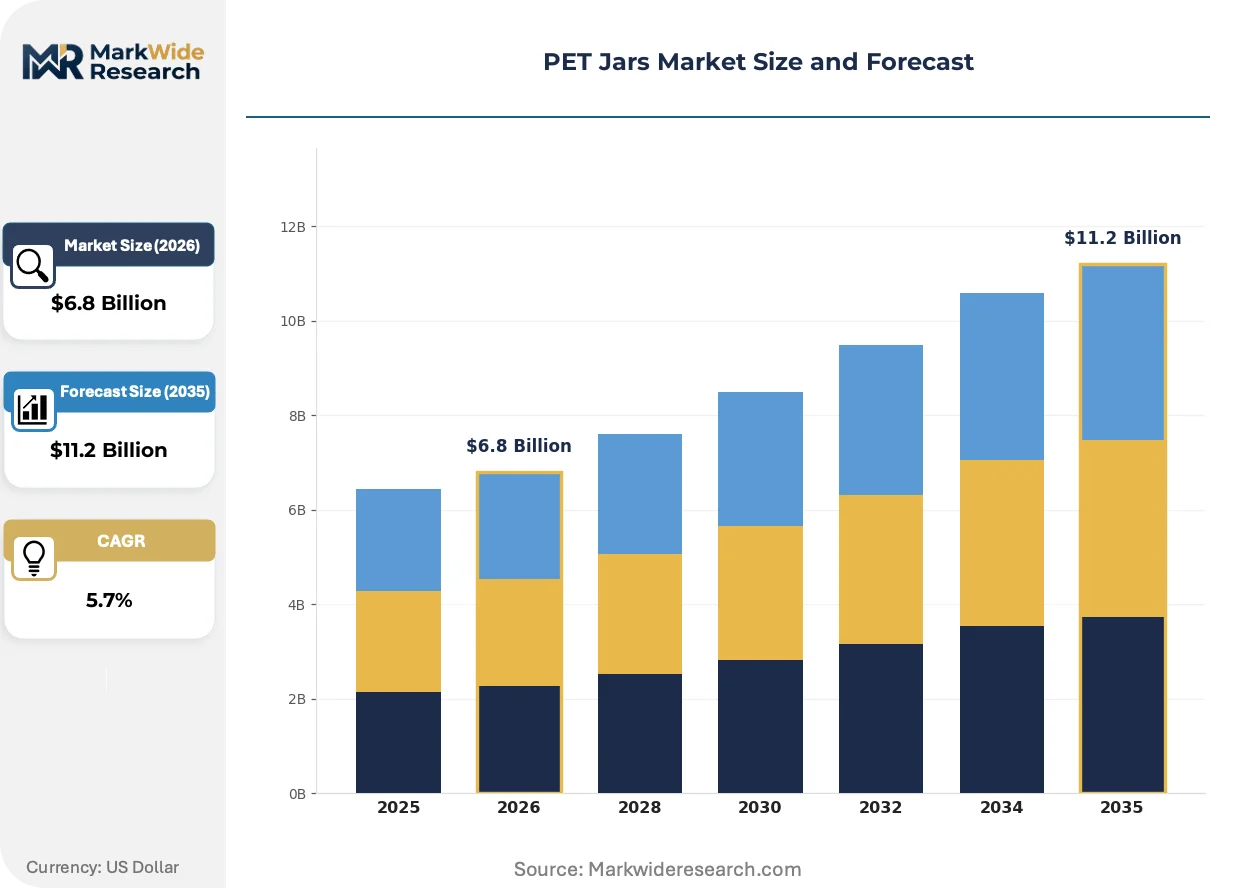
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wide Mouth Jars, Narrow Mouth Jars, Tamper Evident Jars, Specialty Jars Closure Type: Screw Caps, Snap-on Lids, Flip Top Caps, Other Closures End User: Food and Beverage, Pharmaceuticals, Cosmetics, Household Products Capacity: Below 100ml, 100ml to 500ml, 500ml to 1L, Above 1L |
| Companies Covered | Amcor plc, Berry Global Inc., Gerresheimer AG, ALPLA, Graham Packaging Company, Plastipak Holdings Inc., Resilux NV, Comar LLC, Alpha Packaging LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Jars Market Evolving Landscape
Digital manufacturing controls and circular material flows are restructuring how converters compete on speed-to-tool and carbon-accounted sourcing. These shifts favor asset-light operators with rapid rPET qualification capabilities.
Plasma-enhanced chemical vapor deposition barrier coatings are rendering obsolete multilayer PET constructions for oxygen-sensitive sauces and cooking oils. Mid-sized Italian converters are retrofitting existing blow-molding stations with vacuum plasma chambers to capture premium condiment contracts. The technology is compressing material costs by eliminating EVOH interlayers while maintaining shelf-life performance.
REACH SVHC candidate list expansion is forcing reformulation of color masterbatches and UV stabilizers across EU-serving production lines. ECHA notifications for titanium dioxide and certain phthalate alternatives are triggering supply chain audits that delay new product introductions by four to six months. Pharmaceutical jar segments are responding fastest, migrating to mineral-based opacifiers ahead of food-contact applications.
Direct-to-retailer specification consolidation is compressing the converter base serving major European grocery chains. Buying desks in Rotterdam and Hamburg are unbundling jar supply from closure and label procurement, forcing converters to certify complete primary packaging systems. This pattern is most visible in German discount retail, where annual tender cycles now require carbon-footprint disclosure at the SKU level.
PET Jars Market Segmentation
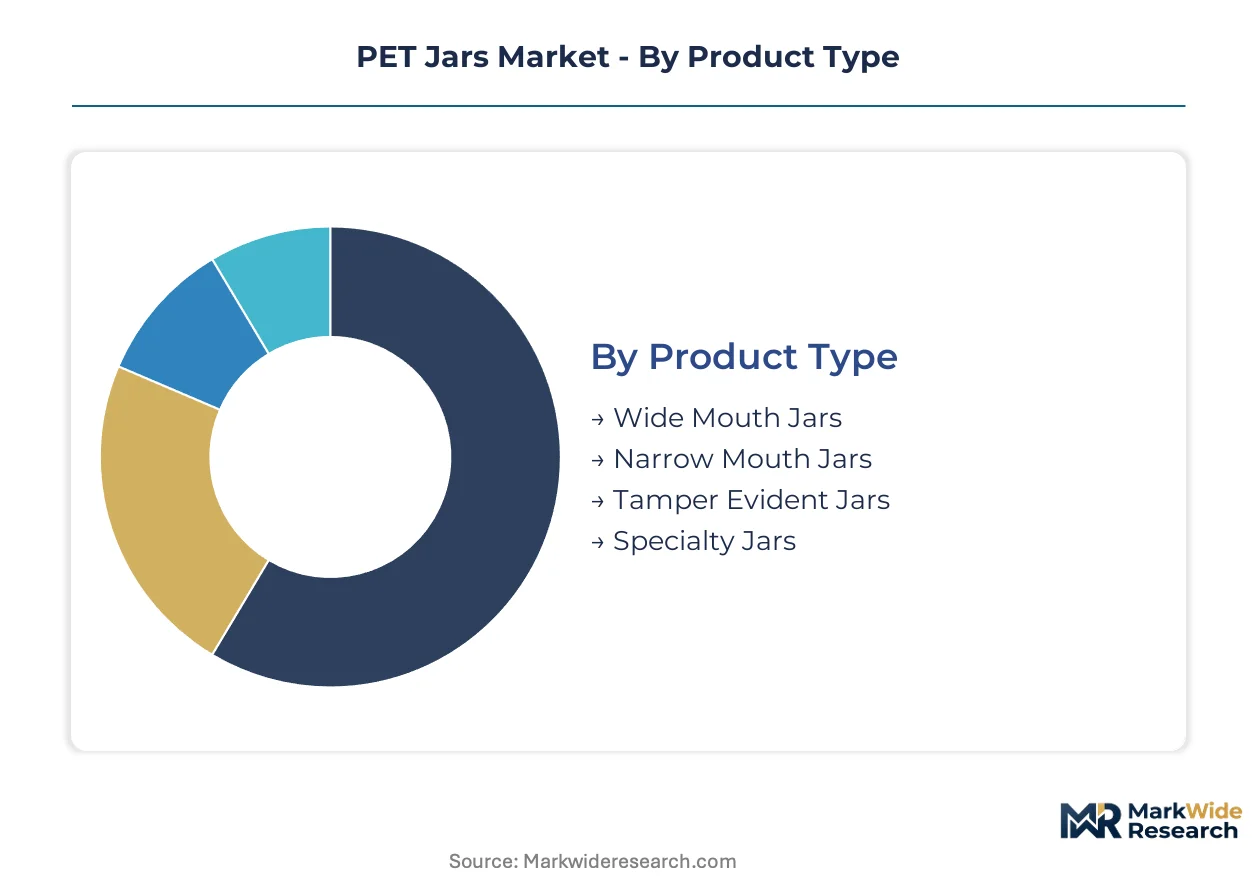
PET jar converters configure production lines around specific dimensional and functional requirements that determine blow-molding parameters, closure compatibility, and barrier specifications. Segmentation choices directly shape capital allocation decisions for rPET qualification and lightweighting investments.
Product Type:
After-sales service intensity varies sharply across jar formats, with wide-mouth designs requiring more frequent tooling maintenance and neck-finish calibration support than narrow-mouth alternatives.
- Wide Mouth Jars:These containers feature neck openings exceeding 63mm diameter to accommodate spoon or scoop access for viscous products. German and Polish food processors dominate demand for nut butter and spread applications where EU Packaging and Packaging Waste Regulation compliance pressures favor recyclable single-material construction.
- Narrow Mouth Jars:Standard 28mm to 38mm neck finishes suit controlled-pour applications for cooking oils and liquid condiments. North American private-label retailers specify these formats for cost-optimized sauce lines where shipping cube efficiency outweighs convenience features.
- Tamper Evident Jars:Integral tear-band or shrink-sleeve security features serve pharmaceutical and high-value food segments requiring visible breach indication. FDA food contact and EU MDR traceability mandates drive specification complexity in these formats.
- Specialty Jars:Custom geometries including square shoulders, grip panels, or embossed branding surfaces target premium cosmetic and gift-food positioning. Italian converters specialize in short-run specialty tooling for Mediterranean olive oil exporters.
Wide Mouth Jars holds the largest share; momentum sits with Tamper Evident Jars.
Closure Type:
Cost tier differentiation separates commodity screw-cap compatibility from premium dispensing features that command per-unit premiums and specialized assembly equipment.
- Screw Caps:Threaded aluminum or plastic closures remain the baseline specification across high-volume food contracts. Continuous thread (CT) and lug finishes dominate German retail supply chains where automated capping line speeds exceed 400 units per minute.
- Snap-on Lids:Press-fit polyethylene closures suit dry goods and non-liquid applications where reseal performance is secondary to cost minimization. Indian organized retail expansion in Maharashtra favors snap-on formats for spice and dry-food private-label programs.
- Flip Top Caps:Hinged dispensing closures command margin premiums in condiment and personal care segments where one-handed operation drives consumer preference. REACH SVHC constraints on color masterbatches complicate flip-top sourcing for EU-serving converters.
- Other Closures:Pump dispensers, trigger sprayers, and child-resistant mechanisms serve niche pharmaceutical and household chemical applications. ECHA notification delays for titanium dioxide alternatives extend qualification timelines for opacified closure components.
Screw Caps dominate volume; Flip Top Caps are climbing the fastest.
End User:
Application-specific certification requirements fragment converter capabilities, with pharmaceutical and food-contact qualifications rarely overlapping in mid-sized operations.
- Food and Beverage:Shelf-stable sauces, spreads, and ready-to-eat meals constitute the primary demand pool. Central European packaging clusters in Germany and Austria serve cross-border Polish and Czech food processors with BRCGS-certified wide-mouth solutions.
- Pharmaceuticals:Moisture-sensitive and oxygen-critical drug formulations specify barrier-enhanced PET or alternative materials. EU MDR serialization mandates are opening assembly contracts for tamper-evident jars with embedded QR-code authentication.
- Cosmetics:Premium skincare and haircare brands specify thick-walled jars with decorative finishing. REACH reformulation pressures on UV stabilizers are accelerating migration to mineral-based opacifiers ahead of food-contact applications.
- Household Products:Cleaning chemicals and automotive fluids utilize chemical-resistant PET grades with fluorinated or multilayer barriers. HDPE substitution pressure is strongest in this segment where cost sensitivity exceeds material preference.
Food and Beverage commands the largest share; Pharmaceuticals shows the steepest expansion trajectory.
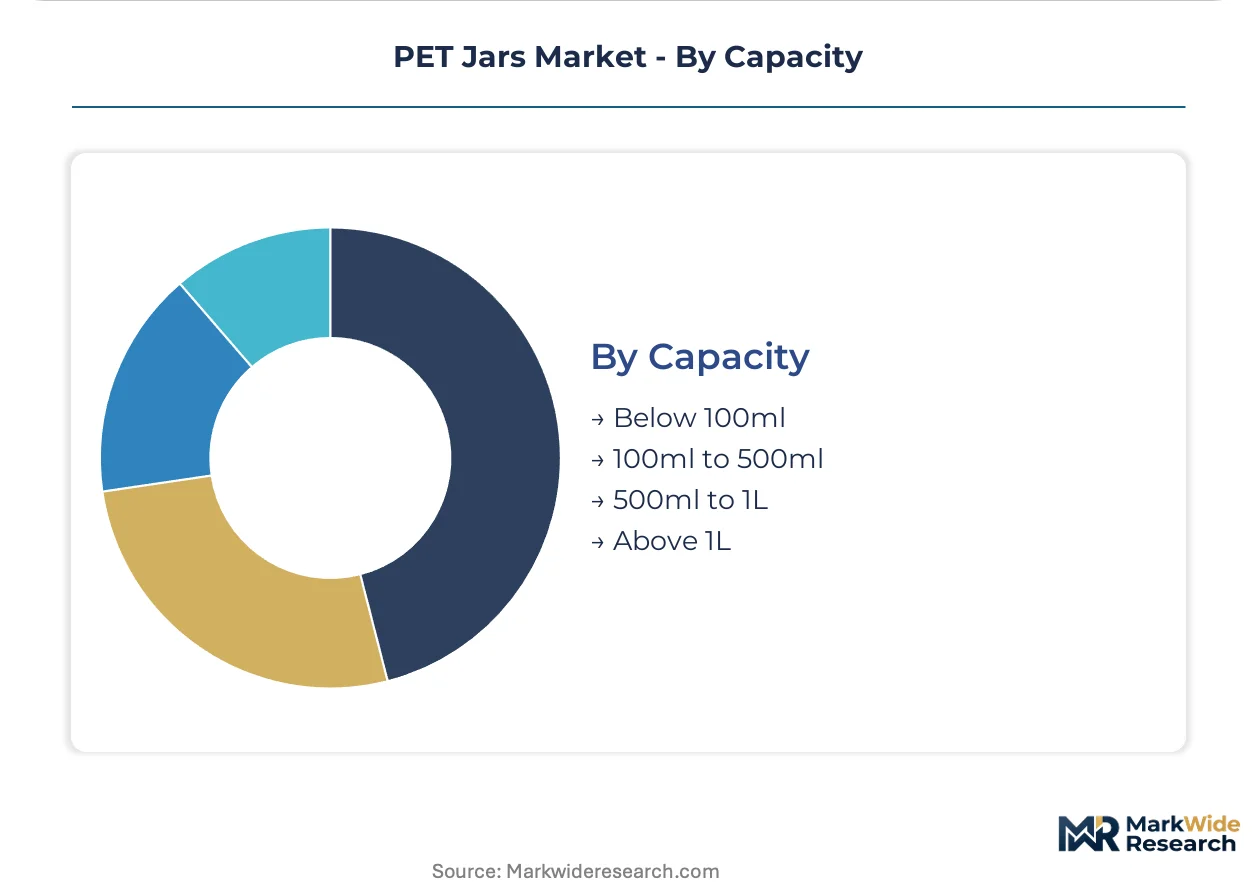
Capacity:
Volume scale determines blow-molding equipment selection, with sub-100ml formats requiring different cavity configurations and cycle parameters than liter-plus containers.
- Below 100ml:Single-serve and sample-size jars serve travel retail and pharmaceutical trial packaging. Italian ISBM specialists concentrate capability in this band for cosmetic and fragrance applications.
- 100ml to 500ml:Mid-size formats balance portability with household consumption rates for premium condiments and personal care. This band sees intense competition from aluminum and glass alternatives in European sustainable packaging tenders.
- 500ml to 1L:The most contested capacity range anchors condiment and cooking sauce contracts across North American and European retail. Finite element analysis-enabled lightweighting below 20 grams is qualifying converters for reduced EPR fees in German discount retail.
- Above 1L:Bulk formats for food service and institutional channels prioritize shipping cube efficiency over shelf aesthetics. rPET feedstock volatility compresses margins on fixed-price annual contracts in this high-resin-content segment.
500ml to 1L holds the largest share; Below 100ml is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation mandates are pulling converter investment toward rPET sourcing infrastructure across major food processing clusters. Germany anchors Central European supply chains while North American and Asian markets develop distinct compliance pathways.
Germany
Bavarian and North Rhine-Westphalian packaging clusters serve cross-border Polish and Czech food processors with BRCGS-certified wide-mouth jar solutions. ECHA REACH SVHC notifications on titanium dioxide are triggering supply chain audits that delay new product introductions. Hamburg buying desks now require carbon-footprint disclosure at the SKU level for annual tender cycles.
United States
FDA food contact regulations shape material selection for converters supplying private-label retail programs across Midwestern and Southeastern food processing corridors. North American private-label retailers specify narrow-mouth formats for cost-optimized sauce lines where shipping cube efficiency outweighs convenience features. Berry Global leverages its manufacturing footprint to sustain cost leadership in high-volume food contracts.
India
Organized retail expansion in Maharashtra and Gujarat creates first-mover advantages for jar converters establishing local blow-molding partnerships. FSSAI compliance requirements filter supplier qualification for food contact applications in emerging private-label retail programs. Mumbai and Ahmedabad industrial zones concentrate demand for snap-on lid formats in spice and dry-food segments.
Italy
Mid-sized ISBM specialists in Northern Italy concentrate capability for sub-100ml cosmetic and fragrance applications. ECHA reformulation pressures on UV stabilizers accelerate migration to mineral-based opacifiers ahead of food-contact applications. Emilia-Romagna and Lombardy converters retrofit existing blow-molding stations with vacuum plasma chambers to capture premium condiment contracts.
China
GB standards compliance and dual carbon goals reshape material sourcing for converters serving domestic food and beverage brands. Yangtze River Delta packaging clusters develop rPET qualification capabilities to meet tightening environmental mandates. Shanghai and Jiangsu province converters compete on speed-to-tool for export-oriented sauce and cooking oil contracts.
PET Jars Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: backward-integrated resin controllers, asset-light regional specialists, and premium-format customizers. Dominant competitive moves include geographic expansion through distribution partnerships and technology licensing for lightweighting simulation capabilities.
Among North American and European fabricators, Amcor plc, Berry Global Inc., and ALPLA occupy positions spanning multiple archetypes. Amcor represents the scale-driven multinational tier with broad geographic coverage. Berry Global exemplifies cost-optimized volume production anchored in food contract manufacturing. ALPLA sits within the backward-integrated controller category through its captive preform production network.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Gerresheimer AG |
| ALPLA |
| Graham Packaging Company |
| Plastipak Holdings Inc. |
| Resilux NV |
| Comar LLC |
| Alpha Packaging LLC |
| Others |
Value Network & Pricing Analysis
rPET feedstock volatility compresses converter margins on fixed-price annual contracts while simultaneously determining which suppliers capture tier-one food processor relationships and which retreat to spot-market resin sourcing. This instability widens pricing spreads between backward-integrated resin controllers and independent converters, reshaping procurement patterns across Central European packaging clusters.
Pricing Analysis
Certification level creates the primary spread across the PET jars market, with BRCGS and ISO 22000-qualified converters commanding 15-20% premiums over uncertified competitors in German retail tender cycles. Three-tier pricing structure across premium, standard, and economy levels reflects rPET content percentages, lightweighting performance, and after-sales technical support bundling. Cost compression in the economy tier is intensifying because independent converters lack captive preform supply during resin allocation periods. Private-label retail buyers exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize barrier performance and traceability compliance over unit cost.
Supply Chain Analysis
Extended payment terms from Hamburg and Rotterdam buying desks now stretch to 90-120 days, forcing mid-sized converters into supply-chain finance facilities backed by resin distributors. Manufacturing concentrates in Germany, Austria, and Belgium, with Bavarian clusters serving cross-border Polish and Czech food processors. Virgin PET and rPET flake constitute the critical input dependencies, alongside color masterbatches facing REACH SVHC reformulation delays. Single-source vulnerability runs through Austrian backward-integrated resin controllers that limit independent access during allocation periods. Distribution runs through converter-direct relationships with major grocery buying desks, bypassing traditional packaging distributors for high-volume sauce and condiment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET jars market functions as a defensive-moat arena where regulatory entrenchment protects qualified incumbents. Switching costs for food processors span 12-18 month requalification timelines that lock in converter relationships.
For Market Incumbents: Pre-empt margin erosion by securing captive rPET sourcing through bottle-to-bottle recycling partnerships before EU Packaging and Packaging Waste Regulation mandates tighten. Add ISBM capacity in Poland or Czechia to capture cross-border demand from Central European food processors expanding production. Certification investment in EU MDR assembly capabilities opens pharmaceutical serialization contracts that HDPE substitution threats cannot easily displace. For New Entrants and Emerging Players: Maharashtra and Gujarat organized retail expansion offers first-mover positioning for converters establishing local blow-molding partnerships with Indian spice and dry-food brands. The sub-100ml cosmetic jar segment in Northern Italy remains penetrable for ISBM specialists with plasma barrier coating capabilities. Go-to-market execution should anchor on FSSAI compliance bundling with snap-on lid format expertise for emerging private-label programs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-light regional specialists with rapid rPET qualification capabilities over capital-heavy volume players. Long-term viability over the next decade hinges on converter positioning ahead of mandatory recycled content thresholds. Acquisition targets should display backward integration into preform production or captive recycling streams. The signal to watch is rPET price volatility spikes that force distressed exits among resin-dependent independents.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Sourcing Infrastructure Investment | EU Packaging and Packaging Waste Regulation compliance secures access to German retail tender cycles. |
| Lightweighting Technology Licensing | Finite element analysis simulation capabilities qualify converters for reduced EPR fees in discount retail. |
| Plasma Barrier Coating Retrofit | Vacuum plasma chambers capture premium condiment contracts by eliminating EVOH interlayer costs. |
| Pharmaceutical Serialization Integration | EU MDR traceability mandates open assembly contracts for tamper-evident jars with embedded QR authentication. |
| Geographic Expansion to Indian Clusters | Maharashtra and Gujarat blow-molding partnerships capture organized retail modernization in spice segments. |
Research Methodology
Initial hypotheses were tested against primary input from blow-molding plant managers, procurement leads at Central European food processors, packaging distributor channel partners, and technical R&D directors at resin suppliers, then refined through secondary validation. Trade data from Eurostat and national customs authorities, ECHA REACH notification databases, SEC filings from publicly traded converters, and industry association reports from Plastics Europe provided triangulation anchors. Bottom-up capacity and demand modeling converged with top-down macroeconomic scenario analysis.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation dimensions spanning jar format type, closure compatibility tier, end-use application, capacity band, and regional regulatory cluster. CAGRs were derived from production volume trends, capacity utilization rates, and contract renewal pricing patterns observed across converter interviews. rPET availability constraints and corresponding price volatility formed critical forecast inputs alongside lightweighting technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by backward-integrated resin controllers to restrict independent converter access would shift outcomes substantially. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Post-Consumer Recycled Plastic Packaging Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
Asia Pacific Single-Use Plastic Packaging Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Poland Plastic Packaging Tubes Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
PE Blow Molded Products Market