
 Biopharma Cold Chain Packaging Market | 2026-2036
Biopharma Cold Chain Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Biopharma Cold Chain Packaging Market Outlook
Specialized cold-chain engineering talent is redrawing competitive boundaries as biologics complexity outpaces conventional packaging expertise. Cryoport Systems leverages deep cryogenic capabilities to anchor its position in cell therapy logistics. Sonoco ThermoSafe sustains manufacturing scale across multi-temperature pallet and parcel solutions. va-Q-tec AG differentiates through vacuum-insulated panel technology leadership in ultra-low temperature transport.
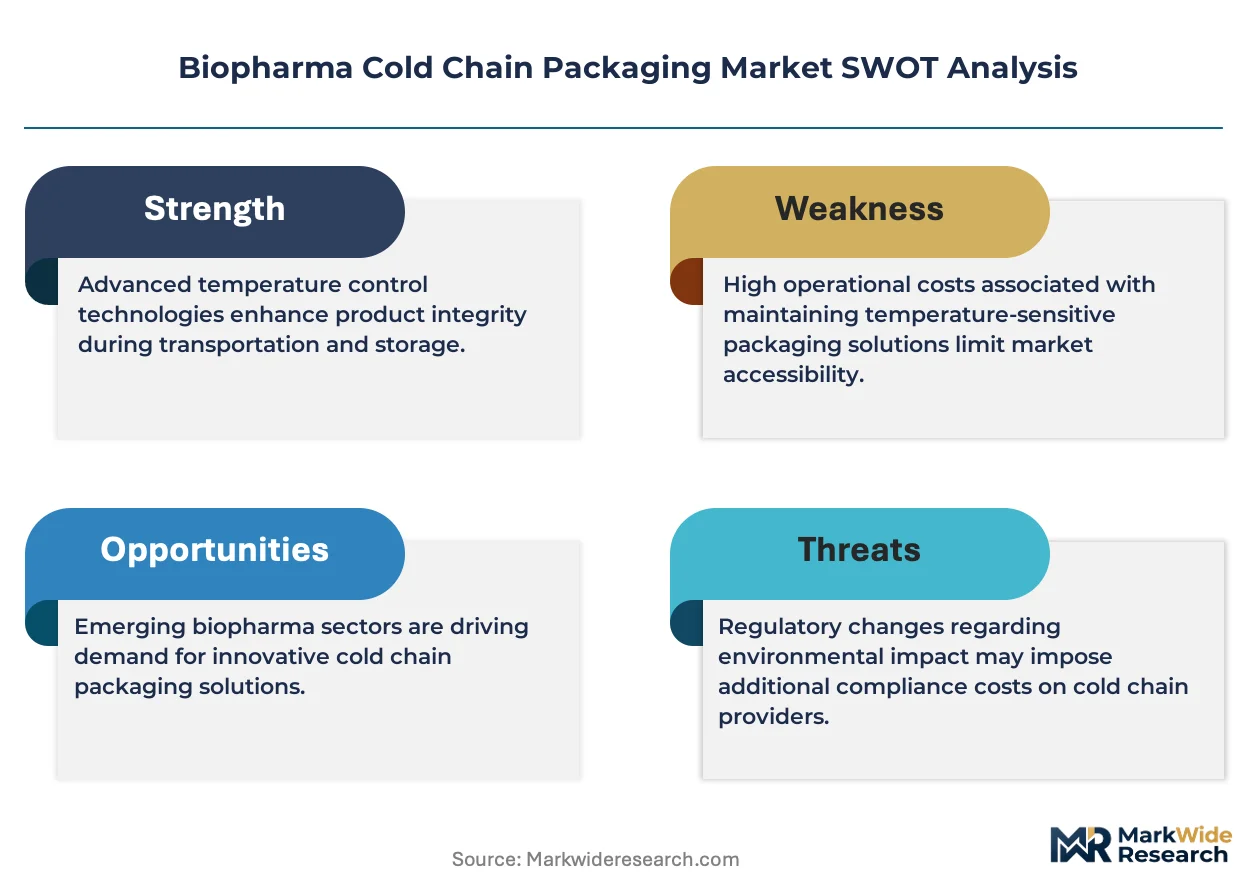
Biopharma cold chain packaging encompasses engineered thermal protection systems designed to maintain precise temperature ranges for temperature-sensitive biological products, incorporating materials such as expanded polystyrene, polyurethane foam, and phase change substances with validated performance thresholds spanning controlled room temperature through cryogenic conditions. Its primary purpose centers on preserving product efficacy, ensuring patient safety, and maintaining regulatory compliance across pharmaceutical distribution networks. Insulated boxes dominate parcel-scale shipments for biologics and vaccines, while refrigerated containers capture expanding demand for international bulk movements of gene therapies. Passive systems retain the largest installed base due to lower operational complexity, though active systems with integrated refrigeration units command premium positioning for extended-duration or high-value payloads.
FDA cold chain guidance, EU Good Distribution Practice standards, and WHO temperature-control requirements collectively mandate extensive thermal validation, real-time monitoring documentation, and risk-based qualification protocols that elevate packaging performance standards and barrier market entry. IATA CEIV Pharma certification and Parenteral Drug Association technical reports further tighten operational benchmarks for cross-border biopharmaceutical shipments. Stakeholders must weigh capital allocation between passive system scale economies and active system reliability premiums as therapy modalities fragment across temperature requirements.
Market Dynamics
Cell and gene therapy commercialization is compressing validation timelines and forcing packaging suppliers to engineer for cryogenic stability at parcel scale, reshaping capital deployment across passive and active thermal protection systems.
Growth Catalysts
- EU GDP Guidelines:Temperature monitoring mandates for biologics distribution are accelerating qualification protocols for multi-use thermal shippers across European pharmaceutical networks.
- Cell Therapy Manufacturing:Autologous and allogeneic cell production in the United States, Germany, and Japan is generating sustained demand for liquid nitrogen vapor-phase packaging at clinical trial and commercial scales.
- Vacuum-Insulated Panels:VIP technology is extending passive system performance durations, enabling lane expansion into emerging biologics production clusters without active refrigeration infrastructure.
Market Restraints
- Phase Change Material Costs:Paraffin and salt-hydrate PCM feedstock volatility is compressing margins for mid-tier passive system manufacturers dependent on petroleum-derived inputs.
- Testing Infrastructure Concentration:ISTA 7E thermal profile validation capacity clusters in the United States and Western Europe, creating qualification bottlenecks for Asia-Pacific market entrants.
- Active System Capex Barriers:Refrigerated container fleet expansion requires secured pharmaceutical lane density that regional logistics providers in Latin America and Southeast Asia cannot yet guarantee.
Strategic Opportunities
- India CDSCO Biologics Pathway:Streamlined approval frameworks for biosimilars and vaccines are attracting cold chain infrastructure investment from multinational packaging suppliers.
- Reusable Shipper Models:Reverse logistics networks for conditioned thermal packaging are opening service revenue streams distinct from single-use product sales.
- Real-Time Sensor Convergence:Integration of IoT temperature loggers with blockchain documentation is creating differentiated offerings for high-value gene therapy shipments requiring chain-of-custody verification.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Qualified thermal engineers capable of designing for minus 150 degrees Celsius transport are concentrated among a limited pool of specialists, constraining supplier expansion.
- CEIV Pharma Certification Timelines:IATA certification for pharmaceutical handling facilities requires 12-18 month validation cycles that delay regional hub activation and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopharma Cold Chain Packaging Market |
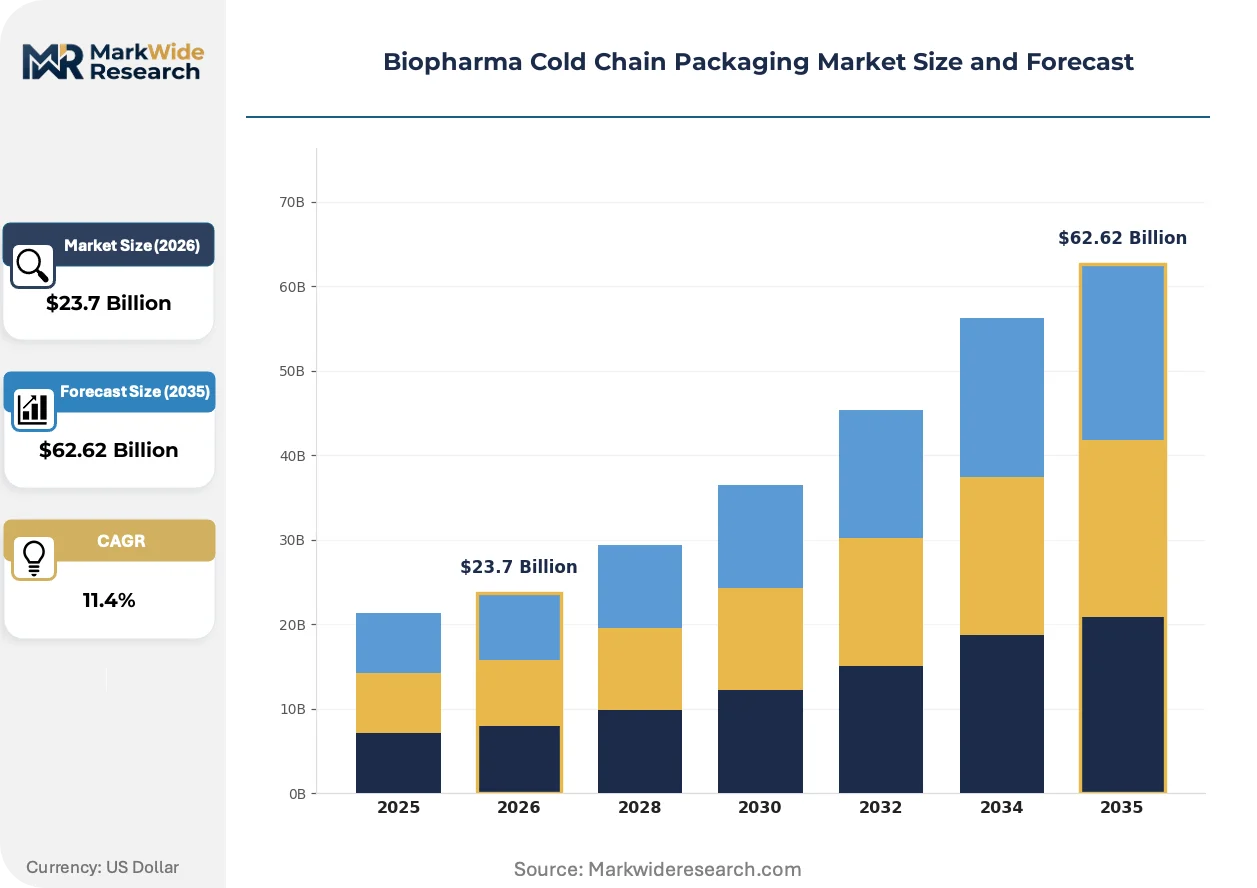
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Boxes, Refrigerated Containers, Temperature-Controlled Pallets, Soft-Sided Containers Technology: Active Systems, Passive Systems, Phase Change Materials, Gel Packs End User: Pharmaceutical Companies, Biotechnology Firms, Clinical Research Organizations, Logistics Providers Packaging Type: Rigid Packaging, Flexible Packaging, Bulk Packaging, Single-Use Packaging |
| Companies Covered | Cryoport Systems, Intelsius, Sonoco ThermoSafe, Envirotainer, SkyCell AG, Sealed Air Corporation, CSafe, va-Q-tec AG, Peli BioThermal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopharma Cold Chain Packaging Market Strategic Shifts
Digital integration and material science advances are redrawing performance boundaries between passive and active thermal protection, while regulatory documentation requirements tighten interoperability standards across pharmaceutical distribution networks.
Phase change material formulations are bifurcating into eutectic blends optimized for specific temperature setpoints rather than generic ranges. Gene therapy manufacturers are specifying custom PCM configurations for minus 80 degrees Celsius stability during extended transit. This specialization is compressing the addressable market for standardized off-the-shelf passive shippers and rewarding suppliers with in-house materials engineering capabilities.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are accelerating compressor technology transitions in active container fleets. Equipment manufacturers are deploying magnetic bearing and free-piston Stirling alternatives to maintain cooling performance under tightening environmental compliance. Pharmaceutical logistics providers operating trans-Atlantic lanes are absorbing retrofit costs ahead of 2030 phase-down deadlines to secure lane certifications.
Consolidated buying by large biopharma manufacturers is displacing fragmented procurement across regional distribution centers. Centralized category management functions are mandating unified thermal performance standards and consolidated supplier panels, compressing vendor counts. This concentration is most visible in United States and Western European markets where top-tier biologics producers have established dedicated cold chain procurement functions.
Biopharma Cold Chain Packaging Market Segmentation
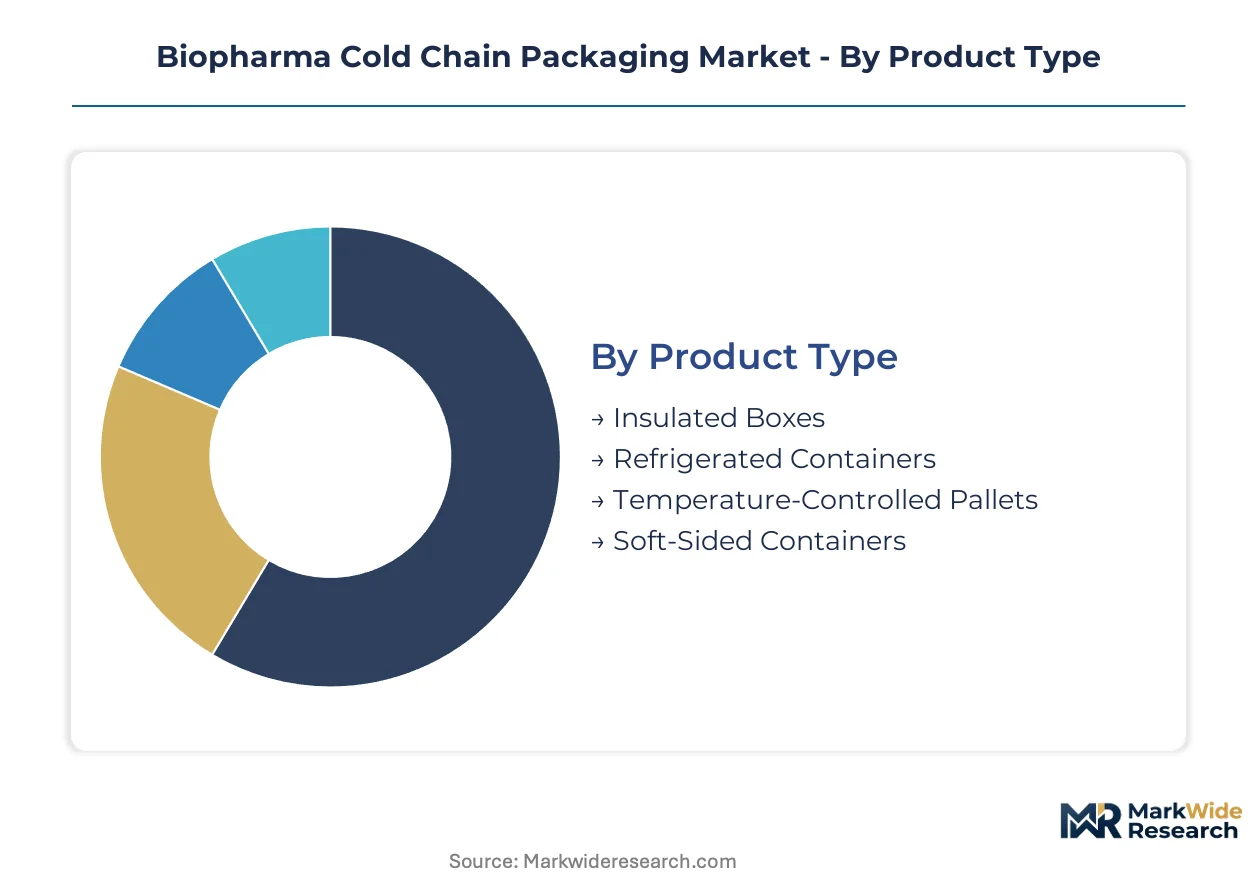
Segmentation in biopharma cold chain packaging reveals how thermal protection requirements fragment across therapy modalities, distribution scales, and regulatory jurisdictions. Each dimension carries distinct engineering specifications, qualification protocols, and supplier capability thresholds that reshape competitive positioning.
Product Type:
Substitution pressure runs highest against rigid parcel formats as flexible and pallet-scale alternatives capture lane expansion opportunities in international distribution networks.
- Insulated Boxes:Expanded polystyrene and polyurethane foam enclosures dominate parcel-scale biologics shipments, with demand concentrating in United States vaccine distribution networks where FDA cold chain validation requirements mandate proven thermal performance documentation.
- Refrigerated Containers:Active compressor-based units with integrated power systems command premium positioning for extended-duration international gene therapy movements, absorbing fleet expansion investment from logistics providers seeking CEIV Pharma certification for trans-Atlantic pharmaceutical lanes.
- Temperature-Controlled Pallets:Large-format passive or hybrid systems enable bulk shipment of temperature-sensitive intermediates and finished biologics.
- Soft-Sided Containers:Flexible insulated envelopes with gel pack integration address last-mile clinical trial material distribution.
Insulated boxes anchor the volume base while refrigerated containers gain share at the steepest rate.
Technology:
Cost tier differentiation separates capital-intensive active refrigeration from operational expenditure models favoring passive thermal mass systems.
- Active Systems:Compressor or thermoelectric cooling with real-time temperature control and data logging addresses high-value cell therapy payloads where excursion tolerance approaches zero.
- Passive Systems:Insulated enclosures with preconditioned thermal mass maintain temperature ranges without external power, capturing the largest installed base due to lower operational complexity and qualification burden across European GDP-compliant distribution networks.
- Phase Change Materials:Eutectic salt-hydrate and paraffin formulations store and release latent heat at precise setpoints, with custom minus 80 degrees Celsius configurations displacing standardized offerings in gene therapy specifications.
- Gel Packs:Water-based phase change devices provide economical short-duration protection for clinical samples and diagnostic specimens.
Passive systems retain the largest revenue share while PCM configurations expand most quickly through therapy-specific customization.
End User:
Customer type determines procurement sophistication, with consolidated pharmaceutical buyers imposing unified thermal standards that compress vendor panels.
- Pharmaceutical Companies:Large-scale biologics manufacturers with centralized category management functions mandate validated shipper performance across global distribution networks, concentrating procurement volume among qualified suppliers with multi-temperature capabilities.
- Biotechnology Firms:Cell and gene therapy developers require cryogenic stability expertise that outstrips conventional packaging engineering, driving partnership structures with specialized thermal logistics providers.
- Clinical Research Organizations:Trial material distribution demands flexible parcel-scale solutions with rapid lane qualification.
- Logistics Providers:Third-party cold chain operators seek reusable shipper fleets with reverse logistics infrastructure.
Pharmaceutical companies dominate procurement volume while biotechnology firms drive the steepest specification escalation.
Packaging Type:
Volume concentration favors single-use formats in clinical and commercial biologics distribution, though sustainability pressures and reusable service models are gaining traction.
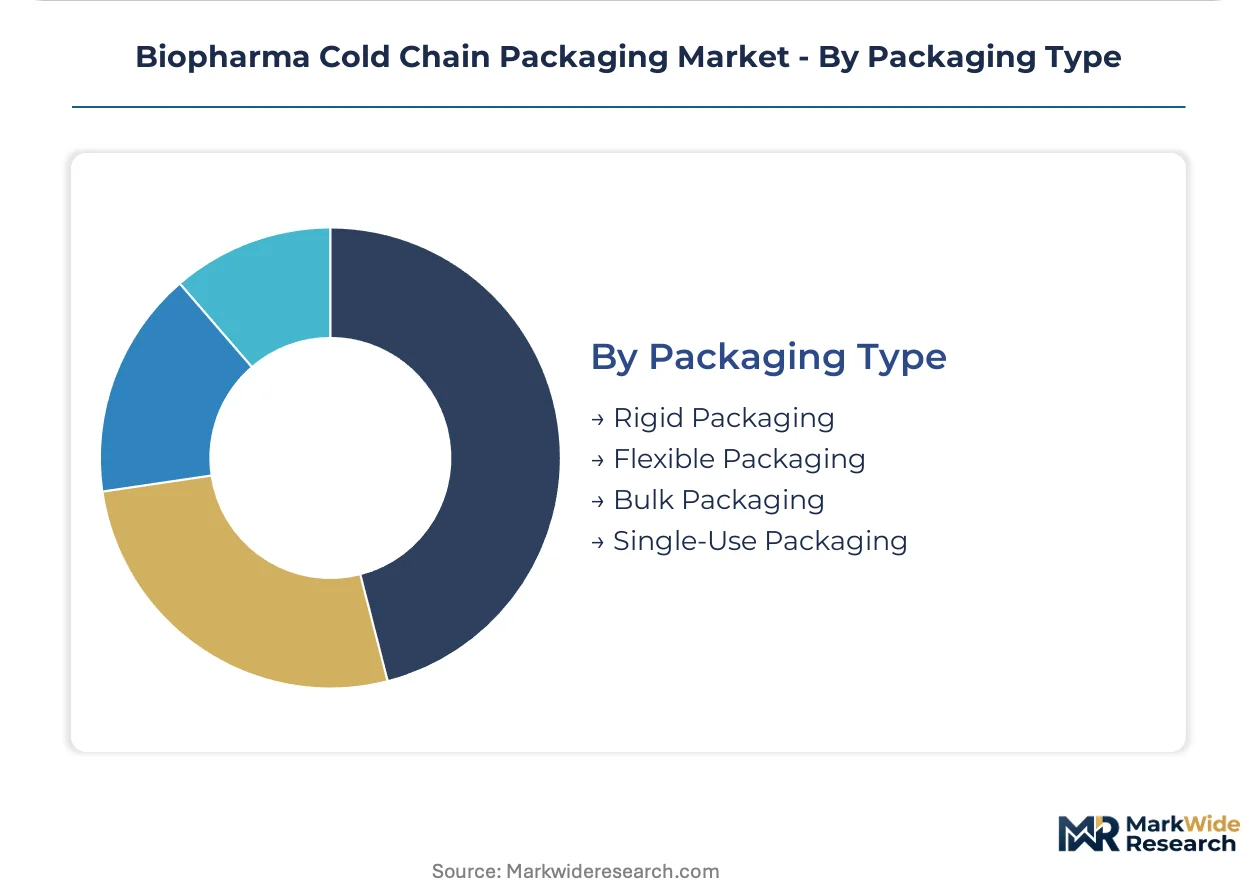
- Rigid Packaging:Molded expanded polystyrene and engineered plastic enclosures provide structural protection for vial and syringe formats, with qualification protocols aligned to ISTA 7E thermal profiles for United States and Western European distribution.
- Flexible Packaging:Insulated envelopes and pouches address cost-sensitive diagnostic specimen transport.
- Bulk Packaging:Pallet-scale thermal protection systems enable consolidated international shipments of temperature-sensitive intermediates.
- Single-Use Packaging:Disposable qualified shippers eliminate reverse logistics burden in decentralized clinical trial networks.
Single-use packaging anchors the volume base while rigid packaging gains share through qualification consolidation among top-tier biologics manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in biopharma cold chain packaging concentrates in the United States and Germany, where specialized engineering talent and regulatory validation infrastructure command premium positioning over cost-competitive manufacturing hubs in India and Southeast Asia.
United States
FDA cold chain guidance and IRA biologics manufacturing incentives are accelerating domestic packaging demand. Cell therapy production clusters in Greater Boston and the San Francisco Bay Area require cryogenic parcel solutions at commercial scale. Third-party logistics providers in Memphis and Louisville are expanding CEIV Pharma-certified facilities to capture transcontinental gene therapy distribution.
Germany
EU GDP compliance mandates and EMA centralized marketing authorization procedures elevate validation requirements for thermal shippers. Vacuum-insulated panel manufacturers in Bavaria and Baden-Württemberg are scaling production to serve continental biologics distribution networks. Frankfurt and Munich airports are consolidating pharmaceutical handling infrastructure under F-Gas Regulation retrofit timelines.
Switzerland
Swissmedic oversight of temperature-sensitive biologics and proximity to European distribution corridors sustain premium packaging demand. Basel's pharmaceutical manufacturing concentration requires validated cold chain solutions for high-value monoclonal antibody exports. Geneva and Zurich logistics hubs are specializing in clinical trial material handling with real-time monitoring capabilities.
India
CDSCO streamlined biologics pathways and PLI scheme incentives are attracting multinational packaging suppliers to establish regional manufacturing. Biosimilar production in Maharashtra and Telangana is generating demand for cost-optimized passive thermal systems. Mumbai and Hyderabad pharmaceutical clusters are developing last-mile cold chain infrastructure for vaccine distribution.
Japan
PMDA quality management requirements for regenerative medicine products mandate rigorous thermal validation protocols. Cell therapy manufacturing in Kanto and Kansai regions requires liquid nitrogen vapor-phase packaging expertise. Tokyo and Osaka logistics providers are integrating IoT temperature logging to satisfy METI supply chain traceability guidelines.
Biopharma Cold Chain Packaging Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with vacuum-insulated panel specialists and cryogenic engineering firms commanding premium positioning against scale-oriented passive system manufacturers. The vendor base separates into three tiers: integrated multinational packaging conglomerates with multi-temperature portfolios, specialized thermal logistics providers with therapy-specific expertise, and regional fabricators serving cost-sensitive diagnostic specimen markets. Consolidation pressure intensifies as large biopharma procurement functions reduce qualified supplier panels. Dominant competitive moves include strategic partnerships between packaging engineers and gene therapy developers, plus capacity expansion in cryogenic qualification infrastructure.
Among cryogenic-specialized providers, Cryoport Systems exemplifies deep ultra-low temperature capabilities, while va-Q-tec AG occupies a position in vacuum-insulated thermal protection. Sonoco ThermoSafe represents scale-driven manufacturing breadth across passive and active system categories. These three anchors illustrate how competitive positioning fragments between engineering specialization, materials technology leadership, and operational scale.
| Leading Market Players |
|---|
| Cryoport Systems |
| Intelsius |
| Sonoco ThermoSafe |
| Envirotainer |
| SkyCell AG |
| Sealed Air Corporation |
| CSafe |
| va-Q-tec AG |
| Peli BioThermal |
| Others |
Value Chain & Pricing Dynamics
Vacuum-insulated panel substitution for conventional polyurethane foam is redrawing supply geography toward Bavarian manufacturing clusters while compressing price premiums for ultra-low temperature shippers as scale economies emerge. This materials transition simultaneously elevates performance thresholds and concentrates supplier bargaining power among European fabricators with in-house VIP production.
Pricing Analysis
United States-Germany price spreads of 35-50% separate CEIV Pharma-certified active containers from GDP-compliant passive alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and volume scale. Cost compression in mid-tier passive systems intensifies because petroleum-derived PCM feedstock volatility erodes manufacturer margins. Clinical research organizations exhibit highest price sensitivity, while gene therapy developers prioritize excursion tolerance over unit economics.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific resin suppliers through Rotterdam and Hamburg port congestion are elevating landed costs for expanded polystyrene feedstock. Manufacturing concentration centers on Germany, the United States, and China for insulated box fabrication, with cryogenic engineering talent anchored in Swiss and German technical institutes. Raw material dependencies encompass paraffin PCM blends, vacuum-insulated panel cores, and compressor refrigerants subject to EU F-Gas phase-down restrictions. Single-source vulnerability runs through liquid nitrogen vapor-phase packaging engineering. Distribution runs through CEIV Pharma-certified logistics hubs in Memphis, Frankfurt, and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs formidable defensive moats in biopharma cold chain packaging, as FDA and EU GDP validation timelines create switching costs that lock in qualified suppliers across multi-year contract structures.
For Market Incumbents: Shield market position by accelerating cryogenic qualification infrastructure investment in Greater Boston and San Francisco Bay Area cell therapy clusters. Deepen backward integration into vacuum-insulated panel manufacturing to capture materials margin and secure supply continuity against Asian resin volatility. Prioritize IATA CEIV Pharma certification maintenance as emerging logistics providers threaten lane exclusivity. For New Entrants and Emerging Players: CDSCO fast-track certification for Indian biosimilar distribution offers the most penetrable entry vector, with Maharashtra and Telangana production clusters generating unmet demand for cost-optimized passive thermal systems. Target clinical trial material logistics as the white-space segment where rapid lane qualification capabilities outweigh incumbent scale advantages. Deploy reusable shipper service models with reverse logistics infrastructure to differentiate from single-use product incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed passive system manufacturers lacking cryogenic engineering depth, presenting consolidation targets for strategic buyers seeking multi-temperature portfolios. Five-to-ten year viability hinges on cell and gene therapy commercialization velocity outpacing validation capacity expansion. Monitor CEIV Pharma certification backlog durations as the inflection signal indicating capacity-constrained pricing power versus competitive commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Qualification Infrastructure Expansion | CEIV Pharma certification capacity in cell therapy clusters secures multi-year contract lock-in with gene therapy developers. |
| Vacuum-Insulated Panel Manufacturing Integration | In-house VIP production at Bavarian facilities captures margin and insulates against Asian feedstock volatility. |
| Reusable Shipper Reverse Logistics Networks | Service revenue streams from conditioned thermal packaging differentiate offerings from commoditized single-use alternatives. |
| Real-Time Sensor Blockchain Integration | IoT temperature logger convergence with chain-of-custody documentation addresses high-value gene therapy shipment requirements. |
| Indian CDSCO Certification Fast-Track Investment | Regional manufacturing in Maharashtra and Telangana captures biosimilar production demand under streamlined approval frameworks. |
Study Parameters
Initial hypotheses were tested against primary input from cold chain logistics directors, regulatory affairs specialists, pharmaceutical procurement managers, and thermal packaging engineers, then refined through secondary validation. FDA guidance documents, EU GDP compliance bulletins, IATA CEIV Pharma certification records, and WHO temperature-control technical reports anchored secondary source triangulation. Bottom-up demand modeling across therapy modalities and top-down market sizing reconstructions were cross-referenced for convergence.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within segmentation dimensions encompassing product type, temperature range, end-user category, and regional regulatory cluster. CAGRs were derived from trajectory fitting to historical qualification timelines and forward capacity expansion announcements. Modeled inputs incorporate cell therapy manufacturing facility commissioning schedules and PCM formulation patent expiration patterns.
Underlying assumptions cover sustained FDA and EU GDP enforcement intensity, with deviation risk concentrated in regulatory harmonization delays or accelerated F-Gas refrigerant phase-down timelines. Forecasts reflect these documented conditions and stated boundary parameters. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
North America Cold Chain Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
North America Passive Temperature Controlled Packaging Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Food Cold Chain Market