
 Foam Cooler Box Market | 2026-2036
Foam Cooler Box Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Cooler Box Market Analysis
Fragmentation across outdoor enthusiasts and event planners is expanding the addressable customer base beyond traditional retail channels. Igloo leverages its brand heritage and mass-market distribution to sustain volume leadership in hard coolers. YETI competes through premium positioning and direct-to-consumer channel control. RTIC differentiates by occupying the value-tier segment with comparable thermal performance at lower price points.
A foam cooler box is a thermally insulated container manufactured from expanded polystyrene, polyethylene, or polyurethane foam, designed to maintain sub-ambient temperatures for perishable goods through passive cooling with ice or gel packs. Wall thickness typically ranges from 1.5 to 3 inches, with R-values between 5 and 8 per inch depending on foam density and composition. Hard coolers command the largest revenue share due to durability and reusability, while soft coolers represent the fastest-growing product type as hikers and anglers prioritize portability. Medical storage applications carry the highest margin pools because validated cold-chain compliance commands premium pricing from pharmaceutical distributors and clinical research organizations.
The EPA regulates foam manufacturing emissions under Clean Air Act provisions, while OSHA sets workplace exposure limits for isocyanates used in polyurethane production. State-level extended producer responsibility laws in California and New York are reshaping material selection and end-of-life collection obligations. Stakeholders must monitor how FDA cold-chain guidance for biologics and evolving state bans on single-use expanded polystyrene redirect procurement specifications across food transport and medical storage segments.
Market Dynamics
Expanded polystyrene bans under REACH and state-level prohibitions are forcing material substitution toward polyethylene and polyurethane alternatives, compressing legacy supply chains while opening margin pools for compliant foam formulations.
Growth Catalysts
- REACH Phase-Down of EPS:European chemical regulations are redirecting procurement budgets toward alternative foam substrates, accelerating polyethylene cooler adoption across catering and pharmaceutical cold-chain segments.
- Outdoor Event Rebound:Catering services in Florida, Texas, and California are expanding disposable cooler purchases for festivals, weddings, and corporate gatherings, concentrating demand in sun-belt recreational corridors.
- Biologics Cold-Chain Expansion:FDA guidance on temperature-sensitive pharmaceuticals is elevating validated medical storage specifications, creating premium pricing tiers for R-value compliant containers in clinical research distribution.
Market Restraints
- Petrochemical Input Volatility:Styrene monomer and isocyanate feedstock costs fluctuate with crude oil indices, compressing gross margins for manufacturers locked into long-term distributor contracts.
- Single-Use Stigma:Environmental advocacy campaigns and municipal waste ordinances in California and New York are eroding brand equity for expanded polystyrene products regardless of technical performance.
- Closed-Cell Density Limits:Polyurethane formulations above 2.5 pounds per cubic foot face diminishing thermal returns, capping R-value improvements without radical chemistry changes.
Strategic Opportunities
- India Pharmaceutical Distribution:CDSCO cold-chain mandates for vaccines and insulin are creating first-mover advantages for insulated packaging suppliers establishing local molding operations.
- Direct-to-Consumer Channel Control:Subscription meal-kit services and specialty seafood shippers are bypassing retail intermediaries, capturing margin through branded cooler programs with embedded return logistics.
- Recycled Content Mandates:California's extended producer responsibility laws are rewarding post-consumer polyethylene incorporation, differentiating compliant suppliers in public procurement tenders.
Industry Challenges
- Thermal Validation Talent Scarcity:Medical-grade cooler manufacturers face acute shortages of ISTA-certified testing engineers capable of executing 21 CFR Part 11 compliant qualification protocols.
- Multi-Material Recycling Infrastructure:Mixed foam-laminate constructions with film barriers and adhesive layers complicate end-of-life sorting, requiring capital investment in specialized densification equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Cooler Box Market |
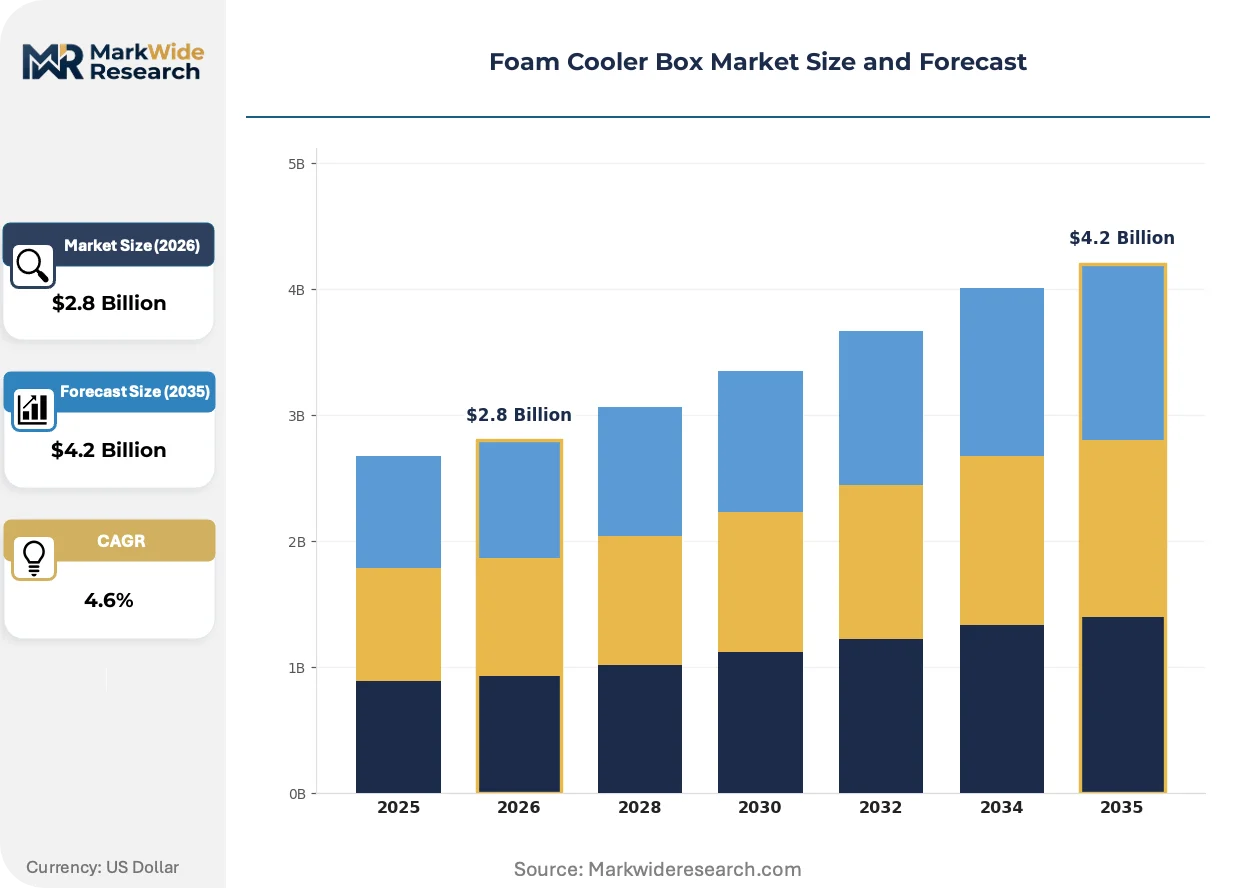
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Boxes, Soft Coolers, Hard Coolers, Ice Chests End User: Catering Services, Outdoor Enthusiasts, Retailers, Event Planners Material: Expanded Polystyrene, Polyethylene, Polyurethane, Styrofoam Application: Food Transport, Medical Storage, Research Labs, Camping |
| Companies Covered | Rubbermaid, Engel, YETI, RTIC, Grizzly, Igloo, Pelican, Sonoco ThermoSafe, Coleman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Cooler Box Market Emerging Trajectories
Material science breakthroughs and regulatory compliance automation are compressing product development cycles while fragmenting traditional channel structures across recreational and medical end-uses.
Rotational-molded polyethylene is overtaking injection-molded expanded polystyrene in hard cooler durability tiers. Marine outfitters and hunting lodges in the Gulf Coast states are specifying seamless-wall construction for saltwater and UV resistance. This shift is compressing SKU proliferation by consolidating performance claims around drop-test and thermal retention metrics rather than price-point segmentation.
REACH authorization requirements for styrene monomer are forcing European manufacturers to document full substance life cycles or reformulate entirely. The industrial consequence is a bifurcation between legacy EPS molders investing in chemical recycling partnerships and new entrants commercializing bio-based polyols. Medical storage applications are most affected, with pharmaceutical distributors now requiring ECHA-compliant material passports for all secondary packaging components.
Buyers in the catering and event planning segment are consolidating vendor relationships around full-service cold-chain programs rather than transactional cooler purchases. Distributors are responding with fleet management services encompassing pickup, sanitation, and redeployment of reusable polyethylene containers. This pattern is most visible in California's wine country and Florida's wedding corridor, where event producers face liability exposure from temperature excursions in high-value perishables.
Foam Cooler Box Market Segmentation
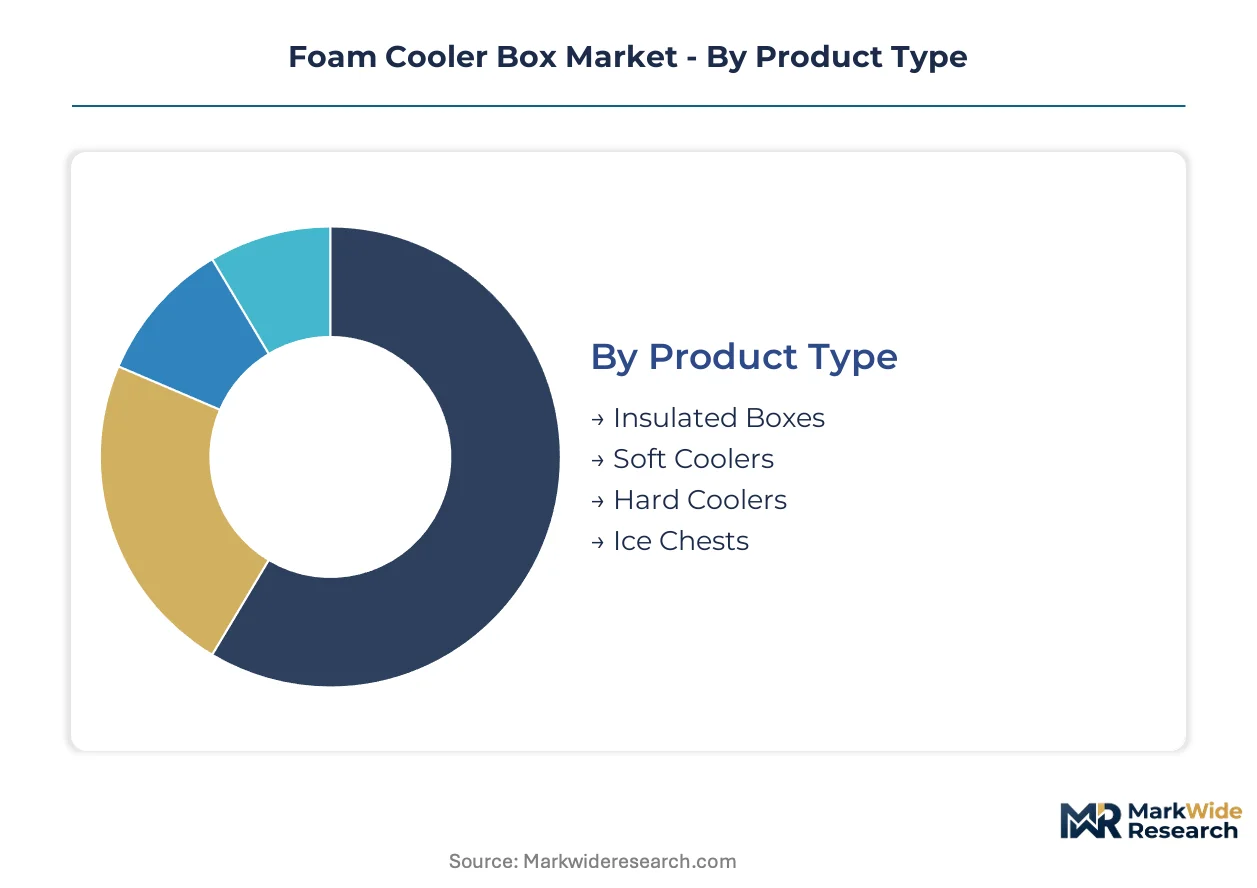
Segmentation in the Foam Cooler Box Market reveals how certification burdens, material compliance, and end-use thermal requirements fragment procurement specifications across recreational and medical channels. Understanding these divides exposes where margin pools concentrate and which product architectures command premium positioning.
Product Type:
FDA 21 CFR Part 11 validation applies exclusively to medical-grade hard coolers, while recreational soft coolers face no federal thermal certification mandates.
- Hard Coolers:Rotational-molded polyethylene construction delivers seamless-wall durability for saltwater marine environments and UV-exposed hunting lodges. Demand clusters in Florida, Texas, and California where recreational boating activity drives replacement cycles. R-values between 5 and 8 per inch satisfy weekend-length thermal retention without active cooling.
- Soft Coolers:Laminated fabric shells with closed-cell foam inserts prioritize packability for hikers and anglers. Weight-conscious outdoor enthusiasts in Pacific Northwest trail systems are displacing rigid alternatives. Portability constraints limit wall thickness to under 1.5 inches, compressing thermal duration against hard-sided equivalents.
- Insulated Boxes:Disposable expanded polystyrene containers dominate catering procurement for single-event cold-chain coverage. REACH phase-downs are redirecting volume toward polyethylene alternatives in European pharmaceutical distribution.
- Ice Chests:Legacy injection-molded designs retain price-sensitive retail placement. Mass-market distributors in suburban big-box channels sustain volume through seasonal promotional cycles.
Hard Coolers sits at the top of the volume ranking, with Soft Coolers climbing the fastest.
End User:
Cost tier stratification separates validated medical procurement from transactional recreational purchasing, with liability exposure driving specification divergence.
- Catering Services:Full-service cold-chain programs with fleet management and sanitation protocols are consolidating vendor relationships. California wine country and Florida wedding corridor event producers face temperature excursion liability on high-value perishables.
- Outdoor Enthusiasts:Direct-to-consumer subscription meal-kit services and specialty seafood shippers are bypassing retail intermediaries. Embedded return logistics in branded cooler programs capture margin through repeat engagement.
- Retailers:Mass-market distribution sustains volume leadership through seasonal inventory turns. Big-box chains concentrate shelf space around heritage brand recognition and price-point segmentation.
- Event Planners:Disposable cooler purchases rebound with outdoor festival and corporate gathering recovery. Sun-belt recreational corridors in Florida, Texas, and California concentrate procurement timing around spring and fall event seasons.
Catering Services commands the steepest margin expansion, with Outdoor Enthusiasts gaining share fastest through channel disintermediation.
Material:
Supply concentration in petrochemical feedstocks exposes each substrate to distinct regulatory headwinds and recycling infrastructure gaps.
- Expanded Polystyrene:Lightweight cellular structure delivers cost-efficient thermal insulation for single-use applications. State-level bans in California and New York and REACH authorization requirements in Europe are eroding addressable market scope regardless of technical performance.
- Polyethylene:Rotational-molded durability satisfies marine and UV exposure requirements for reusable hard coolers. California extended producer responsibility laws reward post-consumer recycled content incorporation in public procurement tenders.
- Polyurethane:Superior R-value density supports medical-grade cold-chain validation for biologics transport. Isocyanate feedstock volatility and OSHA workplace exposure limits compress formulation flexibility above 2.5 pounds per cubic foot.
- Styrofoam:Brand-name expanded polystyrene faces intensifying environmental advocacy campaigns and municipal waste ordinances. Technical equivalence to generic EPS offers no differentiation against regulatory displacement.
Polyethylene leads current volume rankings, with Polyurethane expanding most quickly in pharmaceutical-validated segments.
Application:
Margin concentration correlates directly with thermal validation burden, separating commodity food transport from compliance-intensive medical storage.
- Medical Storage:FDA cold-chain guidance for temperature-sensitive biologics mandates ISTA-certified testing and 21 CFR Part 11 compliant qualification protocols. Acute scarcity of qualified validation engineers creates supply bottlenecks for clinical research organization distribution.
- Food Transport:Catering and meal-kit services prioritize cost-efficient passive cooling without federal thermal mandates. Liability exposure on high-value perishables is driving consolidation around full-service fleet management programs.
- Research Labs:Validated specifications overlap with pharmaceutical requirements but at lower volume scale. Academic procurement cycles introduce payment term and specification variability.
- Camping:Recreational portability demands dominate over thermal duration optimization. Hiker and angler preference for packable soft coolers is displacing rigid alternatives in trail-accessible retail channels.
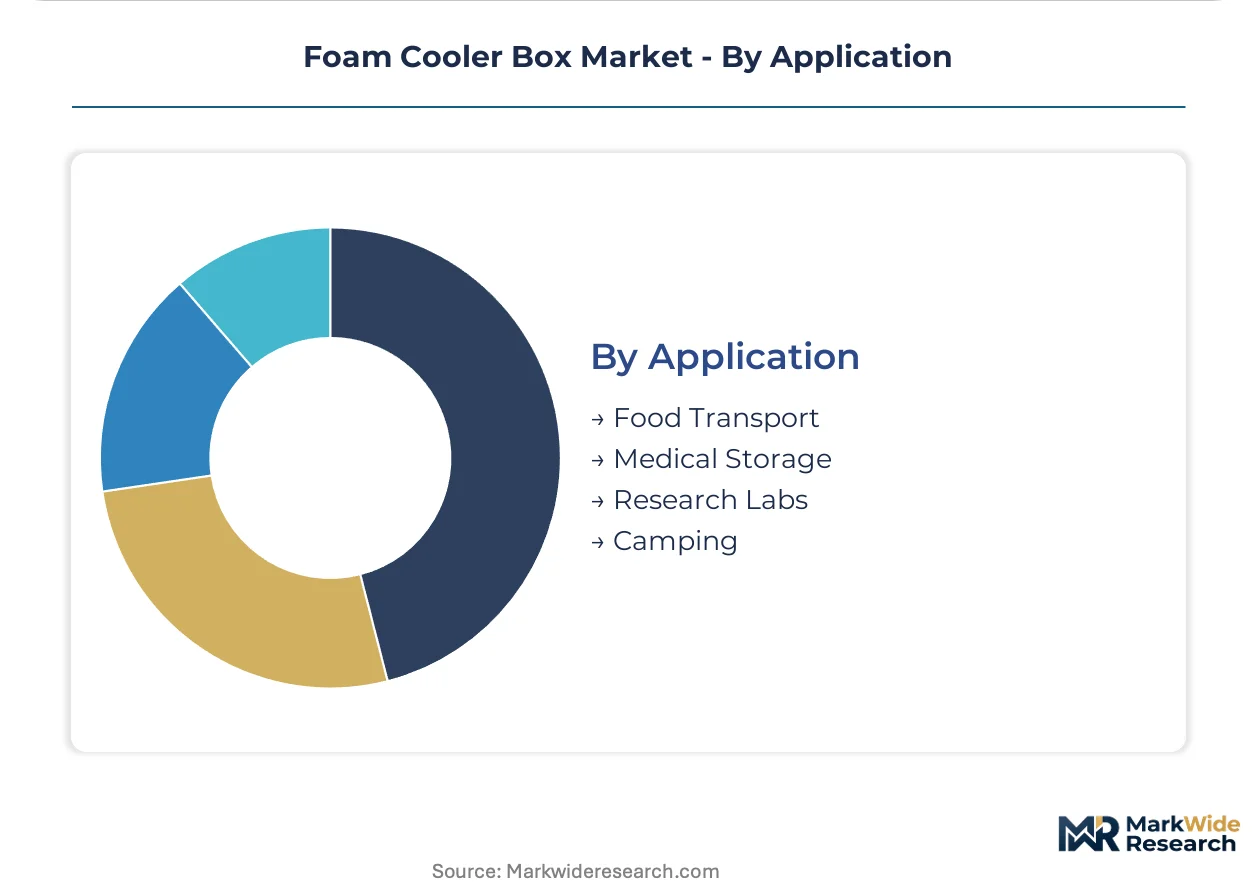
Food Transport holds top volume position, with Medical Storage ascending fastest on premium pricing tiers for cold-chain compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates recreational cooler demand around coastal boating corridors, while Germany anchors European pharmaceutical cold-chain procurement under REACH material mandates.
United States
Florida, Texas, and California generate concentrated demand from recreational boating and camping activity clusters. State-level extended producer responsibility laws in California and New York reshape material selection and end-of-life collection obligations for manufacturers. The Gulf Coast marine outfitter market specifies rotational-molded polyethylene construction for saltwater durability.
Germany
Pharmaceutical distributors drive specification-grade procurement for validated medical storage applications. ECHA REACH authorization requirements for styrene monomer force manufacturers to document full substance life cycles or reformulate entirely. The Rhine-Ruhr industrial corridor hosts chemical recycling partnerships between legacy EPS molders and compliant foam innovators.
India
CDSCO cold-chain mandates for vaccines and insulin create first-mover opportunities for insulated packaging suppliers establishing local molding operations. The national pharmaceutical regulator enforces temperature-sensitive distribution standards across generic drug supply chains. Maharashtra and Gujarat pharmaceutical clusters demand ISTA-certified qualification protocols for clinical trial logistics.
China
Domestic catering services and seafood export channels expand polyethylene cooler adoption as REACH-equivalent environmental standards phase down expanded polystyrene alternatives. The Ministry of Ecology and Environment implements dual carbon goals affecting petrochemical feedstock sourcing. Yangtze River Delta manufacturing hubs supply rotational-molded durability tiers for marine and UV-exposed applications.
Brazil
ANVISA pharmaceutical distribution regulations elevate cold-chain compliance requirements for biologics transport across tropical climate corridors. Outdoor event catering rebounds in São Paulo and Rio de Janeiro wedding markets, driving disposable cooler procurement. The Southeast industrial region concentrates rotational molding capacity for reusable polyethylene container programs.
Foam Cooler Box Market Vendor Landscape
United States producers anchor one tier of mass-market heritage brands; European specialists hold validated medical-grade certification capabilities. The vendor base splits between consolidated mass-market distribution and fragmented premium-tier direct-to-consumer channels. Three strategic archetypes dominate: heritage volume leaders, premium positioning specialists, and value-tier performance competitors. Capacity expansion in rotational-molded polyethylene and strategic partnerships for chemical recycling infrastructure represent the dominant competitive moves.
Within the heritage volume tier, Igloo Products Corp. and Coleman Company, Inc. exemplify mass-market distribution scale, while YETI Holdings, Inc. occupies premium positioning through direct-to-consumer channel control. Rubbermaid represents diversified industrial conglomerate participation. These four entities collectively illustrate the competitive spectrum from price-point segmentation to validated thermal performance certification.
| Leading Market Players |
|---|
| Rubbermaid |
| Engel |
| YETI |
| RTIC |
| Grizzly |
| Igloo |
| Pelican |
| Sonoco ThermoSafe |
| Coleman |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical distributors and clinical research organizations concentrate procurement around validated cold-chain specifications, anchoring premium pricing tiers to FDA 21 CFR Part 11 compliance and ISTA-certified thermal qualification protocols rather than commodity resin costs.
Pricing Analysis
Capacity additions in rotational-molded polyethylene across the Yangtze River Delta and Gulf Coast states are reshaping price floors for reusable hard coolers, compressing margins on legacy injection-molded designs. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade polyurethane containers with full validation documentation from recreational polyethylene units and disposable expanded polystyrene alternatives. Cost compression in the expanded polystyrene tier intensifies because REACH authorization requirements and state-level bans erode addressable volume regardless of technical performance. Event planners and catering services exhibit the highest price sensitivity, while pharmaceutical distributors accept substantial premiums for cold-chain compliance documentation.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical distributors and marine outfitters mandate multi-supplier qualification for rotational-molded polyethylene and polyurethane foam substrates, preventing single-source dependence despite concentration advantages. Manufacturing capacity clusters in China, the United States, and Germany, with petrochemical feedstock supply drawing from styrene monomer and isocyanate production corridors tied to crude oil indices. Single-source vulnerability in isocyanate feedstock channels exposes polyurethane formulators to OSHA workplace exposure limit compliance costs and raw material volatility. Distribution runs through mass-market retail chains for recreational segments and direct-to-consumer channels for subscription meal-kit services, with specialized medical distributors handling validated cold-chain procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Material substitution economics between expanded polystyrene and polyethylene alternatives create geographic-arbitrage opportunities, as European REACH compliance costs exceed North American state-level ban implementation expenses by a substantial margin.
For Market Incumbents: Extend rotational-molding capacity in saltwater-exposed coastal corridors to capture marine outfitter specification upgrades, while consolidating chemical recycling partnerships to defend against bio-based polyol entrants. Backward integration into post-consumer polyethylene collection networks addresses California extended producer responsibility compliance and secures recycled content mandates for public procurement tenders. For New Entrants and Emerging Players: Specialty seafood shippers and subscription meal-kit services represent the most penetrable channel partners, bypassing retail intermediaries through embedded return logistics programs. Target India's Maharashtra and Gujarat pharmaceutical clusters with local molding operations to capture CDSCO cold-chain mandate first-mover positioning, leveraging ISTA-certified qualification protocols as the primary go-to-market credential. For Investors and Strategic Acquirers: Packaging conglomerates with existing cold-chain infrastructure are the most active acquirer in this space, seeking validated thermal performance capabilities to complement commodity food transport portfolios. Mid-cap rotational molders with FDA-compliant medical-grade certifications represent the optimal acquisition target archetype over the coming decade. Watch for CDSCO enforcement acceleration in India as the inflection indicator signaling premium pricing tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Rotational-Molding Capacity Expansion | Gulf Coast marine outfitters specify seamless-wall construction for saltwater durability and UV resistance. |
| Chemical Recycling Partnership | Legacy EPS molders in Germany's Rhine-Ruhr corridor partner with compliant foam innovators under REACH mandates. |
| Direct-to-Consumer Channel Launch | Subscription meal-kit services bypass retail intermediaries through branded cooler programs with embedded return logistics. |
| Medical-Grade Certification Investment | FDA 21 CFR Part 11 validation commands premium pricing from pharmaceutical distributors and clinical research organizations. |
| Post-Consumer Recycled Content Integration | California extended producer responsibility laws reward polyethylene incorporation in public procurement tenders. |
Methodological Framework
Multiple input streams — primary interviews with rotational molding plant managers, pharmaceutical procurement leads, and catering fleet operators, alongside customs records, EPA emissions filings, and SEC 10-K disclosures — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from ECHA REACH authorization databases, FDA cold-chain guidance documents, and state-level extended producer responsibility legislation. Primary fieldwork encompassed technical R&D directors at foam formulation specialists and channel sales heads at marine outfitter distribution networks.
Data-stream reconciliation across the projection horizon applied analytical frameworks modeling product type, material substrate, end-user vertical, and regional regulatory cluster dimensions. CAGRs were derived through segment-level volume build-ups and value-per-unit trajectories, with cross-referencing to petrochemical feedstock cost indices and cold-chain compliance premium structures. Forecast inputs incorporated CDSCO mandate enforcement timelines, REACH phase-down schedules, and outdoor event recovery patterns across sun-belt recreational corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to isocyanate feedstock volatility and accelerated expanded polystyrene regulatory displacement. Deviation in FDA biologics cold-chain guidance stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Cryo Box Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Cryogenic Boxes Market