
 UAE Corrugated Board Packaging Market | 2026-2036
UAE Corrugated Board Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Corrugated Board Packaging Market Analytics
MOHAP's updated packaging safety regulations is shifting compliance costs upward for new entrants while favoring established domestic manufacturers. Arabian Packaging Co. LLC leverages integrated box plants across the northern emirates to sustain cost advantages. World Pack Industries LLC anchors its position through specialty grades for pharmaceutical cold chains. Universal Carton Industries LLC competes on rapid custom turnaround for e-commerce fulfillment centers.
UAE corrugated board packaging consists of fluted paperboard sheets laminated between flat linerboards, typically constructed from recycled Kraft paper with burst strengths ranging from 150 to 400 psi depending on wall configuration. The material functions primarily as protective secondary packaging for transit, stacking, and retail display across manufacturing and distribution networks. Single-wall and double-wall grades dominate volume throughput due to their cost-efficiency in food and beverage logistics, while die-cut formats capture expanding margin pools from electronics and healthcare clients requiring precision-fit protection. Custom packaging types outpace standard formats in value contribution as brand owners demand differentiated unboxing experiences and shelf-ready structures.
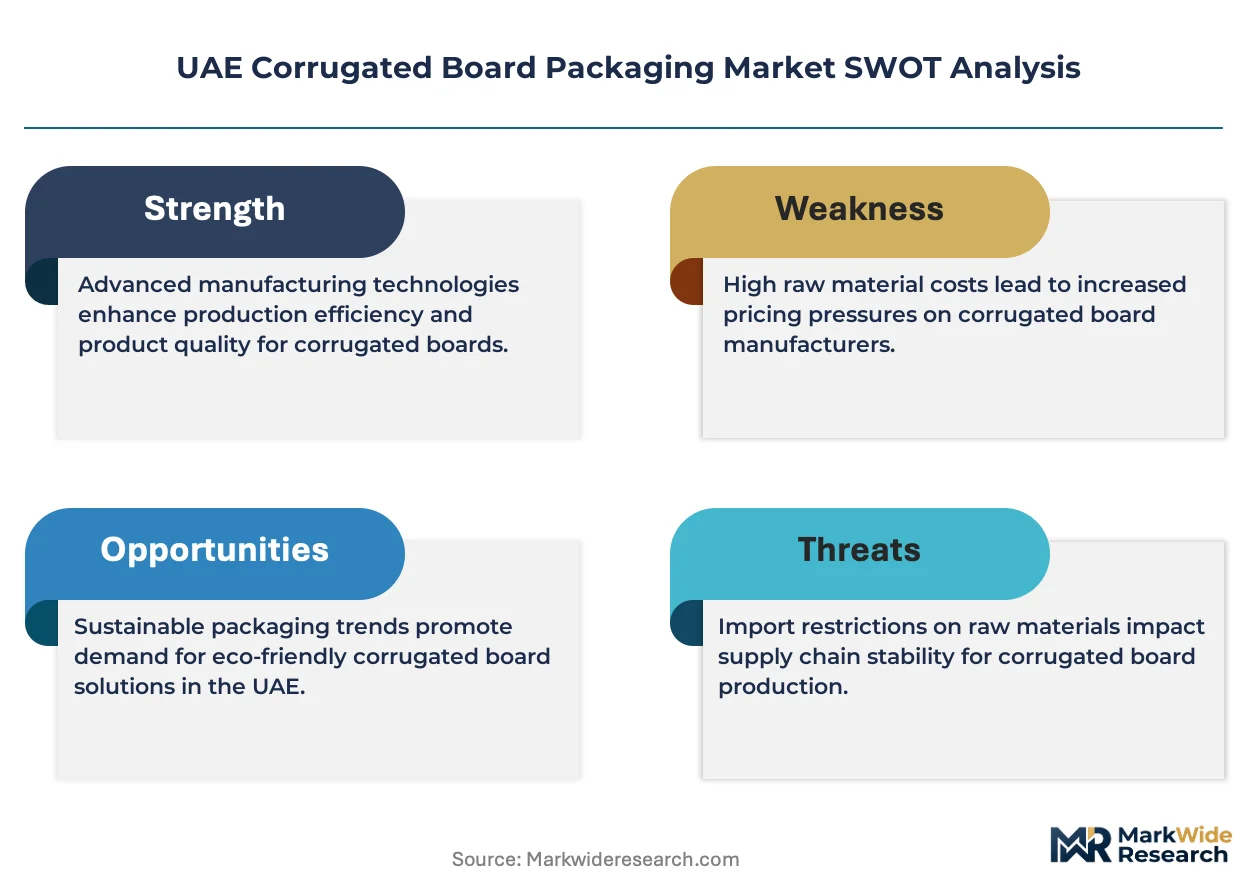
MOHAP enforces material contact safety standards for food-grade corrugated, while the UAE's Emirates Authority for Standardization and Metrology mandates fiber sourcing disclosures and recyclability thresholds under its sustainability labeling framework. These requirements filter import eligibility and elevate domestic recycling infrastructure investment. Stakeholders must monitor how Abu Dhabi's industrial policy revisions and Dubai's circular economy mandates reshape substrate specifications and supplier qualification timelines.
Market Dynamics
MOHAP's packaging safety mandates are compressing supplier qualification timelines while elevating material traceability requirements across UAE corrugated supply chains.
Growth Catalysts
- Food-grade safety standards:MOHAP's material contact regulations mandate fiber sourcing disclosures for temperature-sensitive supply chains. Cold-chain logistics providers are expanding corrugated procurement for pharmaceutical and fresh produce transit.
- Jebel Ali industrial corridor concentration:Dubai's logistics hub anchors manufacturing and distribution networks for regional export markets. E-commerce fulfillment centers cluster within this corridor, driving demand for rapid-turnaround custom formats.
- Recyclability labeling framework:Emirates Authority for Standardization and Metrology mandates fiber content thresholds and sustainability disclosures. Domestic recycling infrastructure investment is accelerating to meet compliance requirements.
Market Restraints
- Recycled Kraft paper cost volatility:Input fiber prices fluctuate with global pulp markets and regional recycling collection rates. Cost pass-through mechanisms lag price swings by one to two procurement cycles.
- Sharjah packaging cluster supply concentration:Northern emirates host limited integrated box plant capacity. Freight costs from this concentration point erode margins for southern emirate deliveries.
- Plastic crate substitution in reusable loops:Beverage distributors and automotive parts suppliers are piloting returnable plastic packaging for closed-loop logistics. Corrugated remains disadvantaged on trip-cost economics beyond single-use applications.
Strategic Opportunities
- Abu Dhabi industrial policy revisions:Substrate specification incentives for circular economy compliance are creating qualification windows for domestic manufacturers. Local content requirements favor emirate-based production.
- Die-cut precision formats for electronics:Smartphone and semiconductor distributors require anti-static, precision-fit corrugated structures. This application commands margin premiums over standard RSC boxes.
- Digital print convergence with structural design:Variable-data printing integrated with parametric box design enables batch-size-one production. Brand owners in cosmetics and premium food are adopting this for limited-edition releases.
Industry Challenges
- Structural design software talent scarcity:Parametric modeling and finite-element analysis for protective packaging require specialized engineering skills. UAE technical institutes lack dedicated corrugated simulation curricula.
- MOHAP certification timeline compression:New material approvals for food-contact applications now require accelerated testing protocols. Laboratory capacity constraints extend qualification periods beyond commercial launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Corrugated Board Packaging Market |
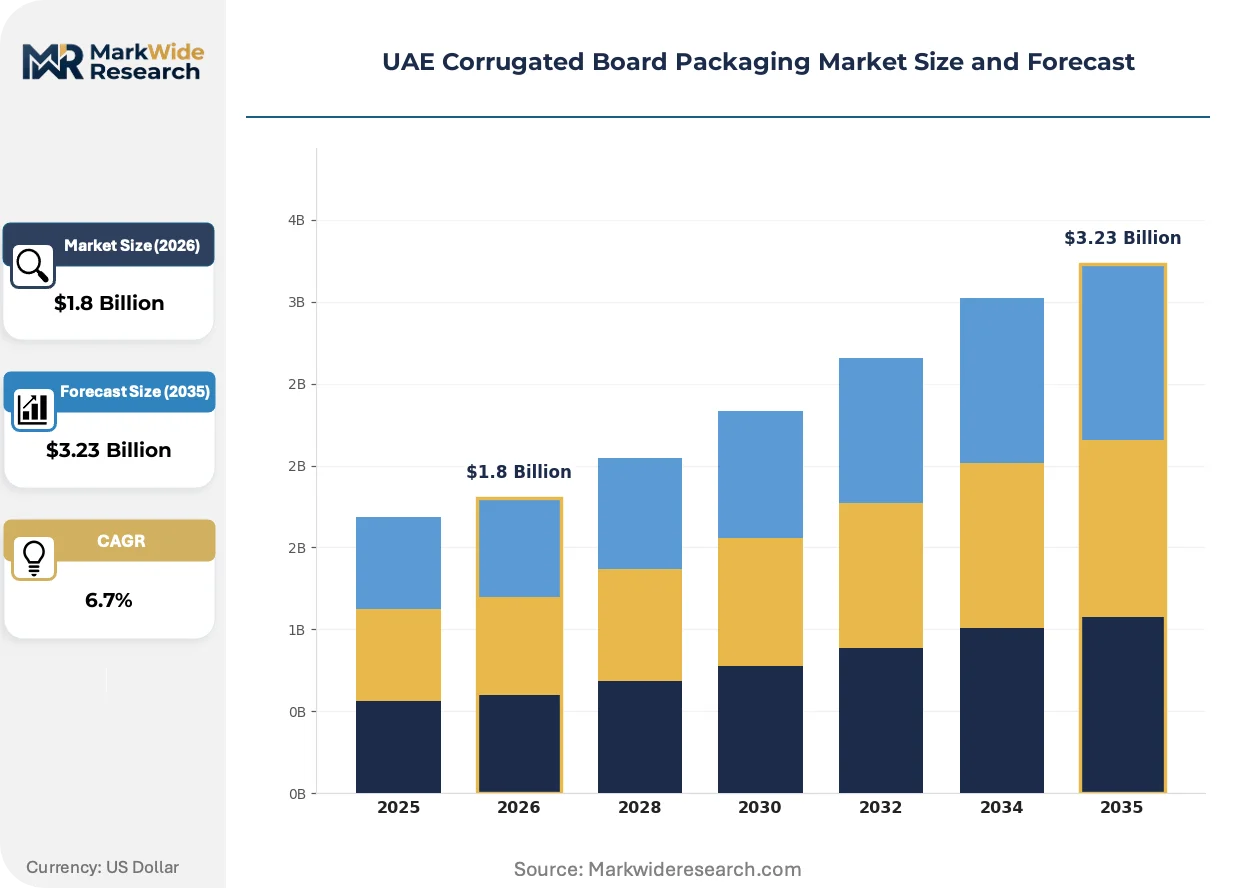
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-wall, Double-wall, Triple-wall, Die-cut End User: Food & Beverage, Electronics, Textile, Healthcare Packaging Type: Retail, Bulk, Standard, Custom Distribution Channel: Direct Sales, Online, Distributors, Retailers |
| Companies Covered | World Pack Industries LLC, M.A.H.Y. Khoory and Co., Arabian Packaging Co. LLC, Tarboosh Packaging Co. LLC, Green Packaging Boxes IND. LLC, Queenex Corrugated Carton Factory, Universal Carton Industries LLC, Unipack Containers & Carton Products LLC, Falcon Pack, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Corrugated Board Packaging Market Evolving Landscape
Digital production technologies and circular economy mandates are restructuring how corrugated specifications are developed, approved, and manufactured across UAE supply chains.
Water-based barrier coatings are replacing polyethylene-laminated structures in food-contact applications. Dairy and meat processors are adopting these formats to meet recyclability targets without sacrificing moisture resistance. The technology is absorbing capital allocation that previously flowed to conventional plastic extrusion lines.
MOHAP's updated packaging safety regulations mandate blockchain-traceable material documentation for pharmaceutical and food-grade corrugated. Manufacturers must integrate supply chain visibility systems from fiber sourcing through finished box delivery. Small and mid-sized converters face compliance cost barriers that favor integrated producers with captive recycling operations.
Brand owners are consolidating corrugated specifications around shelf-ready display formats that eliminate secondary handling at retail. Cosmetics and confectionery distributors in Dubai's duty-free channels are driving this specification shift. Procurement teams now evaluate total landed cost including retail labor rather than unit box pricing alone.
UAE Corrugated Board Packaging Market Segmentation
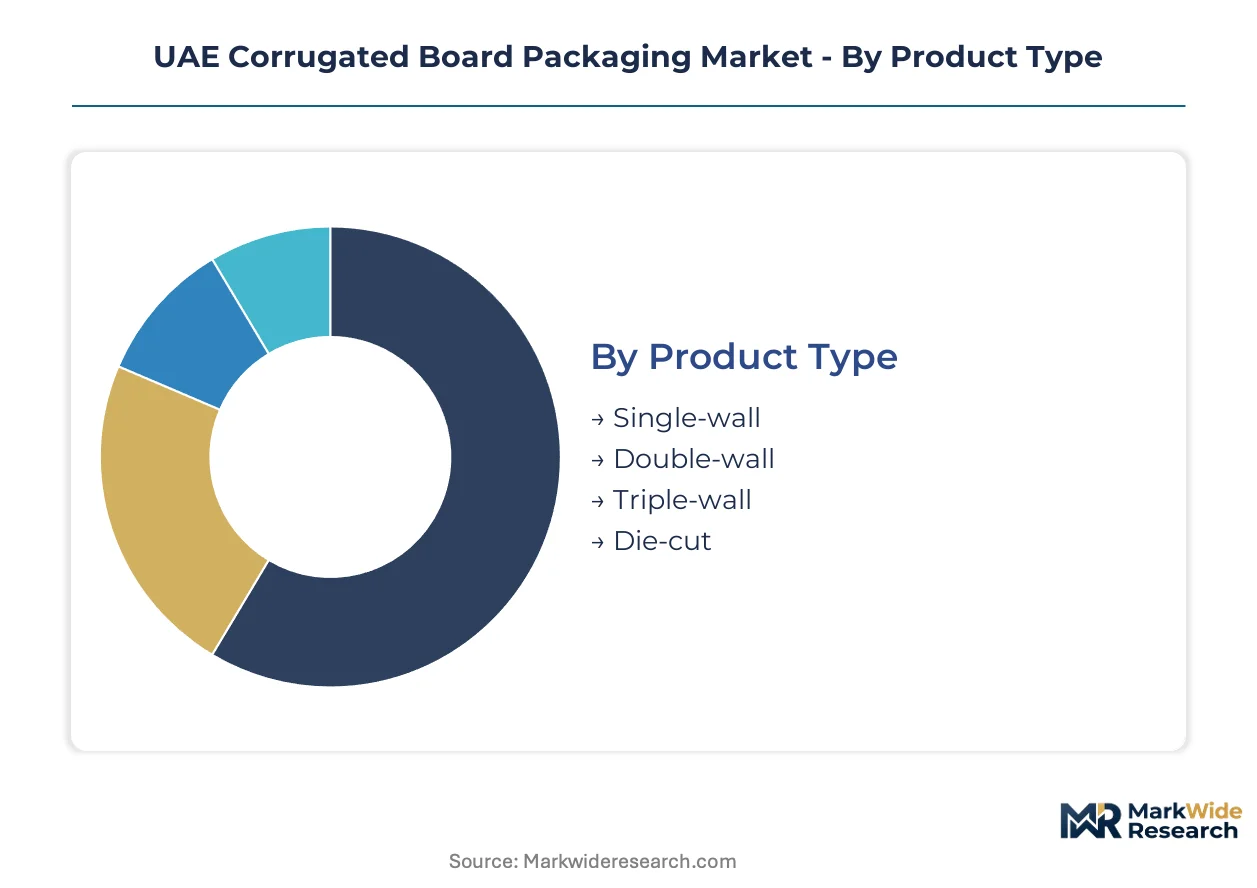
Corrugated board packaging in the UAE fragments across structural grades, end-use requirements, and fulfillment formats. Each dimension shapes procurement priorities differently—material engineers optimize wall configurations, brand owners specify unboxing experiences, and logistics operators balance unit economics with damage rates.
Product Type:
Single-wall and double-wall configurations dominate tonnage throughput, while specialty grades capture margin premiums in temperature-sensitive applications.
- Single-wall:One fluted medium between two linerboards delivers 150-200 psi burst strength for lightweight consumer goods. Dubai's e-commerce fulfillment centers specify this grade for parcel shipments under 15 kilograms, prioritizing freight cube efficiency over crush resistance.
- Double-wall:Two fluted layers laminated between three linerboards achieve 275-350 psi burst strength. Food and beverage distributors across the Jebel Ali corridor deploy this grade for palletized export shipments to GCC markets, where stacking height and humidity exposure demand structural redundancy.
- Triple-wall:Heavy-duty industrial applications requiring 400+ psi burst strength utilize this seven-ply construction for machinery and automotive parts transit.
- Die-cut:Precision-cut formats with integrated locking tabs and display headers serve electronics and cosmetics brands seeking shelf-ready presentation without secondary assembly.
Today's leader: Double-wall. Tomorrow's challenger: Die-cut.
End User:
Food and beverage procurement anchors volume demand, while healthcare specifications are tightening material traceability requirements fastest.
- Food & Beverage:Dairy processors, meat packers, and ambient goods distributors consume standard RSC boxes and moisture-resistant formats. MOHAP's material contact mandates now require blockchain-traceable fiber documentation for temperature-sensitive supply chains, compressing supplier qualification timelines.
- Healthcare:Pharmaceutical cold-chain logistics providers specify anti-static, precision-fit corrugated with integrated temperature indicators. World Pack Industries LLC anchors this segment through specialty grades meeting MOHAP's accelerated testing protocols for sterile transit.
- Electronics:Smartphone and semiconductor distributors require die-cut structures with ESD coatings and drop-test certification for high-value device protection.
- Textile:Garment exporters utilize lightweight single-wall formats with printed brand identifiers for retail-ready presentation in European and Asian destination markets.
Healthcare specifications are climbing fastest as MOHAP tightens pharmaceutical packaging safety mandates.
Packaging Type:
Standard formats move volume through procurement efficiency, while custom specifications capture expanding margin pools from brand differentiation investments.
- Custom:Parametric-designed boxes with variable-data printing enable batch-size-one production for limited-edition cosmetics and premium food releases. Universal Carton Industries LLC competes on rapid turnaround for these specifications, compressing design-to-delivery cycles to under 72 hours.
- Retail:Shelf-ready display formats with tear-away headers and integrated stacking features eliminate secondary handling at point-of-sale. Dubai's duty-free channels are consolidating procurement around this specification class.
- Standard:Regular slotted containers and half-slotted containers serve bulk commodity movements where unit cost minimization dominates supplier selection.
- Bulk:Gaylord boxes and pallet-sized containers handle intermediate raw material shipments for manufacturing inputs across Sharjah's industrial zones.
Custom formats gain share as brand owners prioritize unboxing experience over unit box pricing.
Distribution Channel:
Direct sales relationships dominate contract value, while distributor networks extend geographic reach into northern emirate manufacturing clusters.
- Direct Sales:Integrated box plants with captive recycling operations contract directly with multinational food and beverage manufacturers. Arabian Packaging Co. LLC leverages this channel across its northern emirates facilities to sustain cost advantages through volume commitments.
- Distributors:Independent packaging resellers aggregate demand from small and mid-sized manufacturers lacking procurement scale for mill-direct relationships. Sharjah's packaging cluster hosts the densest distributor concentration, though freight costs erode margins for southern emirate deliveries.
- Online:Digital procurement platforms enable rapid specification quoting and sample ordering for e-commerce fulfillment centers requiring just-in-time inventory management.
- Retailers:Big-box packaging suppliers serve immediate-need purchases for small businesses and seasonal volume spikes.
Direct sales lock in volume stability. Distributor networks are expanding fastest as mid-market manufacturers digitize procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and production specialists cluster along the UAE's industrial corridors, anchoring corrugated manufacturing capacity in proximity to Dubai's logistics infrastructure and Sharjah's converting facilities.
Dubai
E-commerce fulfillment centers and pharmaceutical distributors drive demand for rapid-turnaround custom formats. Dubai's Department of Economic Development enforces circular economy mandates that reshape substrate specifications for retail-ready packaging. Jebel Ali industrial corridor hosts dense concentrations of integrated box plants serving GCC export markets.
Abu Dhabi
Food and beverage manufacturers expanding cold-chain operations require temperature-resistant corrugated structures for dairy and meat transit. Abu Dhabi's industrial policy revisions incentivize local content requirements and circular economy compliance. Khalifa Industrial Zone attracts domestic manufacturers qualifying for emirate-based production incentives.
Sharjah
Mid-sized converters and distributor networks aggregate demand from northern emirate manufacturing clusters. Sharjah's packaging cluster concentrates limited integrated box plant capacity, creating freight cost disadvantages for southern emirate deliveries. Hamriyah Free Zone hosts recycling infrastructure investment accelerating to meet Emirates Authority for Standardization and Metrology fiber content thresholds.
Northern Emirates
Ras Al Khaimah and Fujairah manufacturing zones generate demand for bulk commodity packaging serving construction materials and industrial inputs. Federal-level sustainability labeling frameworks apply uniformly across these emirates. Saif Zone and Fujairah Free Zone host logistics operators consolidating procurement for regional distribution networks.
UAE Corrugated Board Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the UAE corrugated landscape, creating a tiered structure where scale-driven integrated producers hold cost advantages over niche converters. Market concentration favors established domestic manufacturers with captive recycling operations and multi-emirate facility networks. Two strategic archetypes dominate: vertically integrated box plants with fiber-to-finished-box control, and agile custom specialists competing on design-to-delivery speed. Capacity expansion and qualification timeline compression represent the dominant competitive moves as MOHAP mandates tighten material traceability requirements.
Among UAE-based integrated producers, Arabian Packaging Co. LLC and Universal Carton Industries LLC exemplify contrasting strategic positions within the competitive structure. World Pack Industries LLC occupies a specialized tier serving pharmaceutical cold-chain logistics with compliance-intensive formats. These three entities represent the spectrum from scale-driven manufacturing to specification-intensive custom production that characterizes the market's competitive segmentation.
| Leading Market Players |
|---|
| World Pack Industries LLC |
| M.A.H.Y. Khoory and Co. |
| Arabian Packaging Co. LLC |
| Tarboosh Packaging Co. LLC |
| Green Packaging Boxes IND. LLC |
| Queenex Corrugated Carton Factory |
| Universal Carton Industries LLC |
| Unipack Containers & Carton Products LLC |
| Falcon Pack |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters with multi-generational operational legacies anchor pricing discipline across the UAE corrugated landscape, their captive recycling operations insulating cost structures while MOHAP compliance investments compress margins for asset-light competitors. This ownership pattern concentrates supply-side bargaining power in Jebel Ali and Sharjah corridors, forcing price-cost pass-through negotiations to favor integrated producers with backward fiber control.
Pricing Analysis
The bundled-versus-unbundled service split separates contract structures across the UAE corrugated market, with integrated box plants packaging design services, logistics coordination, and sustainability certification into multi-year agreements while independent converters compete on unbundled unit pricing. Price differentiation hinges on MOHAP food-contact certification tier and volume scale commitments above container-load thresholds. Cost compression in standard single-wall grades is intensifying because recycled Kraft fiber prices fluctuate with global pulp markets. Small e-commerce fulfillment centers exhibit highest price sensitivity, while pharmaceutical cold-chain operators prioritize compliance assurance over unit cost minimization.
Supply Chain Analysis
Recycled Kraft paper supply rests on fiber collection networks across India, Indonesia, and domestic UAE municipal recycling programs, with import dependency running through Jebel Ali port infrastructure. Virgin pulp alternatives draw from Scandinavian and Brazilian producers when recycled fiber quality falls below MOHAP traceability thresholds. Starch adhesives and water-based barrier coatings constitute secondary input dependencies. Single-source vulnerability concentrates in specialty-grade linerboard where European mills dominate pharmaceutical-grade specifications. Distribution runs through direct mill relationships for multinational food manufacturers and independent distributor networks serving northern emirate mid-market converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE corrugated market offers margin expansion through premium-tier specification shifts toward die-cut precision formats and blockchain-traceable food-grade certifications, while automation investments in digital print and parametric design compress per-unit conversion costs for agile producers.
For Market Incumbents: Hedge against plastic crate substitution in beverage closed-loop logistics by accelerating water-based barrier coating capacity and securing MOHAP pharmaceutical certification ahead of timeline compression. Anchor position through captive recycling expansion in Hamriyah Free Zone to meet Emirates Authority for Standardization and Metrology fiber content thresholds. Defensive consolidation should target mid-sized Sharjah converters with established northern emirate distributor relationships. For New Entrants and Emerging Players: The pricing gap between premium die-cut formats and economy single-wall grades offers white-space entry for digital-native converters with parametric design capabilities and sub-72-hour turnaround commitments. Target Abu Dhabi food and beverage manufacturers qualifying for Khalifa Industrial Zone local content incentives. Deploy online procurement platforms with instant specification quoting to capture mid-market manufacturers digitizing supplier relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light custom specialists lacking captive recycling infrastructure but holding established MOHAP certification and e-commerce fulfillment center relationships. Five-to-ten-year viability favors integrated producers with multi-emirate facility networks and backward fiber control. Watch for Abu Dhabi industrial policy revision implementation as inflection signal for emirate-based production incentive qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Recycling | Hamriyah Free Zone recycling infrastructure investment accelerates compliance with Emirates Authority fiber thresholds. |
| Digital Print Convergence with Parametric Design | Variable-data printing integrated with structural software enables batch-size-one production for cosmetics limited editions. |
| MOHAP Pharmaceutical Certification Acceleration | Fast-tracked sterile transit packaging approval captures World Pack Industries LLC's cold-chain logistics anchor position. |
| Shelf-Ready Display Format Specification Lock-In | Dubai duty-free channel procurement consolidation eliminates secondary handling costs for confectionery distributors. |
| Blockchain-Traceable Fiber Documentation Integration | Supply chain visibility systems from fiber sourcing through delivery meet MOHAP's updated food-grade safety mandates. |
Research Methodology
Bottom-up food and beverage, pharmaceutical, and electronics end-use modeling reconciled against top-down corrugated board production capacity tracking forms the analytical core of this study. Primary interviews with procurement managers at multinational food manufacturers, plant engineers at integrated box facilities, cold-chain logistics operators, and sustainability compliance officers combined with secondary validation from Emirates Authority for Standardization and Metrology fiber content disclosures, MOHAP packaging safety regulation filings, Jebel Ali Free Zone industrial statistics, and UAE customs trade data. Triangulation between demand-side consumption estimates and supply-side mill output records resolves data asymmetries.
Input-output matrices map recycled Kraft fiber availability, starch adhesive supply, and water-based coating capacity against finished box production across single-wall, double-wall, and die-cut structural grades throughout the projection horizon. Segmentation dimensions include product type configuration, end-user industry vertical, packaging format standardization level, and distribution channel structure. CAGRs derive from regression analysis against historical corrugated consumption patterns and projected e-commerce fulfillment center expansion, pharmaceutical cold-chain investment, and food-grade safety mandate compliance costs.
Caveats apply where MOHAP certification timeline compression, recycled fiber import tariff adjustments, or abrupt plastic crate substitution adoption in beverage logistics could materially shift the outlook. Forecasts embed assumptions regarding Emirates Authority labeling framework enforcement consistency and Khalifa Industrial Zone incentive continuity. A small set of named triggers—Abu Dhabi industrial policy implementation pace, blockchain-traceable documentation technology cost curves, and northern emirate freight infrastructure investment—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Release Paper Market