
 South Africa Paper Packaging Market | 2026-2036
South Africa Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Paper Packaging Market Analytics
Consolidation among South African food exporters is recalibrating volume commitments across the converter base. Mpact Limited leverages integrated pulp-to-box manufacturing to secure multi-year contracts with citrus cooperatives. Sappi Limited anchors the premium coated kraft segment through specialized containerboard grades engineered for humid supply chains. Mondi plc competes via lightweight corrugated innovations that reduce freight costs for Cape wine shippers.
South Africa paper packaging comprises cellulose-based substrates—typically 80–350 gsm board weights—formed through kraft pulping, corrugation, and die-cutting processes to protect goods during distribution. The primary commercial purpose centers on unitization, shelf presentation, and moisture barrier performance for perishable exports. Boxes dominate volume flows through the food and beverage channel, where corrugated case demand tracks citrus, avocado, and wine shipment cycles. Bags represent the fastest-expanding format among biodegradable packaging types, driven by retail plastic bans in Johannesburg and Cape Town metropolitan zones.
The Department of Forestry, Fisheries and the Environment enforces extended producer responsibility frameworks that mandate recycled content thresholds and post-consumer collection targets. BIS-equivalent SABS standards govern board stiffness and print adhesion for food-contact applications, shaping converter capital allocation toward certified production lines. Stakeholders must monitor enforcement cadence against informal recycler capacity constraints and port logistics reliability to align capacity decisions with actual compliance timelines.
Market Dynamics
Extended producer responsibility mandates from the Department of Forestry, Fisheries and the Environment are redirecting capital toward recyclable substrates and certified collection infrastructure, compressing converter margins while reshaping procurement specifications across agricultural export channels.
Growth Catalysts
- EPR Compliance Deadlines:The Department of Forestry, Fisheries and the Environment's recycled content thresholds force converters to retool lines, creating first-mover advantages for certified suppliers serving citrus and wine exporters.
- Agricultural Export Volume Expansion:Gauteng and Western Cape food manufacturers are scaling corrugated box procurement to match avocado and citrus shipment cycles through Durban and Cape Town ports.
- Biodegradable Bag Substitution:Metropolitan plastic bans in Johannesburg and Cape Town are accelerating kraft paper bag adoption across retail grocery and quick-service restaurant channels.
Market Restraints
- Pulp Input Cost Volatility:South African converters face margin pressure from global hardwood pulp price swings and domestic electricity tariff escalations that erode corrugated board production economics.
- Port Infrastructure Bottlenecks:Durban container terminal congestion and equipment shortages create inventory holding cost surcharges that paper packaging buyers pass partially back to converters.
- Flexible Plastic Barrier Performance:High-moisture produce segments retain multi-layer plastic laminates where paper-based alternatives fail humidity resistance thresholds during extended sea freight.
Strategic Opportunities
- KwaZulu-Natal Manufacturing Corridor Expansion:Port-proximate converter capacity in Durban remains underdeveloped relative to citrus export growth, offering brownfield site advantages for integrated producers.
- Coated Kraft Innovation for Humid Supply Chains:Specialized containerboard grades with moisture-resistant barriers can displace plastic in avocado and stone fruit export packaging where SABS standards currently permit limited substitution.
- Informal Recycler Integration:Post-consumer collection targets create partnership openings with Johannesburg and Cape Town waste picker cooperatives to secure fiber supply and compliance documentation.
Industry Challenges
- Die-Cutting Automation Skill Gaps:Converter operations in the Eastern Cape and Free State struggle to recruit technicians capable of maintaining high-speed flexo folder-gluer lines.
- SABS Certification Timeline Compression:Food-contact board stiffness and print adhesion approvals require 8-12 month validation cycles that misalign with seasonal agricultural procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Paper Packaging Market |
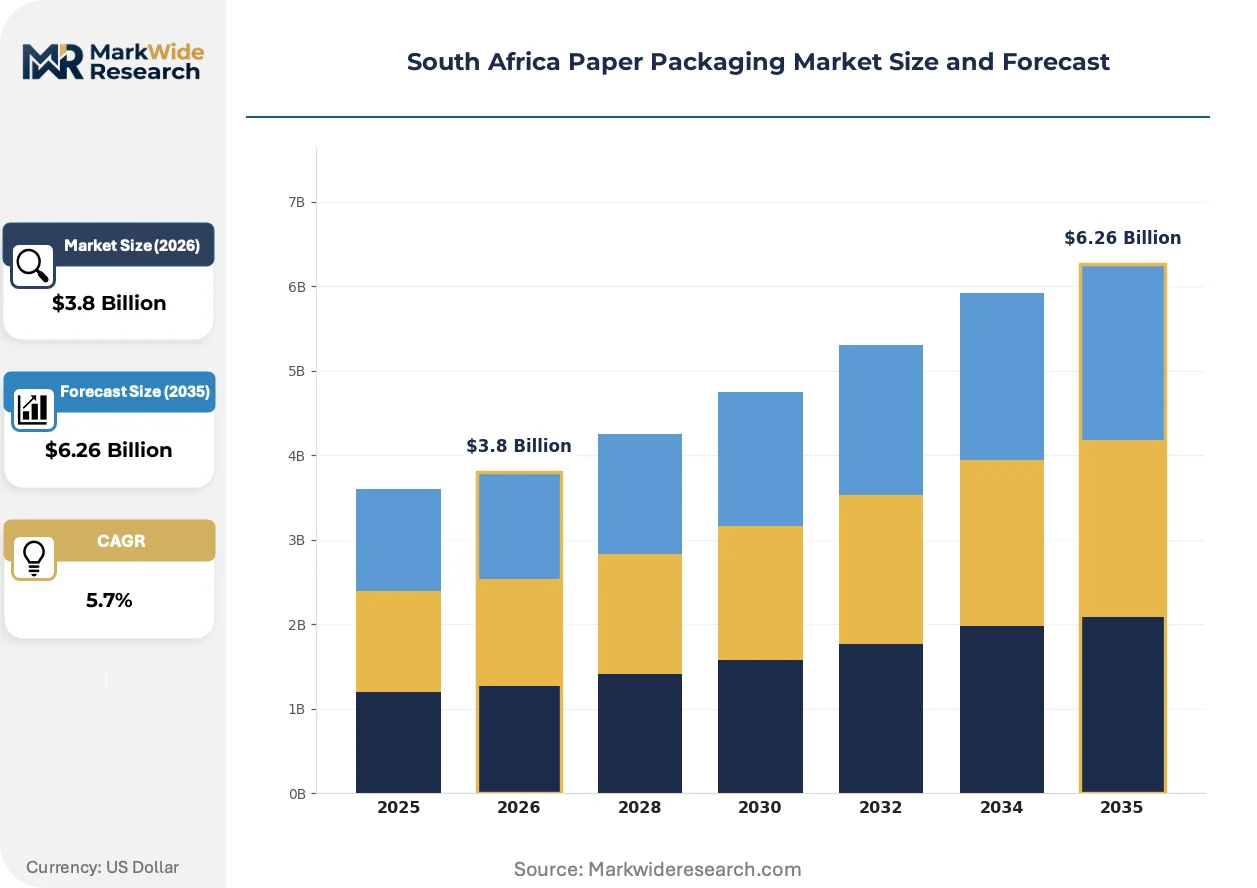
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Cartons, Bags, Wraps End User: Food & Beverage, Personal Care, Electronics, Pharmaceuticals Packaging Type: Recyclable, Biodegradable, Coated, Uncoated Distribution Channel: Online Retail, Wholesale, Supermarkets, Convenience Stores |
| Companies Covered | Mpact Limited, Huhtamaki Oyj, Sappi Limited, Smurfit Kappa Group, Amcor plc, Mondi plc, Corruseal Holdings (Pty) Ltd., Detmold Group, Nampak Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Paper Packaging Market Evolving Landscape
Lightweighting technologies and digital print integration are compressing traditional corrugated specifications while regulatory compliance automation is reshaping how converters document chain-of-custody for export customers.
High-performance lightweight corrugated flutes are rewriting freight economics for Cape wine shippers by reducing case weight without sacrificing stacking strength. Mondi plc and regional competitors have accelerated adoption of F-flute and N-flute profiles among premium export packers seeking container cube optimization. This technology is rewriting the cost structure of long-haul agricultural logistics by trimming dimensional weight charges and pallet utilization rates.
The Department of Forestry, Fisheries and the Environment's extended producer responsibility framework is mandating audited post-consumer collection rates and recycled content minimums for all packaging placed on the South African market. Converter capital allocation now prioritizes tracking software and third-party certification over pure capacity expansion. Food and beverage exporters in the Western Cape are responding by specifying FSC-certified substrates and demanding batch-level compliance documentation from Durban-based suppliers.
Buyer consolidation among citrus cooperatives and wine estates is compressing contract renewal cycles and shifting procurement toward multi-year volume commitments with integrated producers. Smaller converters lacking pulp-to-box integration face exclusion from tender processes that specify single-source accountability for EPR compliance. This behavioral shift is most visible in the Western Cape export corridor where Mpact Limited's captive fiber supply secures preferential contracting terms against merchant board competitors.
South Africa Paper Packaging Market Segmentation
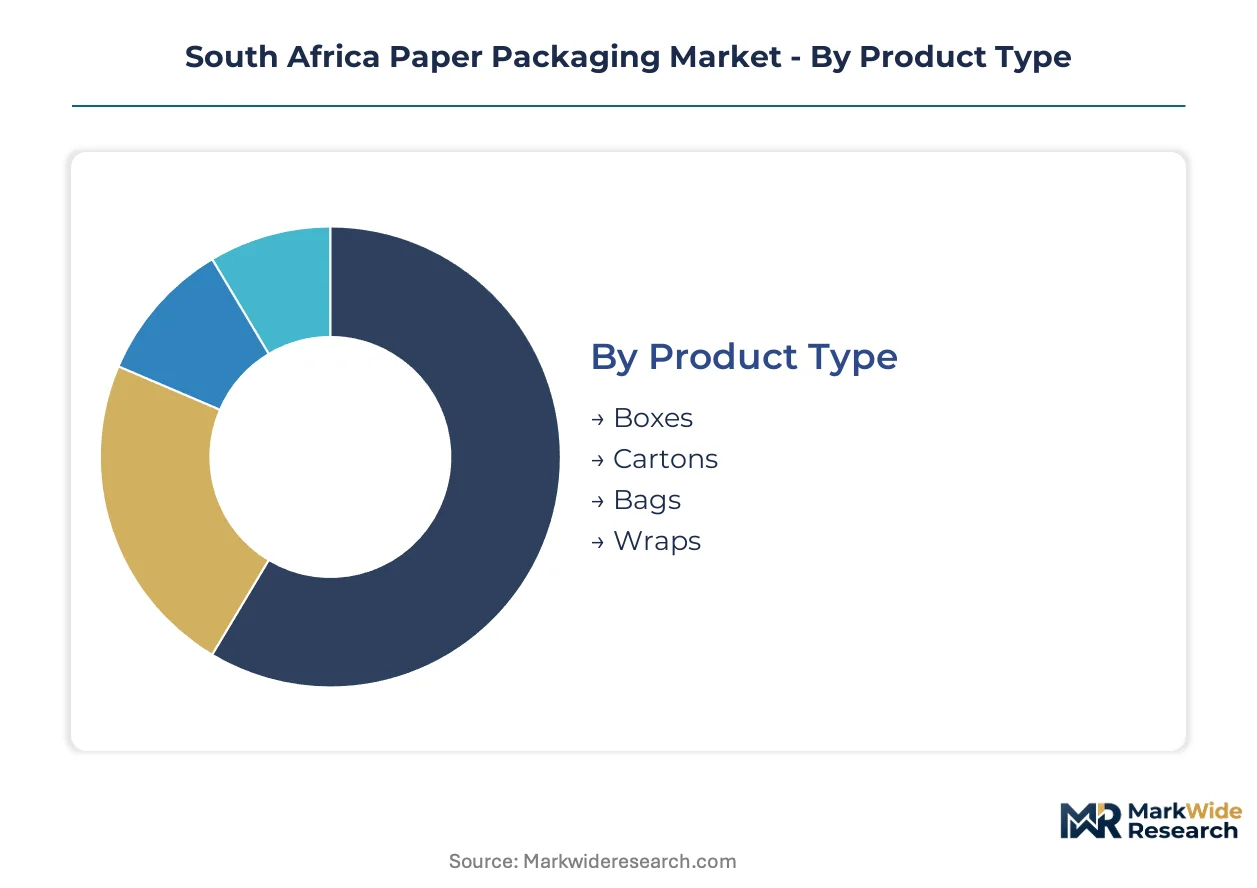
South Africa's paper packaging market segments along four functional dimensions that shape procurement patterns and converter investment priorities. Product type and end-use concentration determine volume flows, while packaging type and distribution channel specifications govern compliance requirements and margin structures across Gauteng, Western Cape, and KwaZulu-Natal manufacturing corridors.
Product Type:
Boxes command volume leadership through agricultural export channels, while bags capture the steepest expansion trajectory driven by metropolitan plastic substitution mandates.
- Boxes:Corrugated fiberboard constructions ranging from single-wall B-flute to triple-wall configurations dominate citrus, avocado, and wine export logistics. Demand concentrates in Durban-based converters serving KwaZulu-Natal's port-proximate manufacturing corridor, where citrus cooperative procurement cycles drive seasonal capacity utilization peaks.
- Bags:Multi-ply kraft constructions with twisted or flat handles serve retail grocery and quick-service restaurant channels under Johannesburg and Cape Town plastic ban enforcement. These formats are gaining share fastest among biodegradable packaging types as municipal regulations tighten.
- Cartons:Folding carton grades in 200–350 gsm solid bleached sulfate target premium food and personal care shelf presentation in Western Cape manufacturing zones.
- Wraps:Lightweight 40–80 gsm kraft and greaseproof specifications protect individual food items within larger distribution units across wholesale and convenience store channels.
Today's leader: Boxes. Tomorrow's challenger: Bags.
End User:
Food and beverage procurement dwarfs other segments, though pharmaceutical specifications command premium pricing through SABS certification requirements.
- Food & Beverage:Citrus, avocado, and wine exporters in the Western Cape and Gauteng drive corrugated case specifications with moisture-resistant barrier demands for extended sea freight. The Department of Forestry, Fisheries and the Environment's extended producer responsibility mandates force these buyers to specify certified recyclable substrates with audited chain-of-custody documentation.
- Personal Care:Folding carton and rigid box formats for premium cosmetics and skincare products require high-print-quality coated boards from Western Cape converters, with SABS food-contact-grade stiffness standards often applied by analogy.
- Electronics:Anti-static corrugated and molded pulp protective packaging serves Durban-imported consumer electronics distribution through wholesale and online retail channels.
- Pharmaceuticals:Cold-chain-qualified insulated shippers and serialized cartons for temperature-sensitive drug distribution require the most stringent SABS validation cycles, compressing converter margins but sustaining price premiums.
Food and beverage anchors volume; pharmaceuticals sustain margin.
Packaging Type:
Recyclable specifications dominate procurement mandates, while coated grades retain defensive positioning in humid supply chains where paper-based alternatives face technical barriers.
- Recyclable:Standard kraft and test liner-based corrugated meeting Department of Forestry, Fisheries and the Environment post-consumer collection targets. These specifications are mandatory for citrus cooperative contracts and increasingly specified by Cape wine estates seeking export market access.
- Coated:Polyethylene-extruded or wax-impregnated barriers for high-moisture produce segments where humidity resistance thresholds exceed uncoated board capabilities. Demand concentrates in stone fruit and avocado export channels through Cape Town port logistics.
- Biodegradable:Compostable kraft bag constructions accelerated by Johannesburg and Cape Town metropolitan plastic bans, with waste picker cooperative collection partnerships emerging as a compliance mechanism.
- Uncoated:Basic kraft liner and medium specifications for dry goods distribution where cost minimization overrides barrier performance, prevalent in wholesale channel procurement.
Recyclable formats capture regulatory tailwinds; coated grades defend technical niches.
Distribution Channel:
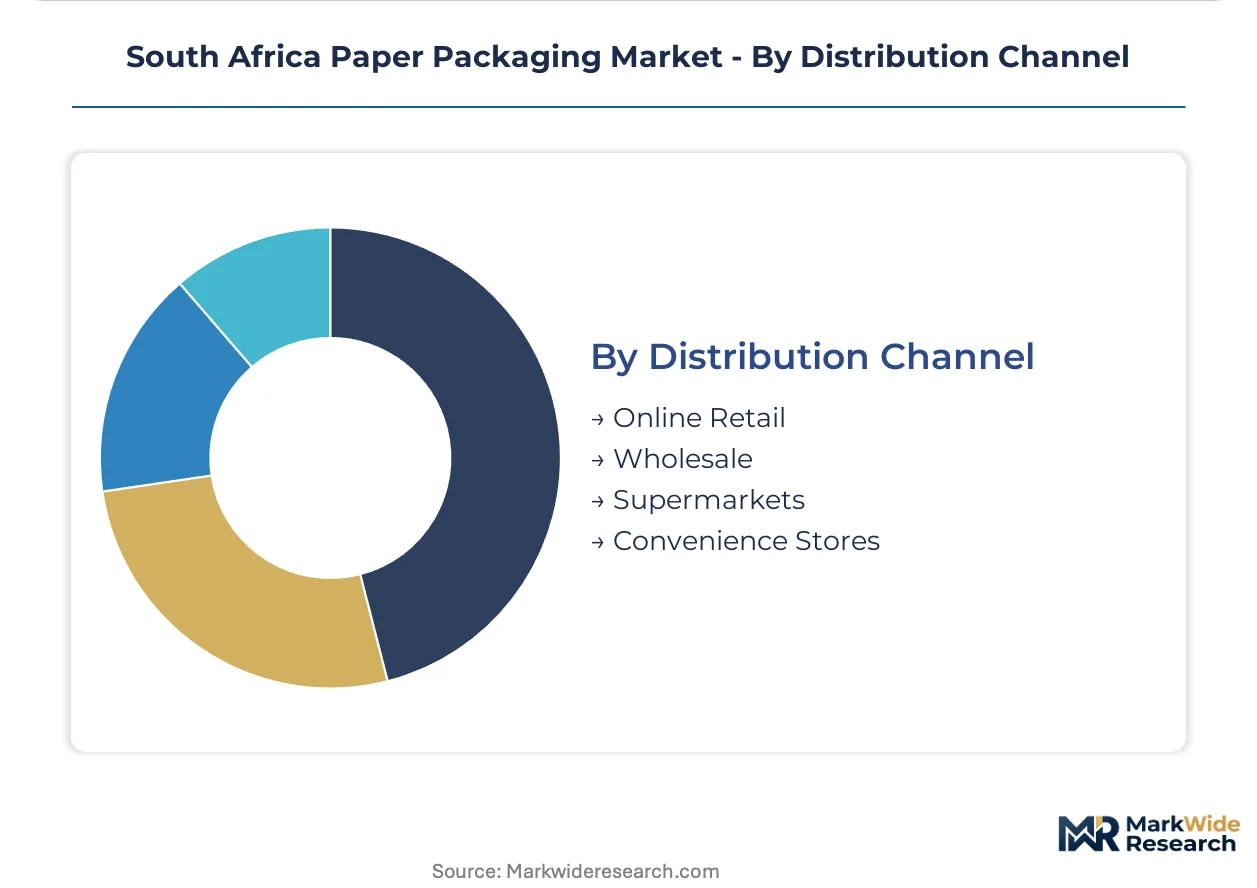
Wholesale procurement governs converter volume planning, while online retail specifications are compressing lead times and forcing digital print integration.
- Wholesale:Bulk corrugated case procurement by agricultural exporters and food manufacturers through direct converter relationships, characterized by multi-year volume commitments and EPR compliance documentation requirements.
- Supermarkets:Private-label folding carton and bag specifications for retail grocery chains in Johannesburg, Cape Town, and Durban metropolitan zones, with plastic-to-paper substitution mandates driving format shifts.
- Online Retail:E-commerce corrugated specifications emphasizing dimensional weight optimization and print-on-demand branding, forcing converter investment in digital flexo and die-cutting automation.
- Convenience Stores:Small-format bag and wrap procurement for quick-service restaurant and grab-and-go food channels, with localized distribution from Durban and Cape Town converters.
Wholesale secures volume foundations; online retail forces capability upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's corrugated packaging sector operates at roughly triple South Africa's scale, yet both markets face identical pressure from extended producer responsibility frameworks that redirect converter investment toward certified collection infrastructure.
Gauteng
Johannesburg-based food manufacturers drive corrugated procurement for agricultural re-export through Durban port logistics. The Department of Forestry, Fisheries and the Environment mandates recycled content thresholds that force Pretoria-area converters to retool lines. The Vaal Triangle manufacturing cluster concentrates die-cutting capacity serving citrus cooperative volume commitments.
Western Cape
Cape wine estates and avocado exporters specify moisture-resistant containerboard grades for extended sea freight to European markets. Municipal plastic bans in Cape Town metropolitan zones accelerate kraft bag adoption across retail grocery channels. The Stellenbosch-Paarl corridor anchors coated kraft innovation for humid supply chains.
KwaZulu-Natal
Durban-based converters face port infrastructure bottlenecks that create inventory holding cost surcharges passed partially back to board suppliers. Citrus export growth through the container terminal outpaces local corrugated capacity expansion. The port-proximate manufacturing corridor remains underdeveloped relative to shipment volume cycles.
Eastern Cape
Port Elizabeth automotive component suppliers generate secondary demand for protective corrugated and molded pulp formats. Die-cutting automation skill gaps constrain converter operations across Gqeberha manufacturing zones. The Coega Special Economic Zone attracts brownfield investment targeting export logistics integration.
South Africa Paper Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South Africa's paper packaging sector, creating a tiered structure where integrated pulp-to-box manufacturers hold procurement advantages. The vendor base clusters around three strategic archetypes: captive fiber producers securing multi-year agricultural contracts, merchant board converters competing on flexibility, and multinational specialists importing barrier technologies. Dominant competitive moves include backward integration into recycled fiber collection and geographic expansion toward port-proximate manufacturing corridors.
Within the integrated producer tier, Mpact Limited and Sappi Limited exemplify archetypes of captive supply control over containerboard inputs. Mondi plc occupies a position among multinational specialists leveraging lightweight corrugated innovations. These three entities anchor competitive dynamics across the Western Cape export corridor and KwaZulu-Natal manufacturing zones.
| Leading Market Players |
|---|
| Mpact Limited |
| Huhtamaki Oyj |
| Sappi Limited |
| Smurfit Kappa Group |
| Amcor plc |
| Mondi plc |
| Corruseal Holdings (Pty) Ltd. |
| Detmold Group |
| Nampak Limited |
| Others |
Value Network & Pricing Analysis
Extended producer responsibility mandates from the Department of Forestry, Fisheries and the Environment are forcing converters to absorb certification and collection infrastructure costs, compressing margins and shifting procurement power toward integrated pulp-to-box manufacturers with captive fiber supply.
Pricing Analysis
Capacity additions in KwaZulu-Natal's port-proximate manufacturing corridor are reshaping price floors for corrugated containerboard serving citrus export channels. Pricing stratifies across FSC-certified premium grades, SABS-compliant standard tiers, and uncoated economy specifications for dry goods distribution. Cost compression in the economy tier is intensifying because merchant board converters lack backward integration into recycled fiber collection. Agricultural exporters in the Western Cape exhibit the lowest price sensitivity due to moisture-resistant barrier requirements, while wholesale distributors of dry goods remain highly price-sensitive.
Supply Chain Analysis
Domestic-content mandates under South Africa's extended producer responsibility framework are reshaping sourcing patterns toward local recycled fiber collection partnerships and certified domestic production lines. Raw material supply draws from Brazilian eucalyptus pulp imports, domestic recovered paper streams, and hardwood kraft from Sappi's Saiccor mill. The supply chain faces single-source vulnerability in Durban port logistics, where container terminal congestion creates inventory holding cost surcharges. Distribution runs through direct converter relationships with agricultural exporters, supplemented by wholesale channel partnerships serving Johannesburg and Cape Town metropolitan retail zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's paper packaging market functions as a regulatory compounder where Department of Forestry, Fisheries and the Environment compliance deadlines create structural advantages for certified producers capable of documenting audited post-consumer collection rates.
For Market Incumbents: Cement procurement lock-in through multi-year volume commitments with citrus cooperatives and wine estates before SABS certification timelines compress further. Prioritize captive supply of recycled fiber via partnerships with Johannesburg and Cape Town waste picker cooperatives to defend margin position against merchant board competitors lacking collection infrastructure.
For New Entrants and Emerging Players: Enter via brownfield site acquisition in Durban's underdeveloped port-proximate manufacturing corridor, where citrus export growth outpaces local corrugated capacity expansion. Target the biodegradable bag segment accelerated by metropolitan plastic bans, leveraging compostable kraft specifications and waste picker cooperative collection partnerships as a compliance mechanism.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated pulp-to-box specialists controlling captive fiber supply and certified collection infrastructure. Five-to-ten year viability hinges on positioning ahead of tightened recycled content thresholds and extended producer responsibility enforcement cadence. Monitor Durban port infrastructure investment announcements as the critical inflection signal for KwaZulu-Natal manufacturing corridor expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Collection | Secures compliance documentation for Department of Forestry, Fisheries and the Environment mandates while reducing merchant board dependency. |
| Coated Kraft Innovation for Humid Supply Chains | Enables displacement of plastic barriers in avocado and stone fruit exports through SABS-certified moisture-resistant containerboard grades. |
| Port-Proximate Manufacturing Expansion | Reduces inventory holding costs from Durban container terminal congestion for citrus cooperative volume commitments. |
| Digital Print Integration for E-Commerce Specifications | Addresses online retail dimensional weight optimization and print-on-demand branding requirements from Cape Town and Johannesburg distributors. |
| Informal Recycler Partnership Programs | Creates audited post-consumer collection documentation for extended producer responsibility compliance while securing fiber supply. |
Research Methodology
Bottom-up food and beverage export modeling reconciled against top-down containerboard production tracking forms the analytical core of this study. Primary interviews with corrugated converter operations managers, citrus cooperative procurement directors, SABS certification specialists, and Durban port logistics coordinators were validated against secondary sources including Department of Forestry, Fisheries and the Environment regulatory filings, SABS standards documentation, and customs export data for agricultural shipments. Trade association publications from the Paper Manufacturers Association of South Africa and converter capacity databases provided additional triangulation points.
Historical trendline analysis of citrus, avocado, and wine shipment cycles through Durban and Cape Town ports established baseline demand patterns across the projection horizon. Segmentation modeling incorporated product type dimensions, end-use concentration by agricultural export channel, packaging type compliance requirements, and distribution channel specifications. CAGRs were derived from regression analysis of converter capacity utilization against export volume growth, with adjustments for extended producer responsibility implementation timelines and SABS certification cycle compression.
Inputs from Department of Forestry, Fisheries and the Environment regulatory announcements and port authority infrastructure plans were available through the study window; gaps in informal recycler capacity data and enforcement cadence specifics introduce uncertainty bands around compliance-driven demand acceleration assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market