
 Retail Logistics Market | 2026-2036
Retail Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Logistics Market Analysis
The shift from single-source freight contracts toward multi-provider networks is broadening the competitive field for mid-sized retailers seeking resilience against capacity shocks. DHL International GmbH leverages its European ground network to sustain dense last-mile coverage across Germany and the Netherlands. XPO Logistics, Inc. anchors North American less-than-truckload operations through its proprietary freight optimization platform. FedEx differentiates via integrated air-ground express infrastructure that dominates time-definite delivery windows for premium e-commerce shipments.
Retail logistics encompasses the planning, execution, and control of physical goods movement from distribution centers to end consumers, typically operating within delivery radii under 100 miles for last-mile segments and requiring real-time inventory visibility across nodes. Warehouse Management Systems now coordinate automated sortation, robotic picking, and dynamic slotting to compress order cycle times below four hours in high-velocity facilities. Transportation services command the largest value share within service-type segmentation due to fuel, labor, and asset intensity, while same-day delivery within delivery models is expanding fastest as consumer tolerance for waiting compresses. Cloud computing within technology segmentation underpins margin expansion by reducing capital expenditure on proprietary server infrastructure.
The EPA regulates commercial vehicle emissions under Phase 3 greenhouse gas standards, compelling fleet operators to accelerate zero-emission vehicle procurement or face operational restrictions in California and other adopting states. The EU Green Deal and F-Gas Regulation shape cold-chain logistics by mandating refrigerant transitions and carbon intensity disclosures for cross-border parcel flows. OSHA warehouse safety standards influence automation investment decisions by raising the cost threshold for manual handling operations. Stakeholders must monitor how fragmented national emissions rules reshape network design trade-offs between speed and compliance cost.
Market Dynamics
Same-day delivery compression is forcing retailers to reconfigure fulfillment networks around micro-fulfillment centers positioned within 25 miles of dense population clusters.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:Fleet operators in California and adopting states face operational restrictions without zero-emission vehicle procurement, accelerating capital deployment into electric van and truck fleets.
- Robotic picking systems:High-velocity facilities deploy autonomous mobile robots and dynamic slotting algorithms to compress order cycle times below four hours.
- Dallas-Chicago-Inland Empire corridor:Concentrated distribution hub development across these three nodes anchors North American e-commerce fulfillment capacity expansion.
Market Restraints
- Commercial vehicle battery cost volatility:Lithium-ion cell prices and rare earth magnet supply constraints inflate electric fleet procurement budgets beyond diesel parity thresholds.
- Warehouse labor concentration in exurban zones:Fulfillment center siting near affordable housing corridors creates dependency on thin local labor pools with high seasonal turnover.
- Refrigerant transition timelines:EU F-Gas Regulation mandates for cold-chain logistics compress equipment replacement cycles while alternative refrigerant supply remains constrained.
Strategic Opportunities
- India's PLI scheme for logistics infrastructure:Production-linked incentives for automated warehousing and cold storage construction open greenfield development corridors around Mumbai and Delhi.
- Cloud-native Warehouse Management Systems:Convergence of edge computing and API-first architecture enables mid-sized retailers to access tier-one automation without proprietary server capital expenditure.
- Reverse logistics monetization:Returns processing infrastructure captures refurbishment and resale value streams that pure forward-logistics providers forfeit.
Industry Challenges
- Certified forklift operator shortages:OSHA warehouse safety standards raise training compliance costs while labor markets lack sufficient credentialed equipment handlers.
- Multi-node inventory synchronization:Real-time visibility across micro-fulfillment centers, dark stores, and traditional DCs demands API integration with legacy ERP systems that lack native cloud connectivity.
- Cross-border carbon intensity disclosure:EU Green Deal requirements for parcel flow emissions tracking force network redesigns that trade speed for compliance documentation capacity.
Report Scope
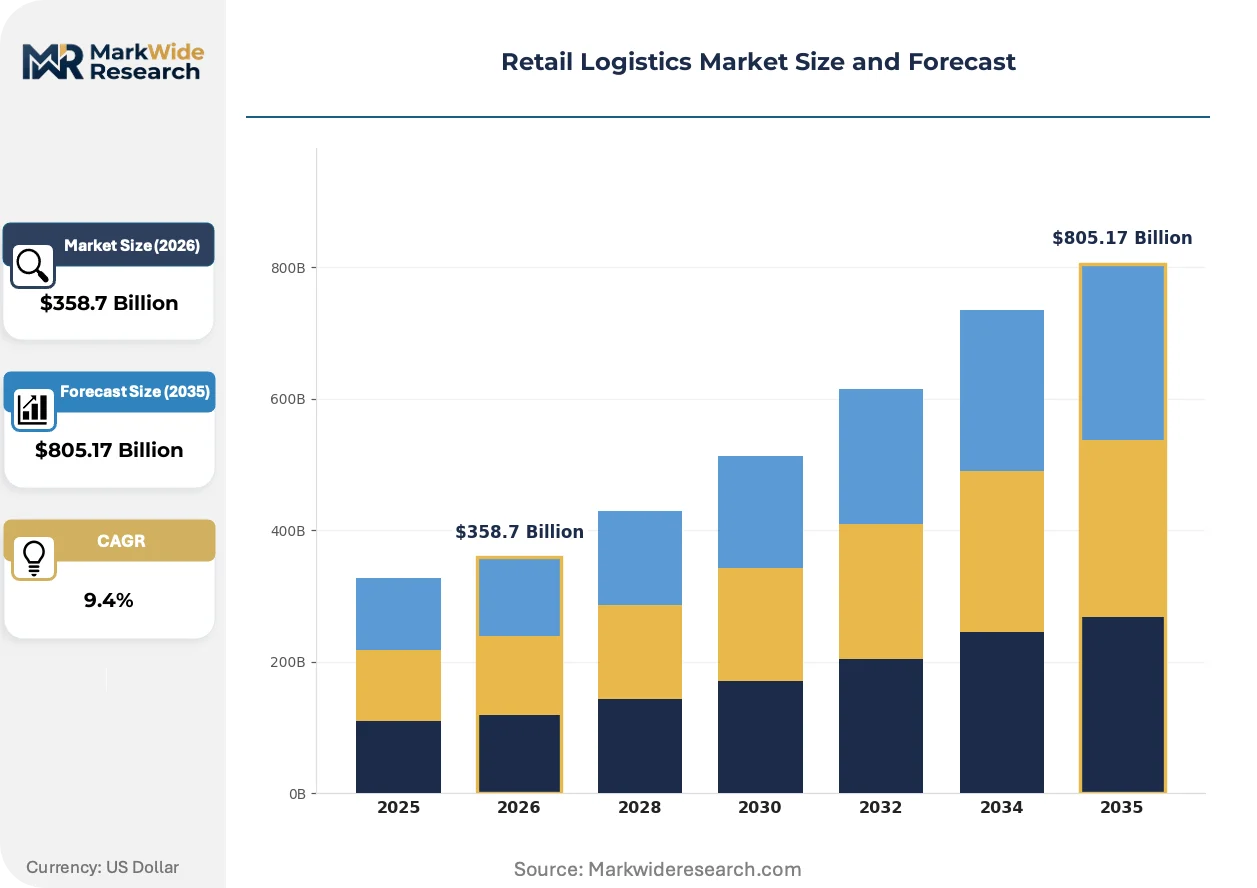
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Logistics Market |
| Market Size in 2026 | $358.7 Billion |
| Market Size in 2035 | $805.17 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Transportation, Distribution, Inventory Management Delivery Model: Direct Shipping, Click and Collect, Same-Day Delivery, Scheduled Delivery Technology: Warehouse Management Systems, RFID, Automation, Cloud Computing Customer Type: eCommerce, Supermarkets, Specialty Retailers, Wholesale Distributors |
| Companies Covered | XPO Logistics, Inc., DSV, Kuehne + Nagel International, C.H. Robinson Worldwide, Inc., Nippon Express, FedEx, United Parcel Service, DHL International GmbH, APL Logistics Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Logistics Market Emerging Trajectories
Automation density is bifurcating fulfillment economics between capital-heavy automated facilities and labor-dependent legacy warehouses.
Autonomous mobile robots with dynamic pathing algorithms are electrifying warehouse throughput economics. Grocery and fashion retailers with high SKU volatility deploy these systems at 18-24 month payback thresholds. The technology is electrifying competitive separation between automated networks and manual facilities.
EU Green Deal carbon border adjustments for cross-border parcel flows are reshaping network architecture. Logistics operators must now document Scope 3 emissions across subcontracted last-mile providers. Cold-chain and express segments face the steepest compliance cost escalations as refrigerant and fuel disclosures tighten.
Buyer tolerance for delivery windows has compressed from 3-5 days to same-day or four-hour slots. Home improvement and health and beauty verticals show the steepest expectation shifts. Urban corridors in Germany and the Netherlands exhibit the most acute delivery-speed pressure as omnichannel retailers compete for basket retention.
Retail Logistics Market Segmentation
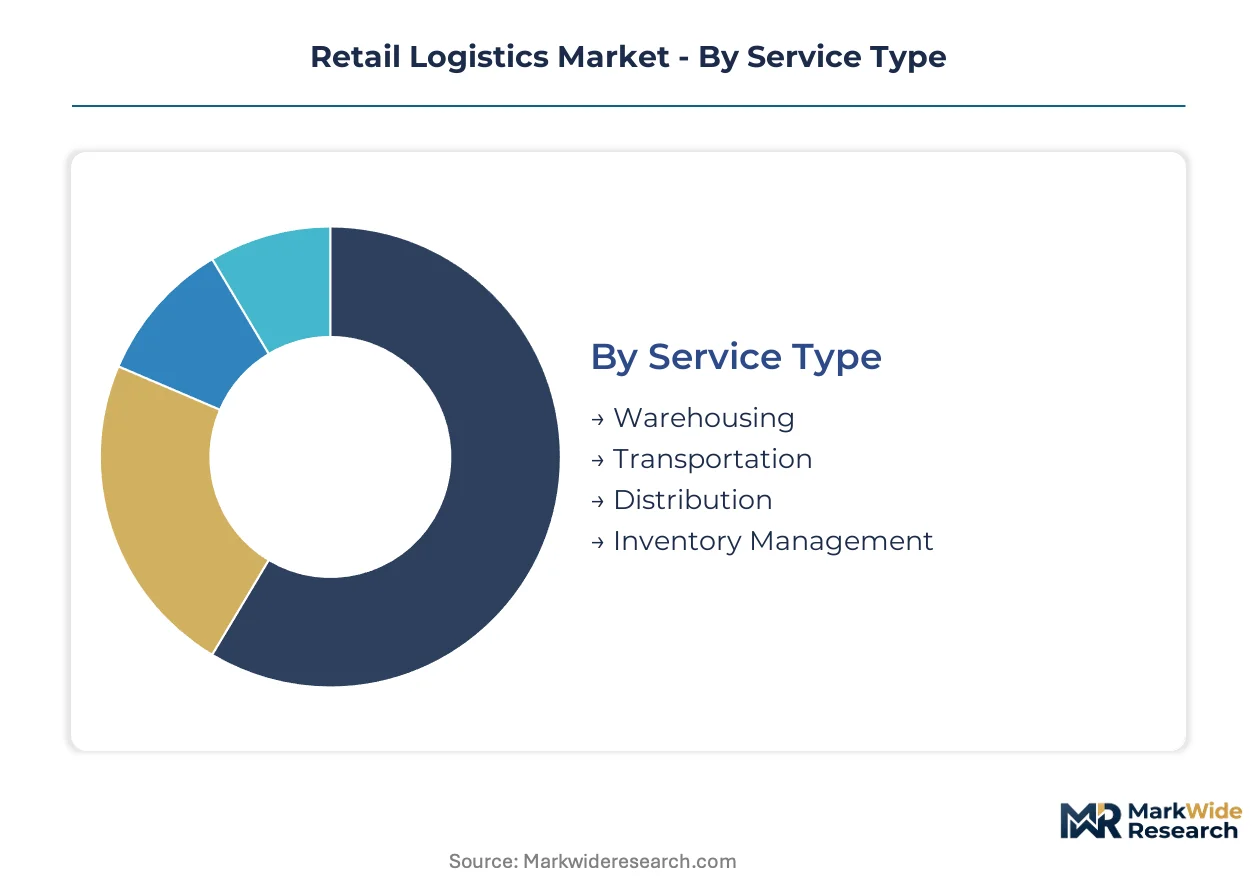
Retail logistics segmentation reveals how capital intensity, technology maturity, and customer tolerance for delivery speed fragment service economics. Each axis shapes network design trade-offs between fixed infrastructure and variable labor costs.
Service Type:
Technical sophistication and asset ownership patterns differentiate service tiers, with fuel and labor intensity driving margin structure.
- Transportation:Fuel, labor, and vehicle asset intensity concentrate value capture here. Fleet operators face EPA Phase 3 compliance deadlines in California and adopting states, forcing zero-emission procurement decisions that reshape total cost of ownership calculations.
- Warehousing:Fixed real estate and automation capital dominate economics. High-velocity facilities deploy robotic picking and dynamic slotting to compress order cycle times below four hours, with Dallas-Chicago-Inland Empire corridor nodes commanding premium lease rates.
- Distribution:Cross-dock throughput velocity determines efficiency. Network design balances inventory carrying cost against last-mile proximity to dense population clusters.
- Inventory Management:Real-time visibility systems coordinate stock positioning across nodes. Cloud-native platforms reduce capital expenditure barriers for mid-sized retailers.
Mature deployment sits with Transportation. Newer deployment is concentrated in Inventory Management.
Delivery Model:
Customer tolerance for waiting compresses delivery windows, with speed premiums stratifying operational complexity and capital requirements.
- Same-Day Delivery:Micro-fulfillment centers positioned within 25 miles of dense clusters enable this model. Urban corridors in Germany and the Netherlands exhibit acute speed pressure as omnichannel retailers compete for basket retention.
- Click and Collect:Dark store conversion of retail footprints creates hybrid inventory pools. Grocery and fashion verticals leverage existing real estate to avoid pure-play delivery cost structures.
- Scheduled Delivery:Route density optimization maximizes vehicle utilization. Home improvement and furniture segments favor appointment-based windows due to handling complexity.
- Direct Shipping:Parcel carrier integration bypasses retailer-controlled infrastructure. Small and mid-sized e-commerce merchants rely on FedEx and DHL networks for time-definite service.
Established volume sits with Scheduled Delivery. Steepest expansion trajectory belongs to Same-Day Delivery.
Technology:
Cloud architecture and edge computing convergence reshape capital deployment patterns across automation tiers.
- Cloud Computing:API-first infrastructure eliminates proprietary server expenditure. Mid-sized retailers access tier-one automation capabilities through subscription models rather than capital-intensive deployments.
- Automation:Autonomous mobile robots with dynamic pathing algorithms electrify throughput economics. Grocery and fashion retailers with high SKU volatility achieve 18-24 month payback thresholds.
- Warehouse Management Systems:Coordination layer for automated sortation, robotic picking, and dynamic slotting. Legacy ERP integration challenges persist for facilities lacking native cloud connectivity.
- RFID:Item-level tracking enables real-time inventory visibility. Implementation concentrates in high-value apparel and electronics verticals where shrinkage cost justifies tag expense.
Deep implementation sits with Warehouse Management Systems. Fastest adoption velocity sits with Cloud Computing.
Customer Type:
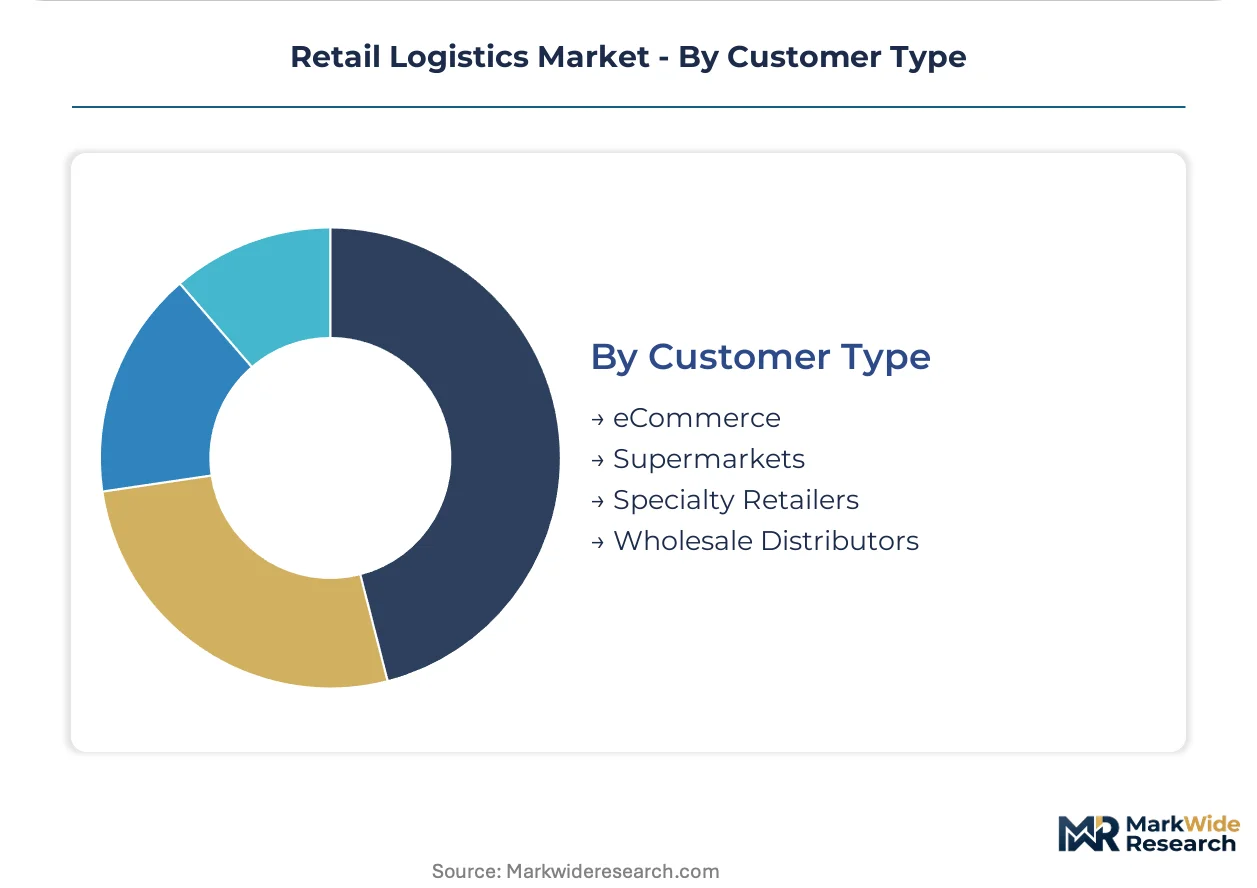
Order profile volatility and return rates differentiate service requirements across retail verticals.
- eCommerce:Return rates averaging 20-30% in fashion verticals demand reverse logistics infrastructure. Pure-play online merchants forfeit refurbishment value streams without dedicated returns processing capacity.
- Supermarkets:Cold-chain compliance and perishable handling dominate operational design. EU F-Gas Regulation mandates compress equipment replacement cycles for temperature-controlled distribution.
- Specialty Retailers:Concentrated SKU depth with seasonal demand spikes. Inventory positioning balances stockout risk against obsolescence cost in fashion and electronics categories.
- Wholesale Distributors:Pallet-level throughput with lower velocity requirements. Full-truckload economics favor consolidation with retail fulfillment networks.
Scale concentration sits with eCommerce. Emerging complexity sits with Supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand concentrates around the Dallas-Chicago-Inland Empire corridor, where distribution hub development anchors North American e-commerce fulfillment capacity expansion.
United States
Same-day delivery compression drives micro-fulfillment center deployment within 25 miles of dense population clusters. EPA Phase 3 greenhouse gas standards compel fleet operators in California and adopting states toward zero-emission vehicle procurement. The Inland Empire anchors the nation's largest concentration of automated high-velocity facilities serving western e-commerce markets.
Germany
Omnichannel basket retention battles intensify delivery-speed pressure across urban corridors. EU Green Deal carbon border adjustments mandate Scope 3 emissions documentation across subcontracted last-mile networks. The Rhine-Ruhr metropolitan region sustains Europe's densest automated ground network coverage for time-definite parcel flows.
Netherlands
Consumer tolerance for waiting compresses toward four-hour delivery windows in grocery and fashion verticals. F-Gas Regulation mandates accelerate refrigerant transitions for temperature-controlled distribution infrastructure. Rotterdam's port-centric logistics cluster integrates automated sortation with European cross-border parcel consolidation.
India
Production-linked incentives for automated warehousing and cold storage construction unlock greenfield development corridors. BIS standards and central logistics infrastructure programs reshape capital deployment patterns around Mumbai and Delhi. The Delhi-Mumbai Industrial Corridor attracts dedicated fulfillment center investment from international operators seeking scale positions.
China
Dual carbon goals and national emissions standards redirect fleet procurement toward electric commercial vehicles. SAMR logistics sector regulations coordinate with MIIT smart supply chain initiatives. The Yangtze River Delta maintains the world's highest automation density in consumer goods fulfillment facilities.
Retail Logistics Market Vendor Landscape
Capacity expansion dominates the current landscape as operators race to establish micro-fulfillment positions within 25 miles of dense population clusters. The market structure concentrates around integrated express networks, asset-light freight brokers, and specialized cold-chain operators. Three archetypes define competitive positioning: integrated air-ground carriers with proprietary infrastructure, technology-enabled freight optimization platforms, and European ground network specialists with dense last-mile coverage. M&A activity and strategic partnerships represent the dominant competitive moves as mid-sized retailers seek resilience against capacity shocks.
Among integrated express carriers, FedEx and United Parcel Service exemplify the infrastructure-heavy archetype that dominates time-definite delivery windows for premium e-commerce shipments. DHL International GmbH occupies a position within the European ground network specialist tier, leveraging dense coverage across Germany and the Netherlands. XPO Logistics, Inc. represents the technology-enabled freight optimization model, anchoring North American less-than-truckload operations through proprietary platforms.
| Leading Market Players |
|---|
| XPO Logistics, Inc. |
| DSV |
| Kuehne + Nagel International |
| C.H. Robinson Worldwide, Inc. |
| Nippon Express |
| FedEx |
| United Parcel Service |
| DHL International GmbH |
| APL Logistics Ltd |
| Others |
Supply Flow & Price Mechanics
Diesel fuel price indices and lithium-ion cell benchmarks cascade through fleet procurement budgets, compressing margin structures for operators balancing EPA Phase 3 compliance deadlines against same-day delivery speed premiums. Transportation services absorb the steepest cost volatility, with fuel and asset intensity stratifying pricing power between integrated carriers and asset-light freight brokers.
Pricing Analysis
Volume concentration in scheduled delivery segments subsidizes razor-thin margins in same-day tiers, where micro-fulfillment center depreciation and electric fleet premiums inflate per-unit costs. Three-tier pricing structure across premium time-definite, standard next-day, and economy ground parcel segments separates FedEx and DHL integrated networks from regional LTL operators. Cost compression in standard tiers intensifies as cloud-native Warehouse Management Systems democratize automation capabilities for mid-sized retailers. Specialty retailers with high SKU volatility exhibit lowest price sensitivity, while commodity e-commerce merchants competing on free shipping thresholds face acute margin pressure.
Supply Chain Analysis
Returns processing infrastructure—refurbishment flows from fashion verticals averaging 20-30% return rates—now determines network economics as pure forward-logistics providers forfeit resale value streams. China, South Korea, and Japan anchor autonomous mobile robot manufacturing, while Germany and the Netherlands concentrate dense last-mile automation deployment. Lithium-ion cell supply and rare earth magnet availability constrain electric commercial vehicle procurement timelines. Single-source vulnerability in semiconductor components for warehouse automation controllers threatens facility commissioning schedules. Distribution runs through the Dallas-Chicago-Inland Empire corridor for North American e-commerce fulfillment, with Rotterdam and Shanghai anchoring intercontinental consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified forklift operator shortages and warehouse labor concentration in exurban zones constrain fulfillment center throughput expansion, propping pricing for automated facilities with robotic picking capacity. Supply-side bottlenecks in electric fleet procurement compound these constraints.
For Market Incumbents: Deploy proprietary freight optimization platforms to anchor less-than-truckload market share against technology-enabled challengers. Consolidate micro-fulfillment positions within 25 miles of dense population clusters before lease rate inflation in the Inland Empire and Dallas corridors accelerates. Integrate reverse logistics refurbishment infrastructure to capture resale value streams that pure-play delivery networks forfeit.
For New Entrants and Emerging Players: Cloud-native Warehouse Management System marketplaces offer the most penetrable entry vector for mid-sized retailers seeking tier-one automation without proprietary server capital expenditure. Target India's PLI scheme corridors around Mumbai and Delhi for greenfield automated warehousing development. Partner with established parcel carriers for last-mile coverage rather than replicating FedEx or DHL ground network density.
For Investors and Strategic Acquirers: The window for entry favors specialized cold-chain operators with EU F-Gas Regulation compliance infrastructure already deployed. Long-term viability hinges on automation density differentiation as labor-dependent legacy warehouses face OSHA compliance cost escalations. Monitor lithium-ion cell price volatility and EPA Phase 3 adoption timelines across California and contiguous states as inflection indicators for electric fleet procurement economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Network Expansion | Positions operators within 25 miles of dense population clusters to capture same-day delivery premiums. |
| Electric Fleet Procurement Acceleration | EPA Phase 3 compliance deadlines in California force zero-emission vehicle deployment ahead of total cost parity. |
| Reverse Logistics Infrastructure Buildout | Captures refurbishment and resale value streams from fashion verticals with 20-30% return rates. |
| Cloud-Native WMS Platform Integration | Democratizes tier-one automation capabilities for mid-sized retailers through API-first subscription models. |
| Cold-Chain Refrigerant Transition | EU F-Gas Regulation mandates compress equipment replacement cycles while alternative refrigerant supply remains constrained. |
Methodological Framework
SEC 10-K filings, EPA regulatory dockets, and customs trade data formed the secondary backbone, cross-referenced against primary interviews with warehouse operations directors, fleet procurement managers, and omnichannel retail supply chain executives. Bottom-up facility capacity counts and top-down service revenue estimates were triangulated to anchor market sizing across transportation, warehousing, and inventory management segments.
Historical trendline analysis of automation deployment velocity and delivery window compression informed the projection framework across the analysis window. Segmentation dimensions modeled include service type, delivery model, technology tier, and customer vertical with regional regulatory cluster differentiation. CAGRs were derived from capacity expansion pipelines and fleet procurement order backlogs, with electric vehicle adoption curves and cloud infrastructure penetration serving as key forecast inputs.
The model holds under stable lithium-ion cell supply and phased EPA adoption timelines; deviation in rare earth magnet export restrictions or accelerated state-level emissions mandates would shift fleet procurement economics. Practitioners should monitor OSHA warehouse safety standard enforcement intensity and EU Green Deal carbon border adjustment implementation for early signals of compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Air Freight Market
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Pharmaceutical Logistics Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
GCC Contract Logistics Market