
 Egypt Courier, Express, and Parcel (CEP) Market | 2026-2036
Egypt Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Courier, Express, and Parcel (CEP) Market Insights
Asset-light fleet leasing and third-party logistics partnerships are reshaping competitive entry barriers across Egypt's CEP landscape. Aramex leverages its regional hub infrastructure to anchor cross-border express volumes through Cairo International Airport. Mylerz Egypt for Logistics and Technology Services competes through technology-led last-mile optimization and cash-on-delivery integration. Bosta specializes in e-commerce fulfillment, controlling niche same-day delivery corridors in Alexandria and the Nile Delta.
Courier, express, and parcel services constitute a logistics infrastructure layer managing time-definite shipment collection, sorting, line-haul transportation, and last-mile distribution across domestic and international corridors. These services operate on hub-and-spoke network architectures with standardized tracking protocols, dimensional weight pricing, and service-level agreements measured in hours or days for delivery commitment. Same-day delivery and next-day delivery segments command premium pricing structures due to Cairo's traffic congestion and the operational cost of maintaining distributed micro-fulfillment nodes. Ground transportation dominates the delivery mode mix given Egypt's extensive road network connecting the Nile Valley, though air freight sustains urgent international shipping volumes through dedicated cargo terminals. E-commerce end users generate the highest volume growth as digital payment penetration and marketplace expansion restructure consumer fulfillment expectations.
Egyptian Customs Authority regulations govern cross-border parcel classification and duty assessment, directly impacting international shipping cost structures and clearance velocity for express operators. The General Authority for Investment and Free Zones oversees logistics zone licensing, shaping where sorting facilities and distribution hubs can establish operations with tariff exemptions. National Telecommunications Regulatory Authority standards apply to tracking system data integrity and customer information handling. Stakeholders must monitor how customs digitization timelines and free-zone expansion decisions will redistribute competitive advantage between integrated global networks and domestic last-mile specialists.
Market Dynamics
Egypt's CEP sector is compressing delivery windows through distributed micro-fulfillment nodes and real-time route optimization, reshaping capital allocation between hub infrastructure and last-mile density.
Growth Catalysts
- Egyptian Customs Authority digitization:Automated clearance protocols are reducing cross-border parcel dwell times at Cairo International Airport cargo terminals. Express operators gain velocity advantages for international express volumes.
- Upper Egypt e-commerce penetration:Merchants are extending fulfillment networks into Sohag, Assiut, and Qena governorates. Previously underserved populations now access marketplace delivery services.
- Cash-on-delivery integration:Digital payment infrastructure gaps are driving COD adoption rates above regional averages. Logistics providers capture float revenue and customer trust through secure collection protocols.
Market Restraints
- Fuel price volatility:Ground transportation dominates Egypt's delivery mode mix, exposing operators to diesel subsidy fluctuations. Line-haul economics compress when energy costs spike.
- Greater Cairo infrastructure concentration:Sorting facilities and distribution hubs cluster in Cairo and Alexandria, creating single-point vulnerability. Upper Egypt lacks equivalent logistics zone density under General Authority for Investment and Free Zones licensing.
- Dimensional weight pricing limitations:E-commerce merchants resist standardized pricing models for irregular parcels. Revenue per shipment stagnates against rising operational complexity.
Strategic Opportunities
- New Valley and Matrouh corridor development:Sparse logistics coverage in Egypt's western desert regions offers first-mover positioning. Arid climate conditions favor climate-controlled warehousing differentiation.
- National Telecommunications Regulatory Authority data localization:Mandated customer information handling standards create compliance barriers for foreign platforms. Domestic operators gain competitive shelter through indigenous data architecture.
- AI-driven predictive routing:Machine learning convergence with telematics is enabling dynamic dispatch algorithms. Cairo's traffic congestion patterns become optimizable rather than merely navigable.
Industry Challenges
- Micro-fulfillment real estate scarcity:Securing small-format urban warehouses in Cairo's dense neighborhoods requires premium lease negotiations. Capex intensity rises as operators compete for limited last-mile nodes.
- Legacy customs system interoperability:Egyptian Customs Authority's phased digitization creates transitional friction. Operators must maintain parallel manual and electronic clearance workflows during system migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Courier, Express, and Parcel (CEP) Market |
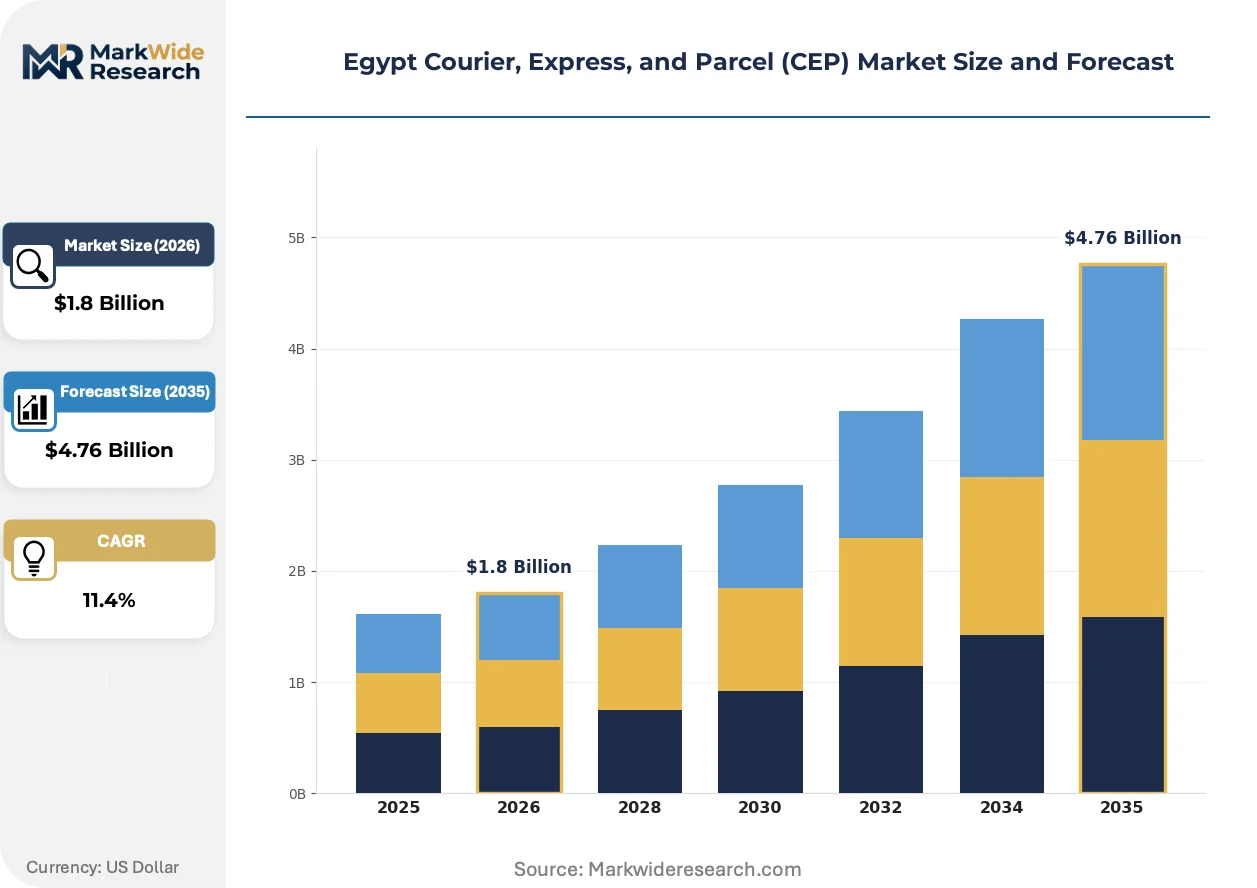
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, International Shipping, Freight Services Delivery Mode: Ground Transportation, Air Freight, Sea Freight, Drone Delivery End User: E-commerce, Retail, Manufacturing, Pharmaceuticals Package Type: Envelope, Box, Pallet, Tube |
| Companies Covered | Mylerz Egypt for Logistics and Technology Services, Bosta, Aramex, ABS Courier & Freight Systems, SkyNet Worldwide Express, DHL Group, Egypt Post, Middle East Courier Services, FedEx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Courier, Express, and Parcel (CEP) Market Trends and Innovations
Operational technology is penetrating Egypt's CEP infrastructure at uneven rates, with domestic specialists leapfrogging legacy systems while global networks retrofit existing hub architecture.
Dynamic route optimization software is digitizing dispatch decisions across Cairo's congested road network. E-commerce fulfillment centers deploy real-time traffic integration to compress delivery windows. The technology is digitizing previously static route planning, enabling same-day service commitments in Alexandria and Delta corridors.
Egyptian Customs Authority regulations are mandating pre-arrival data submission for all cross-border parcels. Express operators must reconfigure IT systems to transmit harmonized codes before physical arrival. International shipping segments face the steepest compliance investment requirements.
Buyer expectations are compressing delivery commitment windows from next-day to same-day in Greater Cairo. Marketplace platforms unbundle fulfillment services from merchant relationships. This behavioral shift concentrates volume with operators maintaining distributed micro-fulfillment presence.
Egypt Courier, Express, and Parcel (CEP) Market Segmentation
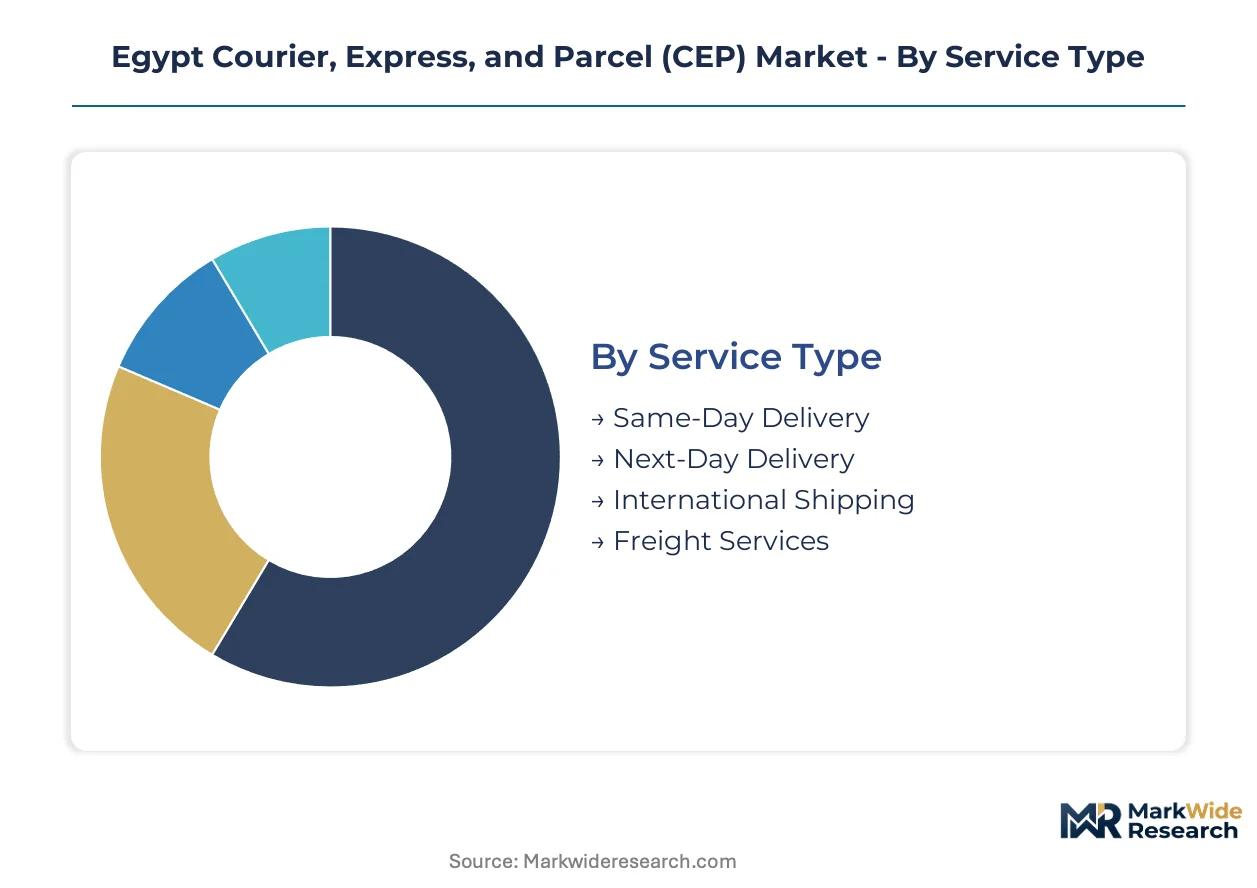
Service differentiation across Egypt's CEP landscape determines capital deployment patterns between premium velocity networks and cost-optimized ground infrastructure. Segment boundaries shift as e-commerce merchants unbundle fulfillment from core logistics, creating specialized sub-markets with distinct margin profiles and regulatory exposure.
Service Type:
Cost tier stratification separates premium time-definite commitments from deferred economy services, with pricing power concentrated in velocity-sensitive corridors.
- Same-Day Delivery:Ultra-rapid fulfillment operates through distributed micro-fulfillment nodes and dynamic dispatch algorithms. Demand clusters in Greater Cairo's dense urban corridors where traffic congestion creates premium pricing tolerance for urgent replenishment and perishable goods.
- Next-Day Delivery:Standard express commitment leverages hub-and-spoke sorting infrastructure with overnight line-haul operations. Alexandria and Nile Delta manufacturing zones drive volume as just-in-time supply chains compress inventory holding periods.
- International Shipping:Cross-border parcel clearance depends on Egyptian Customs Authority digitization timelines and pre-arrival data submission protocols.
- Freight Services:Heavy cargo consolidation serves industrial shippers with palletized volumes requiring specialized handling equipment.
Same-Day Delivery holds installed capacity. Next-Day Delivery is rotating up the share rankings.
Delivery Mode:
Supply concentration across transportation modes reflects infrastructure endowment and fuel cost exposure, with modal choice dictated by shipment urgency and destination accessibility.
- Ground Transportation:Diesel-powered fleet networks dominate domestic parcel distribution through Egypt's Nile Valley road corridor. Upper Egypt governorates rely exclusively on ground infrastructure as air cargo terminal density concentrates in Cairo and Alexandria.
- Air Freight:Dedicated cargo terminals at Cairo International Airport anchor urgent international express volumes with customs-bonded sorting facilities. Egyptian Customs Authority clearance velocity determines competitive positioning for cross-border premium services.
- Sea Freight:Maritime container consolidation serves non-urgent bulk shipments through Alexandria and Damietta ports with extended transit windows.
- Drone Delivery:Experimental last-mile automation faces National Telecommunications Regulatory Authority spectrum allocation and urban airspace coordination constraints.
Ground Transportation holds installed capacity. Air Freight is rotating up the share rankings.
End User:
Customer type segmentation reveals diverging service requirements across fulfillment complexity, payment integration needs, and regulatory compliance exposure.
- E-commerce:Digital marketplace fulfillment demands cash-on-delivery integration, real-time tracking, and flexible address modification. Cairo and Alexandria merchant bases are expanding into Sohag, Assiut, and Qena with localized last-mile partnerships.
- Retail:Omnichannel distribution combines store replenishment with direct-to-consumer dropshipment from regional distribution centers.
- Manufacturing:Production input logistics requires scheduled delivery windows synchronized with assembly line operations.
- Pharmaceuticals:Temperature-controlled chain-of-custody protocols govern vaccine and biologic distribution with specialized packaging validation.
E-commerce holds installed capacity. Pharmaceuticals is rotating up the share rankings.
Package Type:
Volume and form factor dimensions determine sorting automation compatibility, dimensional weight pricing applicability, and last-mile vehicle fleet configuration.
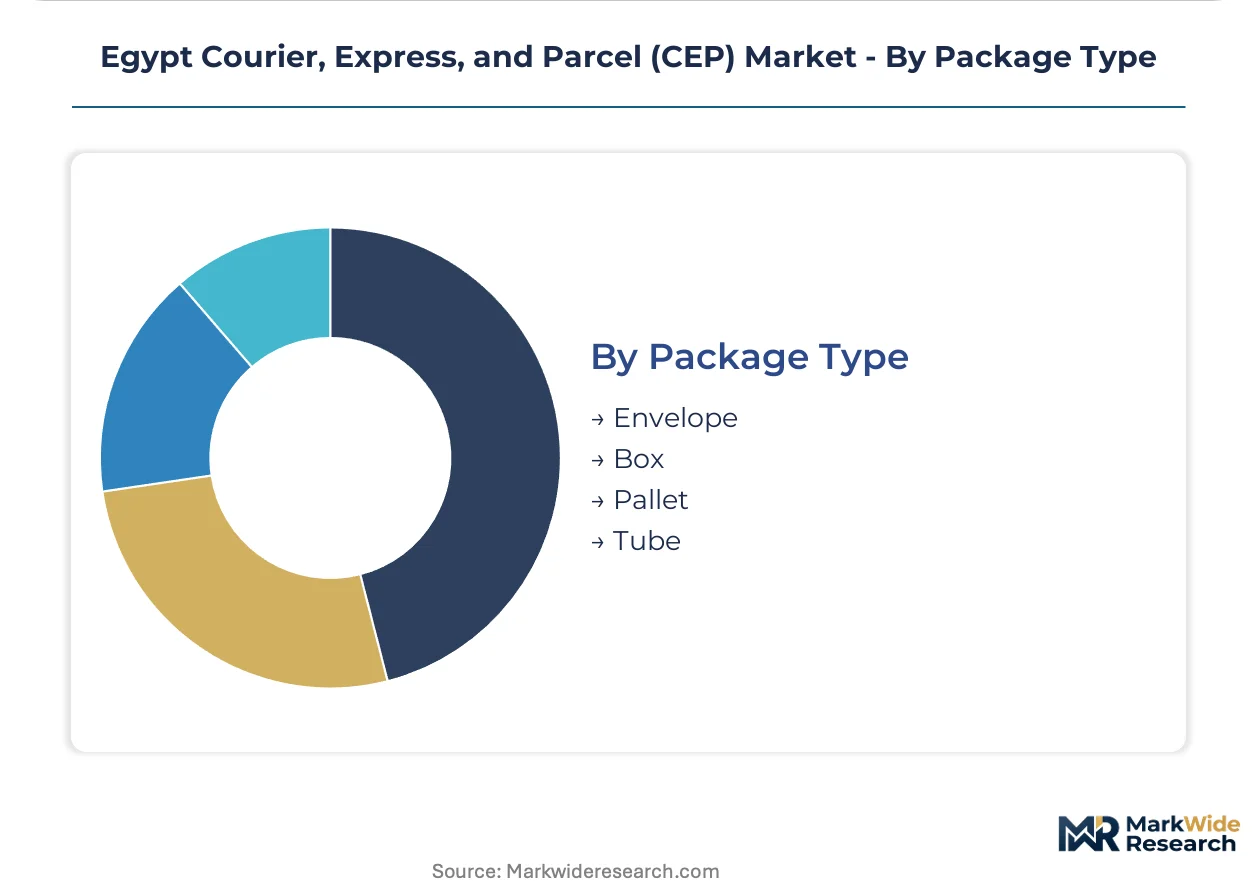
- Envelope:Document and small-item flat packaging enables automated letter sorting with minimal handling labor. Financial services and legal documentation drive consistent demand through Cairo's central business district corridors.
- Box:Standard corrugated packaging dominates e-commerce parcel volume with modular stacking efficiency for hub conveyor systems.
- Pallet:Unitized freight requires forklift-capable facilities and specialized line-haul equipment for B2B industrial distribution.
- Tube:Cylindrical formats for posters, textiles, and industrial components present irregular handling challenges for automated sortation.
Box holds installed capacity. Envelope is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's import-export imbalance shapes CEP demand geography, with inbound cross-border parcels dominating Cairo International Airport cargo volumes while domestic e-commerce fulfillment networks expand southward toward consumption growth.
Greater Cairo Metropolitan Zone
Dense urban corridors generate same-day delivery premiums as traffic congestion stretches fulfillment windows. Egyptian Customs Authority bonded facilities at Cairo International Airport anchor international express clearance. New Cairo and 6th of October City micro-fulfillment nodes multiply as e-commerce merchants unbundle logistics from core retail operations.
Alexandria and the Nile Delta
Manufacturing clusters in Damietta and Tanta drive B2B express volumes for just-in-time supply chains. Alexandria Port maritime connectivity sustains sea freight consolidation for non-urgent bulk shipments. The city's Mediterranean coastal position attracts climate-controlled warehousing investment for pharmaceutical distribution.
Upper Egypt Governorates
Sohag, Assiut, and Qena represent underpenetrated demand frontiers where cash-on-delivery integration determines market access. Ground transportation infrastructure along the Nile Valley enables cost-effective line-haul economics. Localized last-mile partnerships substitute for direct operator presence in sparse logistics zones.
Red Sea Coastal Corridor
Hurghada and Safaga tourism hubs generate irregular parcel flows requiring flexible capacity deployment. Suez Canal Economic Zone logistics licensing under General Authority for Investment and Free Zones attracts bonded warehousing investment. Port infrastructure supports maritime-air intermodal options for time-sensitive cargo.
Egypt Courier, Express, and Parcel (CEP) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in last-mile density and customs brokerage. Egypt's CEP structure tiers between integrated global networks with Cairo hub infrastructure and domestic specialists optimizing cash-on-delivery collection. Three archetypes dominate: regional express platforms with cross-border clearance capabilities, technology-led last-mile optimizers, and state-affiliated postal networks with rural coverage mandates. Competitive moves concentrate on micro-fulfillment real estate acquisition and Egyptian Customs Authority compliance system integration.
Within the domestic specialist tier, Mylerz Egypt for Logistics and Technology Services and Bosta exemplify technology-led last-mile optimization archetypes. Aramex occupies a position representing regional platform integration with Cairo International Airport hub infrastructure. These three anchors illustrate how competitive positioning separates global network access from localized fulfillment density and COD collection capabilities.
| Leading Market Players |
|---|
| Mylerz Egypt for Logistics and Technology Services |
| Bosta |
| Aramex |
| ABS Courier & Freight Systems |
| SkyNet Worldwide Express |
| DHL Group |
| Egypt Post |
| Middle East Courier Services |
| FedEx |
| Others |
Pricing and Supply Chain Analysis
Cairo International Airport cargo terminals anchor Egypt's cross-border parcel capacity, concentrating sorting infrastructure and customs-bonded facilities in a single hub. This geographic concentration grants express operators with dedicated terminal access pricing power over international shipping segments while exposing ground transportation providers to diesel cost volatility across the Nile Valley corridor.
Pricing Analysis
E-commerce merchants anchor pricing structures around cash-on-delivery integration costs and last-mile density premiums. Three-tier pricing separates same-day commitments from next-day and deferred economy services, with quality grade and geographic delivery cost as primary differentiation drivers. Pricing pressure stems from dimensional weight pricing resistance among irregular parcel shippers. Small-format retailers exhibit highest price sensitivity; pharmaceutical distributors tolerate premium rates for temperature-controlled chain-of-custody protocols.
Supply Chain Analysis
Fuel subsidy fluctuations between Egypt and regional diesel suppliers dominate operational risk exposure for ground transportation networks. Fleet capacity concentrates in domestic leasing partnerships and third-party logistics arrangements rather than captive asset ownership. Sorting automation components and telematics hardware draw from East Asian manufacturing hubs. Distribution runs through hub-and-spoke architectures with Cairo as the central node, extending via line-haul road networks to Alexandria and Upper Egypt governorates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's CEP sector exhibits cyclical recovery characteristics as e-commerce penetration rebounds from digital payment infrastructure gaps. Cash-on-delivery float revenue and customs digitization timelines constitute the primary cyclical drivers resetting competitive positioning.
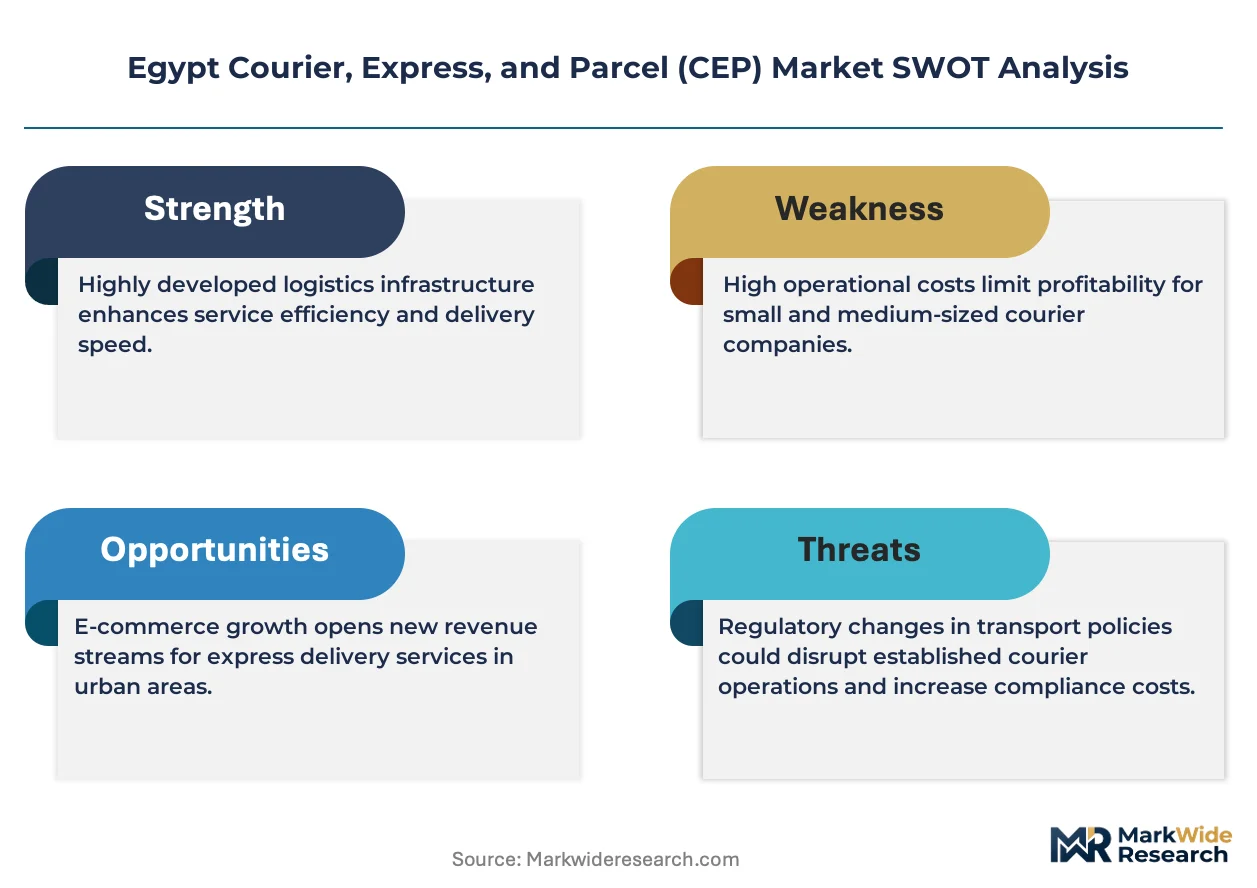
For Market Incumbents: Build switching-cost moats through Egyptian Customs Authority compliance system integration and micro-fulfillment real estate lock-up in New Cairo and 6th of October City. Threats from technology-led last-mile optimizers like Mylerz demand countermeasures through proprietary route optimization algorithms. Capacity addition in Upper Egypt governorates substitutes for direct presence via localized partnership networks. For New Entrants and Emerging Players: Establish a beachhead in Sohag and Qena corridors where incumbent density remains sparse and cash-on-delivery integration gaps persist. Upper Egypt's underpenetrated demand frontier offers lowest competitive intensity. Go-to-market positioning should emphasize COD collection infrastructure and Arabic-language customer interfaces as differentiation against global network operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic specialists with indigenous data architecture compliant with National Telecommunications Regulatory Authority localization mandates. Long-term viability rests on last-mile density rather than cross-border clearance scale. Acquisition target archetype: technology-enabled last-mile operators with proven COD collection protocols. Signal to watch: Egyptian Customs Authority digitization completion timelines as inflection indicator for international express segment profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Node Expansion | Distributed warehousing in Cairo's dense neighborhoods compresses same-day delivery windows against traffic congestion. |
| Customs Compliance System Integration | Egyptian Customs Authority pre-arrival data submission protocols determine cross-border express clearance velocity. |
| Cash-on-Delivery Infrastructure Buildout | Secure collection protocols in Upper Egypt governorates unlock previously inaccessible e-commerce demand. |
| AI-Driven Predictive Routing Deployment | Machine learning algorithms optimize dispatch decisions across Cairo's congested road network. |
| Localized Last-Mile Partnership Networks | Third-party logistics arrangements in Sohag and Assiut substitute for direct operator presence in sparse zones. |
Research Methodology
Operator-level perspectives from fleet managers, e-commerce fulfillment directors, customs brokerage specialists, and last-mile dispatch coordinators anchored the qualitative base. Primary interviews with executives at Aramex, Mylerz, and Bosta supplemented secondary validation through Egyptian Customs Authority regulatory filings, General Authority for Investment and Free Zones licensing records, and National Telecommunications Regulatory Authority standards documentation. Bottom-up volume triangulation across service type, delivery mode, and end-user segments converged with top-down macroeconomic anchoring.
Scenario-bracketing around fuel subsidy volatility, customs digitization pace, and e-commerce penetration rates framed the analytical approach. Segmentation dimensions modeled included service velocity tier, transportation mode, customer type, and geographic corridor throughout the forecast period. CAGRs were derived from trend extrapolation with elasticity adjustments for COD adoption and infrastructure investment cycles. Forecast inputs incorporated traffic congestion indices and micro-fulfillment real estate lease cost trajectories specific to Greater Cairo.
Stress conditions across diesel price spikes, customs system migration delays, and Upper Egypt demand acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timelines and infrastructure buildout pacing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
France Freight and Logistics Market
Logistics and Shipping
Japan Freight Forwarding Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Spain 3PL Market